
 Global Biocompatible Materials Market | 2026-2036
Global Biocompatible Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biocompatible Materials Market Foresight
Medical device manufacturers are redrawing procurement priorities around long-term implant reliability, while research laboratories expand exploratory budgets for next-generation scaffolds. BASF SE leverages its polymer science heritage to dominate high-purity PEEK supply chains for spinal implants. Evonik Industries AG specializes in biodegradable polymers that anchor its position within drug delivery reservoirs. DuPont de Nemours, Inc. competes through fluoropolymer expertise that sustains vascular graft performance standards.
Biocompatible materials are substances engineered to perform specific functions within living organisms without eliciting adverse immune responses, typically meeting ISO 10993 cytotoxicity and sensitization benchmarks through controlled surface chemistry and purity protocols. These materials enable permanent implants, transient drug carriers, and regenerative matrices across surgical and therapeutic settings. Polymers command the largest value share due to tunable degradation rates and processing versatility, while hydrogels represent the fastest-expanding category as tissue engineering protocols advance toward organ-specific constructs. Metals retain entrenched positions in load-bearing orthopedic applications where fatigue resistance and osseointegration remain non-negotiable.
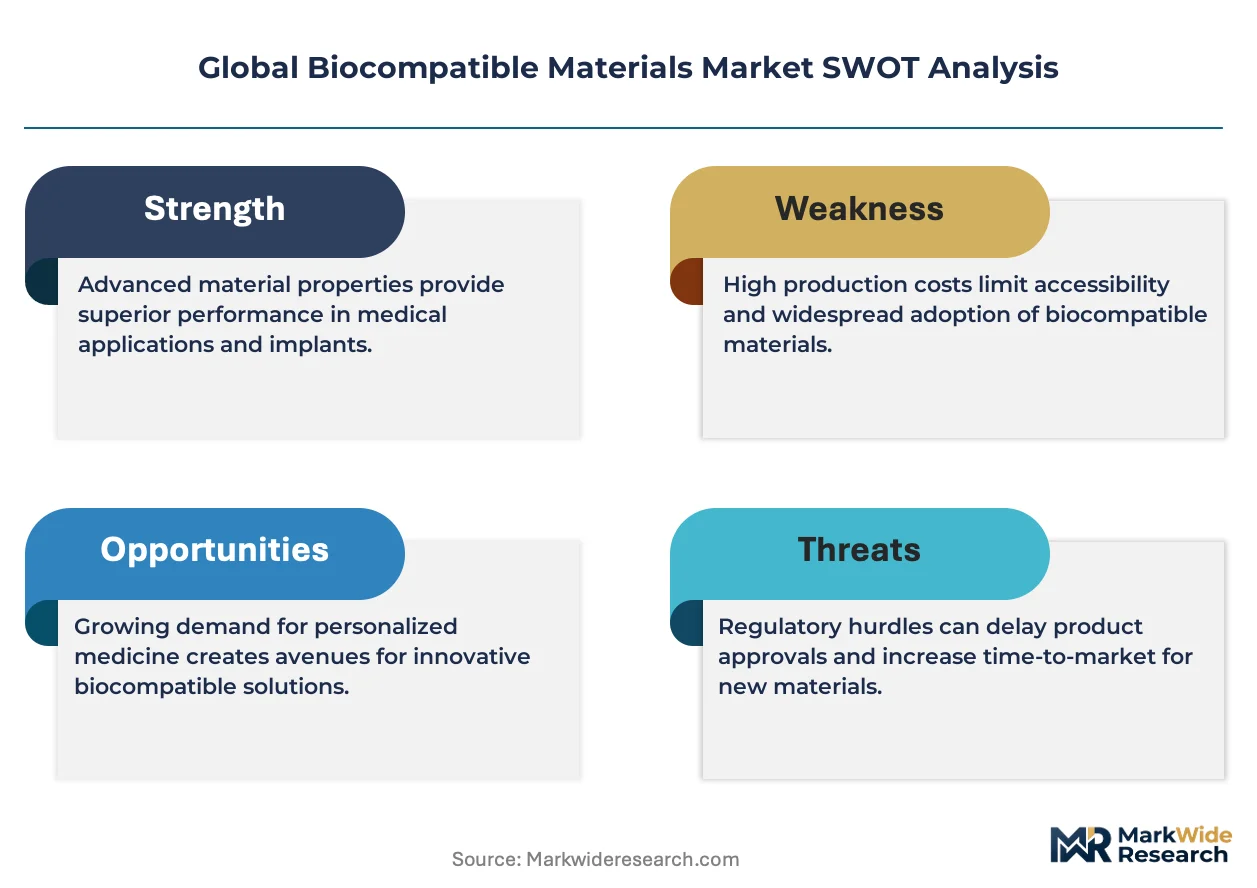
FDA biocompatibility guidance, EU MDR clinical evaluation requirements, and ISO 10993 testing standards collectively determine market access timelines and qualification costs for material suppliers. The EU AI Act's emerging implications for software-integrated smart implants will extend compliance burdens into algorithmic validation domains. Stakeholders must monitor regulatory divergence between the FDA's risk-based device classification and the EU's heightened clinical evidence thresholds when allocating R&D and registration resources.
Market Dynamics
EU MDR's clinical evidence requirements are compressing supplier qualification timelines while concentrating procurement among vertically integrated polymer compounders with captive testing infrastructure.
Growth Catalysts
- Spinal implant polymerization:PEEK formulations now dominate interbody fusion cages as surgeons prioritize radiolucency and modulus-matching to bone.
- FDA 510(k) biocompatibility guidance:Streamlined submission pathways for established material families accelerate time-to-market for iterative device designs.
- Germany's Tuttlingen-Freiburg corridor:Dense clustering of precision manufacturers creates localized demand pull for implant-grade polymers and surface-treated metals.
Market Restraints
- High-purity monomer scarcity:Pharmaceutical-grade lactide and glycolide feedstock supply concentrates among three European specialty chemical producers.
- ISO 10993-18 chemical characterization:Expanded extractables testing protocols extend qualification cycles by months for novel polymer formulations.
- Titanium alloy substitution pressure:Cobalt-chrome and ceramic matrix composites threaten entrenched positions in hip arthroplasty bearing surfaces.
Strategic Opportunities
- India's CDSCO fast-track pathway:Accelerated approval mechanisms for materials with prior US or EU authorization attract qualification investments.
- Soft tissue regeneration matrices:Decellularized extracellular matrix scaffolds open orthopedic applications beyond traditional hard-tissue implants.
- EU AI Act integration:Smart implants with embedded sensors require algorithm-validated biocompatible housings, creating premium material tiers.
Industry Challenges
- Polymer rheology specialization:Shortage of process engineers capable of tuning melt-flow indices for thin-wall catheter extrusion constrains capacity expansion.
- MDR technical documentation:Clinical evaluation report requirements for legacy materials force retrospective biocompatibility studies without predicate pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biocompatible Materials Market |
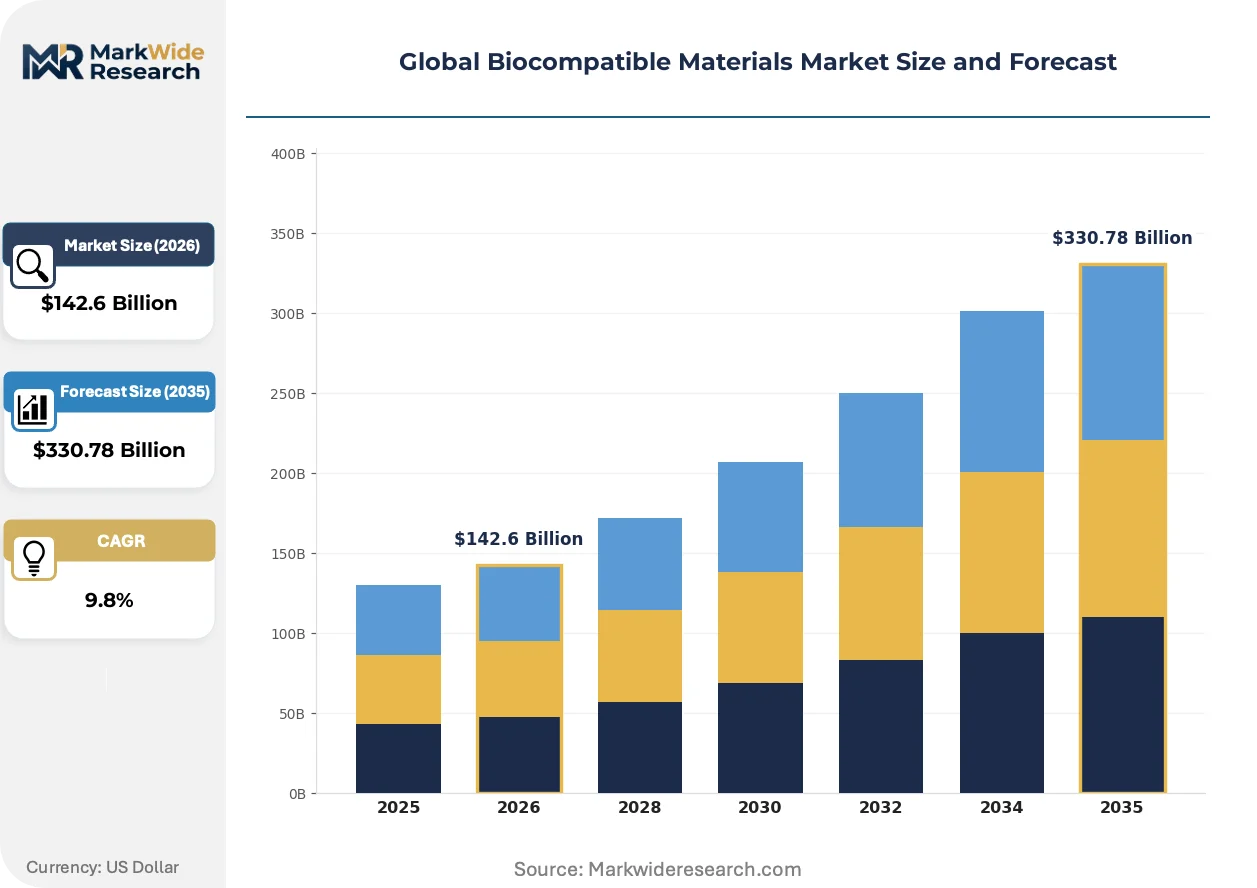
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $330.78 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymers, Ceramics, Metals, Composites, Hydrogels Application Area: Orthopedics, Dental Implants, Cardiovascular Devices, Drug Delivery, Tissue Engineering End User: Medical Device Manufacturers, Research Laboratories, Pharmaceutical Companies, Academic Institutions Product Form: Powders, Films, Coatings, Fibers, Scaffolds |
| Companies Covered | BASF SE, Evonik Industries AG, DuPont de Nemours, Inc., Covestro AG, Stratasys Ltd., Medtronic plc, Celanese Corporation, 3D Systems Inc., Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biocompatible Materials Market Shifts & Advancements
Surface engineering and programmable degradation are rewriting material selection criteria across implantable device categories, compressing development cycles for patient-matched solutions.
Bioabsorbable magnesium alloys are supplanting permanent metal fixtures in pediatric orthopedic applications where growth accommodation matters. European trauma device manufacturers now specify WE43 and AZ31 grades for craniofacial plates. This substitution eliminates secondary removal surgeries while demanding entirely new corrosion-control coating stacks.
REACH authorization restrictions on certain phthalate plasticizers are forcing cardiovascular device manufacturers to reformulate blood-contacting polymers. The industrial consequence involves multi-year validation studies for replacement chemistries in tubing and connector applications. German and French catheter producers are accelerating migration to citrate-based alternatives ahead of sunset dates.
Hospital procurement consortia are consolidating supplier panels around full-lifecycle material traceability. Original equipment manufacturers now face audit requirements extending from resin lot to explanted device retrieval. This concentration is most visible in Benelux and Nordic healthcare systems where national tendering dominates implant acquisition.
Global Biocompatible Materials Market Segmentation
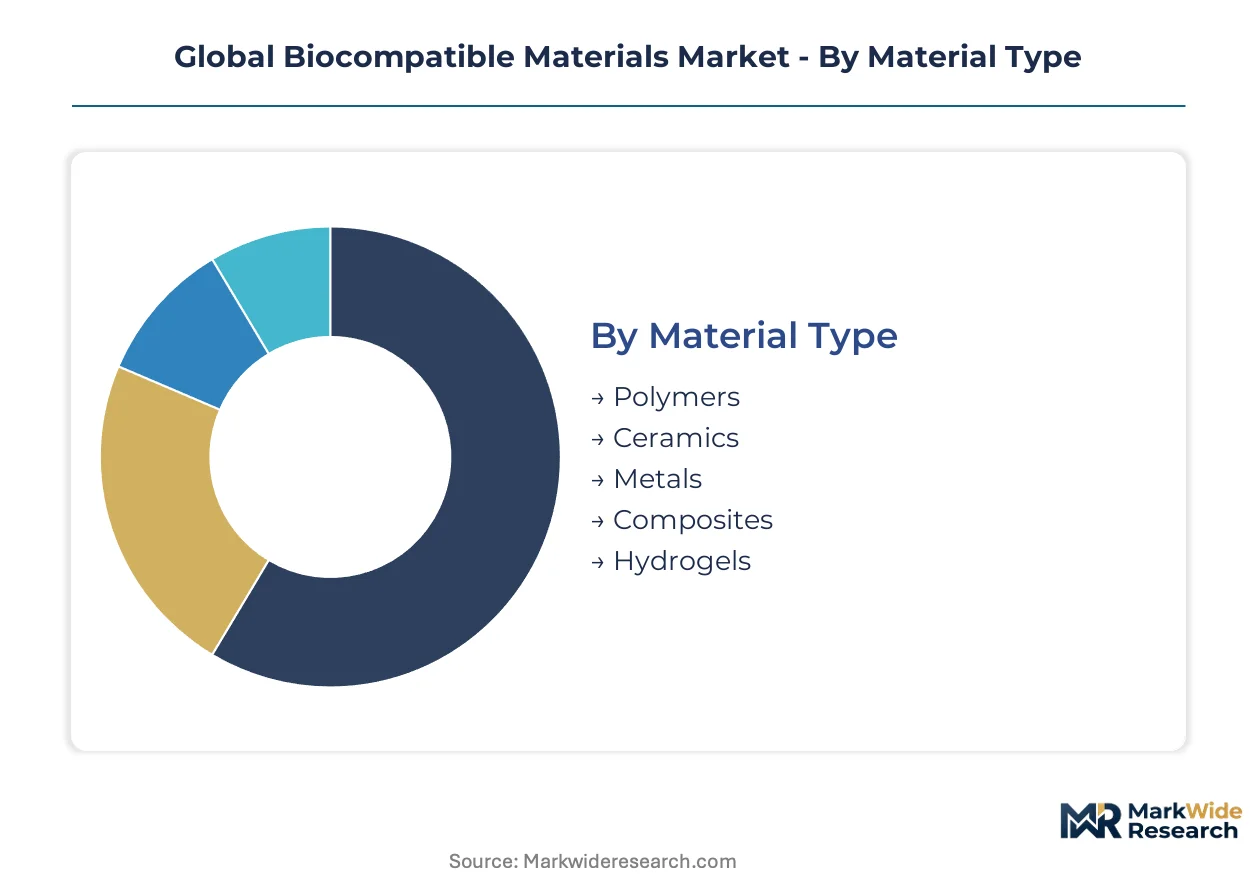
Material selection pathways diverge sharply between high-volume implant manufacturing and precision research applications. Procurement channels for biocompatible materials stratify by certification burden, batch size, and regulatory documentation depth.
Material Type:
Polymers and metals move through established medical device distributor networks, while hydrogels and composites increasingly route through specialized research supply channels.
- Polymers:Thermoplastic and thermoset formulations dominate spinal implant and catheter manufacturing due to tunable degradation profiles and melt-processability. PEEK supply chains concentrate around Germany's chemical corridor serving Tuttlingen device manufacturers.
- Hydrogels:Cross-linked polymer networks with high water content anchor tissue engineering protocols and drug delivery matrices. Demand from academic institutions in Boston and Singapore is climbing fastest as organ-specific scaffold protocols advance.
- Ceramics:Alumina and zirconia formulations serve hip arthroplasty bearing surfaces with wear resistance requirements.
- Metals:Titanium alloys and cobalt-chrome retain entrenched positions in load-bearing orthopedic applications.
- Composites:Polymer-ceramic and polymer-metal hybrids address modulus-matching challenges in dental and trauma implants.
By volume, polymers lead. By growth pace, hydrogels are ahead.
Application Area:
Cost tier stratification separates commodity implant materials from premium regenerative matrices requiring extended biocompatibility validation.
- Orthopedics:Joint replacement and spinal fixation devices consume the largest polymer and metal volumes, with PEEK interbody cages and titanium pedicle screws representing standard-of-care procurement categories. German and Swiss hospital consortia drive specification tightening around fatigue resistance documentation.
- Tissue Engineering:Decellularized scaffolds and bioactive matrices command premium pricing due to complex manufacturing and stringent sterility requirements. Research laboratories in Cambridge and Stanford are expanding exploratory budgets fastest for organ-specific construct development.
- Cardiovascular Devices:Stent polymers and vascular graft materials face REACH-driven plasticizer reformulation pressures.
- Dental Implants:Zirconia and titanium abutments concentrate procurement among specialized European manufacturers.
- Drug Delivery:Biodegradable polymers for implantable reservoirs require pharmaceutical-grade monomer supply chains.
Orthopedics generates the highest material tonnage. Tissue engineering shows the steepest expansion trajectory.
End User:
Volume concentration sits with medical device manufacturers, while margin capture favors research laboratories with lower price sensitivity and higher specification tolerance.
- Medical Device Manufacturers:Large-scale polymer and metal procurement for FDA 510(k) and EU MDR compliant implants dominates commercial flow. Vertically integrated compounders with captive ISO 10993 testing infrastructure capture preferred supplier status.
- Research Laboratories:Exploratory hydrogel and composite sourcing for next-generation scaffold development operates through specialized distributors with flexible batch sizing. Academic medical centers in Germany and the United States are expanding material budgets fastest for regenerative medicine programs.
- Pharmaceutical Companies:Biodegradable polymer sourcing for controlled-release formulations requires pharmaceutical-grade documentation.
- Academic Institutions:Grant-funded procurement for tissue engineering research prioritizes novel material access over cost optimization.
Medical device manufacturers account for the largest procurement volume. Research laboratories are expanding purchasing fastest.
Product Form:
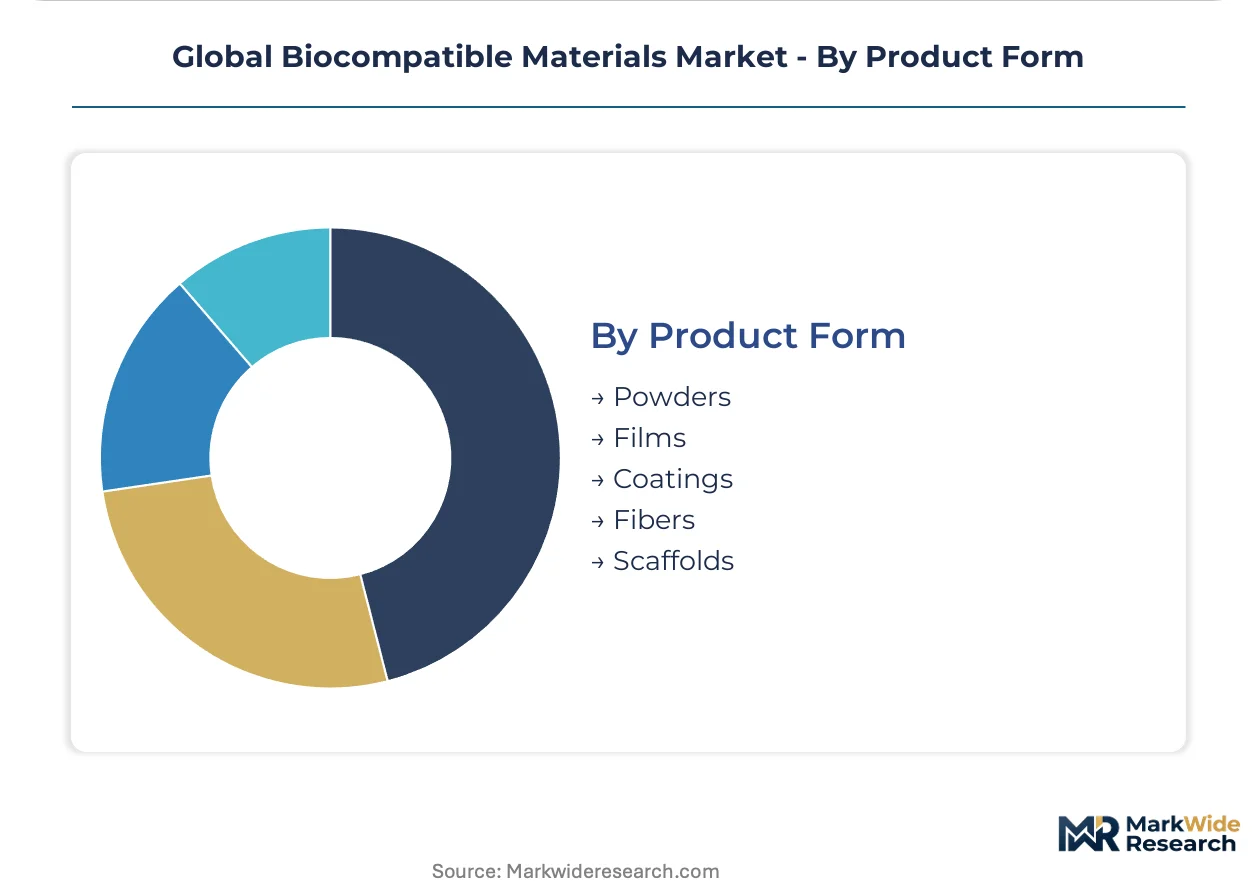
Supply chain maturity separates powder and film commodities from scaffold and coating specialties with concentrated production footprints.
- Scaffolds:Three-dimensional porous structures for cell seeding and tissue regeneration require precision manufacturing with pore architecture control. Electrospinning and 3D printing equipment limitations constrain supplier expansion.
- Coatings:Surface modification layers for corrosion resistance and biointegration command premium pricing due to application-specific formulation requirements. Drug-eluting stent manufacturers in Ireland and Minnesota drive specification complexity.
- Powders:Ceramic and metal feedstock for sintering and additive manufacturing routes through commodity chemical distributors.
- Films:Thin polymer membranes for barrier applications serve established packaging and device markets.
- Fibers:Suture and textile scaffold materials concentrate among specialized extrusion houses.
Powders lead by shipment volume. Scaffolds are climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker throughput underwrites European polymer feedstock security, while the Qingdao-Jinan high-speed rail corridor connects Shandong Peninsula medical device clusters to northern China's distribution networks.
United States
Spinal implant manufacturers in Warsaw, Indiana and Memphis, Tennessee drive PEEK and titanium procurement volumes. FDA 510(k) biocompatibility guidance streamlines qualification pathways for established material families. The Minneapolis-St. Paul corridor concentrates vascular graft producers facing REACH-driven plasticizer reformulation timelines.
Germany
Tuttlingen's precision surgical instrument cluster and Freiburg's medical technology corridor generate localized demand for implant-grade polymers and surface-treated metals. EU MDR clinical evidence requirements compress supplier qualification timelines toward vertically integrated compounders. Baden-Württemberg's chemical corridor serves spinal device manufacturers with captive ISO 10993 testing infrastructure.
China
NMPA fast-track pathways for materials with prior FDA or CE marking accelerate domestic qualification investments. The Yangtze River Delta medical device manufacturing belt around Shanghai and Suzhou expands polymer compounding capacity. Domestic trauma device producers specify WE43 magnesium alloys for pediatric craniofacial applications.
Switzerland
Swissmedic's alignment with EU MDR standards enables seamless material qualification for orthopedic implant exports. The Lake Geneva region concentrates dental implant manufacturers sourcing zirconia and titanium abutments. Basel's pharmaceutical polymer heritage supports biodegradable drug delivery reservoir development.
India
CDSCO accelerated approval mechanisms attract qualification investments for materials with prior US or EU authorization. Maharashtra's Mumbai-Pune pharmaceutical corridor expands medical device polymer processing. Tamil Nadu's Chennai medical device cluster develops domestic PEEK compounding for spinal implant manufacturers.
Global Biocompatible Materials Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing pharmaceutical-grade polymer heritage and captive regulatory testing infrastructure. The supplier base stratifies between high-volume implant material compounders and specialized scaffold manufacturers serving research laboratories. Three archetypes dominate: vertically integrated polymer producers with ISO 10993 capabilities, precision metals processors with orthopedic certification depth, and research-focused hydrogel specialists. Competitive moves center on backward integration into high-purity monomer supply and strategic partnerships with hospital procurement consortia demanding full-lifecycle traceability.
Among German chemical conglomerates, BASF SE and Evonik Industries AG exemplify the vertically integrated archetype, with the latter representing specialization in biodegradable polymer segments. DuPont de Nemours, Inc. anchors the fluoropolymer expertise cluster serving vascular graft applications. These three occupy positions where regulatory documentation depth and batch consistency protocols determine preferred supplier status with large-scale device manufacturers.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| DuPont de Nemours, Inc. |
| Covestro AG |
| Stratasys Ltd. |
| Medtronic plc |
| Celanese Corporation |
| 3D Systems Inc. |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
ISO 10993-18 chemical characterization requirements gate both supplier qualification timelines and price differentiation simultaneously, compressing procurement toward vertically integrated compounders with captive testing infrastructure while forcing premium tiers for novel polymer formulations lacking predicate pathways. Hospital procurement consortia in Benelux and Nordic healthcare systems now demand full-lifecycle traceability from resin lot to explanted device retrieval, tightening supplier panels and amplifying pricing power for compliant material providers.
Pricing Analysis
Volume-discount tiering structures separate implant-grade polymer procurement into three distinct levels: premium formulations with complete ISO 10993 documentation and predicate device histories, standard grades with established biocompatibility profiles but limited application breadth, and economy tiers for non-implantable device housings. Price differentiation rests on certification depth and batch consistency protocols rather than raw material costs alone. Pricing pressure stems from EU MDR clinical evidence requirements extending qualification cycles without corresponding reimbursement expansion. Medical device manufacturers exhibit highest price sensitivity due to compressed margin structures, while research laboratories tolerate premium positioning for novel scaffold access.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for pharmaceutical-grade lactide and glycolide monomers sourced from European specialty chemical producers. Supply concentrates in Germany's chemical corridor around Ludwigshafen and Marl, with secondary nodes in Switzerland's Basel region and limited US capacity around Houston. Raw material dependencies center on high-purity monomers, specialty catalysts for controlled polymerization, and precision extrusion equipment. Single-source vulnerability pervades biodegradable polymer feedstock supply, where three European producers dominate pharmaceutical-grade output. Distribution runs through medical device distributor networks for established polymers, while hydrogels and research-grade materials route through specialized academic supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart implant sensor integration is reconfiguring biocompatible materials as platform components within algorithm-validated device ecosystems, where material suppliers must now co-qualify housing chemistries alongside embedded software modules. This interoperability shift demands backward integration into both pharmaceutical-grade polymer production and regulatory documentation capabilities.
For Market Incumbents: Consolidate backward integration into high-purity monomer supply chains to defend against feedstock scarcity threatening biodegradable polymer margins. Expand captive ISO 10993 testing infrastructure in Germany's Baden-Württemberg corridor to compress qualification timelines for EU MDR compliance. Deepen strategic partnerships with hospital procurement consortia demanding full-lifecycle traceability, locking in preferred supplier status before contract consolidation completes.
For New Entrants and Emerging Players: India's CDSCO fast-track pathway for materials with prior US or EU authorization offers the most penetrable regulatory entry point, enabling accelerated market access without duplicating expensive biocompatibility studies. Target soft tissue regeneration matrices and decellularized extracellular scaffold niches where incumbent polymer compounders lack specialized manufacturing capabilities. Pursue grant-funded academic laboratory relationships as initial revenue anchors, leveraging flexible batch sizing tolerance to refine production protocols before scaling.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by extending material qualification burdens into algorithmic validation domains for smart implant housings. Long-term viability centers on suppliers capable of serving both traditional implantable devices and sensor-integrated next-generation platforms. Target vertically integrated mid-cap compounders with pharmaceutical-grade polymer heritage and established hospital procurement relationships. Monitor NMPA fast-track utilization rates as signal for Chinese domestic qualification investment intensity and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive pharmaceutical-grade lactide production insulates against European feedstock concentration and REACH authorization volatility. |
| CE Marking Pathway Investment | EU MDR technical documentation capabilities compress supplier qualification timelines for spinal implant manufacturers in Tuttlingen. |
| Hospital System Partnership | Preferred supplier agreements with Benelux procurement consortia secure volume commitments through full-lifecycle traceability compliance. |
| Software Companion Development | Algorithm-validated biocompatible housings capture premium tiers within EU AI Act regulated smart implant categories. |
| Geographic Manufacturing Footprint | Domestic PEEK compounding in Tamil Nadu's Chennai cluster reduces import dependency for Indian spinal implant producers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers at spinal implant manufacturers, procurement managers at German hospital consortia, regulatory affairs leads at polymer compounders, and R&D directors at tissue engineering laboratories. Secondary validation drew from FDA 510(k) submission databases, EU MDR technical documentation filings, ISO 10993 testing standard revisions, and customs trade data tracking pharmaceutical-grade monomer flows. Bottom-up segment sizing triangulated against top-down market boundary estimates derived from medical device production statistics.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented approaches spanning material type, application area, end user category, and product form dimensions. CAGRs were derived from regression analysis against implant procedure growth rates, regulatory approval velocity, and polymer substitution elasticities in orthopedic and cardiovascular segments. Industry-specific inputs incorporated EU MDR implementation pace, REACH plasticizer sunset timelines, and NMPA fast-track pathway utilization patterns.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory stringency and stable hospital procurement consolidation; material deviation in MDR enforcement intensity or reimbursement policy would warrant model refresh. Specific risks include titanium alloy substitution acceleration in hip arthroplasty, bioabsorbable magnesium corrosion-control coating failures, and algorithmic validation requirement expansion under EU AI Act enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Chitosan Oligosaccharides and Glucosamine Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
South America Collagen Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Biomaterials Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Biomimetic Materials Market