
 US Heparin Market | 2026-2036
US Heparin Market Size, Share, and Industry Trends Forecast 2026-2036
US Heparin Market Analysis
USP monograph compliance and FDA current Good Manufacturing Practice certification is redrawing competitive access in the US heparin supply base. Pfizer Inc. leverages its integrated plasma-derived API network to secure domestic manufacturing continuity. Baxter International Inc. anchors hospital infusion channel relationships through premixed heparin sodium portfolios. Amphastar Pharmaceuticals, Inc. specializes in multi-dose vial formats that serve high-throughput surgical centers.
Heparin is a sulfated glycosaminoglycan anticoagulant derived from porcine intestinal mucosa or bovine lung tissue, with unfractionated forms averaging molecular weights of 15,000 daltons and low molecular weight variants ranging 4,000 to 6,000 daltons; it accelerates antithrombin III inhibition of thrombin and factor Xa to prevent clot formation during surgery, dialysis, and critical care. Low molecular weight heparin commands the largest revenue share due to predictable pharmacokinetics and reduced monitoring burden, while pre-filled syringe delivery modes are gaining fastest as home care protocols expand. Cardiology and orthopedic surgery applications together concentrate the majority of unit demand, with hematology representing a narrower but higher-margin specialty segment.
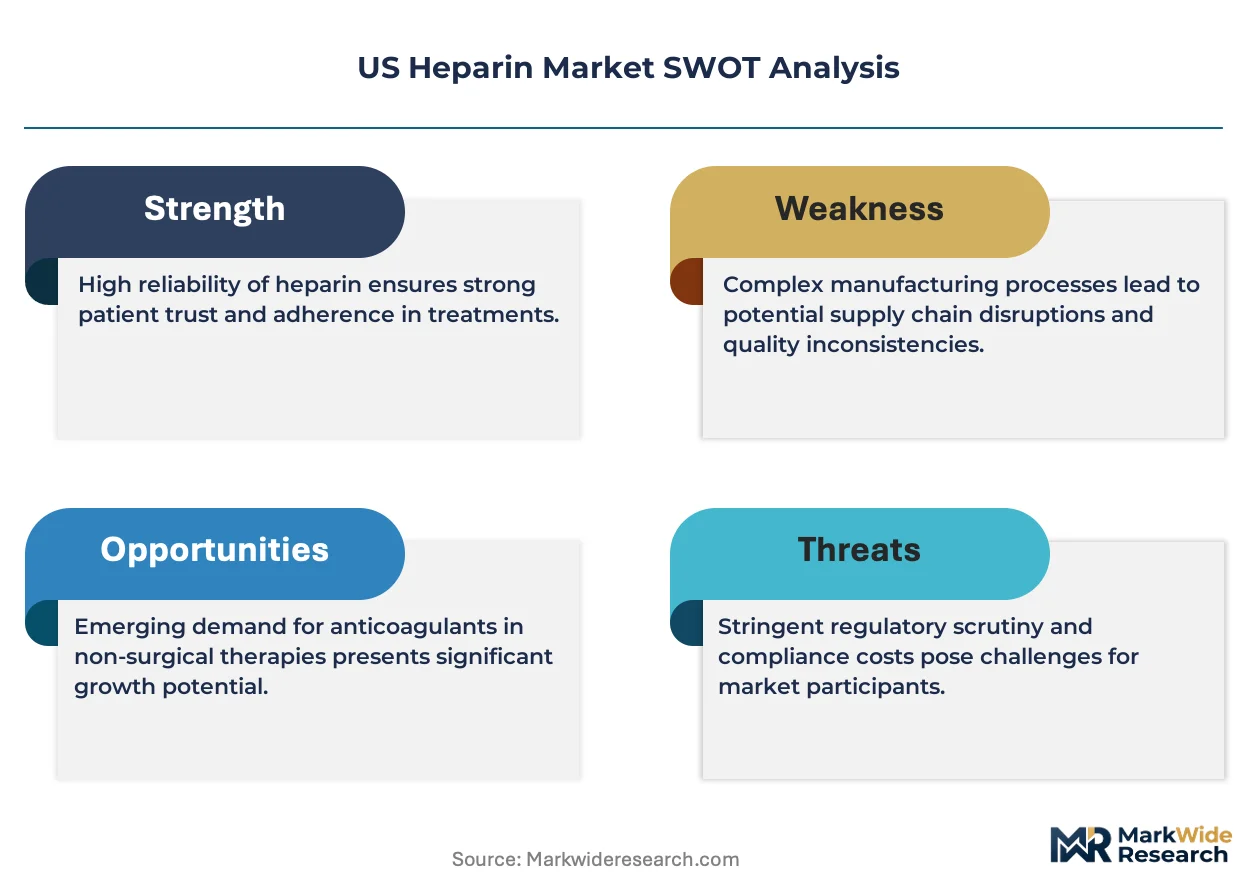
FDA, USP, and the Department of Health and Human Services shape heparin market access through API traceability mandates, potency standard enforcement, and strategic national stockpile procurement priorities. These frameworks elevate barriers for non-domestic manufacturers while rewarding suppliers with verified porcine supply chains and finished-dose redundancy. Stakeholders must monitor FDA inspectional focus on heparin sodium suppliers and assess backward integration into controlled sourcing as a defensive priority.
Market Dynamics
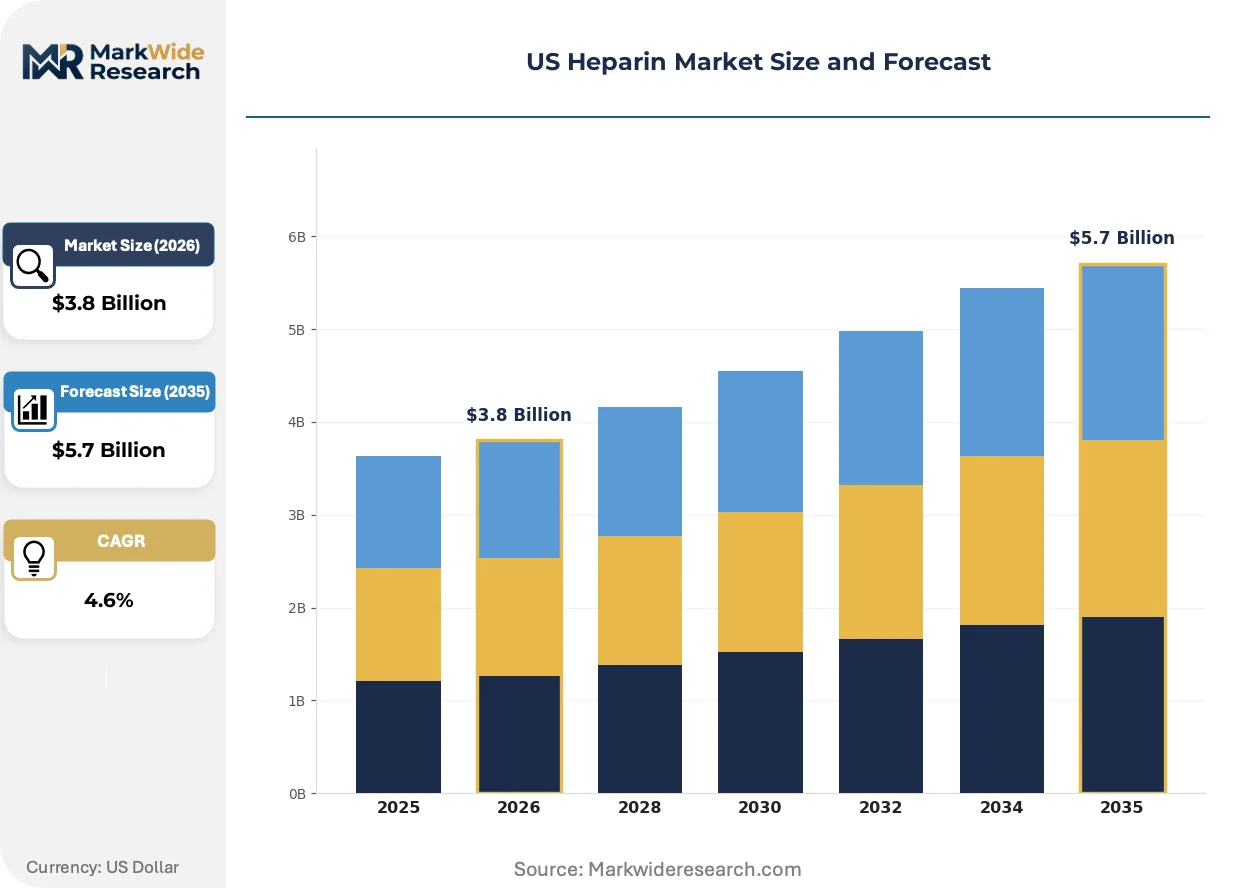
FDA's tightened API traceability mandates are forcing hospital procurement departments to requalify heparin suppliers, privileging manufacturers with verified domestic porcine supply chains and redundant finished-dose capabilities over low-cost importers.
Growth Catalysts
- Rebound in elective surgical volumes:Orthopedic and cardiovascular procedure backlogs across Texas, California, and Florida hospital systems are expanding anticoagulant formularies and unit demand for pre-filled heparin syringes.
- Low molecular weight heparin pharmacokinetics:Predictable anticoagulation profiles reduce monitoring burdens in dialysis centers and home care settings, accelerating protocol adoption.
- Strategic National Stockpile procurement priorities:Department of Health and Human Services stockpiling requirements for critical anticoagulants secure multi-year offtake commitments for qualified domestic manufacturers.
Market Restraints
- Porcine mucosa supply concentration:Over 80% of US heparin API derives from Chinese porcine intestinal tissue, creating geopolitical and contamination risk exposure.
- FDA inspectional intensity:Current Good Manufacturing Practice enforcement actions against foreign heparin sodium facilities are reducing qualified supplier pools and extending lead times.
- Direct oral anticoagulant substitution:DOACs like apixaban and rivaroxaban displace heparin in stable outpatient anticoagulation, compressing addressable market expansion in non-acute settings.
Strategic Opportunities
- Home infusion channel expansion:Medicare reimbursement shifts toward outpatient parenteral anticoagulation create white space for pre-filled heparin syringe formats in home health agencies.
- Bovine lung heparin reactivation:FDA pathway development for non-porcine anticoagulant sources offers supply diversification for religious and allergy-sensitive patient populations.
- USP monograph compliance premium:Hospitals are paying tiered premiums for heparin lots with full API batch documentation, rewarding backward-integrated manufacturers.
Industry Challenges
- Analytical chemist scarcity:Heparin potency testing requires specialized chromatography expertise that contract laboratories struggle to staff, extending release timelines.
- Legacy ERP integration:Hospital procurement systems require expensive middleware upgrades to support FDA-mandated API lot-level traceability data fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Heparin Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfractionated Heparin, Low Molecular Weight Heparin, Heparin Sodium, Heparin Calcium Application: Cardiology, Orthopedic Surgery, Neurology, Hematology End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Delivery Mode: Injection, Infusion, Pre-filled Syringes, Others |
| Companies Covered | Pfizer Inc., Baxter International Inc., Amphastar Pharmaceuticals, Inc., Fresenius Kabi USA LLC, B. Braun SE, Sagent Pharmaceuticals, Dr. Reddy's Laboratories Ltd., Sanofi, Viatris Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Heparin Market Emerging Trajectories
Synthetic heparin analogs and recombinant production platforms are disrupting traditional porcine-derived supply chains, while digital traceability systems and shifting procurement governance reshape how anticoagulants reach end-users.
Biosimilar low molecular weight heparin formulations are fragmenting the hospital formulary landscape. Regional health systems in Florida and Texas are piloting interchangeable enoxaparin substitutes to reduce per-procedure anticoagulation costs. This technology is fragmenting purchasing consortium leverage, as individual hospitals gain latitude to source from secondary suppliers without therapeutic switching committees.
FDA's Drug Supply Chain Security Act implementation timeline for lot-level traceability is compressing heparin supplier qualification windows. Manufacturers must deploy interoperable serialization systems by November 2024 or face distribution lockout. Injectable anticoagulant portfolios are most affected, with hospital GPOs demanding pre-implementation compliance attestations from incumbent vendors.
Consolidated service line procurement is displacing fragmented category management in large hospital systems. Cardiovascular service lines now control anticoagulant selection rather than pharmacy departments, elevating clinical outcome data over unit price in supplier scorecards. This shift is most visible in California's integrated delivery networks, where cath lab directors hold veto power over heparin sodium sourcing decisions.
US Heparin Market Segmentation
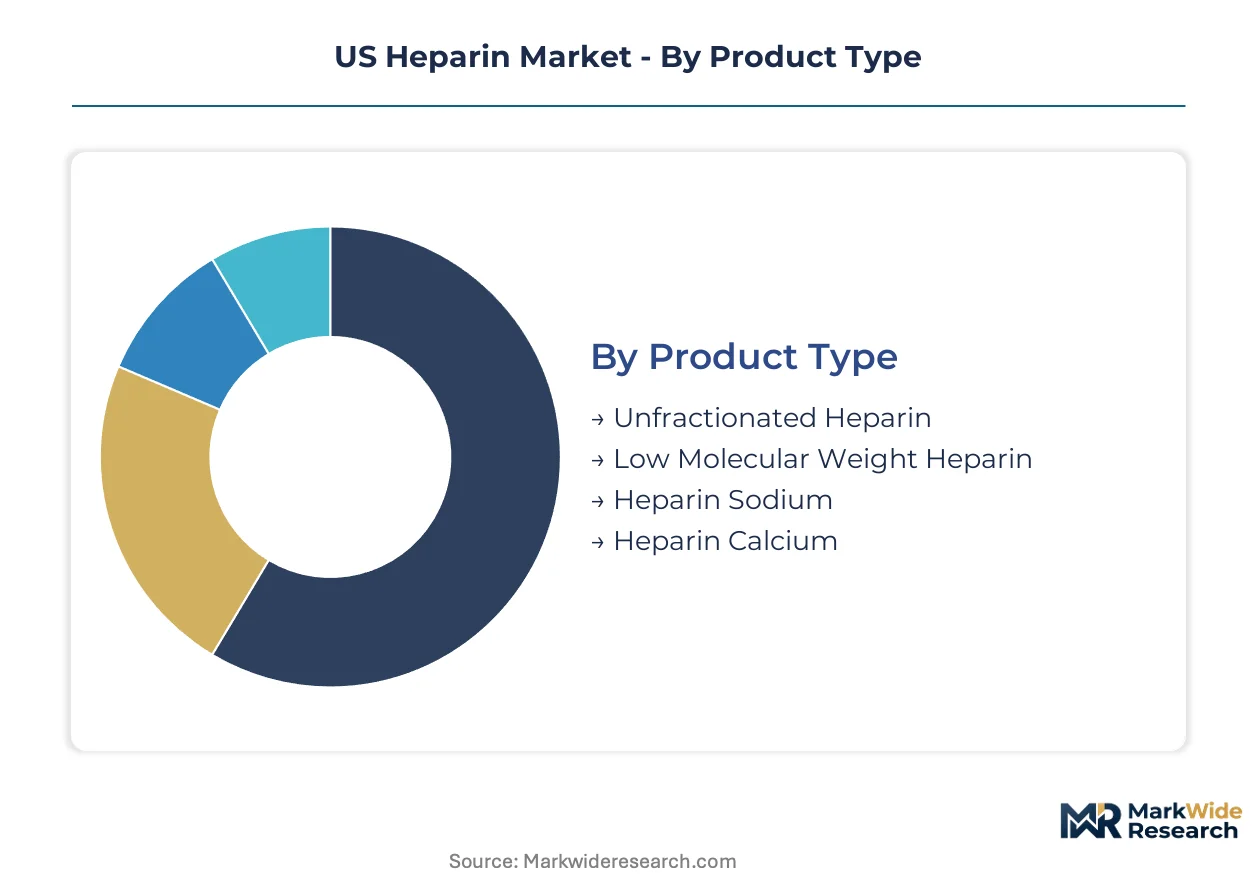
Heparin procurement in the United States fragments across product chemistry, clinical application, and care setting. Each segment carries distinct FDA compliance burdens and margin profiles that determine supplier viability.
Product Type:
Margin pools concentrate in formulations with extended half-lives and reduced monitoring requirements.
- Low Molecular Weight Heparin:Sulfated glycosaminoglycan chains averaging 4,000 to 6,000 daltons deliver predictable anticoagulation profiles. Texas and Florida dialysis centers are standardizing on enoxaparin protocols to reduce nursing labor in high-throughput units.
- Unfractionated Heparin:Native porcine-derived polysaccharide with molecular weights spanning 5,000 to 30,000 daltons requires continuous activated partial thromboplastin time monitoring. California cardiovascular service lines retain this format for procedural flexibility in cath labs where rapid reversal remains critical.
- Heparin Sodium:Sodium salt formulation dominates hospital infusion bags and premixed solutions for surgical thromboprophylaxis.
- Heparin Calcium:Calcium salt variant reduces injection site pain in subcutaneous administration protocols for outpatient anticoagulation.
Low molecular weight heparin holds installed capacity. Unfractionated heparin is rotating up the share rankings in procedural settings where reversibility commands premium pricing.
Application:
Volume concentrates where procedure backlogs intersect with mandatory anticoagulation protocols.
- Cardiology:Percutaneous coronary intervention and atrial fibrillation ablation procedures drive unit demand across California integrated delivery networks. Cath lab directors in these systems now control formulary decisions, elevating outcome data over acquisition cost in supplier scorecards.
- Orthopedic Surgery:Total joint replacement and spinal fusion protocols require extended thromboprophylaxis. Florida hospital systems are expanding pre-filled syringe inventories to address elective surgery backlogs in high-volume orthopedic centers.
- Neurology:Ischemic stroke management and neurointerventional procedures utilize heparin for intra-arterial thrombolysis.
- Hematology:Disseminated intravascular coagulation and heparin-induced thrombocytopenia management represent narrower but higher-margin specialty applications.
Cardiology commands the largest addressable procedure volume. Orthopedic surgery is expanding most quickly as deferred interventions clear surgical schedules.
End User:
Procurement sophistication varies sharply across facility type and reimbursement environment.
- Hospitals:Large health systems in Texas, California, and Florida operate consolidated service line procurement that displaces fragmented pharmacy category management. Cardiovascular service lines now hold veto authority over anticoagulant selection.
- Home Care:Medicare reimbursement shifts toward outpatient parenteral anticoagulation are creating white space for pre-filled heparin syringe formats. Home health agencies in California are piloting patient self-administration protocols.
- Clinics:Ambulatory surgery centers and infusion centers require rapid-turn inventory with lot-level traceability documentation.
- Diagnostic Laboratories:Coagulation testing and reference laboratories utilize heparin as anticoagulant in blood collection tubes and assay reagents.
Hospitals retain the deepest backward integration into supplier qualification. Home care is climbing the fastest as reimbursement migration accelerates.
Delivery Mode:
Packaging format determines channel access and inventory carrying cost structure.
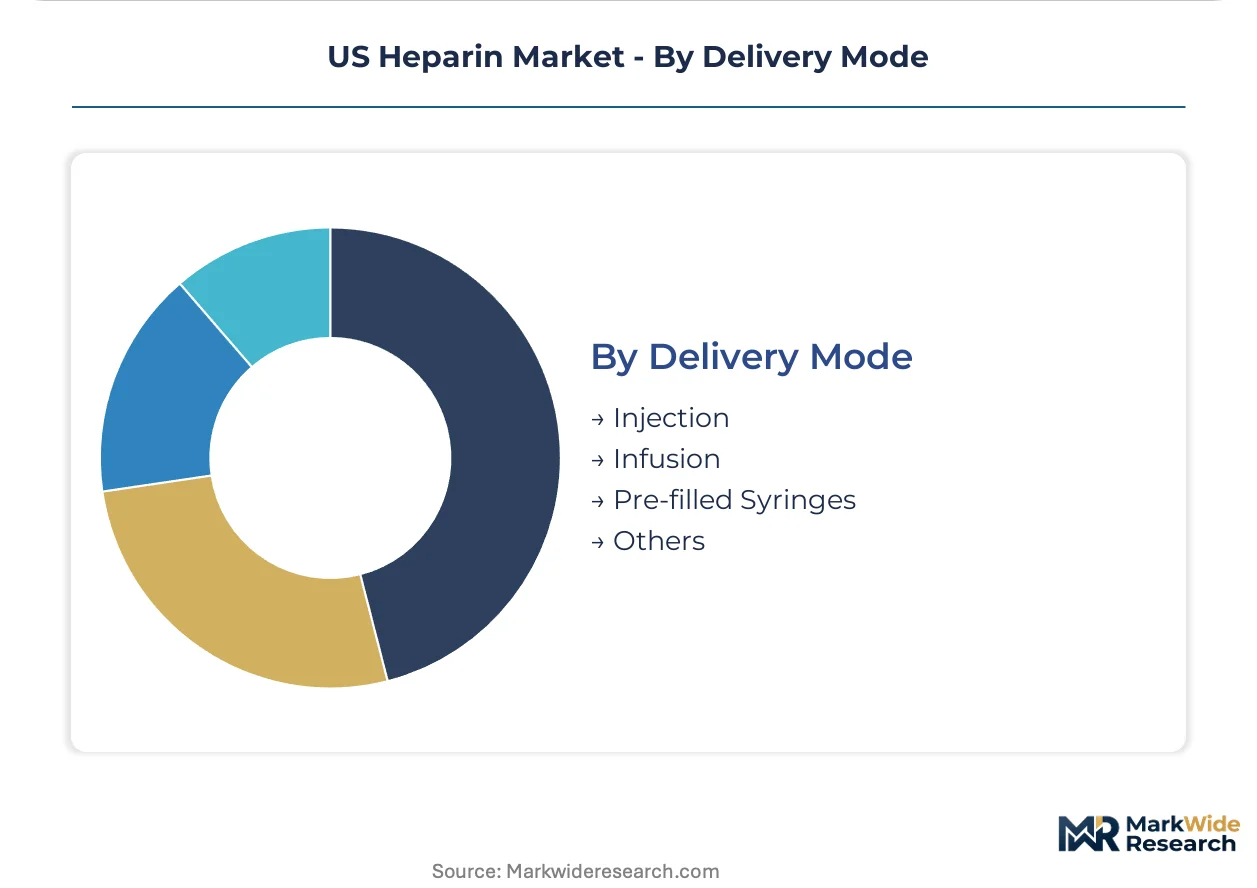
- Pre-filled Syringes:Single-unit sterile syringes reduce dosing errors and nursing preparation time. Home health agencies and surgical pre-admission clinics in Florida are adopting this format to support patient discharge protocols.
- Injection:Multi-dose vials serve high-throughput surgical centers where batch preparation efficiency outweighs single-unit convenience.
- Infusion:Premixed heparin sodium in large-volume parenteral bags anchors hospital pharmacy automation and smart pump integration.
- Others:Includes topical heparin formulations and specialty compounding formats for niche clinical scenarios.
Infusion retains the largest installed base in acute care. Pre-filled syringes is gaining share fastest as care settings shift toward outpatient and home administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors pharmaceutical import volume on the West Coast, while the Houston Ship Channel secures Gulf Coast distribution for porcine-derived active pharmaceutical ingredients. These maritime gateways position California and Texas as the dominant nodes for heparin supply chain throughput.
California
Integrated delivery networks in Los Angeles and San Francisco are consolidating cardiovascular service line procurement, with cath lab directors gaining veto authority over anticoagulant selection. FDA's Drug Supply Chain Security Act enforcement pressures hospital systems to upgrade ERP systems for lot-level traceability. The San Diego biotech corridor hosts contract analytical laboratories specializing in heparin potency testing.
Texas
Dialysis center networks in Houston and Dallas are standardizing on enoxaparin protocols to reduce nursing labor in high-throughput units. The Department of Health and Human Services maintains strategic national stockpile warehousing in Fort Worth for critical anticoagulant reserves. Medical Center Houston anchors the largest concentration of cardiovascular procedural volume in the South Central region.
Florida
Orthopedic surgery backlogs in Tampa and Miami are expanding pre-filled syringe inventories to address deferred joint replacement procedures. State health department procurement rules favor suppliers with verified domestic porcine supply chains. The Orlando health sciences cluster supports home health agency pilot programs for patient self-administration of parenteral anticoagulants.
New York Metro
Academic medical centers in Manhattan and Long Island retain unfractionated heparin for procedural flexibility in interventional cardiology suites. New York State Department of Health regulations mandate enhanced documentation for imported API lots. The Port of Newark-Elizabeth handles East Coast heparin sodium shipments for distribution into Northeast hospital networks.
Illinois
Chicago-based hospital procurement consortia are negotiating multi-year offtake agreements with qualified domestic manufacturers. Illinois Medicaid reimbursement shifts are creating outpatient parenteral anticoagulation pathways for home care transitions. The Rockford pharmaceutical manufacturing corridor hosts finished-dose heparin packaging operations.
US Heparin Market Vendor Landscape
Listed leaders compete with private specialists across plasma-derived API sourcing and hospital channel access. The US heparin market exhibits tiered concentration, with integrated pharmaceutical conglomerates holding hospital formulary positions while mid-scale injectable specialists capture ambulatory surgery center volume. Three archetypes dominate: backward-integrated plasma fractionators, premixed infusion bag suppliers, and multi-dose vial formatters. Competitive moves center on API supply chain redundancy investments and premixed portfolio expansions.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Baxter International Inc. exemplify the backward-integrated archetype with captive porcine supply chain control. Amphastar Pharmaceuticals, Inc. occupies a position within the injectable specialty tier, representing format-focused suppliers that serve high-throughput surgical centers. These three entities anchor the competitive structure, with each archetype competing through distinct channel relationships rather than direct product substitution.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Baxter International Inc. |
| Amphastar Pharmaceuticals, Inc. |
| Fresenius Kabi USA LLC |
| B. Braun SE |
| Sagent Pharmaceuticals |
| Dr. Reddy's Laboratories Ltd. |
| Sanofi |
| Viatris Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day API release timelines concentrate pricing power among manufacturers with captive analytical laboratories, while hospital procurement departments absorb inventory carrying costs that tier contract values across qualified supplier pools. FDA's Drug Supply Chain Security Act mandates force ERP upgrade investments that stratify purchasing consortium leverage, embedding traceability premiums into landed heparin sodium costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the hospital formulary landscape, with USP monograph compliance and full API batch documentation driving tier placement. Volume-scale discounts concentrate among Texas and Florida health systems with consolidated cardiovascular service line procurement, while standalone orthopedic centers face higher per-unit acquisition costs. Cost compression in standard-tier unfractionated heparin is intensifying because biosimilar enoxaparin entrants fragment purchasing leverage. Ambulatory surgery centers exhibit highest price sensitivity due to procedure-based reimbursement constraints; integrated delivery networks prioritize outcome data over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate Department of Health and Human Services procurement, while hospital pharmacies maintain just-in-time inventory to minimize heparin sodium degradation risk. Over 80% of US heparin API draws from Chinese porcine intestinal tissue, with domestic porcine mucosa and bovine lung alternatives anchoring diversification efforts. Single-source vulnerability concentrates in API extraction and sulfation chemistry capabilities, with contamination events triggering rapid supplier switching. Distribution runs through hospital GPO contracts and direct manufacturer agreements, bypassing wholesale intermediaries for injectable anticoagulants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across Texas, California, and Florida has shifted buyer power toward cardiovascular service lines, fragmenting traditional pharmacy category management authority and elevating clinical outcome metrics in supplier selection.
For Market Incumbents: Secure redundant finished-dose capabilities and captive porcine supply chain control to defend against FDA inspectional actions that disqualify foreign API facilities. Deepen backward integration into US-based porcine mucosa sourcing as biosimilar enoxaparin entrants compress standard-tier margins. For New Entrants and Emerging Players: Anchor in Medicare-reimbursed home infusion channels where pre-filled syringe demand outpaces incumbent manufacturing capacity. Target Florida and California home health agencies with patient self-administration protocols, leveraging direct-to-provider contracting outside GPO frameworks. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting injectable specialty units with stranded hospital formulary positions. Five-to-ten year viability hinges on FDA compliance infrastructure and verified domestic API sourcing; monitor FDA warning letter issuance rates as inflection indicator for supplier pool contraction.| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Chain Redundancy Investment | Domestic porcine sourcing secures continuity against Chinese import disruption. |
| Pre-filled Syringe Manufacturing Scale-Up | Home care reimbursement shifts demand patient-administered anticoagulant formats. |
| USP Monograph Compliance Certification | Full batch documentation commands tiered hospital procurement premiums. |
| Bovine Lung Heparin FDA Pathway Development | Non-porcine sources address religious and allergy-sensitive patient populations. |
| Hospital GPO Direct Contracting | Cardiovascular service line control bypasses traditional pharmacy procurement. |
Methodological Framework
Desk research of FDA inspectional databases, USP monograph revision records, and hospital GPO contract filings preceded structured interviews with heparin sodium procurement directors, dialysis center medical directors, cath lab directors, and contract analytical laboratory managers. Secondary validation drew from FDA warning letter archives, CMS Medicare reimbursement bulletins, and porcine supply chain trade publications. Bottom-up unit demand modeling triangulated against top-down pharmaceutical import data.
Variance decomposition across product chemistry, clinical application, care setting, and delivery mode dimensions structured the analytical framework throughout the forecast period. CAGRs derived from procedure volume elasticity to surgical backlog clearance and anticoagulant protocol substitution rates. Forecast inputs incorporated FDA Drug Supply Chain Security Act implementation compliance timelines and strategic national stockpile procurement commitments.
Underlying assumptions cover elective surgical volume recovery trajectories and heparin-induced thrombocytopenia incidence stability, with deviation risk concentrated in Chinese API import restrictions and DOAC substitution acceleration. Forecasts reflect these documented conditions. Revision becomes warranted when FDA inspectional disqualification rates cross thresholds that eliminate qualified supplier capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Hydrogel Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Chitosan Films Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Bone Substitutes Market
Biomaterials
Chitosan Oligosaccharides Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Flowable Hemostats Market