
 Resorbable Polymers Market | 2026-2036
Resorbable Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Resorbable Polymers Market Analytics
Subscription-based polymer characterization services are restructuring how raw material suppliers monetize technical relationships with device manufacturers. Evonik Industries AG leverages its biomaterials testing infrastructure to sustain long-term contracts with orthopedic OEMs. Corbion N.V. anchors global PLA supply for medical-grade applications through captive lactide production. Poly-Med Incorporated specializes in custom extrusion of absorbable fibers for niche surgical applications.
Resorbable polymers comprise aliphatic polyesters—primarily polylactic acid (PLA), polyglycolic acid (PGA), and their copolymer PLGA—that hydrolyze into biocompatible byproducts within controlled timeframes ranging from weeks to years depending on crystallinity and molecular weight. These materials serve as temporary structural supports in drug delivery matrices, tissue scaffolds, and surgical implants that eliminate secondary removal procedures. PLGA dominates current volume due to its tunable degradation kinetics, while PGA maintains premium positioning in high-tensile suture applications where rapid absorption is clinically required. Film and scaffold forms command superior margins compared to commodity powder grades because downstream device makers demand validated batch-to-batch consistency.
FDA 510(k) and PMA pathways enforce stringent biocompatibility testing under ISO 10993 standards, while EMA's Medical Device Regulation mandates enhanced clinical evidence for resorbable implantables entering European markets. REACH compliance in the European Union further constrains residual monomer thresholds, pushing manufacturers toward purer polymerization catalysts and post-processing protocols. Stakeholders must monitor evolving biodegradability certification frameworks in Asia-Pacific jurisdictions where national pharmacopeias are drafting polymer-specific monographs.
Market Dynamics
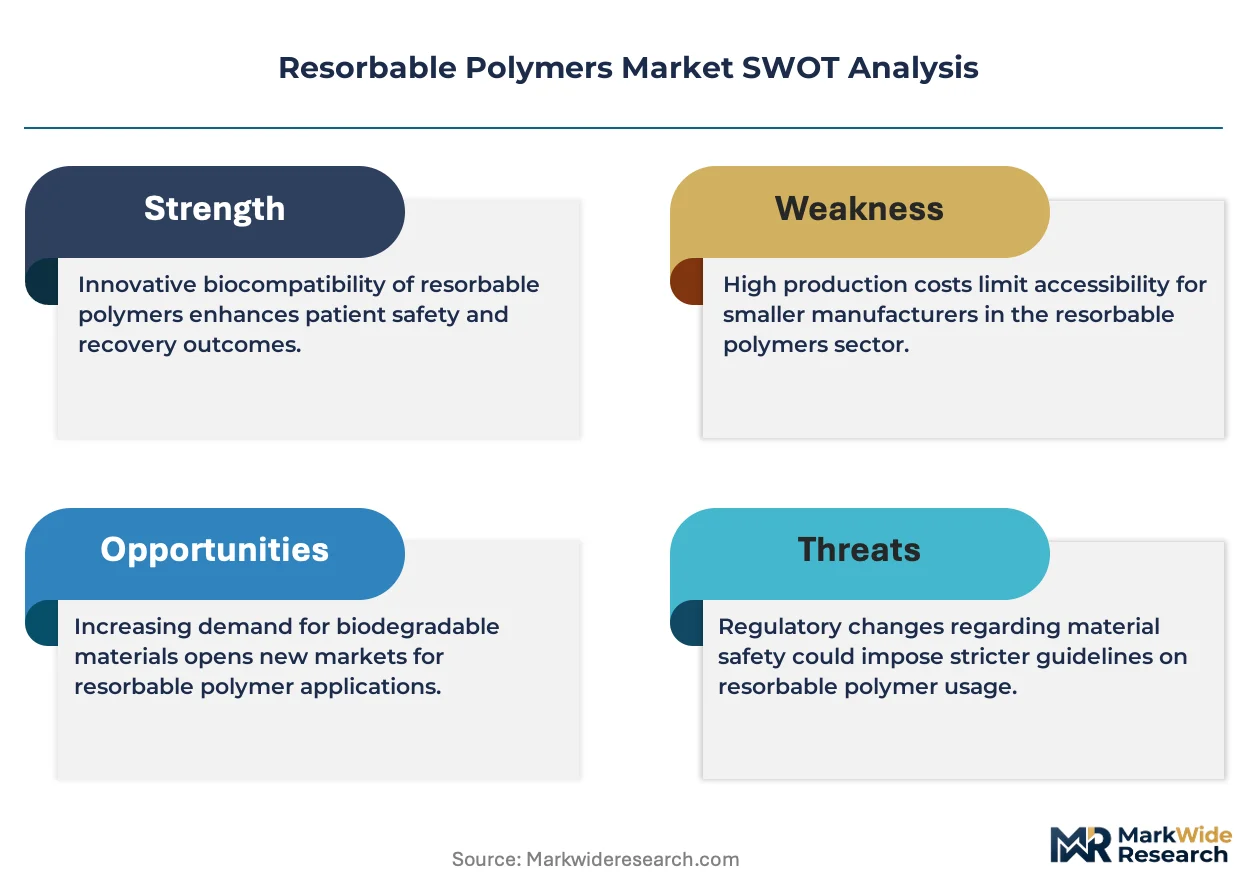
FDA's tightening purity documentation for Class III bioresorbable devices is forcing raw material suppliers to invest in validated batch-to-batch consistency infrastructure, restructuring contractual relationships between polymer producers and orthopedic OEMs.
Growth Catalysts
- EMA Medical Device Regulation:Enhanced clinical evidence requirements for resorbable implantables are accelerating hospital procurement of pre-validated polymer grades from certified suppliers in Germany and South Korea.
- Aliphatic polyester copolymer innovation:Tunable PLGA degradation kinetics are enabling drug-eluting scaffold applications that eliminate secondary removal procedures in cardiovascular interventions.
- Orthopedic implant demand clusters:Bioresorbable fixation device sourcing is intensifying across hospital networks in the United States, Germany, and South Korea where surgical volume concentrates.
Market Restraints
- Lactide feedstock concentration:Corbion N.V.'s captive production anchors global medical-grade PLA supply, creating single-source vulnerability for specialized polymerization catalysts.
- ISO 10993 biocompatibility testing costs:Multi-phase cytotoxicity and degradation-profile validation extends development timelines for novel resorbable formulations entering FDA 510(k) pathways.
- REACH residual monomer thresholds:European Union chemical compliance mandates purer post-processing protocols that compress margins for commodity powder-grade producers.
Strategic Opportunities
- Asia-Pacific pharmacopeia development:National polymer-specific monograph drafting in South Korea and Japan creates first-mover positioning for degradation-profile documentation services.
- Custom absorbable fiber extrusion:Niche surgical applications in microsuture and neural conduit segments reward specialized production capabilities outside commodity PLGA volume plays.
- Subscription-based characterization services:Long-term technical contracts for biomaterials testing are monetizing supplier-manufacturer relationships beyond transactional raw material sales.
Industry Challenges
- Degradation-profile prediction expertise:Hydrolysis kinetics modeling for crystallinity-molecular weight interactions requires polymer scientists with medical-device regulatory exposure, a scarce hybrid skill set.
- Batch-to-batch validation infrastructure:Film and scaffold form producers must maintain in-house metrology capabilities that commodity powder-grade competitors cannot replicate, demanding sustained capex commitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resorbable Polymers Market |
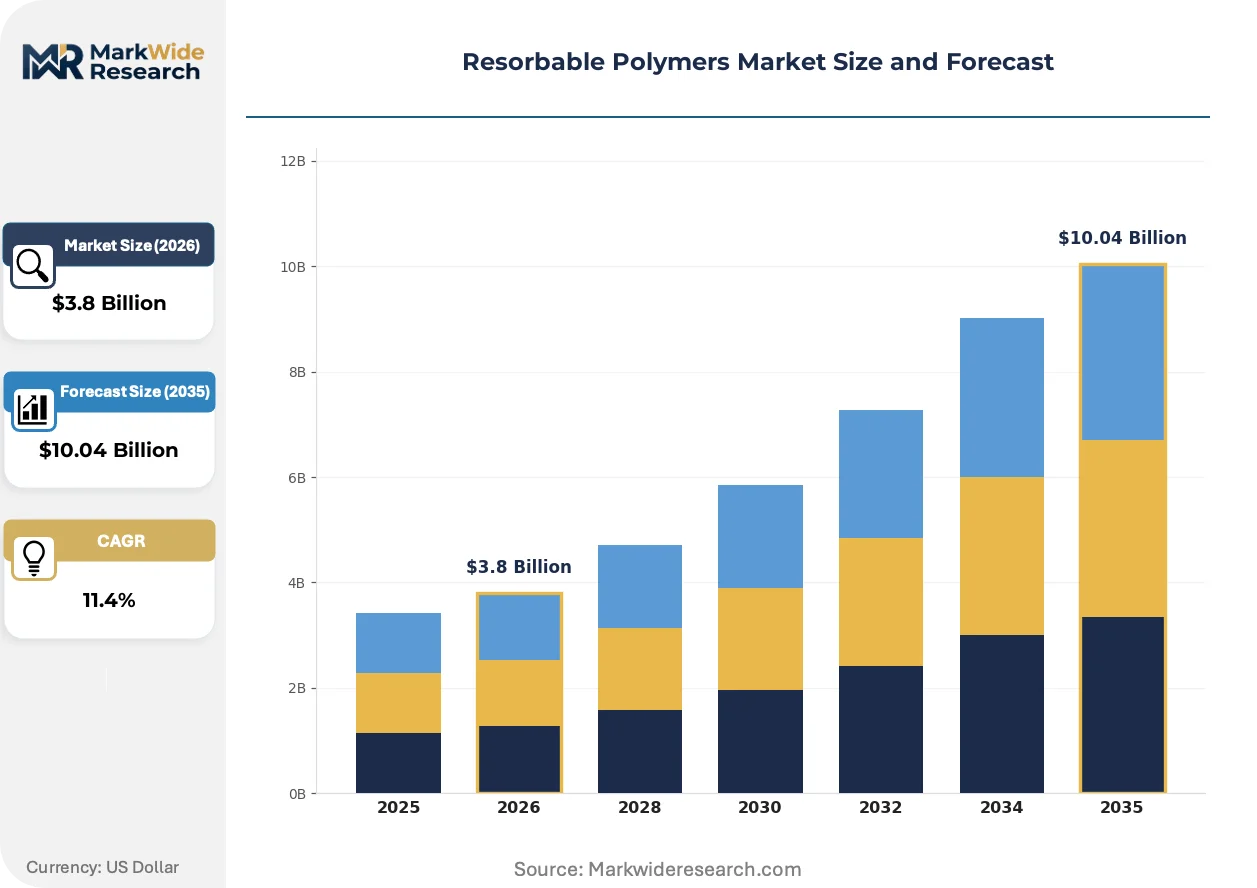
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PGA, PLGA, PBS Application: Drug Delivery, Tissue Engineering, Sutures, Implants End User: Hospitals, Clinics, Research Laboratories, Academic Institutes Form: Films, Powders, Fibers, Scaffolds |
| Companies Covered | Corbion N.V., Evonik Industries AG, Foster Corporation, KLS Martin Group, DSM Biomedical, Ashland Global Holdings Inc., Poly-Med Incorporated, Zeus Company LLC, Seqens Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resorbable Polymers Market Evolving Landscape
Electrospun nanofiber scaffold fabrication is converging with 3D bioprinting workflows, compressing development cycles for personalized tissue engineering applications while forcing polymer suppliers to qualify novel rheological specifications.
Bioresorbable polymer synthesis is converging with surface modification chemistries to enable cell-adhesive ligand presentation without compromising bulk degradation kinetics. Tissue engineering laboratories at academic medical centers in Germany and South Korea are piloting these hybrid materials for osteochondral defect repair. The structural consequence is compression of traditional scaffold-fabrication equipment margins as integrated material-function platforms displace commodity substrate sales.
REACH compliance enforcement is tightening residual monomer thresholds for aliphatic polyesters entering European medical device supply chains. ECHA's expanded substance evaluation obligations are forcing polymerization catalyst substitution toward organometallic systems with cleaner degradation byproduct profiles. High-tensile PGA suture manufacturers serving EU markets are absorbing reformulation costs that commodity PLA powder producers cannot pass through to price-sensitive packaging applications.
Hospital procurement of resorbable fixation devices is consolidating toward integrated sourcing agreements that bundle polymer supply with validated device design history files. Orthopedic OEMs in the United States are displacing spot-market raw material purchases with multi-year characterization service contracts. This contractual shift concentrates volume with suppliers maintaining captive biomaterials testing infrastructure, marginalizing polymer producers without in-house ISO 10993 capabilities.
Resorbable Polymers Market Segmentation
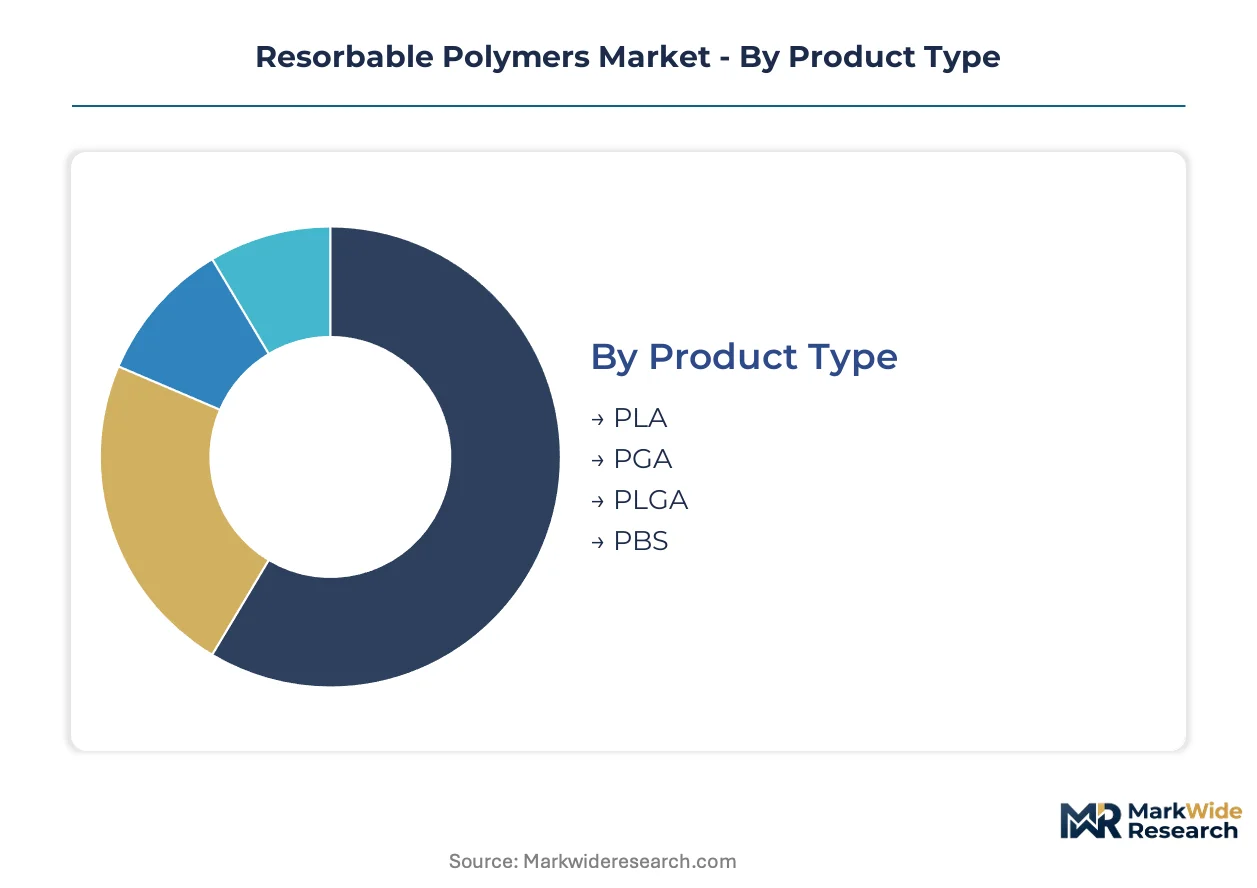
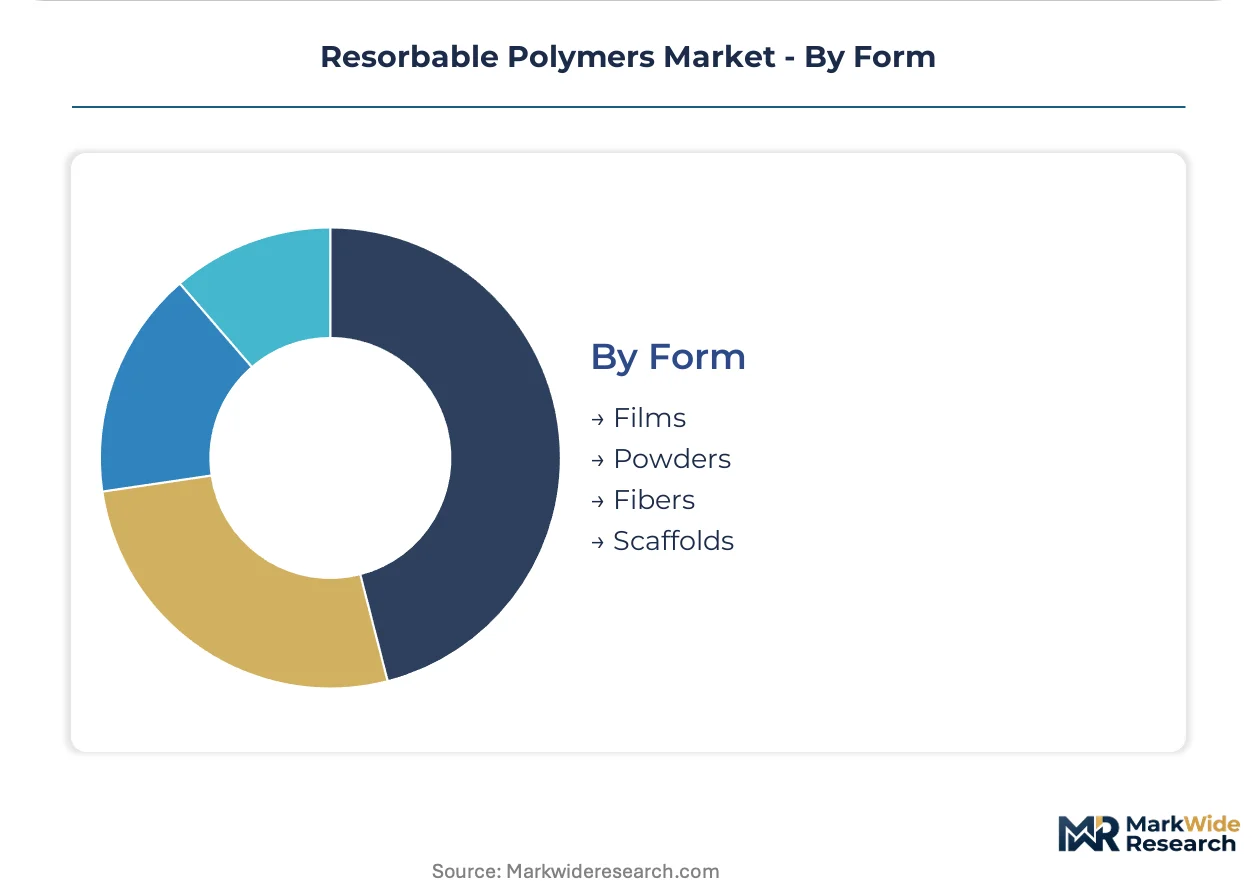
Resorbable polymer segmentation reflects divergent purity requirements across medical applications. Device manufacturers specify crystallinity and molecular weight thresholds that commodity suppliers cannot meet. Form factor selection determines whether batch-to-batch validation infrastructure becomes a competitive necessity.
Product Type:
Standardization dominates commodity aliphatic polyesters while custom copolymer ratios command premium positioning in cardiovascular and orthopedic niches.
- PLA:Polylactic acid serves as the baseline medical-grade polyester with degradation timelines spanning months to years depending on stereochemistry. Hospital procurement of PLA-based fixation devices concentrates in Germany and the United States where orthopedic surgical volume supports validated supply agreements.
- PGA:Polyglycolic acid hydrolyzes rapidly within weeks, making it indispensable for high-tensile suture applications where absorption speed reduces foreign body response. Demand clusters in South Korean and United States hospital networks where surgical throughput justifies premium pricing for rapid-resorption formulations.
- PLGA:Copolymer ratios enable tunable degradation kinetics unattainable with homopolymers alone.
- PBS:Polybutylene succinate offers alternative hydrolysis profiles for packaging-adjacent medical applications.
Most installed capacity flows through PLA. Expansion is steepest in PLGA where drug-eluting scaffold applications multiply.
Application:
Margin structure inverts between commodity suture markets and scaffold applications requiring ISO 10993 batch validation.
- Drug Delivery:Polymer matrices control active pharmaceutical ingredient release through surface erosion and bulk degradation mechanisms. PLGA microparticle formulations dominate United States and German markets where FDA and EMA pathways enforce degradation-profile documentation for parenteral depot injections.
- Tissue Engineering:Electrospun and 3D-bioprinted scaffolds demand custom rheological specifications and cell-adhesive surface modifications. Academic medical centers in South Korea and Germany pilot hybrid materials for osteochondral defect repair, compressing traditional substrate margins.
- Sutures:High-volume surgical consumption rewards scale producers with validated sterilization protocols.
- Implants:Bioresorbable fixation devices require multi-year characterization service contracts beyond transactional raw material sales.
Drug delivery captures the highest value per kilogram. Tissue engineering is climbing the fastest as personalized medicine applications proliferate.
End User:
Procurement sophistication varies from research-scale custom synthesis to hospital-system integrated sourcing agreements.
- Hospitals:Integrated sourcing agreements now bundle polymer supply with validated device design history files, displacing spot-market purchases. United States orthopedic OEMs concentrate volume with suppliers maintaining captive biomaterials testing infrastructure.
- Clinics:Outpatient surgical centers source pre-validated suture and fixation device formats through distributor networks.
- Research Laboratories:Custom extrusion and small-batch characterization services support prototype scaffold development.
- Academic Institutes:Grant-funded tissue engineering programs pilot novel surface modification chemistries before commercial translation.
Hospitals absorb the greatest polymer volume. Academic institutes are gaining share fastest as translational research funding expands.
Form:
Downstream processing intensity separates film and scaffold producers from commodity powder competitors.
- Films:Thin-sheet formats for barrier membranes and drug-eluting layers require in-house metrology capabilities that validate thickness uniformity and degradation-profile consistency. German and South Korean device manufacturers specify film grades with documented crystallinity distributions.
- Scaffolds:Porous architectures for tissue engineering integrate electrospinning and 3D-bioprinting workflows, forcing polymer suppliers to qualify novel rheological specifications. United States and German academic medical centers drive specification evolution.
- Powders:Micronized grades serve compression molding and solvent-casting processes with lower barrier to entry.
- Fibers:Extruded filaments for suture and textile applications demand high-tensile PGA or PLGA with controlled draw ratios.
Most validated production capacity serves film formats. Scaffold applications show the steepest specification evolution as bioprinting matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in resorbable polymer procurement intensity despite comparable orthopedic surgical volumes, with German hospital networks demanding more extensive degradation-profile documentation than their American counterparts.
United States
FDA 510(k) and PMA pathways enforce stringent ISO 10993 biocompatibility testing, accelerating hospital procurement of pre-validated polymer grades. The agency's tightening purity documentation for Class III bioresorbable devices forces raw material suppliers toward validated batch-to-batch consistency infrastructure. Greater Boston and Minneapolis-St. Paul host concentrated orthopedic OEM activity where integrated sourcing agreements now displace spot-market purchases.
Germany
EMA Medical Device Regulation mandates enhanced clinical evidence for resorbable implantables entering European markets, driving hospital procurement of certified polymer grades. REACH compliance further constrains residual monomer thresholds, pushing manufacturers toward purer polymerization catalysts. The Baden-Württemberg and Bavaria regions concentrate medical device manufacturing where academic medical centers pilot hybrid surface-modified materials for osteochondral defect repair.
South Korea
MFDS pathways for resorbable medical devices are tightening alongside national pharmacopeia drafting of polymer-specific monographs, creating first-mover positioning for degradation-profile documentation services. Seoul Capital Area hospital networks intensify procurement of resorbable sutures and drug-eluting scaffolds. Busan-Ulsan anchors specialized production capabilities for custom absorbable fiber extrusion serving microsurgical applications.
China
NMPA medical device registration requirements for bioresorbable implants are converging with international standards, though national pharmacopeia development for polymer-specific monographs lags Western jurisdictions. Yangtze River Delta medical device clusters in Shanghai and Suzhou scale domestic PLA and PLGA production capacity. Local manufacturers absorb reformulation costs to meet residual monomer thresholds for export-oriented supply chains.
Japan
PMDA quality management system requirements for resorbable implantables enforce documentation standards comparable to FDA and EMA pathways. METI industrial policy supports domestic biomaterials testing infrastructure development. Kansai region academic medical centers in Osaka and Kyoto pilot electrospun nanofiber scaffold fabrication converging with 3D bioprinting workflows.
Resorbable Polymers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated polymer suppliers capturing long-term characterization service contracts while commodity powder-grade producers compete on spot-market transactions. The vendor base concentrates around three strategic archetypes: multinational chemical conglomerates with captive biomaterials testing infrastructure, specialized medical-grade polymer manufacturers with custom extrusion capabilities, and regional compounders serving distributor networks. Dominant competitive moves include backward integration into lactide feedstock production and multi-year technical service contracts that monetize supplier-manufacturer relationships beyond transactional raw material sales.
Among European-based chemical conglomerates, Evonik Industries AG and Corbion N.V. exemplify contrasting strategic positions within the premium polymer tier. Evonik leverages its biomaterials testing infrastructure to sustain long-term contracts with orthopedic OEMs, representing the integrated service-provider archetype. Corbion anchors global medical-grade PLA supply through captive lactide production, occupying a position that creates single-source vulnerability for specialized polymerization catalysts. Poly-Med Incorporated sits within the specialist tier, its custom extrusion capabilities for absorbable fibers serving niche surgical applications outside commodity PLGA volume plays.
| Leading Market Players |
|---|
| Corbion N.V. |
| Evonik Industries AG |
| Foster Corporation |
| KLS Martin Group |
| DSM Biomedical |
| Ashland Global Holdings Inc. |
| Poly-Med Incorporated |
| Zeus Company LLC |
| Seqens Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders in South Korea and Germany anchor specialized production for medical-grade aliphatic polyesters, translating captive process expertise into pricing discipline that commodity powder-grade competitors cannot match. Their long-tenured technical relationships with orthopedic OEMs insulate premium film and scaffold formats from spot-market volatility.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for commodity PLA powder grades, compressing margins for producers without validated batch-to-batch consistency infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified film grades from unvalidated powder, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from REACH residual monomer compliance costs that commodity producers cannot pass through to packaging-adjacent medical applications. Hospital procurement committees demonstrate lowest price sensitivity for drug-eluting scaffold grades, while distributor-served outpatient clinics drive hardest bargains on standard suture formats.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled resorbable devices remain underdeveloped, with most orthopedic OEMs absorbing write-downs rather than pursuing polymer recovery. Supply concentrates in the Netherlands, Germany, and South Korea for medical-grade lactide and specialized polymerization catalysts. The chain draws from agricultural feedstock for lactic acid, organometallic catalyst systems, and validated sterilization packaging as critical inputs. Single-source vulnerability around Corbion's captive lactide production creates structural risk for PLA-dependent device manufacturers. Distribution runs through integrated sourcing agreements that bundle polymer supply with design history file validation, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards margin expansion through degradation-profile documentation services that transform transactional raw material sales into recurring technical contracts.
For Market Incumbents: Anticipate regulatory divergence between FDA purity documentation and EMA clinical evidence requirements by maintaining dual-pathway validation infrastructure. Deepen backward integration into lactide feedstock to neutralize single-source vulnerability, while investing in electrospinning equipment partnerships that capture specification evolution in tissue engineering scaffolds. For New Entrants and Emerging Players: Academic medical center research laboratories represent the most penetrable channel partner type for custom extrusion services, offering prototype-scale contracts that bypass incumbent volume commitments. Target South Korea's national pharmacopeia development window by positioning degradation-profile documentation capabilities ahead of polymer-specific monograph finalization. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders lacking ISO 10993 in-house capabilities but holding specialized fiber extrusion equipment. Long-term viability hinges on conversion from spot-market commodity sales to subscription-based characterization relationships. Monitor MFDS and PMDA pharmacopeia drafting timelines as inflection indicators for first-mover documentation service premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Production | Neutralizes single-source feedstock risk from Corbion's captive supply dominance. |
| ISO 10993 Biomaterials Testing Infrastructure | Enables long-term characterization contracts with United States orthopedic OEMs. |
| Custom Absorbable Fiber Extrusion Capability | Captures niche margin in microsuture and neural conduit segments outside commodity PLGA. |
| Degradation-Profile Documentation Services | Positions for Asia-Pacific pharmacopeia first-mover advantage in South Korea and Japan. |
| Electrospinning Equipment Partnerships | Qualifies novel rheological specifications for 3D bioprinting workflow integration. |
Research Methodology
Coverage spans the United States, Germany, South Korea, China, and Japan, with primary inputs from each regional cluster. The approach combines interviews with orthopedic OEM procurement directors, polymer plant managers, biomedical engineers at academic medical centers, and GPO contracts managers, validated against FDA 510(k) filings, EMA Medical Device Regulation guidance documents, MFDS pharmacopeia drafts, and customs trade data for lactide and aliphatic polyester flows. Bottom-up capacity modeling and top-down hospital procurement spend analysis provide triangulation.
Granularity-level modeling distinguishes medical-grade from industrial-grade polymer streams, with separate forecasts for PLA, PGA, PLGA, and PBS by application segment, form factor, and end-user procurement sophistication. CAGRs derive from surgical volume projections, regulatory pathway timeline assumptions, and polymerization capacity expansion announcements across the analysis window. Industry-specific inputs include orthopedic procedure coding trends and drug-eluting scaffold clinical trial advancement rates.
Revisions become necessary when FDA or EMA regulatory guidance shifts materially alter degradation-profile documentation requirements, or when lactide feedstock supply disruptions reshape polymerization economics. Practitioners should monitor national pharmacopeia drafting progress in Asia-Pacific jurisdictions and REACH enforcement intensity for residual monomer thresholds as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PEKK Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Polyisobutene Market