
 Global Synthetic Polymers Market | 2026-2036
Global Synthetic Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Polymers Market Outlook
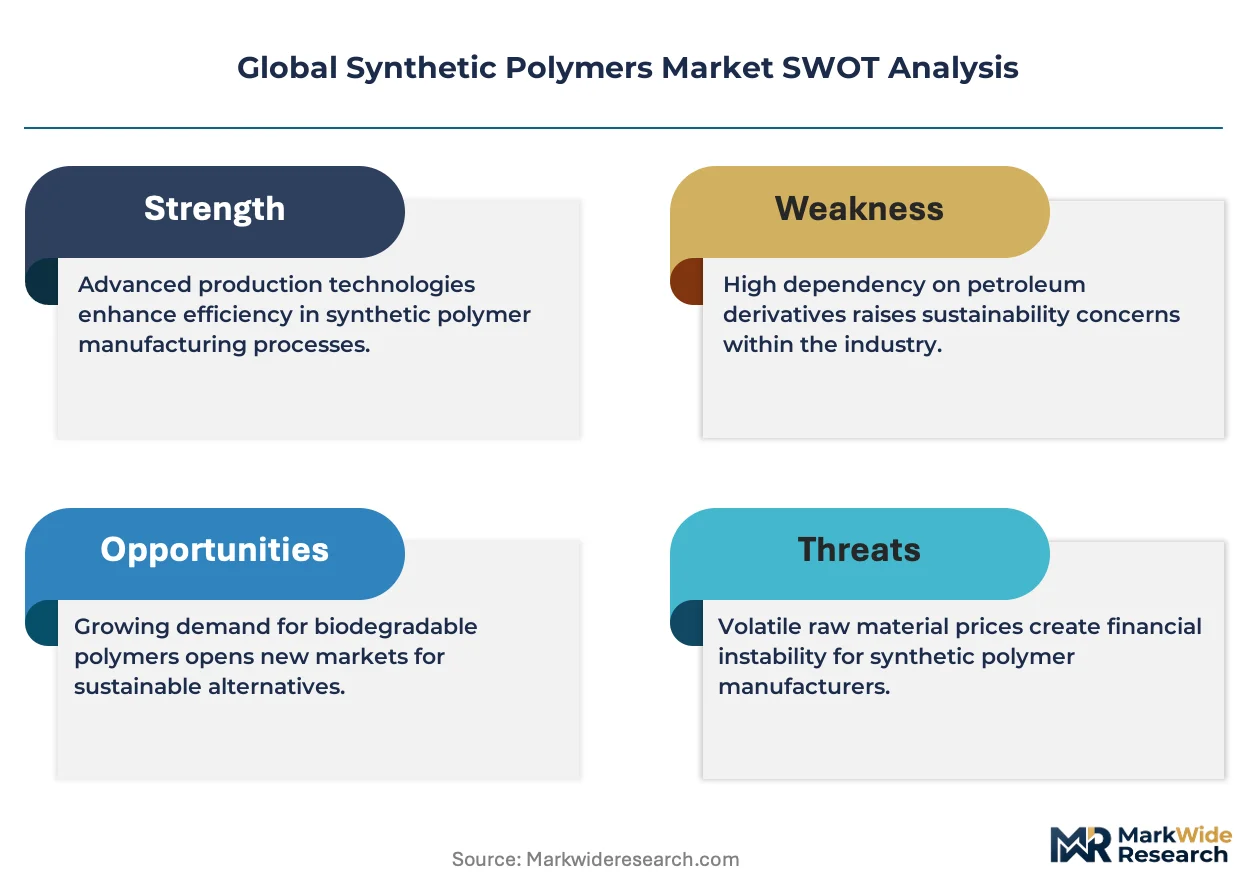
Advanced recycling and bio-based feedstock integration is fragmenting the traditional petrochemical value chain for synthetic polymers. BASF SE leverages its Verbund site network to sustain integrated production economics across Europe and Asia. Dow Inc. anchors its competitive position through proprietary solution-processed polyethylene technologies that serve flexible packaging laminates. SABIC competes aggressively in the Middle East with advantaged ethane feedstock costs and expanding specialty polymer grades for automotive lightweighting.
Synthetic polymers comprise macromolecular compounds built from repeating monomer units through addition or condensation polymerization, typically achieving molecular weights exceeding 10,000 g/mol and exhibiting tunable thermal, mechanical, and barrier properties for industrial fabrication. Their primary commercial purpose centers on substituting metal, glass, and natural materials across mass-manufacturing sectors where cost-efficiency, design freedom, and corrosion resistance prove decisive. Polyethylene dominates volume production as the workhorse commodity resin serving single-use packaging and construction membranes, while nylon retains structural margin pools in automotive under-hood components and industrial fibers demanding heat resistance. The films and fibers forms command premium positioning relative to bulk granules, reflecting downstream conversion complexity and specification intensity in medical textiles and optical display substrates.
The EPA regulates polymer manufacturing emissions under Clean Air Act Title V permitting, while REACH mandates registration and hazard communication for monomers and additives imported into Europe, effectively raising compliance costs for non-EU producers seeking market access. China's MEE enforces GB standards for volatile organic compound emissions from plastic processing, shaping locational decisions for compounding and extrusion investments. Stakeholders must monitor diverging regulatory trajectories on chemical recyclate content mandates, as these will determine which polymer categories qualify for preferential procurement in packaging and automotive supply chains.
Market Dynamics
Mechanical recycling infrastructure buildout is fragmenting virgin resin demand pools as EU Green Deal mandates force packaging converters to certify recyclate content thresholds. This structural shift is compressing commodity polymer margins while creating premium pricing tiers for certified circular grades.
Growth Catalysts
- E-commerce fulfillment expansion:Asia-Pacific packaging converters are scaling blown film extrusion lines to serve last-mile delivery networks. Polyethylene film specifications are tightening for automated sortation compatibility.
- REACH registration requirements:European chemical safety mandates are raising compliance barriers for non-EU producers. Registered polymer additives command sourcing premiums from medical device manufacturers.
- Automotive lightweighting specifications:Under-hood thermal management applications are displacing metal with high-heat nylon compounds. Engineering resin formulations now specify continuous-use temperatures above 150°C.
Market Restraints
- Naphtha feedstock volatility:European crackers remain exposed to crude-linked naphtha costs. Middle Eastern ethane-based producers sustain 40-50% cost advantages on polyethylene.
- Mechanical recycling yield losses:Sortation contamination and thermal degradation limit recyclate quality. Food-contact applications require super-clean flake grades with sub-100 ppm contaminant thresholds.
- Biopolymer substitution pressure:PLA and PHA grades are capturing premium single-use packaging niches. Compostability certifications are becoming procurement gatekeepers for food service disposables.
Strategic Opportunities
- India PLI scheme for specialty chemicals:Production-linked incentives are drawing greenfield engineered polymer investments. Engineering plastics compounding capacity is concentrating around Gujarat chemical clusters.
- Chemical recycling technology convergence:Pyrolysis and gasification platforms are integrating with steam cracker feedslates. Mixed plastic waste streams are becoming viable raw material inputs.
- Direct-to-converter digital platforms:Polymer distributors are launching B2B marketplaces with real-time pricing. Small and mid-size converters are bypassing traditional stocking distributors.
Industry Challenges
- Polymer process engineering talent scarcity:Extrusion and compounding operations face skilled technician shortages. Vocational training pipelines have not kept pace with Southeast Asian capacity expansion.
- Food-contact certification timelines:Novel recyclate grades require 18-24 month EFSA safety evaluations. Brand owner sustainability commitments are outpacing regulatory clearance velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Polymers Market |
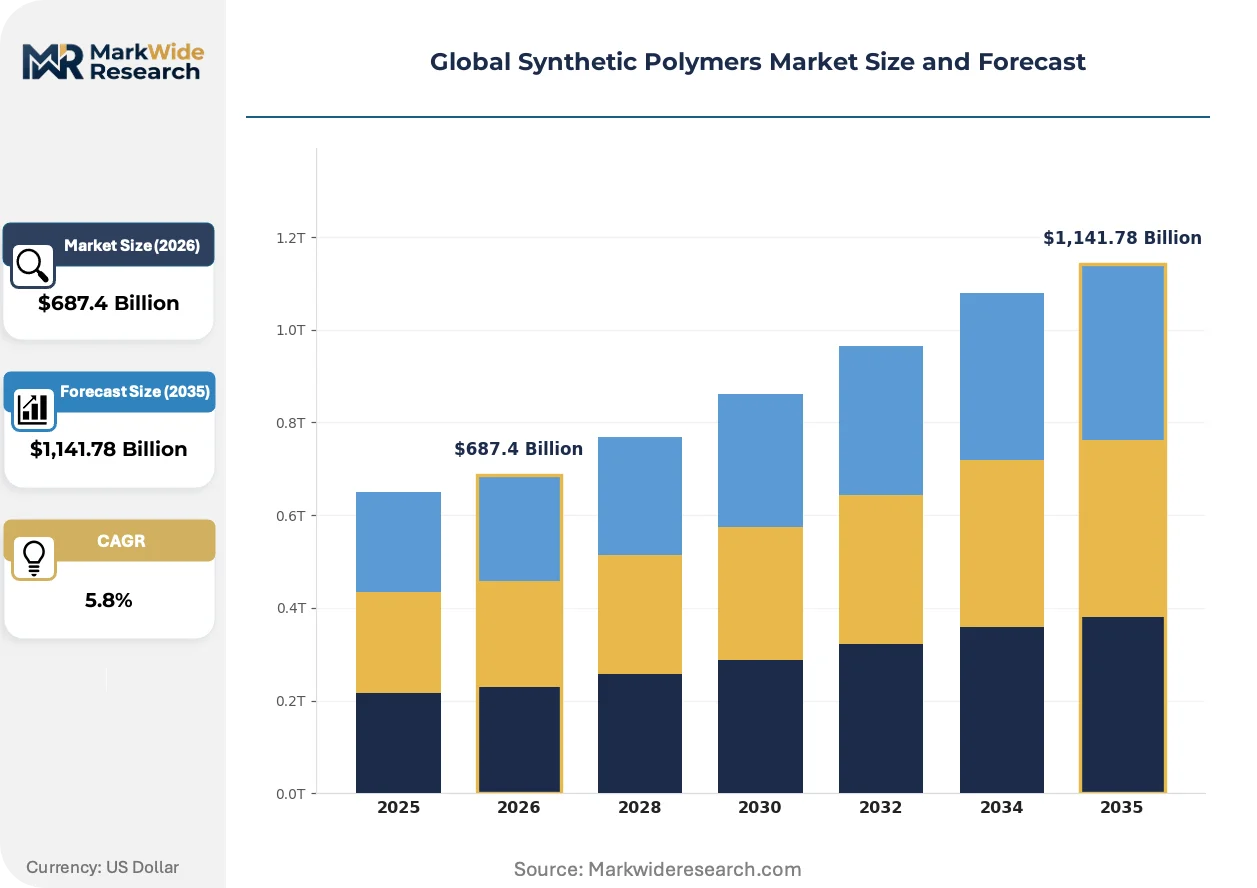
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,141.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Nylon Form: Granules, Sheets, Films, Fibers Application: Automotive, Packaging, Construction, Textiles End Use Industry: Consumer Goods, Electronics, Medical, Energy |
| Companies Covered | BASF SE, Dow Inc., ExxonMobil Chemical Company, DuPont de Nemours, Inc., LyondellBasell Industries N.V., SABIC, Evonik Industries AG, Celanese Corporation, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Polymers Market Strategic Shifts
Digital twin platforms are virtualizing polymer process optimization. Regulatory pressure on carbon intensity is forcing feedstock diversification. Procurement behavior is fragmenting as sustainability credentials displace price-only sourcing matrices.
Advanced process control systems are virtualizing extrusion parameter optimization. Medical tubing manufacturers are deploying real-time rheology monitoring to reduce scrap rates. This capability is compressing batch-to-batch variation and enabling just-in-time compounding contracts with device OEMs.
EU Green Deal plastics circularity mandates are accelerating mechanical recycling infrastructure investments. Packaging converters must certify 30% recyclate content thresholds by 2030. Food-contact applications are driving super-clean flake technology development in Germany and the Netherlands.
Brand owner sustainability scorecards are fragmenting polymer procurement patterns. Consumer goods companies are unbundling price negotiations from carbon accounting. This shift is most visible in European flexible packaging supply chains where mass balance certifications command sourcing premiums.
Global Synthetic Polymers Market Segmentation
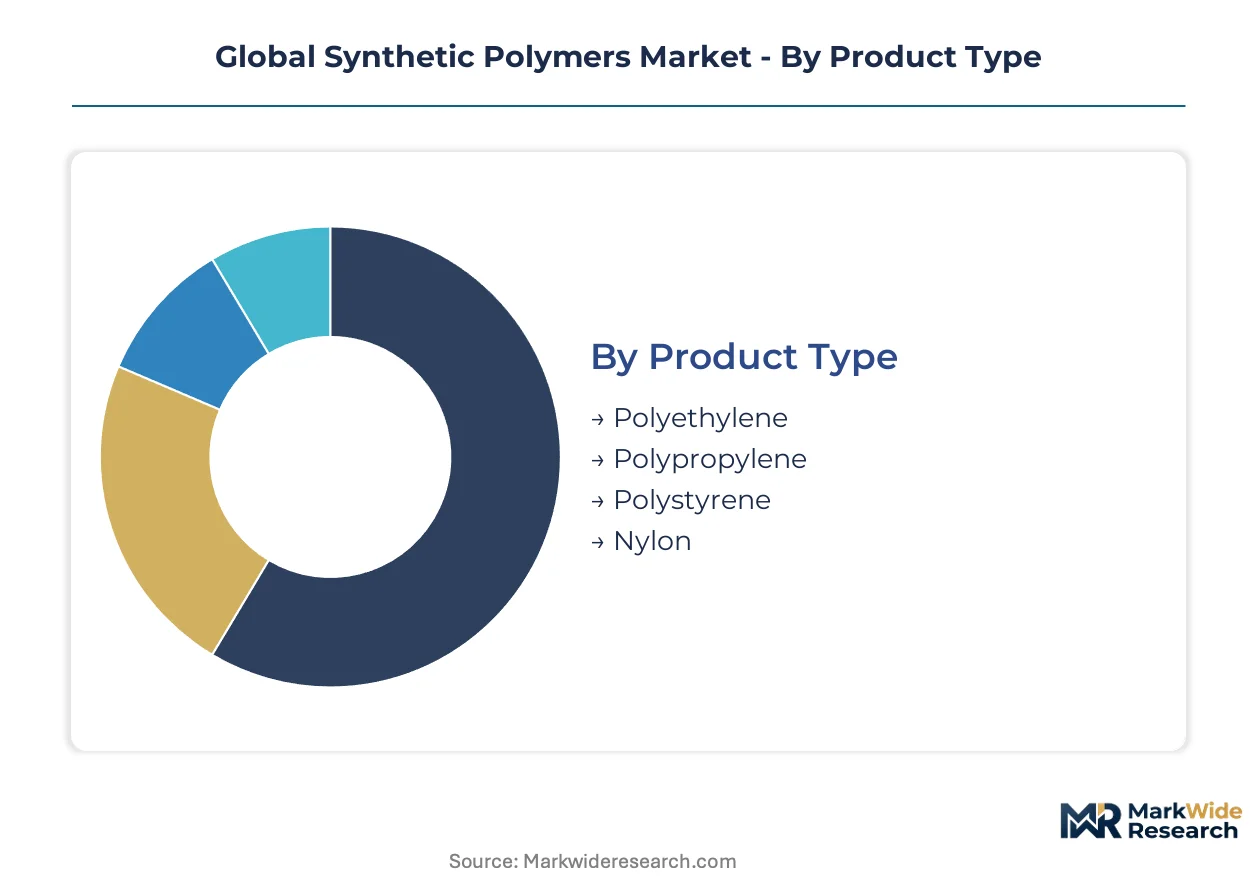
Synthetic polymer procurement patterns fragment sharply across product grades, physical forms, and end-use specifications. Each segmentation dimension carries distinct technical service requirements, margin structures, and regulatory compliance burdens that reshape supplier-customer relationships.
Product Type:
After-sales technical support intensity varies dramatically by resin chemistry, with engineering polymers demanding formulation troubleshooting and commodity grades requiring logistics coordination.
- Polyethylene:This thermoplastic dominates volume production through addition polymerization of ethylene monomer, achieving densities from 0.91 to 0.97 g/cm³ across LDPE, LLDPE, and HDPE variants. Blown film extruders in India and Vietnam are expanding capacity to serve e-commerce fulfillment networks, though naphtha feedstock volatility in European crackers compresses margins against Middle Eastern ethane-based competition.
- Polypropylene:Propylene-based homopolymers and copolymers offer superior heat resistance and rigidity versus polyethylene, with isotactic grades achieving melting points near 160°C. Automotive under-hood applications in Germany and Japan are displacing metal with glass-filled PP compounds as OEMs pursue lightweighting targets under EU CO₂ fleet regulations.
- Polystyrene:Aromatic vinyl polymer produced through bulk or suspension polymerization, valued for transparency and ease of thermoforming. Food service disposables face biopolymer substitution pressure from PLA and PHA grades with compostability certifications.
- Nylon:Polyamide engineering resin synthesized through condensation polymerization, delivering continuous-use temperatures above 150°C. Industrial fiber producers in China face MEE enforcement of GB standards for VOC emissions during extrusion.
Polyethylene holds the largest share; momentum sits with nylon as automotive thermal management specifications tighten.
Form:
Physical configuration determines downstream conversion economics, with films and fibers commanding premium positioning over bulk granules due to specification intensity and quality assurance requirements.
- Granules:Standard pellet form for injection molding and extrusion, with melt flow index specifications varying by application. Compounding operations in Gujarat chemical clusters are expanding engineered polymer capacity under India's PLI scheme for specialty chemicals.
- Sheets:Flat extruded or calendered products for thermoforming and fabrication. Construction membrane specifications in Germany require UV stabilization packages and weldability certification.
- Films:Blown or cast configurations with thickness control critical for barrier properties. EU Green Deal mandates force packaging converters to certify 30% recyclate content thresholds, driving super-clean flake technology investment.
- Fibers:Spun or drawn filaments for textiles and industrial applications. Medical textile manufacturers deploy real-time rheology monitoring to reduce scrap rates and enable just-in-time compounding contracts.
Granules generate the highest volume; films capture the steepest expansion trajectory as flexible packaging specifications proliferate.
Application:
End-use sector selection dictates regulatory exposure, with automotive and medical applications imposing the most stringent certification timelines and traceability requirements.
- Automotive:Interior, exterior, and under-hood components leveraging polymer lightweighting versus metal. REACH registration requirements raise compliance barriers for non-EU additive suppliers serving European OEMs.
- Packaging:Primary and secondary containment across flexible and rigid formats. Mechanical recycling yield losses from sortation contamination limit food-contact recyclate availability, requiring 18-24 month EFSA safety evaluations for novel grades.
- Construction:Membranes, insulation, and piping systems demanding weathering resistance. EPA Clean Air Act Title V permitting shapes locational decisions for US-based extrusion investments.
- Textiles:Apparel, industrial, and technical fiber applications. Polymer process engineering talent scarcity constrains Southeast Asian capacity expansion as vocational training pipelines lag demand.
Packaging commands the dominant volume position; automotive applications are gaining share fastest as electrification redesigns thermal management architectures.
End Use Industry:
Customer industry selection determines sustainability credential requirements, with consumer goods and electronics OEMs unbundling carbon accounting from price negotiations.
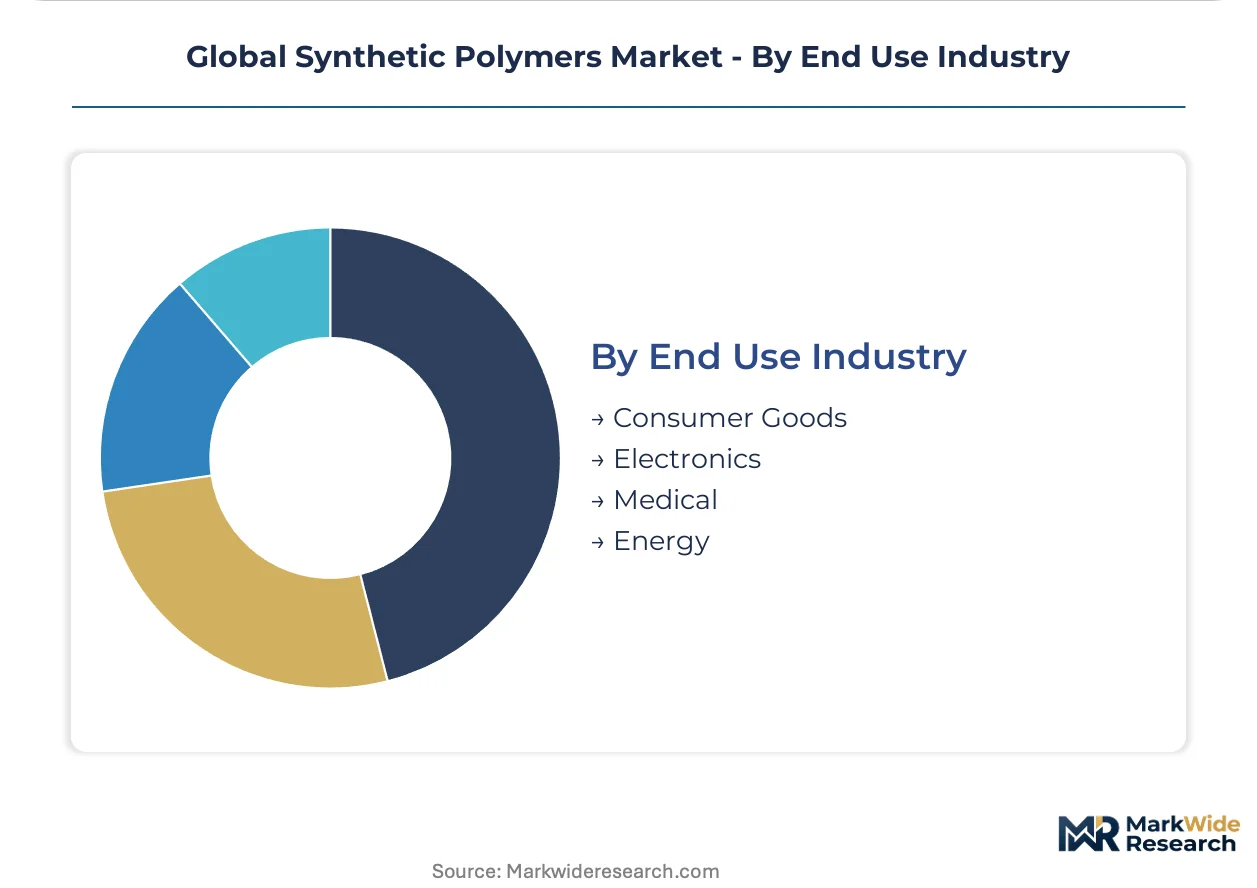
- Consumer Goods:Durable and disposable products for household and personal care. Brand owner sustainability scorecards fragment procurement patterns as mass balance certifications command sourcing premiums.
- Electronics:Housings, connectors, and substrate materials with flame retardancy specifications. RoHS compliance and REACH substance restrictions shape material selection for EU market access.
- Medical:Device components, packaging, and delivery systems requiring biocompatibility validation. FDA and EMA regulatory pathways impose extended qualification timelines for novel polymer grades.
- Energy:Cable insulation, pipeline coatings, and renewable component materials. FERC and national utility regulators specify long-term degradation resistance for infrastructure applications.
Consumer goods anchors volume demand; medical applications exhibit the most rapid expansion as device OEMs reshore supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports polyethylene and polypropylene resins to European packaging converters facing EU Green Deal recyclate mandates. German chemical distributors re-export engineered polymers to Central European automotive tier suppliers. Singapore serves as the regional blending hub for Southeast Asian film extruders.
United States
Gulf Coast ethane crackers supply high-density polyethylene to domestic flexible packaging converters. EPA Clean Air Act Title V permitting shapes locational decisions for new compounding investments. Houston-area chemical complexes are expanding specialty polymer capacity for medical device OEMs reshoring supply chains.
Germany
Automotive OEMs in Baden-Württemberg specify high-heat nylon compounds for under-hood thermal management. REACH registration requirements raise compliance barriers for non-EU additive suppliers. Ludwigshafen chemical clusters sustain integrated production economics through Verbund site networks.
China
Blown film extruders in Zhejiang province scale capacity to serve domestic e-commerce fulfillment networks. MEE enforces GB standards for volatile organic compound emissions from plastic processing. Yangtze River Delta chemical parks concentrate polypropylene compounding for automotive lightweighting programs.
India
Packaging converters in Maharashtra expand polyethylene film lines for quick-commerce delivery networks. PLI scheme for specialty chemicals draws greenfield engineered polymer investments into Gujarat chemical clusters. Mumbai-Pune industrial corridor concentrates engineering plastics compounding capacity.
Saudi Arabia
Jubail Industrial City exports ethane-based polyethylene to Asian markets at 40-50% cost advantages versus European naphtha crackers. SABIC expands specialty polymer grades for automotive lightweighting applications. Yanbu petrochemical complexes integrate pyrolysis platforms for mixed plastic waste feedstock.
Global Synthetic Polymers Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans integrated petrochemical majors, regional compounders, and technology licensors. Three archetypes dominate: feedstock-advantaged Middle Eastern producers, integrated European chemical conglomerates, and specialty engineering resin formulators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players defend margin positions against mechanical recycling substitution.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify divergent strategic positions. BASF anchors European production economics through its Verbund site network spanning Ludwigshafen and Antwerp. Dow occupies a technology-licensing position through proprietary solution-processed polyethylene platforms. SABIC represents the feedstock-advantaged archetype with Jubail-based ethane cracking economics.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| ExxonMobil Chemical Company |
| DuPont de Nemours, Inc. |
| LyondellBasell Industries N.V. |
| SABIC |
| Evonik Industries AG |
| Celanese Corporation |
| Arkema Group |
| Others |
Value Chain & Pricing Dynamics
Middle Eastern ethane-based production clusters in Saudi Arabia and Qatar anchor global polyethylene cost curves, concentrating margin pools downstream with European compounders serving automotive and medical specifications. Naphtha-linked crackers in Germany and Belgium face persistent feedstock disadvantages that compress commodity resin returns while amplifying premiums for certified circular grades.
Pricing Analysis
Solution-processed polyethylene technologies command sustained premiums over conventional Ziegler-Natta grades, while mechanical recyclate certifications create a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EFSA food-contact clearance status and mass balance chain-of-custody documentation. Cost compression in commodity LDPE intensifies as Middle Eastern exports displace European naphtha-based volumes. Small-scale packaging converters exhibit highest price sensitivity; medical device OEMs prioritize certification reliability over unit economics.
Supply Chain Analysis
Contract toll compounding capacity concentrates in Germany, India, and China, with specialized operations clustered around Ludwigshafen, Gujarat chemical parks, and Yangtze River Delta zones. Feedstock sourcing draws from Jubail ethane crackers, North American shale gas liquids, and European naphtha import terminals. Single-source vulnerability runs through pyrolysis oil supply for chemical recycling feedstock integration. Distribution runs through regional distributors with technical service capabilities, though direct-to-converter digital platforms are fragmenting traditional stocking relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal recyclate mandates force packaging converters to requalify supply chains, accelerating penetration of certified circular grades beyond niche premium positioning.
For Market Incumbents: Insulate specialty polymer margin pools by accelerating backward integration into pyrolysis feedstock supply and securing long-term offtake agreements with automotive OEMs reshoring under-hood component production. Mechanical recycling yield losses threaten virgin resin displacement timelines; EFSA certification investments for novel recyclate grades represent the critical defensive lever.
For New Entrants and Emerging Players: Southeast Asian film extrusion markets present underpenetration for super-clean flake compounding operations serving quick-commerce delivery networks. India's PLI scheme for specialty chemicals offers tariff-advantaged production positioning for engineered nylon grades. A technical service-led go-to-market approach targeting mid-size automotive tier suppliers bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across chemical recycling technology platforms as pyrolysis unit economics approach scale thresholds. Long-term viability favors compounders with dual-feedstock flexibility between virgin and recyclate inputs. Acquisition targets should demonstrate EFSA pre-submission progress for food-contact grades. The signal to watch is brand owner sustainability scorecard enforcement velocity exceeding regulatory clearance timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Feedstock | Secures mixed plastic waste supply for chemical recycling integration with steam cracker operations. |
| EFSA Food-Contact Certification Investment | Enables premium positioning in European flexible packaging supply chains facing Green Deal mandates. |
| Direct-to-Converter Digital Platform Launch | Bypasses traditional distributor markups for small and mid-size blown film extruders. |
| Joint Venture in Gujarat Chemical Clusters | Captures PLI scheme incentives for engineered polymer compounding capacity serving automotive OEMs. |
| Long-term Supply Agreement with Medical Device OEMs | Locks in qualification timelines for biocompatible grades as reshoring accelerates. |
Study Parameters
Initial hypotheses were tested against primary input from polymer plant managers, procurement leads at packaging converters, distribution channel partners, and technical R&D directors at compounders, and refined through secondary validation against customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA Clean Air Act permitting records. Bottom-up volume builds from extrusion line capacity and utilization rates triangulated against top-down macroeconomic elasticity models.
Demand-supply-balance dynamics across the analysis window incorporate grade-tier segmentation by density and thermal performance, end-use industry clustering by regulatory exposure, and regional production hub differentiation by feedstock cost structure. CAGRs derive from elasticity-adjusted volume projections and value-per-ton trends by specification intensity. Forecast inputs include automotive lightweighting content-per-vehicle trajectories and e-commerce packaging weight-per-shipment evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Middle Eastern producers or accelerated biopolymer substitution would shift outcomes. Quarterly review of EFSA certification clearance velocities, brand owner sustainability scorecard enforcement, and pyrolysis oil spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Bakelite Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
Resorbable Polymers Market