
 Bioceramics and Hydroxyapatite Market | 2026-2036
Bioceramics and Hydroxyapatite Market Size, Share, and Industry Trends Forecast 2026-2036
Bioceramics and Hydroxyapatite Market Outlook
Academic research laboratories are unwinding procurement share as hospital systems consolidate vendor relationships for bone regeneration materials. Fluidinova leverages nanocrystalline hydroxyapatite production to anchor European supply chains for dental applications. Kyocera dominates technical ceramic manufacturing for orthopedic load-bearing components. Zimmer Biomet sustains vertical control over implant coating operations through captive hydroxyapatite sourcing.
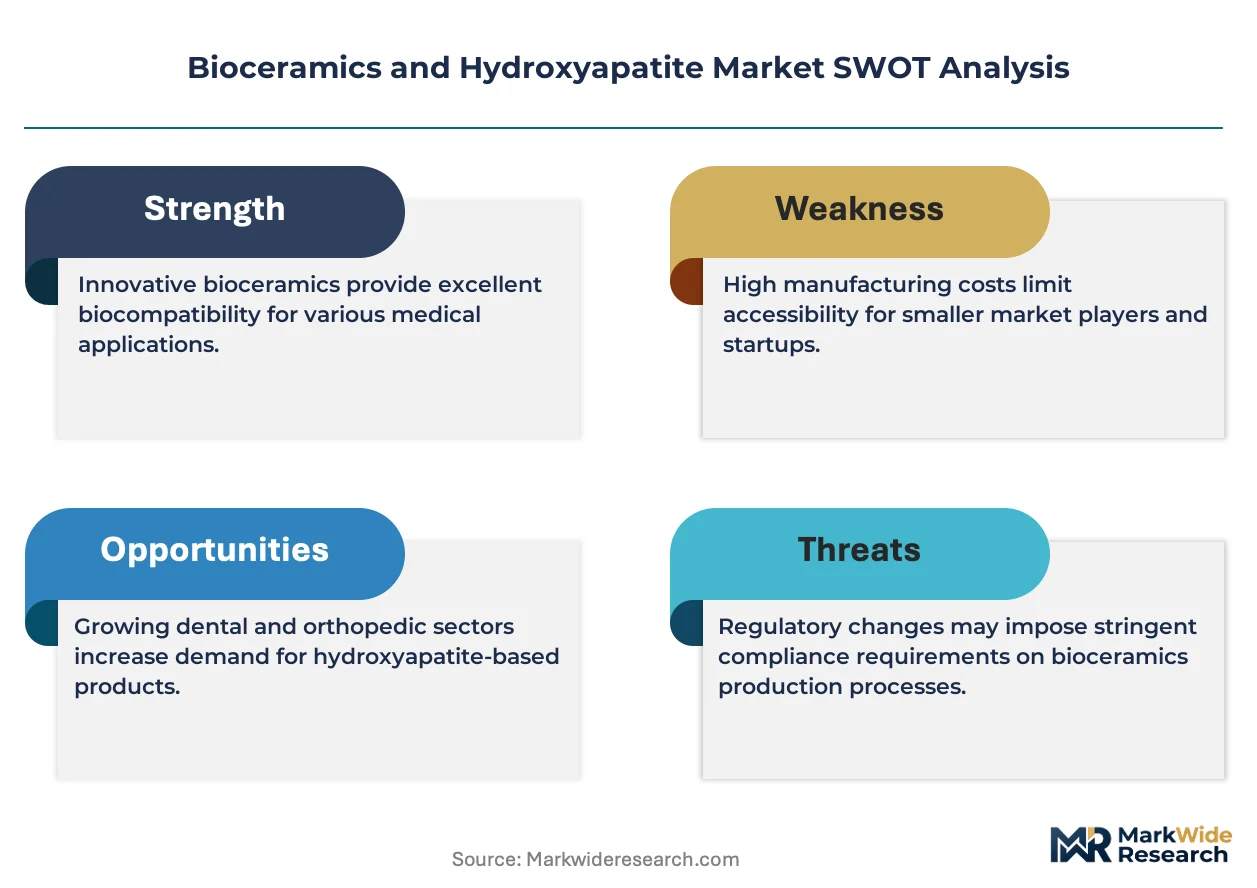
Bioceramics and hydroxyapatite comprise calcium phosphate-based synthetic or mineral-derived materials, typically formulated with Ca10(PO4)6(OH)2 stoichiometry and sintered at 900–1200°C, engineered to bond with living bone tissue and serve as scaffolds for osseointegration. Hydroxyapatite products lead revenue generation due to established reimbursement codes for spinal fusion and dental implant procedures, while bioglass segments capture faster growth from bioactive ion release properties in craniofacial reconstruction. Calcium phosphate cement formulations concentrate margin pools in orthopedic surgery through intraoperative moldability and reduced revision rates.
The FDA 510(k) framework and EU MDR classification systems shape bone substitute approval timelines and clinical evidence requirements for market access across North America and Europe. Japan's PMDA enforces JIS standards for ceramic implant biocompatibility that constrain import eligibility for non-domestic manufacturers. Stakeholders must monitor evolving FDA guidance on 3D-printed bioceramic scaffolds and corresponding reimbursement decisions by CMS and private payers.
Market Dynamics
Hospital procurement consolidation is concentrating vendor relationships for bone regeneration materials, compressing the addressable supplier base while elevating technical service and inventory management expectations from retained vendors.
Growth Catalysts
- FDA 510(k) Pathway:The streamlined clearance framework for bone graft substitutes accelerates product commercialization timelines, reducing regulatory friction for synthetic hydroxyapatite coatings on orthopedic implants.
- Japan's Demographics:Aging populations and universal healthcare coverage sustain high-volume orthopedic and dental procedures, anchoring regional demand concentration for bioceramic implants.
- 3D-Printed Scaffold Fabrication:Additive manufacturing of patient-specific bioceramic geometries is expanding addressable indications in craniofacial reconstruction and complex spinal fusion.
Market Restraints
- Raw Material Purity Constraints:Pharmaceutical-grade calcium phosphate precursors face supply concentration among specialty chemical producers, exposing margin pressure from input cost volatility.
- Sintering Energy Intensity:Kiln operations at 900–1200°C generate substantial utility costs and carbon exposure, particularly for European manufacturers under EU Green Deal emissions frameworks.
- Bioglass Substitution:Bioactive glass formulations with superior ion release kinetics are capturing share in craniofacial applications, constraining hydroxyapatite expansion in high-growth segments.
Strategic Opportunities
- Veterinary Orthopedics:Companion animal surgical volumes are creating untapped demand for bioceramic bone void fillers, with regulatory pathways less burdensome than human medical devices.
- Point-of-Care Cement Mixing:Intraoperative moldability of calcium phosphate cements enables ambulatory surgical center penetration, bypassing hospital centralized procurement.
- EU MDR Transition:Stricter clinical evidence requirements for legacy products are accelerating market access for manufacturers with robust biocompatibility dossiers under the new classification system.
Industry Challenges
- Bioceramics Processing Expertise:The intersection of materials science and medical device manufacturing requires specialized talent pools that remain shallow outside established ceramic clusters.
- Reimbursement Code Alignment:CMS and private payer coverage decisions for 3D-printed scaffolds lag device approvals, compressing commercialization timelines for novel geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioceramics and Hydroxyapatite Market |
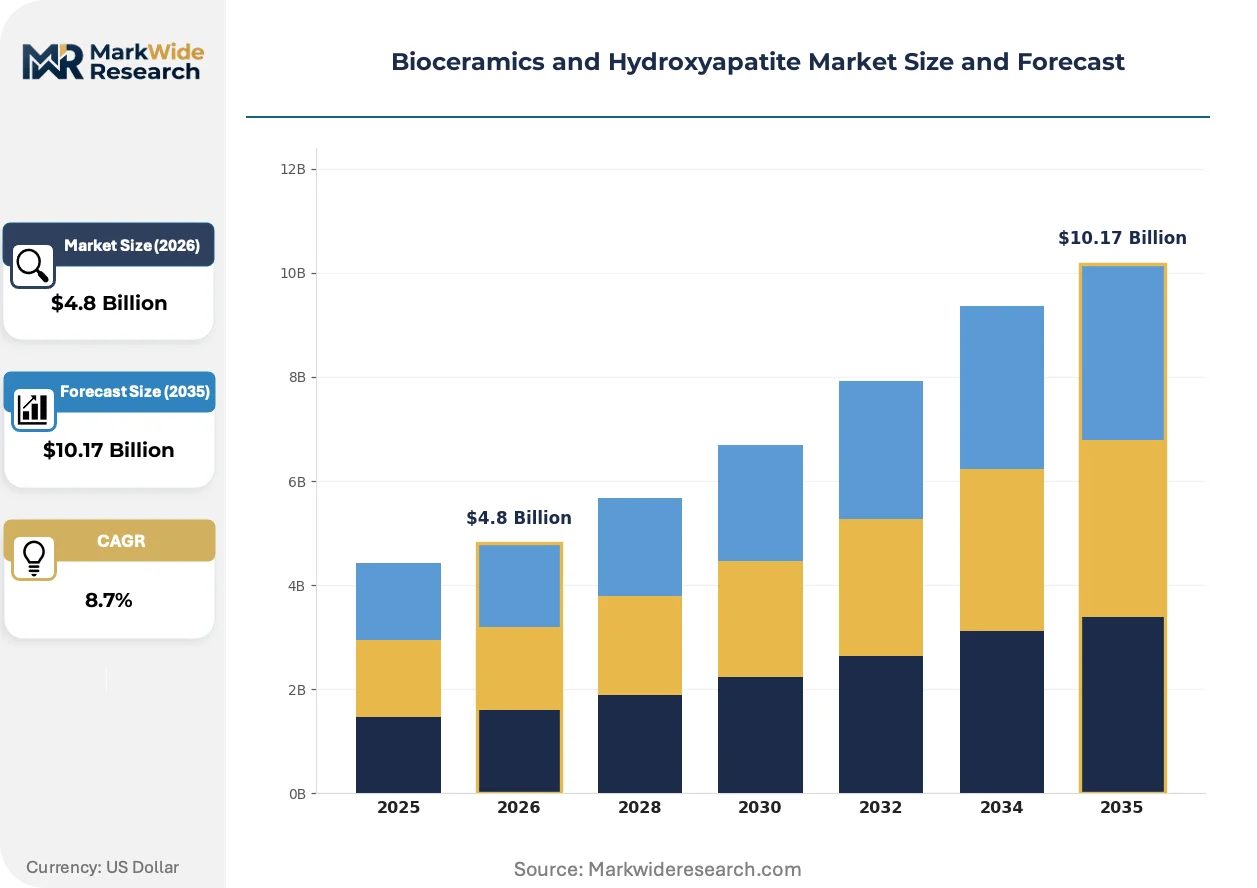
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxyapatite, Tricalcium Phosphate, Bioglass, Calcium Phosphate Cement Application: Dental Implants, Bone Regeneration, Orthopedic Surgery, Tissue Engineering End User: Hospitals, Dental Clinics, Research Laboratories, Rehabilitation Centers Form: Powder, Granules, Coating, Injectable |
| Companies Covered | Daiichi Kigenso Kagaku Kogyo, Fluidinova, Shandong Sinocera Functional Materials, Berkeley Advanced Biomaterials, Zimmer Biomet, CAM Bioceramics, Kyocera, SigmaGraft Biomaterials, Tosoh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioceramics and Hydroxyapatite Market Strategic Shifts
Additive manufacturing protocols are actively reshaping production economics for patient-matched implants, while regulatory frameworks evolve to accommodate novel biocompatibility evidence standards.
Nanocrystalline hydroxyapatite synthesis is supplanting conventional sintered microcrystalline formulations in dental implant surface coatings. Periodontal specialists and oral surgeons are adopting these nanostructured layers to accelerate osseointegration timelines. The shift is compressing competitive differentiation around surface roughness parameters and ion dissolution profiles.
The EU MDR classification system is elevating clinical evidence requirements for bone substitute products previously cleared under less stringent directives. Manufacturers must now generate prospective data or substantial equivalence arguments for legacy portfolio maintenance. Spine and dental segments are responding by consolidating supplier relationships toward vendors with established Notified Body partnerships.
Direct-to-hospital consignment models are displacing distributor-mediated inventory for high-volume orthopedic procedures. Large health systems in Germany and the United States are negotiating vendor-managed inventory agreements that transfer logistics burden to manufacturers. This reconfiguration is most visible in metropolitan hospital clusters where procedure volumes justify dedicated supply chain infrastructure.
Bioceramics and Hydroxyapatite Market Segmentation
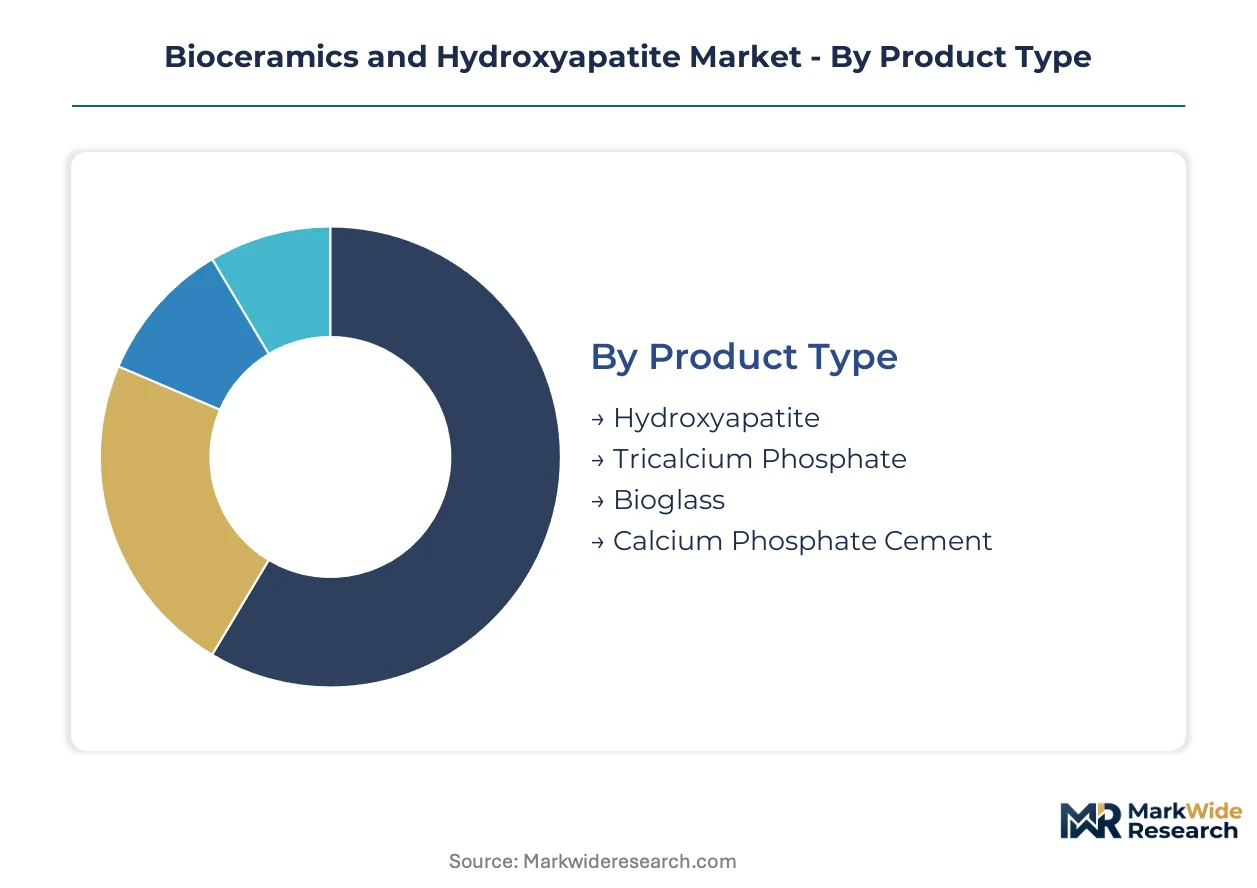
Segmentation in bioceramics reveals divergent supply chain configurations: hydroxyapatite coatings flow through consolidated hospital procurement channels while calcium phosphate cements penetrate ambulatory settings through direct distribution. Understanding these structural patterns enables targeted commercialization strategies across regulatory and reimbursement environments.
Product Type:
Domestic production dominates hydroxyapatite and tricalcium phosphate manufacturing in Japan and the United States, whereas bioglass and calcium phosphate cement formulations rely more heavily on European export supply chains.
- Hydroxyapatite:Synthetic Ca10(PO4)6(OH)2 formulations sintered at 900–1200°C constitute the primary revenue pool. Japanese dental clinics and US hospital systems anchor demand through established reimbursement codes for spinal fusion and implant surface treatments.
- Tricalcium Phosphate:β-TCP and α-TCP variants offer faster resorption kinetics than hydroxyapatite. German orthopedic centers and French maxillofacial units drive adoption for load-bearing applications requiring controlled degradation timelines.
- Bioglass:Silicate-based bioactive glasses with ion release properties command premium positioning in craniofacial reconstruction.
- Calcium Phosphate Cement:Intraoperative moldability enables point-of-care mixing protocols in ambulatory surgical centers.
Hydroxyapatite holds the largest share; momentum sits with calcium phosphate cement as ambulatory penetration accelerates.
Application:
Volume concentration varies sharply by procedure setting: dental implant work concentrates in private clinic networks while bone regeneration flows through hospital-based orthopedic departments.
- Dental Implants:Nanocrystalline hydroxyapatite surface coatings now dominate implantology practice. Japanese periodontal specialists and Spanish oral surgeons specify these layers to compress osseointegration timelines from twelve weeks to six.
- Bone Regeneration:Spinal fusion and maxillofacial defect repair constitute the procedural core. US hospital systems negotiate vendor-managed inventory agreements that transfer logistics burden to manufacturers for high-volume fusion cases.
- Orthopedic Surgery:Load-bearing applications demand technical ceramics with compressive strength exceeding cortical bone.
- Tissue Engineering:3D-printed scaffold fabrication expands addressable indications in complex craniofacial reconstruction.
Bone regeneration commands the revenue base; tissue engineering expands most quickly as additive manufacturing protocols mature.
End User:
Procurement authority is shifting: hospital consolidation compresses vendor counts while dental clinics retain decentralized purchasing flexibility.
- Hospitals:Integrated delivery networks in Germany and the United States now mandate single-source contracts for bone graft substitutes. Technical service capabilities and consignment inventory terms determine vendor retention.
- Dental Clinics:Private practice networks in Japan and Italy drive nanocrystalline coating adoption through direct manufacturer relationships. These clinics bypass distributor markups for implant surface treatments.
- Research Laboratories:Academic procurement share contracts as funding priorities shift toward translational programs.
- Rehabilitation Centers:Post-surgical recovery protocols create secondary demand for bone void filler monitoring and follow-on procedures.
Hospitals retain the dominant procurement volume; dental clinics gain share fastest through coating specialization.
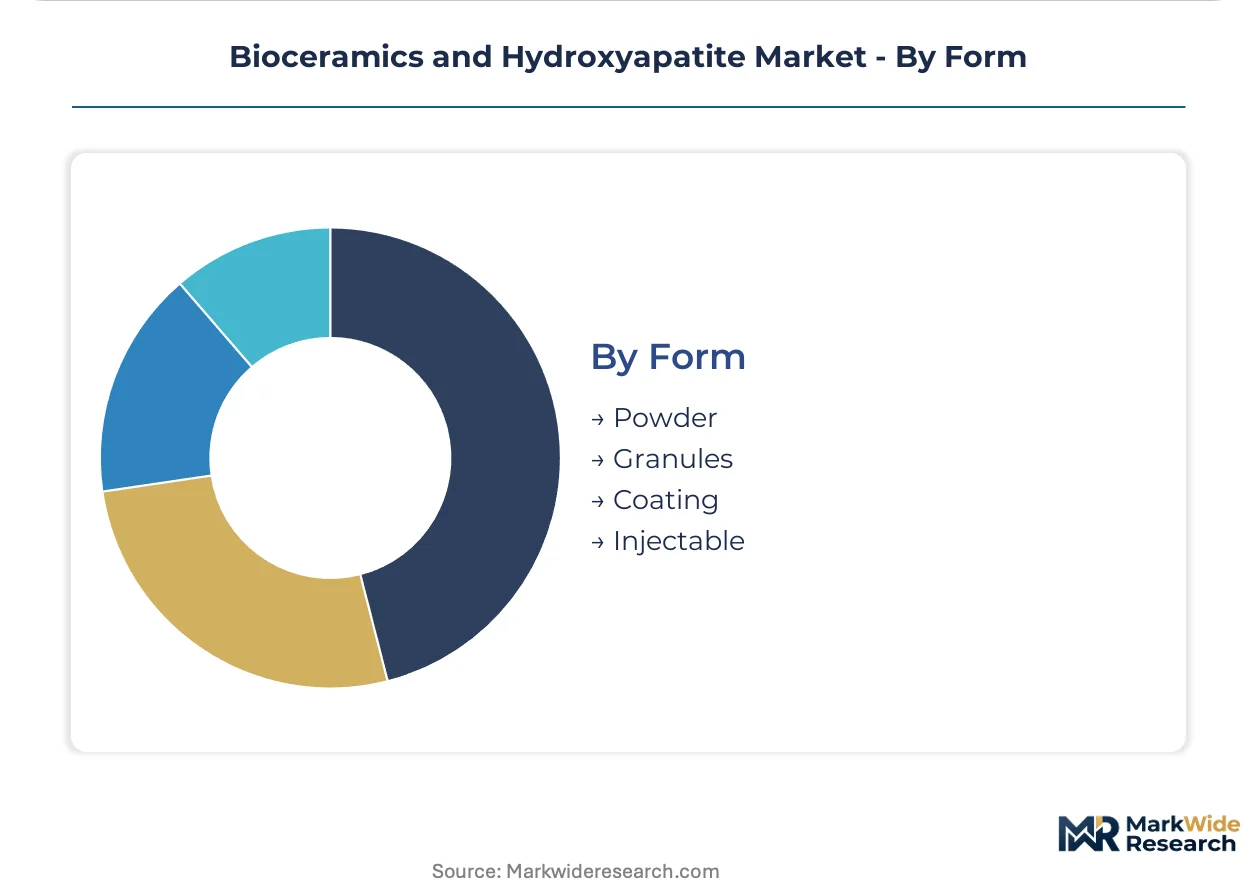
Form:
Processing intensity and logistics requirements vary dramatically: powders and granules ship through conventional medical distribution while coatings demand just-in-time delivery to implant manufacturers.
- Powder:Pharmaceutical-grade calcium phosphate precursors supply downstream formulation. Specialty chemical producers in Belgium and China concentrate production, exposing margin pressure from input cost volatility.
- Granules:Sintered particulate forms suit packed defect filling in orthopedic and dental applications. Japanese manufacturers enforce JIS biocompatibility standards that constrain import eligibility.
- Coating:Plasma-sprayed and electrochemically deposited layers integrate with titanium implant substrates. Captive production at major orthopedic device manufacturers limits merchant market opportunity.
- Injectable:Paste formulations enable minimally invasive delivery through cannula systems. Ambulatory surgical centers in the United States adopt these for cost-effective outpatient procedures.
Granules dominate current volume; injectable forms climb fastest as outpatient migration continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical producers in Belgium and China concentrate pharmaceutical-grade calcium phosphate precursor supply, exposing European and Asian manufacturers to input cost volatility while Japanese domestic production maintains JIS-standard ceramic implant output.
United States
Hospital procurement consolidation compresses vendor counts for bone graft substitutes while the FDA's 510(k) clearance framework accelerates synthetic hydroxyapatite coating approvals. Integrated delivery networks in metropolitan clusters now mandate single-source contracts with vendor-managed inventory terms.
Japan
Aging demographics and universal healthcare coverage sustain high-volume orthopedic and dental procedures, anchoring regional demand concentration. PMDA enforcement of JIS biocompatibility standards constrains import eligibility for non-domestic ceramic implant manufacturers. Tokyo and Osaka dental clinics drive nanocrystalline hydroxyapatite adoption for accelerated osseointegration.
Germany
Orthopedic centers in Bavaria and North Rhine-Westphalia drive tricalcium phosphate adoption for load-bearing applications requiring controlled degradation timelines. EU MDR classification elevates clinical evidence requirements for legacy bone substitute products. German health systems negotiate direct-to-hospital consignment agreements that transfer logistics burden to manufacturers.
China
Specialty chemical production clusters in Shandong and Jiangsu provinces supply downstream calcium phosphate formulation. NMPA medical device regulations shape bone substitute approval timelines for domestic and imported products. Beijing-Tianjin-Hebei hospital networks expand procurement of synthetic hydroxyapatite for spinal fusion procedures.
Belgium
Pharmaceutical-grade precursor manufacturing concentrates in Flanders chemical corridors, exposing margin pressure from energy-intensive sintering operations under EU Green Deal emissions frameworks. Brussels-based logistics infrastructure supports just-in-time delivery to German and French orthopedic device manufacturers.
Bioceramics and Hydroxyapatite Market Competitive Environment
Concentration sits with diversified orthopedic device manufacturers and specialized ceramic producers. Hospital procurement consolidation favors vendors with captive hydroxyapatite sourcing and established Notified Body partnerships. Three archetypes dominate: integrated implant manufacturers with in-house coating operations, standalone bioceramic material suppliers, and diversified technical ceramics producers. Competitive moves center on backward integration into precursor supply and capacity expansion for nanocrystalline formulations.
Among Japanese diversified manufacturers, Kyocera exemplifies technical ceramic expertise applied to orthopedic load-bearing components. Zimmer Biomet anchors the integrated device manufacturer archetype through captive hydroxyapatite sourcing for implant coating operations. Fluidinova represents the specialized nanomaterial supplier tier, leveraging nanocrystalline production capabilities to serve European dental supply chains.
| Leading Market Players |
|---|
| Daiichi Kigenso Kagaku Kogyo |
| Fluidinova |
| Shandong Sinocera Functional Materials |
| Berkeley Advanced Biomaterials |
| Zimmer Biomet |
| CAM Bioceramics |
| Kyocera |
| SigmaGraft Biomaterials |
| Tosoh |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers gate both supply qualification and price differentiation in bone graft substitutes, compressing merchant market access for non-vertically integrated hydroxyapatite suppliers while elevating premium positioning for vendors with captive coating operations and established reimbursement codes.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across synthetic hydroxyapatite products, separating premium-positioned implant coatings with established reimbursement codes from standard-grade bone void fillers and economy-tier unprocessed precursors. Price differentiation rests on JIS certification status and plasma-spray technical service capabilities rather than raw material purity alone. Cost compression in standard-grade granules is intensifying because hospital procurement consolidation demands vendor-managed inventory terms. Dental clinics exhibit the lowest price sensitivity due to direct manufacturer relationships and procedure-specific reimbursement, while ambulatory surgical centers drive hardest bargains on calcium phosphate cement formulations.
Supply Chain Analysis
Pharmaceutical-grade calcium phosphate precursor production concentrates in Belgian chemical corridors and Shandong province manufacturing clusters, exposing downstream formulators to input cost volatility from energy-intensive sintering operations. Raw material flows draw from apatite mineral deposits, synthetic chemical synthesis, and recycled bone-derived sources. Single-source vulnerability concentrates in nanocrystalline hydroxyapatite synthesis expertise, where Fluidinova and limited European specialists control merchant market supply. Distribution runs through direct-to-hospital consignment agreements for high-volume orthopedic systems, bypassing traditional medical device distributors in metropolitan hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as point-of-care cement mixing and veterinary orthopedics create demand niches outside consolidated hospital procurement channels, rewarding specialized entrants with regulatory agility and technical service depth.
For Market Incumbents: Consolidate backward into pharmaceutical-grade precursor supply to defend margin position against Belgian and Chinese chemical producers. Kyocera and Zimmer Biomet should deepen captive hydroxyapatite sourcing while expanding nanocrystalline capacity for dental coating specifications. Hospital procurement consolidation threatens merchant market access; incumbents must secure vendor-managed inventory contracts with integrated delivery networks before single-source mandates harden.
For New Entrants and Emerging Players: Anchor in veterinary orthopedics and ambulatory surgical center calcium phosphate cement supply, where regulatory pathways remain less burdensome than human implant 510(k) requirements. Japanese dental clinic networks offer penetrable coating demand through direct manufacturer relationships bypassing distributor markups. Target EU MDR transition timing to capture legacy product displacement with robust biocompatibility dossiers and Notified Body partnerships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialized ceramic producers lacking orthopedic device manufacturer partnerships. Long-term viability hinges on backward integration completion and 3D-printed scaffold regulatory clearance across the extended analysis window. Watch FDA guidance evolution on additive manufacturing biocompatibility evidence standards as the critical inflection signal for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive pharmaceutical-grade calcium phosphate sourcing insulates margin from Belgian chemical corridor volatility. |
| Nanocrystalline Capacity Expansion | Dental clinic demand for accelerated osseointegration coatings rewards surface roughness parameter specialization. |
| EU MDR Notified Body Partnership | Legacy product reclassification elevates clinical evidence requirements and consolidates vendor relationships toward prepared manufacturers. |
| 3D-Printed Scaffold Regulatory Submission | FDA guidance evolution on additive manufacturing biocompatibility standards gates patient-specific craniofacial reconstruction market access. |
| Veterinary Orthopedics Market Entry | Companion animal surgical volumes offer regulatory pathway efficiency compared to human medical device 510(k) timelines. |
Study Parameters
The analysis maps hydroxyapatite coatings, calcium phosphate cements, bioglass formulations, and tricalcium phosphate granules, each validated through orthopedic surgeons, dental implant specialists, hospital procurement managers, and biomedical engineers. Primary interviews with GPO contracts managers and regulatory affairs leads at ceramic manufacturers combined with secondary triangulation against FDA 510(k) filings, EU MDR Notified Body databases, PMDA approval records, and hospital procurement contract disclosures. Bottom-up procedure volume modeling and top-down specialty chemical production capacity estimates were reconciled.
Outputs were validated against external benchmarks including CMS reimbursement code utilization data, Japanese universal healthcare procedure statistics, and EU Green Deal emissions framework compliance disclosures across the projection horizon. Segmentation dimensions modeled include product form, application setting, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to demographic aging and additive manufacturing adoption curves, with nanocrystalline surface coating specifications and sintering energy cost trajectories as industry-specific forecast inputs.
Material uncertainties — reimbursement code lag for 3D-printed scaffolds, raw material purity supply disruption, and EU MDR transition timing — sit outside the modeled envelope. Forecasts reflect assumptions about hospital procurement consolidation velocity and veterinary regulatory pathway stability. Practitioners should keep alternative scenarios live as FDA additive manufacturing guidance and CMS coverage decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Pulp Cells Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
North America Chitosan Market
Biomaterials
Chitosan Films Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Global Biomaterials Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Global Polymeric Biomaterials Market