
 US Virtual Tour Market | 2026-2036
US Virtual Tour Market Size, Share, and Industry Trends Forecast 2026-2036
US Virtual Tour Market Insights
Enterprise property marketers is bifurcating from individual real estate agents as the dominant buyer archetype in the US virtual tour landscape. Matterport Inc. leverages proprietary camera hardware and cloud processing to anchor the high-end capture segment for institutional clients. Google competes through Street View infrastructure and Maps integration that extends distribution reach across millions of commercial listings. Zillow dominates residential funnel optimization by embedding interactive tours directly into its search and transaction workflow.
Virtual tours in the US market comprise spatially indexed digital environments rendered through photogrammetry, LiDAR point clouds, or real-time 3D engines with positional accuracy typically within one percent of physical dimensions. These systems serve commercial purposes spanning pre-lease visualization, remote facility management, and immersive training simulations where physical site access proves costly or impractical. 3D Tours and 360-Degree Photography under Service Type capture diverging margin pools, with full spatial data commanding premium pricing against flat panoramic imagery. WebGL technology leads deployment scale by eliminating headset dependencies, though VR Headsets within the Technology segment posts faster growth as headset costs decline and enterprise training budgets expand.
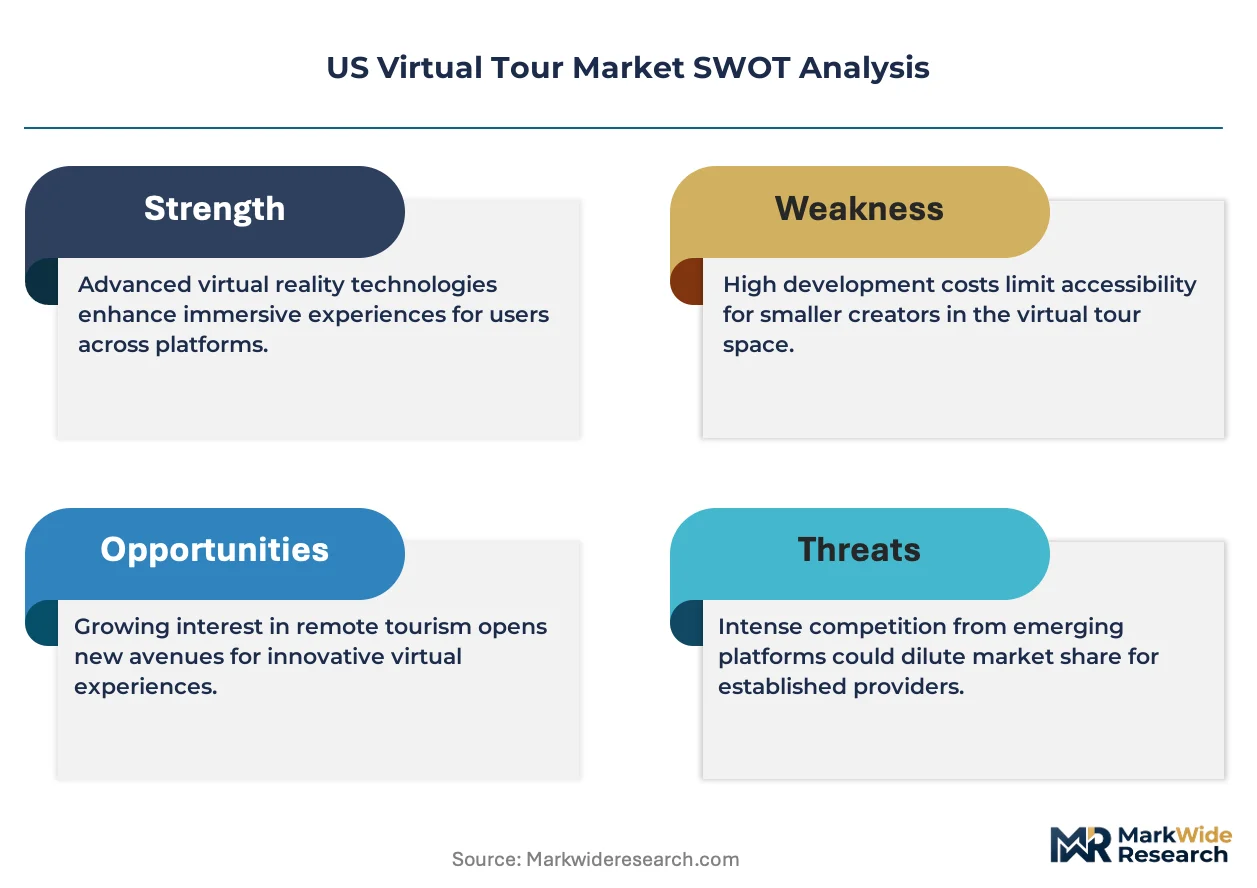
FCC broadband availability maps and infrastructure funding shape market access by determining which properties support bandwidth-intensive streaming delivery. NHTSA guidelines for distracted driving influence mobile app design constraints when automotive retail applications incorporate virtual showroom features. Stakeholders must monitor state-level drone operation permissions under FAA Part 107 waivers, as aerial capture integration becomes critical for large-format commercial and hospitality marketing. The decisive variable ahead lies in whether platform providers build proprietary capture hardware or surrender that layer to commoditized smartphone and camera ecosystems.
Market Dynamics
Enterprise property marketers now demand photogrammetry pipelines that compress capture-to-publish timelines from days to hours, forcing platform providers to rearchitect cloud processing stacks around GPU-accelerated mesh generation.
Growth Catalysts
- FCC Broadband Equity Access and Deployment (BEAD) Program:Infrastructure subsidies extend fiber and fixed wireless to underserved census tracts, expanding addressable property inventory for bandwidth-intensive 3D streaming.
- Commercial Real Estate Pre-Leasing Workflows:Institutional landlords embed spatial data into tenant improvement negotiations, converting virtual tours from marketing accessories to lease execution tools.
- NeRF Neural Radiance Fields:Machine learning reconstruction from sparse image sets reduces on-site capture time by an order of magnitude versus traditional photogrammetry.
Market Restraints
- LiDAR Sensor Cost Concentration:Solid-state LiDAR modules for professional-grade capture remain concentrated among Asian component suppliers, exposing hardware margins to single-source volatility.
- WebGL Rendering Fragmentation:Browser compatibility gaps across Safari, Chrome, and Edge force redundant development tracks, inflating platform engineering overhead.
- Drone Operation Waivers:FAA Part 107 altitude and airspace restrictions limit aerial capture for commercial properties near controlled airspace, constraining marketing asset completeness.
Strategic Opportunities
- Texas Metropolitan Corridors:Austin, Dallas-Fort Worth, and Houston construction volumes exceed national averages, creating concentrated demand for scalable visualization tooling in new development marketing.
- Automotive Retail Showrooms:NHTSA guidelines for mobile app design create compliant frameworks for immersive vehicle configurators, opening dealership channel partnerships.
- Enterprise Training Simulations:VR headset cost curves intersect with OSHA safety training mandates, positioning spatial environments as alternatives to physical hazard exposure.
Industry Challenges
- Photogrammetry Technician Scarcity:Capture quality consistency depends on operators skilled in exposure bracketing and control-point placement, with certification pipelines lagging platform rollout schedules.
- Legacy Property Management System Integration:Yardi, MRI, and RealPage APIs lack standardized spatial data fields, forcing custom middleware development for tour-to-lease workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Virtual Tour Market |
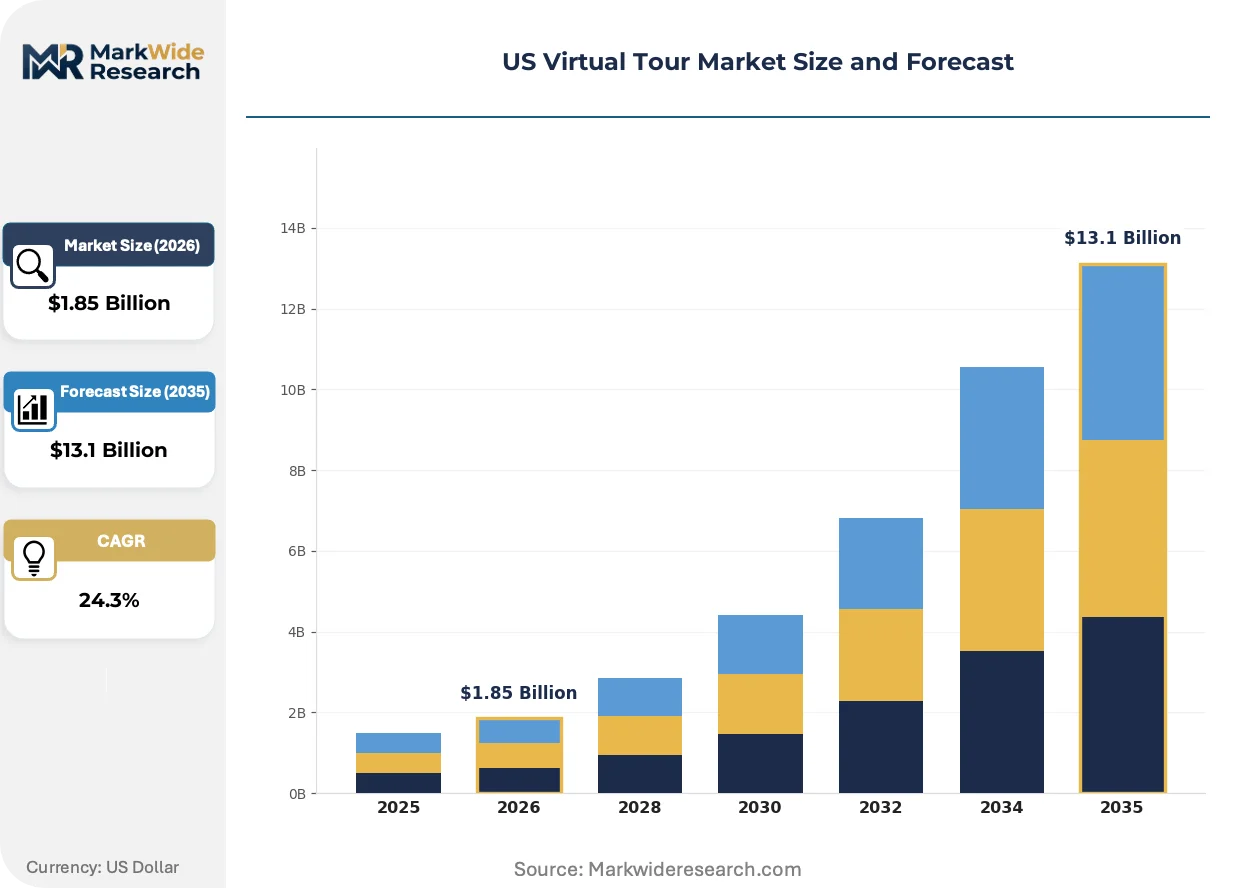
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 3D Tours, 360-Degree Photography, Interactive Experiences, Mobile Apps End User: Real Estate, Museums, Educational Institutions, Hospitality Technology: WebGL, VR Headsets, Augmented Reality, Video Streaming Application: Marketing, Training, Remote Assistance, Event Planning |
| Companies Covered | Matterport Inc., Google, Kuula LLC, Real Tour Vision Inc., Concept3D Inc., Zillow, CloudPano, Roundme Limited, iAriv, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Virtual Tour Market Trends and Innovations
Neural reconstruction methods and edge-rendered streaming architectures are collapsing the cost floor for immersive property visualization, redistributing competitive advantage from hardware ownership to software-defined capture pipelines.
Gaussian Splatting is displacing polygonal mesh workflows as the dominant real-time rendering primitive for browser-based tours. Property marketing agencies in Texas and Florida adopt splatting engines for residential pre-sales, cutting cloud compute costs by eliminating traditional bake-and-stream pipelines. The shift compresses vendor margins for established photogrammetry platforms while enabling smartphone-capture quality previously requiring professional rigs.
FCC infrastructure funding maps now determine platform go-to-market sequencing, with providers prioritizing BEAD-funded counties for sales expansion. The regulatory overlay accelerates rural commercial property digitization where bandwidth constraints previously excluded virtual tour adoption. Title insurers and appraisal workflows in these counties increasingly mandate spatial documentation for remote valuation.
Outcome-based pricing for capture services is replacing per-square-foot rate cards in institutional property management contracts. Landlords in Sun Belt markets negotiate performance-linked fees tied to lease velocity metrics, transferring capture risk to service providers. The model concentrates buyer power among REITs and property conglomerates while squeezing independent photographer networks.
US Virtual Tour Market Segmentation
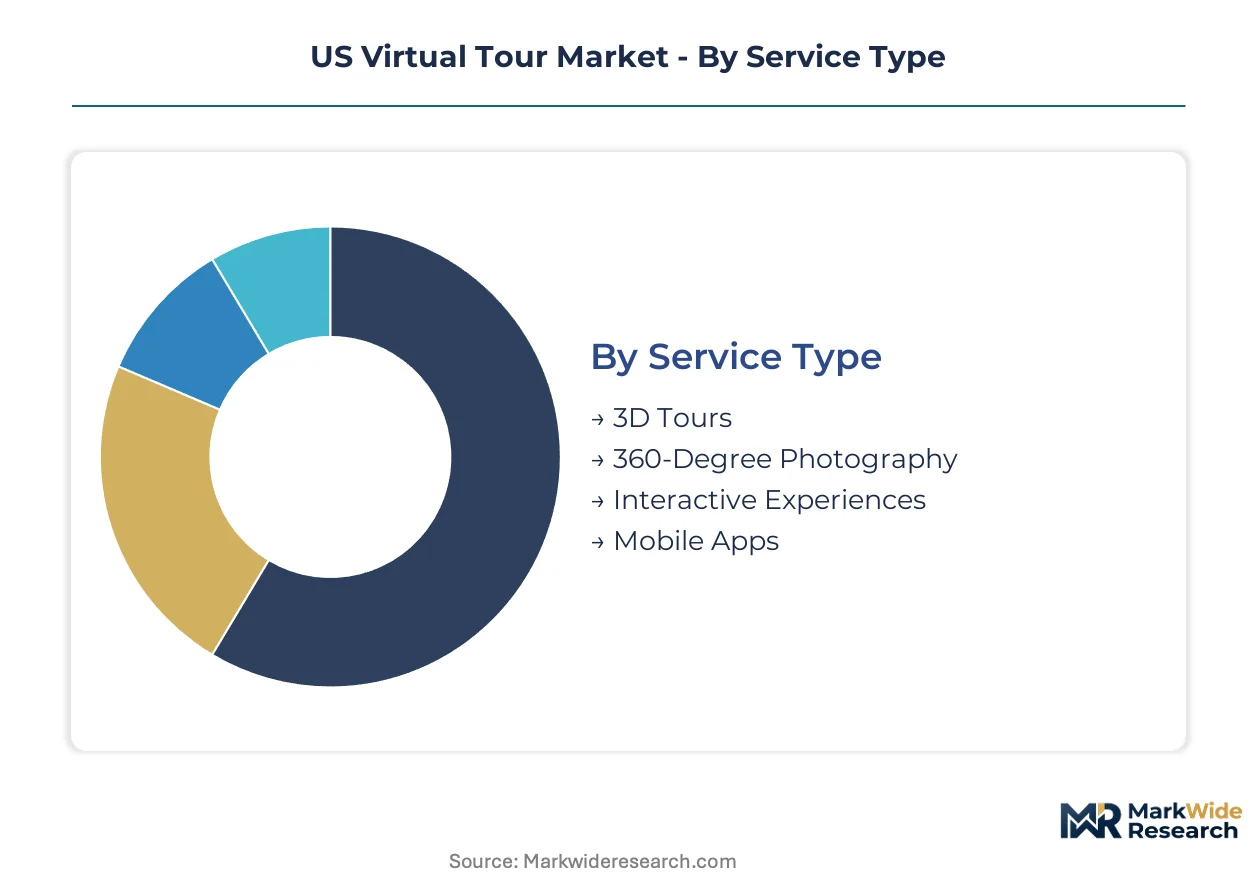
Virtual tour segmentation reveals distinct margin pools and capture complexity across service delivery modes. Technology choices determine whether deployments scale through browser ubiquity or require specialized hardware ecosystems. End-user concentration in Texas metropolitan corridors and commercial real estate brokerages shapes platform provider prioritization.
Service Type:
Domestic demand concentrates in photogrammetry-based offerings serving institutional property marketers, while export-oriented licensing of capture software generates recurring revenue from international markets.
- 3D Tours:Photogrammetry and LiDAR point clouds generate spatially accurate digital twins with positional precision within one percent of physical dimensions. Texas new development marketing and commercial pre-leasing workflows in Dallas-Fort Worth and Houston drive platform subscriptions. FCC BEAD-funded broadband expansion enables bandwidth-intensive streaming delivery to previously underserved census tracts.
- 360-Degree Photography:Flat panoramic imagery captured through single-lens systems offers faster deployment at lower cost points. Residential agents in Sun Belt markets favor this format for rapid listing turnaround, though margin compression intensifies as smartphone capture quality improves.
- Interactive Experiences:Gamified navigation layers and hotspot annotations increase engagement duration for hospitality and museum applications.
- Mobile Apps:Native iOS and Android deployments accommodate NHTSA distracted-driving guidelines for automotive retail showroom integration.
3D Tours commands the established base. The steepest expansion runs through Interactive Experiences.
End User:
Enterprise property marketers now outspend individual practitioners, shifting procurement toward outcome-based contracts tied to lease velocity metrics.
- Real Estate:Commercial brokerages embed spatial data into tenant improvement negotiations, converting tours from marketing accessories to lease execution tools. Institutional landlords in Austin and Houston mandate 3D documentation for pre-leasing of speculative construction.
- Museums:Cultural institutions deploy virtual access programs to extend geographic reach of permanent collections and rotating exhibitions.
- Educational Institutions:University campus tours and remote laboratory access support enrollment and research continuity objectives.
- Hospitality:Hotel and resort marketers use aerial-integrated captures for destination marketing, constrained by FAA Part 107 altitude waivers near controlled airspace.
Real Estate anchors current revenue concentration. Museums demonstrate the most rapid budget allocation increases for immersive programming.
Technology:
Deployment architecture choices determine whether experiences require headset investment or achieve scale through existing browser infrastructure.
- WebGL:Browser-based rendering eliminates hardware dependencies, achieving broadest addressable user base. WebGL leads deployment scale across commercial real estate and hospitality applications where frictionless access outweighs immersion depth. Safari, Chrome, and Edge compatibility gaps force redundant development tracks, inflating platform engineering overhead.
- VR Headsets:Head-mounted displays deliver full positional tracking and stereoscopic depth for enterprise training simulations. OSHA safety training mandates and declining hardware costs position this segment for accelerated adoption in manufacturing and hazardous environment instruction.
- Augmented Reality:Spatial overlays blend digital content with physical environments for furniture placement and renovation visualization.
- Video Streaming:Live-guided walkthroughs support remote assistance and personalized property showings.
WebGL maintains volume leadership. VR Headsets gains share fastest as enterprise training budgets expand.
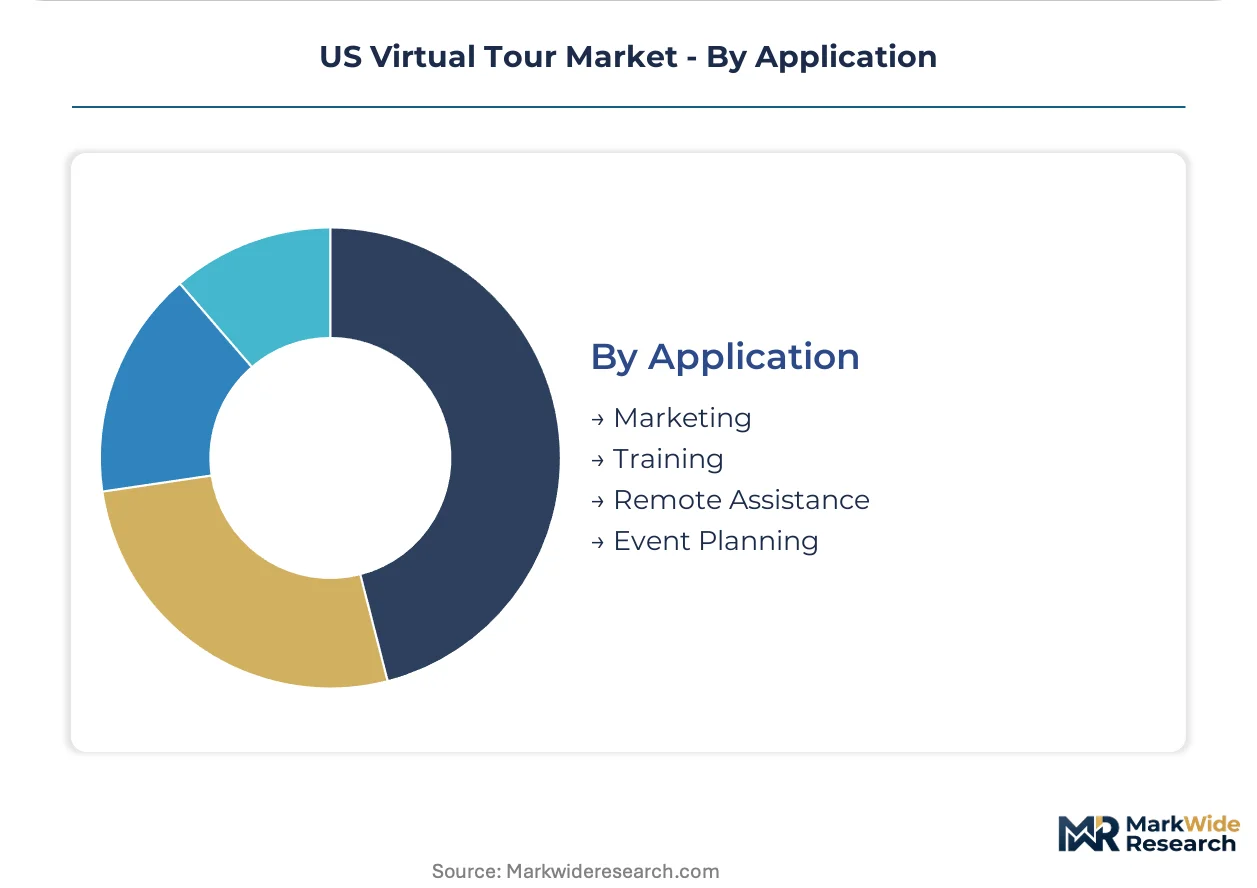
Application:
Use case maturity varies from established marketing workflows to emerging operational integration.
- Marketing:Property visualization for pre-lease and pre-sale conversion dominates current spend. Marketing applications in Texas construction corridors exceed national adoption rates, with developers requiring scalable tooling for multi-phase project launches.
- Training:Immersive hazard exposure simulation reduces physical site visits for OSHA compliance. Training budgets expand as VR headset cost curves intersect with enterprise safety mandates.
- Remote Assistance:Real-time guided navigation supports facility management and maintenance troubleshooting.
- Event Planning:Venue visualization for corporate and social function coordination.
Marketing captures the majority of current platform revenue. Training exhibits the strongest forward momentum from regulatory compliance drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US virtual tour platform providers export capture hardware and cloud processing services to Canadian and Mexican property markets, with Texas-based vendors dominating cross-border delivery into northern Mexico industrial corridors.
Texas
Austin, Dallas-Fort Worth, and Houston construction volumes exceed national averages, creating concentrated demand for scalable visualization tooling in new development marketing. FCC BEAD-funded broadband expansion extends fiber infrastructure to previously bandwidth-constrained census tracts, enabling 3D streaming delivery for rural commercial properties. Dallas-Fort Worth institutional landlords mandate spatial documentation for speculative construction pre-leasing.
California
Silicon Valley technology firms and Los Angeles entertainment studios drive enterprise training simulation deployments for OSHA-compliant hazard exposure reduction. State-level privacy regulations under CCPA influence data handling protocols for cloud-hosted spatial environments. San Francisco commercial brokerages embed photogrammetry into tenant improvement negotiations for Class A office inventory.
Florida
Sun Belt residential markets favor rapid-deployment 360-degree photography for listing turnaround, with Miami hospitality marketers adopting aerial-integrated captures for destination marketing. FAA Part 107 altitude restrictions near controlled airspace constrain marketing asset completeness for coastal resort properties. Orlando theme park operators deploy interactive experiences for pre-visit engagement and accessibility programming.
New York
Manhattan commercial real estate pre-leasing workflows convert virtual tours from marketing accessories to lease execution tools for institutional landlords. State building code documentation requirements influence spatial data retention standards for property management compliance. Brooklyn and Queens development sites utilize smartphone-capture quality previously requiring professional rigs.
Illinois
Chicago commercial brokerage networks embed spatial data into industrial property marketing for logistics and warehouse leasing. Midwest manufacturing facilities adopt VR headset-based training simulations as hardware cost curves intersect with enterprise safety mandates. FAA drone operation waivers limit aerial capture completeness for properties near O'Hare and Midway controlled airspace.
US Virtual Tour Market Competitive Landscape
Player mix skews toward platform-integrated hardware vendors and cloud-native software providers, with mid-tier capture service networks occupying fragmented territory between them. Consolidation pressure intensifies as enterprise property marketers demand compressed capture-to-publish timelines, forcing smaller operators into partnership or exit. Two strategic archetypes dominate: proprietary camera hardware owners anchoring institutional workflows, and browser-based distribution platforms achieving scale through frictionless access. Competitive moves concentrate on GPU-accelerated cloud processing stack rearchitecture and outcome-based pricing model adoption.
Within the hardware-integrated tier, Matterport Inc. and Google occupy positions representing divergent capture philosophies—proprietary camera ecosystems versus Street View infrastructure leveraging existing mapping distribution. Zillow anchors the residential funnel optimization archetype through search workflow embedding. CloudPano exemplifies the agile software-native approach competing on deployment velocity rather than hardware ownership.
| Leading Market Players |
|---|
| Matterport Inc. |
| Kuula LLC |
| Real Tour Vision Inc. |
| Concept3D Inc. |
| Zillow |
| CloudPano |
| Roundme Limited |
| iAriv |
| Others |
Pricing and Supply Chain Analysis
Gaussian Splatting substitution for polygonal mesh workflows simultaneously redistributes cloud compute spend toward GPU infrastructure and compresses vendor margins in established photogrammetry tiers, reshaping procurement geography toward Texas and Florida agencies with smartphone-capture capabilities.
Pricing Analysis
Current-generation NeRF and Gaussian Splatting pipelines command premium SaaS-tiered subscriptions against prior-generation photogrammetry bake-and-stream services, while next-generation edge-rendered architectures threaten further compression. Price differentiation rests on capture complexity tier and FCC broadband availability geography, with bandwidth-constrained rural properties trading at discount. Cost compression in 360-degree photography intensifies as smartphone capture quality encroaches professional rig output. Residential agents in Sun Belt markets exhibit highest price sensitivity; institutional landlords in Dallas-Fort Worth and Houston demonstrate lowest, accepting outcome-based contracts tied to lease velocity.
Supply Chain Analysis
Just-in-time inventory strategies dominate cloud processing stack procurement, with platform providers scaling GPU capacity on demand rather than maintaining dedicated render farms. Hardware concentration centers on Taiwan and South Korea for GPU accelerators, China for LiDAR sensor modules, and Japan for precision optics. Raw material dependencies span rare earth elements for solid-state LiDAR, high-bandwidth memory for neural reconstruction, and specialized glass for camera lenses. Single-source vulnerability in Asian LiDAR component suppliers exposes margins to supply disruption. Distribution runs through direct enterprise sales for institutional property marketers and channel partnerships for residential agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Virtual Tour Market functions as a service-attach opportunity where cloud processing subscriptions and outcome-based capture contracts expand faster than proprietary camera hardware sales, rewarding platform providers with recurring-revenue architecture over equipment vendors.
For Market Incumbents: Compound defensive positioning through GPU-accelerated mesh generation stack rearchitecture and exclusive Yardi, MRI, and RealPage API middleware development. Gaussian Splatting commoditization threatens photogrammetry incumbents with margin erosion. Vertical integration into proprietary capture hardware anchors institutional workflows against smartphone-capture entrants. For New Entrants and Emerging Players: FAA Part 107 certification fast-tracks unlock aerial-integrated capture white space in Texas metropolitan construction corridors and Florida coastal hospitality markets. Enterprise training simulations for OSHA compliance represent the most penetrable application segment. Channel partnerships with automotive retail dealership networks provide compliant go-to-market entry under NHTSA mobile app guidelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors cloud-native software platforms with GPU-accelerated processing stacks over hardware-integrated incumbents. Long-term viability across the projection horizon rests on recurring-revenue attach rates exceeding equipment depreciation cycles. Platform providers with BEAD-funded county penetration demonstrate clearest inflection signal for broadband-enabled 3D streaming scalability.| Strategic Initiative | Industry Significance |
|---|---|
| GPU-Accelerated Cloud Processing Stack Rearchitecture | Compresses capture-to-publish timelines from days to hours for enterprise property marketers. |
| Outcome-Based Pricing Model Adoption | Transfers capture risk to service providers while concentrating buyer power among REITs. |
| FCC BEAD-Funded County Expansion | Enables 3D streaming delivery to previously bandwidth-constrained rural commercial properties. |
| Neural Radiance Field Pipeline Integration | Reduces on-site capture time by an order of magnitude versus traditional photogrammetry. |
| Automotive Retail Dealership Channel Partnership | Creates NHTSA-compliant frameworks for immersive vehicle configurators and virtual showrooms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC broadband availability maps, FAA Part 107 waiver databases, and commercial real estate transaction records. Primary interviews engaged platform engineering leads at cloud-native providers, procurement directors at institutional property management firms, and photogrammetry technicians in Texas and Florida markets. Secondary validation drew from SEC filings of publicly traded capture hardware vendors, BEAD program infrastructure disclosures, and OSHA training simulation procurement data. Bottom-up unit economics triangulated against top-down addressable property inventory estimates.
Segmentation dimensions modeled span service type, end user archetype, deployment technology, and application use case across the analysis window. Service type captures 3D Tours, 360-Degree Photography, Interactive Experiences, and Mobile Apps. End user segmentation distinguishes enterprise property marketers from individual practitioners. Technology segmentation contrasts WebGL browser-based rendering against VR Headset deployments. Application segmentation separates Marketing, Training, Remote Assistance, and Event Planning workflows. CAGRs derived from penetration rate assumptions tied to FCC broadband expansion timelines and commercial construction permit volumes.
Decision-makers should treat outputs as directional under base assumptions of continued FCC infrastructure funding and stable FAA drone operation frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding WebGL browser compatibility convergence and VR headset cost curve trajectories. Revision becomes warranted when NeRF or Gaussian Splatting adoption crosses thresholds that fundamentally alter capture-to-publish economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market