
 North America Data Exfiltration Market | 2026-2036
North America Data Exfiltration Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Exfiltration Market Intelligence
Quantum-resistant encryption is hardening the economics of data protection across enterprise security stacks. Palo Alto Networks leverages its integrated platform strategy to dominate cloud-native deployments. CrowdStrike Holdings Inc. anchors endpoint detection with AI-driven threat intelligence. Fortinet Inc. competes through hardware-optimized security fabric consolidation.
Data exfiltration encompasses the unauthorized transfer of sensitive information from organizational networks through malware, insider actions, or compromised credentials, typically measured by dwell time and data volume metrics. Its primary commercial purpose centers on preventing intellectual property theft, customer record breaches, and operational disruption. Cloud-based deployment leads solution delivery as enterprises migrate security operations off-premises. Endpoint detection represents the fastest-growing solution offering as remote work expands attack surfaces. User behavior analytics commands premium margins by reducing false-positive rates in insider threat programs.
The SEC mandates incident disclosure timelines that compress response windows for publicly traded firms. California's CCPA and emerging state privacy laws in Virginia and Colorado create overlapping compliance obligations that reshape procurement criteria. NIST cybersecurity frameworks influence federal contractor requirements across defense and civilian agencies. Stakeholders must monitor the divergence between federal baseline standards and proliferating state-level mandates.
Market Dynamics
SEC disclosure timelines are compressing incident response windows for publicly traded firms, forcing security procurement cycles to accelerate from annual reviews to quarterly assessments. Healthcare systems and energy infrastructure operators now face overlapping federal mandates and state privacy laws that reshape vendor selection criteria.
Growth Catalysts
- Healthcare digitization:Hospital networks are deploying endpoint detection platforms to protect electronic health records governed by HIPAA breach notification rules. Texas medical centers lead adoption volume.
- SEC cybersecurity mandates:Public companies must disclose material incidents within four business days, eliminating traditional 90-day forensic windows. Compliance departments are expanding security budgets.
- Remote work infrastructure:Distributed workforces in California's technology corridor require cloud-native data loss prevention. Endpoint attack surfaces have multiplied across unmonitored home networks.
Market Restraints
- Specialized talent scarcity:Cybersecurity workforce gaps in threat hunting and forensics extend deployment timelines. Salaries for certified analysts have risen 40% in major metropolitan markets.
- Integration complexity:Legacy security information and event management systems resist API connectivity with modern exfiltration detection tools. Rip-and-replace costs deter mid-market adopters.
- Alert fatigue saturation:False-positive rates in behavior analytics platforms exceed 30% in some deployments, eroding security team confidence and delaying response protocols.
Strategic Opportunities
- Canadian critical infrastructure:Federal cybersecurity directives for energy and transportation sectors lack mature vendor ecosystems. Early entrants can establish preferred supplier status.
- AI-augmented forensics:Machine learning models trained on dwell-time patterns reduce mean-time-to-detection. Security operations centers in financial services are piloting autonomous response workflows.
- Managed detection services:Mid-sized enterprises in Colorado and Virginia prefer subscription-based threat monitoring over capital-intensive platform purchases. Channel partners are building specialized practices.
Industry Challenges
- Cross-border data governance:US firms with Canadian operations navigate divergent breach notification standards between PIPEDA and state-level US privacy laws. Legal review cycles extend procurement decisions.
- Quantum-readiness migration:Cryptographic inventory assessments consume 12-18 months for large enterprises. NIST post-quantum standards require algorithm replacements across data-at-rest and in-transit protections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Exfiltration Market |
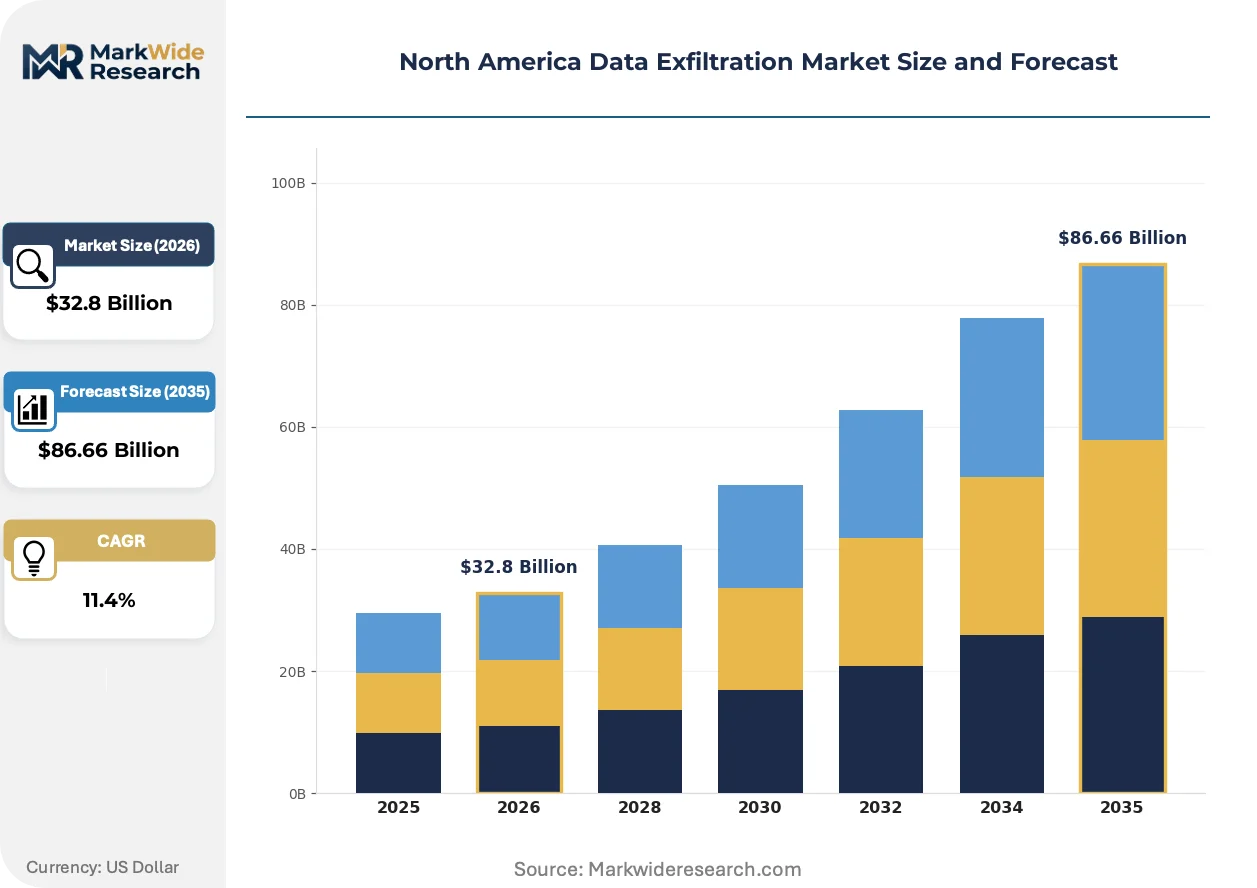
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Solution Offering: Data Loss Prevention, Endpoint Detection, Network Monitoring, User Behavior Analytics, Encryption Tools Application: BFSI, Telecom, Government Agencies, Education Sector, Manufacturing Facilities End User: Large Enterprises, Small & Medium Businesses, Managed Security Service Providers, Data Centers |
| Companies Covered | Palo Alto Networks Inc., Cisco Systems Inc., Forcepoint LLC, Fortinet Inc., Check Point Software Tech Ltd., Barracuda Networks Inc., Broadcom Inc., McAfee Corp., CrowdStrike Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Exfiltration Market Strategic Shifts & Innovations
Security architecture is converging around platform consolidation, replacing point-product stacks with integrated detection and response fabrics. Vendors are embedding artificial intelligence at the data layer to compress identification-to-containment intervals.
Extended detection and response platforms are integrating network, endpoint, and identity telemetry into unified data lakes. Fortune 500 enterprises in financial services and healthcare are standardizing on these architectures. Consolidation is integrating forensic workflows that previously required three separate analyst consoles.
California's CCPA enforcement actions are reshaping data mapping requirements for consumer record protection. Organizations must now maintain granular inventory of personal information flows. Retail and technology sectors in the state are deploying automated data classification to satisfy audit demands.
Security procurement patterns are fragmenting as chief information security officers bypass traditional reseller channels for direct vendor relationships. Cloud-native platforms enable self-service trials that compress evaluation cycles. This shift is most pronounced among venture-backed technology firms in Austin and Seattle metropolitan areas.
North America Data Exfiltration Market Segmentation
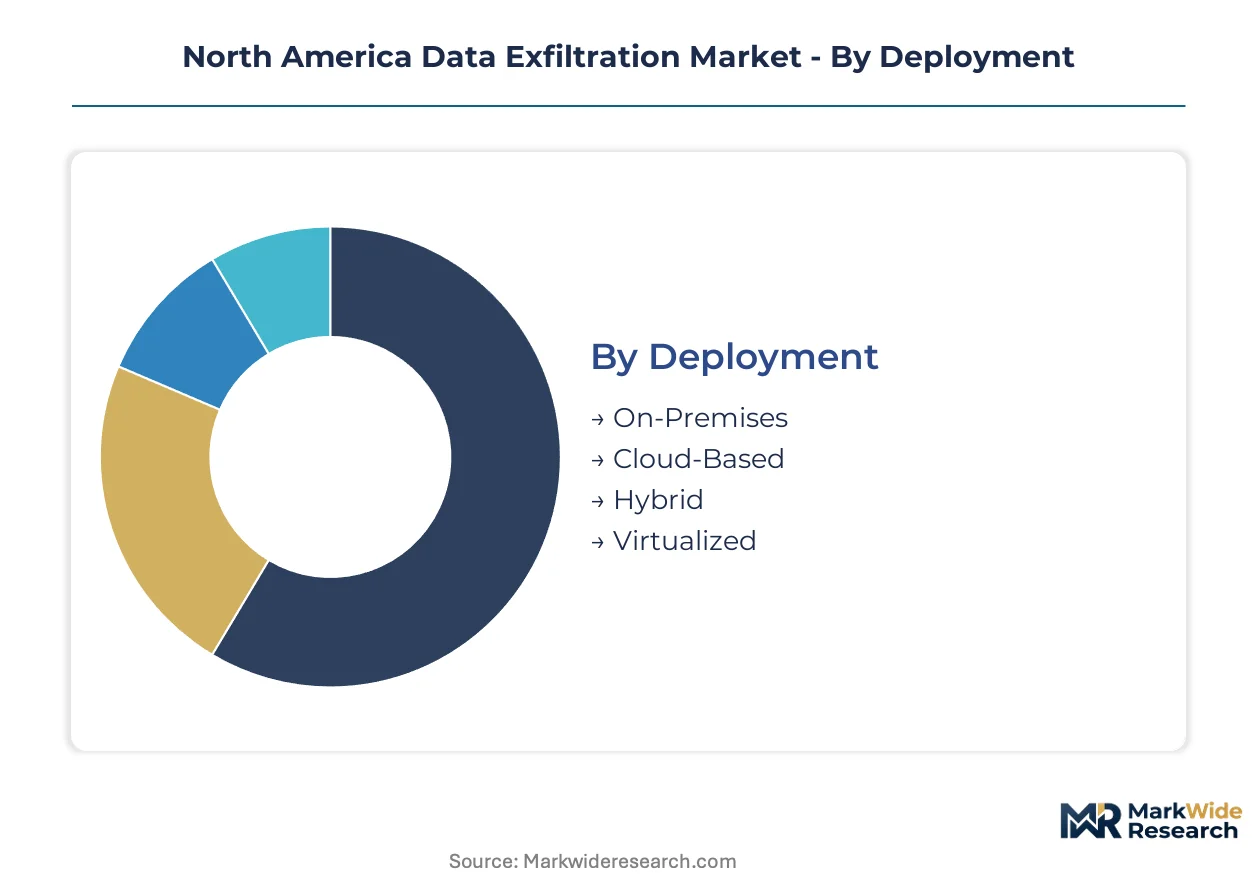
Deployment architecture determines integration complexity and operational overhead for data exfiltration defenses. Solution configurations must align with existing security stacks and regulatory exposure profiles.
Deployment:
Standalone deployments demand dedicated infrastructure and specialized staffing, while embedded systems integrate within broader security fabrics.
- Cloud-Based:Multi-tenant architectures deliver elastic capacity for threat detection workloads without capital expenditure. Financial services firms in New York and Chicago are migrating detection operations to cloud-native platforms to compress deployment timelines.
- Hybrid:Split architectures maintain sensitive data processing on-premises while leveraging cloud analytics for pattern recognition. Energy sector operators in Texas and Alberta favor this model for operational technology segmentation.
- On-Premises:Air-gapped installations serve defense contractors and classified government facilities with strict data sovereignty requirements.
- Virtualized:Containerized detection modules deploy rapidly across distributed infrastructure without hardware procurement cycles.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Hybrid architectures.
Solution Offering:
Premium-margin segments reduce analyst burden through automation, while commodity tools require heavier human oversight.
- User Behavior Analytics:Machine learning models baseline normal activity patterns to flag anomalous data access without signature dependencies. Healthcare systems in California and Massachusetts are prioritizing these tools for insider threat programs under HIPAA scrutiny.
- Endpoint Detection:Agent-based monitoring captures file system operations and network connections on laptops, servers, and mobile devices. Remote work expansion across technology corridors has multiplied endpoint attack surfaces requiring coverage.
- Data Loss Prevention:Policy engines inspect content in motion and at rest to block unauthorized exfiltration channels.
- Network Monitoring:Deep packet inspection and flow analysis identify covert channels and command-and-control communications.
- Encryption Tools:Data-at-rest and in-transit protections render exfiltrated information unintelligible without key access.
Revenue concentration sits with Endpoint Detection; User Behavior Analytics is gaining share fastest through reduced false-positive economics.
Application:
Sector-specific compliance mandates reshape procurement criteria and deployment urgency across vertical markets.
- BFSI:Banks and insurers face SEC disclosure timelines and state privacy law overlap that compress incident response windows. New York and Toronto financial centers are expanding security operations center staffing.
- Government Agencies:Federal and state entities operate under NIST frameworks with mandatory reporting to CISA. Defense contractors in Virginia and Maryland maintain specialized clearance requirements.
- Telecom:Critical infrastructure designation brings FCC and sector-specific cybersecurity obligations for network operators.
- Education Sector:Universities balance open research collaboration with protection of student records under FERPA.
- Manufacturing Facilities:Industrial control system segmentation challenges complicate deployment of standard endpoint agents.
BFSI commands the largest contract values; Government Agencies show the steepest budget expansion trajectory driven by federal directives.
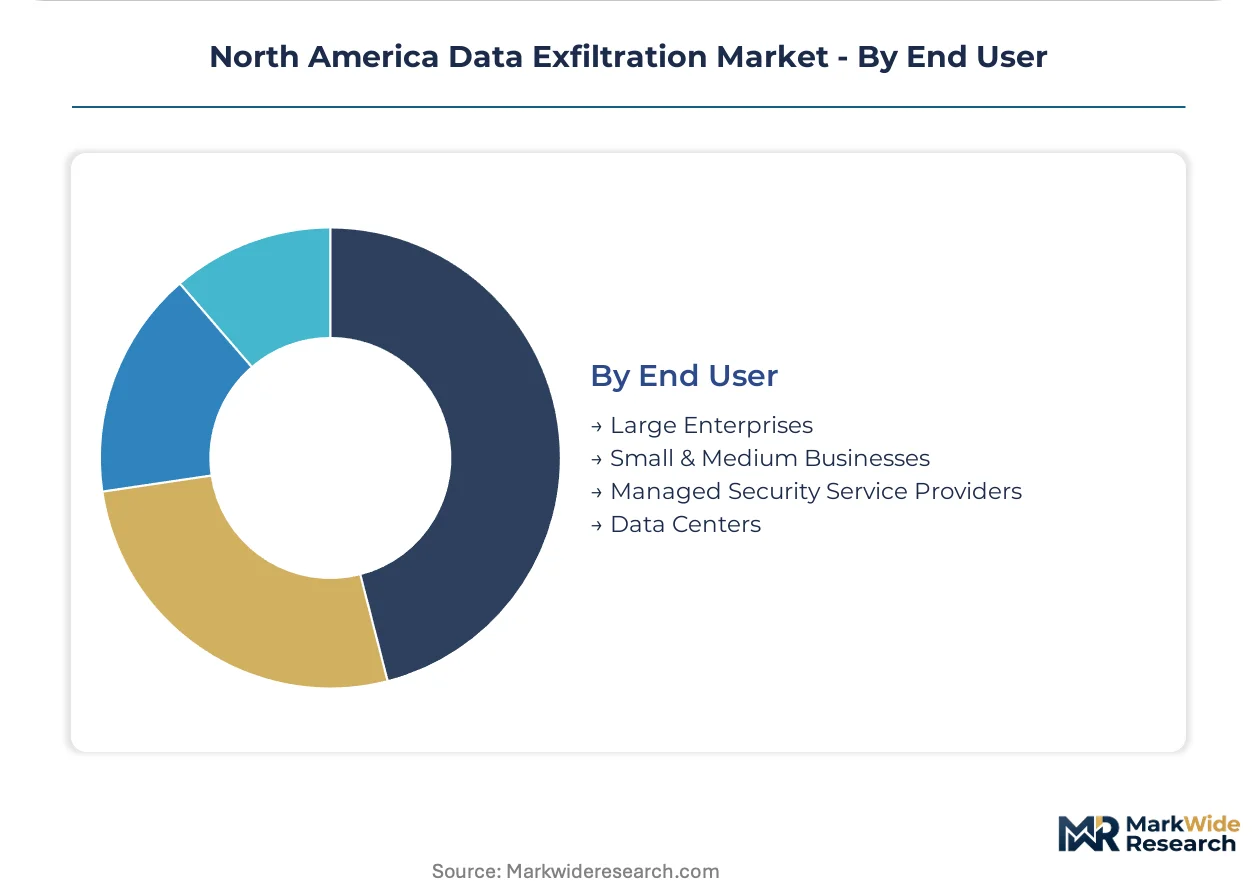
End User:
Organizational scale determines whether internal security operations or external service relationships dominate procurement patterns.
- Large Enterprises:Fortune 500 companies maintain dedicated threat hunting teams and custom integration requirements. California technology firms and Texas energy majors are consolidating vendor relationships around platform strategies.
- Managed Security Service Providers:Third-party operators deliver 24/7 monitoring for organizations lacking internal capabilities. Channel partners in Colorado and Virginia are building specialized data exfiltration practices.
- Small & Medium Businesses:Resource constraints drive preference for bundled security offerings with minimal configuration overhead.
- Data Centers:Colocation and cloud facilities must protect multi-tenant environments with shared infrastructure risks.
Large Enterprises account for dominant procurement volume; Managed Security Service Providers are climbing the fastest as mid-market outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's technology corridor and Texas energy sector anchor North American demand concentration. The SEC's cybersecurity disclosure rules compress incident response timelines across publicly traded firms. Provincial cybersecurity directives in Canada and state-level privacy mandates create overlapping compliance architectures.
United States
California technology firms and Texas energy operators drive procurement volume for cloud-native data loss prevention platforms. The SEC mandates four-business-day incident disclosure timelines that eliminate traditional forensic windows. Healthcare systems in Massachusetts and hospital networks across Texas accelerate endpoint detection deployments under HIPAA breach notification scrutiny.
Canada
Critical infrastructure operators in Alberta's energy sector and Ontario's financial centers demand hybrid deployment architectures for operational technology segmentation. Federal cybersecurity directives for energy and transportation sectors lack mature vendor ecosystems. Security operations centers in Toronto and Vancouver expand staffing to navigate divergent PIPEDA and US state privacy law obligations.
Mexico
Manufacturing facilities in Nuevo León and Mexico City Metro face industrial control system segmentation challenges for standard endpoint agents. The country's national data protection authority enforces breach notification standards that extend procurement review cycles. Nearshoring technology firms in Guadalajara adopt cloud-based detection platforms to protect distributed workforces.
North America Data Exfiltration Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with platform consolidation displacing point-product stacks. The vendor base concentrates around integrated security fabrics rather than standalone tools. Three archetypes dominate: cloud-native platform providers, hardware-optimized security fabric vendors, and AI-driven endpoint detection specialists. M&A activity targets behavioral analytics capabilities, while strategic partnerships accelerate managed detection service channel buildouts.
Within the integrated platform tier, Palo Alto Networks Inc. and Cisco Systems Inc. exemplify cloud-native consolidation strategies, while CrowdStrike Holdings Inc. anchors AI-driven endpoint detection positioning. Fortinet Inc. occupies the hardware-optimized security fabric archetype. These three vendors represent divergent architectural bets on how enterprise security operations will consolidate detection and response workflows.
| Leading Market Players |
|---|
| Palo Alto Networks Inc. |
| Cisco Systems Inc. |
| Forcepoint LLC |
| Fortinet Inc. |
| Check Point Software Tech Ltd. |
| Barracuda Networks Inc. |
| Broadcom Inc. |
| McAfee Corp. |
| CrowdStrike Holdings Inc. |
| Others |
Cost & Logistics Intelligence
Certified threat-hunting labor costs cascade through subscription tiers, compressing margins for mid-market vendors while platform providers in California and Texas capture premium pricing through embedded AI modules. The path from specialized analyst salaries to end-user SaaS pricing stratifies across enterprise scale, with HIPAA-compliant healthcare deployments commanding the highest per-seat rates.
Pricing Analysis
Short lead-time premiums apply to cloud-native deployments requiring sub-30-day implementation windows, while annual contracts with extended onboarding cycles trade at 15-25% discounts. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 platform bundles from mid-market managed service offerings and SMB tool suites. Cost compression in the standard tier is intensifying because CrowdStrike and Palo Alto Networks are bundling endpoint detection with adjacent security modules. Small and medium businesses exhibit the highest price sensitivity, driving preference for per-user subscription models over capacity-based licensing.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor fabrication for specialized network processing chips powering deep packet inspection appliances. Hardware supply chains draw from Taiwan, South Korea, and domestic US facilities for encryption accelerators and threat-intelligence processing units. Critical dependencies include custom ASICs, high-bandwidth memory modules, and quantum-resistant cryptographic libraries. Tariff exposure on Chinese-manufactured server components threatens margin stability for hardware-optimized vendors like Fortinet. Distribution runs through direct vendor relationships with enterprise security teams, bypassing traditional VAR channels for cloud-native platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Data Exfiltration Market functions as a cost-of-compliance arena where SEC four-day disclosure mandates erect barrier-to-entry moats for vendors lacking incident-response automation. Regulatory friction favors incumbents with pre-built CCPA and HIPAA audit workflows.
For Market Incumbents: Deploy AI-augmented forensics capabilities to compress mean-time-to-detection below competitor benchmarks. CrowdStrike's threat-graph architecture demonstrates how behavioral analytics integration defends against Palo Alto's platform consolidation threat. Channel control through MSSP certification programs locks in mid-market recurring revenue streams. For New Entrants and Emerging Players: Canadian critical infrastructure gaps present the most penetrable white-space, with Alberta energy operators and Ontario transportation authorities lacking mature vendor ecosystems. Managed detection services for Colorado and Virginia mid-market firms offer lower competitive density than California's saturated technology corridor. A cloud-native trial-to-subscription model bypasses traditional procurement cycles. For Investors and Strategic Acquirers: CISA directive expansion into state-level agencies is the leading indicator that government segment budget trajectories will steepen further. Behavioral analytics specialists with healthcare HIPAA certifications represent the optimal acquisition archetype for platform consolidation plays. Watch for SEC enforcement actions against delayed disclosure as the signal that compliance automation demand is inflecting.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidated XDR fabrics reduce analyst console fragmentation for Fortune 500 security operations centers. |
| Acquisition of Specialist Firm | Behavioral analytics capabilities address the 30% false-positive rates eroding incumbent tool confidence. |
| Geographic Expansion | Canadian federal cybersecurity directives for energy and transportation sectors lack mature vendor ecosystems. |
| Strategic Partnership | MSSP channel buildouts capture mid-market outsourcing acceleration in Colorado and Virginia metropolitan areas. |
| Product Launch | Quantum-resistant encryption modules align with NIST post-quantum standards requiring algorithm replacements. |
Research Approach
Multi-period observation of endpoint detection adoption rates, SEC disclosure compliance timelines, and healthcare breach notification patterns anchored the trend analysis, supplemented by interviews with CISOs at Fortune 500 financial services firms, security operations center directors in Texas energy infrastructure, HIPAA compliance officers at California hospital networks, and channel partners building managed detection practices. Secondary validation drew from SEC cybersecurity disclosure filings, CISA incident reporting databases, state attorney general breach notification records, and hyperscaler security capex disclosures. Bottom-up deployment volume estimates triangulated against top-down security spending surveys.
Input-output matrices mapped deployment architecture choices to solution offering configurations across organization size tiers and vertical regulatory exposure profiles. Segmentation dimensions modeled include cloud-hybrid-on-premises deployment, endpoint-network-encryption solution type, BFSI-healthcare-government vertical application, and enterprise-MSSP-SMB end-user category. CAGRs were derived from regression analysis of historical procurement velocity against regulatory mandate effective dates. Forecast inputs incorporated HIPAA breach notification enforcement intensity and SEC disclosure timeline compliance rates.
The model holds under stable regulatory enforcement intensity; deviation in CCPA litigation volume or NIST framework revision timing would shift adoption curve assumptions. Forecasts reflect documented assumptions about cloud migration velocity and analyst workforce expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Internet of Things (IoT) Security Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Europe Data Protection-As-A-Service Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
Global Ddos Protection Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
Argentina Cybersecurity Market
Cybersecurity
DNS Security Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Latin America Ransomware Protection Market
Cybersecurity
Artificial Intelligence-Based Cybersecurity Market
Cybersecurity
Bangladesh Cybersecurity Market
Cybersecurity
Global Sandboxing Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
Global Container and Kubernetes Security Market