
 Global Big Data Software Market | 2026-2036
Global Big Data Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Big Data Software Market Foresight
Apache Spark is pivoting away from MapReduce as the default processing engine for large-scale data workloads, cutting infrastructure overhead for enterprises running petabyte-scale pipelines. Microsoft Corporation leverages its Azure ecosystem to anchor hybrid deployment contracts across Fortune 500 accounts. Amazon Web Services dominates spot pricing for elastic compute clusters, sustaining margin pressure on dedicated infrastructure vendors.
Big data software encompasses distributed processing frameworks, columnar storage engines, and query optimization layers designed to ingest, structure, and analyze datasets exceeding terabyte thresholds with sub-second latency requirements. Its primary commercial purpose is converting raw operational signals into actionable intelligence for automated decision systems. Public cloud deployment leads volume adoption while data analytics solutions command the deepest margin pools due to embedded machine learning inference capabilities. Data visualization remains a mature category with consolidation pressure, whereas data integration is accelerating fastest as enterprises unify siloed ERP and CRM repositories.
The EU AI Act imposes risk-tiered documentation mandates on algorithmic systems processing personal or sensitive data, directly shaping procurement criteria for European financial institutions. China's SAMR enforces cross-border data transfer rules under GB standards that constrain how multinational firms architect regional data lakes. ISO 27001 and SOC 2 Type II certifications have become non-negotiable gatekeepers for vendor selection in BFSI procurement cycles. Stakeholders must weigh sovereign data requirements against cloud portability when committing to multi-year platform contracts.
Market Dynamics
Apache Spark's migration from MapReduce to native execution engines is compressing infrastructure costs for petabyte-scale workloads while forcing legacy Hadoop vendors to reposition. This architectural pivot is reshaping procurement criteria across financial services and cloud-native enterprises.
Growth Catalysts
- EU AI Act documentation mandates:Risk-tiered compliance requirements for algorithmic systems processing sensitive data are accelerating replacement cycles among European financial institutions.
- Real-time analytics adoption:Financial services firms are deploying stream processing frameworks to enable sub-second fraud detection and automated trading execution.
- California cloud-native enterprise concentration:Technology firms in the San Francisco Bay Area are anchoring demand for elastic compute clusters with embedded machine learning inference.
Market Restraints
- Cross-border data transfer constraints:China's SAMR enforcement of GB standards restricts how multinational firms architect regional data lakes, fragmenting global deployments.
- Specialized talent scarcity:Shortage of engineers proficient in distributed systems optimization and query engine tuning limits pipeline velocity for enterprise adopters.
- ISO 27001 certification costs:BFSI procurement cycles now require SOC 2 Type II attestation, extending vendor onboarding timelines by 6-12 months.
Strategic Opportunities
- ERP-CRM unification demand:Data integration software is accelerating fastest as enterprises consolidate siloed operational repositories into unified analytics platforms.
- Hybrid deployment architectures:Microsoft Azure's ecosystem anchoring creates pathways for multi-cloud orchestration contracts across regulated industries.
- India's digital public infrastructure:The country's PLI scheme for data centers is attracting hyperscale investment in Mumbai and Hyderabad clusters.
Industry Challenges
- Query optimization expertise gaps:Enterprises struggle to staff teams capable of tuning columnar storage engines for sub-second latency on trillion-row datasets.
- Legacy system integration friction:Mainframe data repositories in established financial institutions resist seamless ingestion into cloud-native processing frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Big Data Software Market |
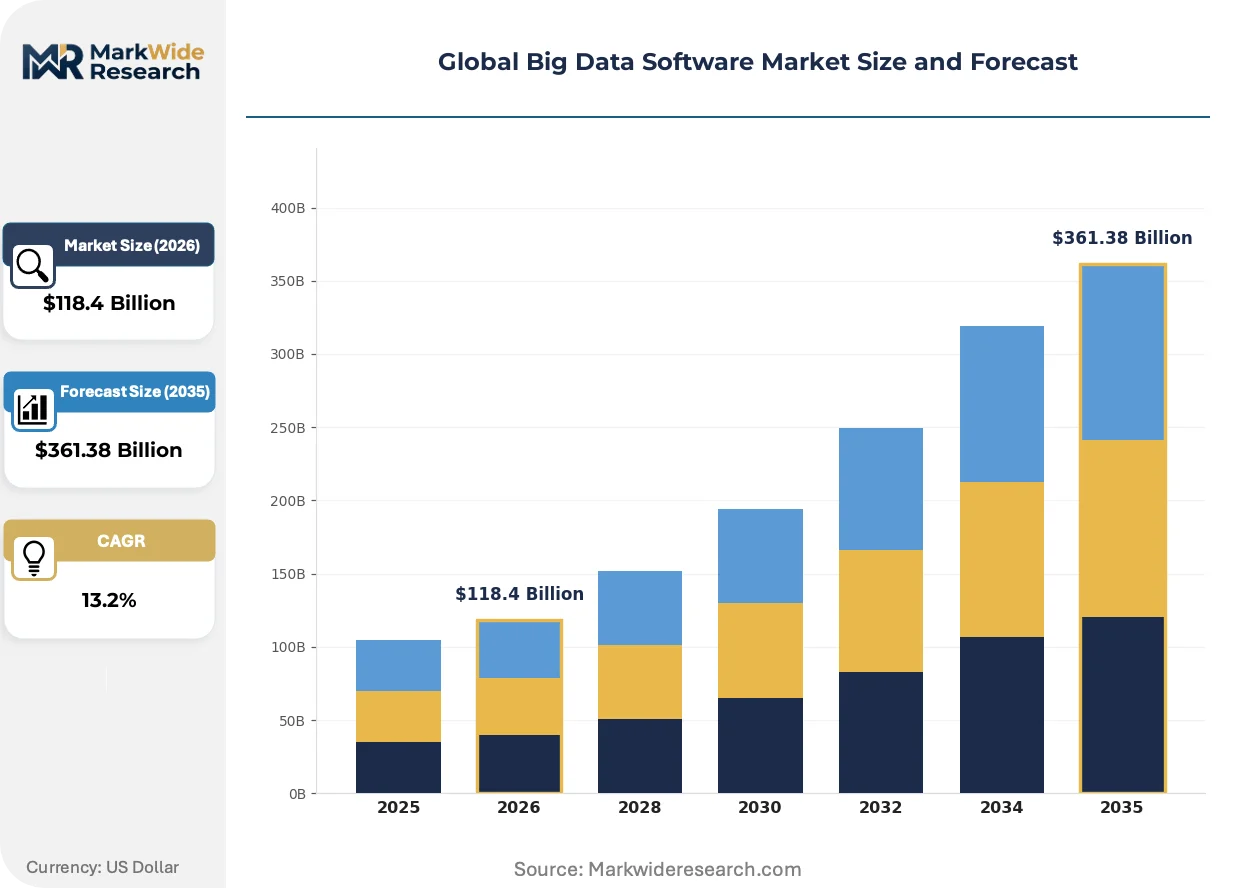
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $361.38 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
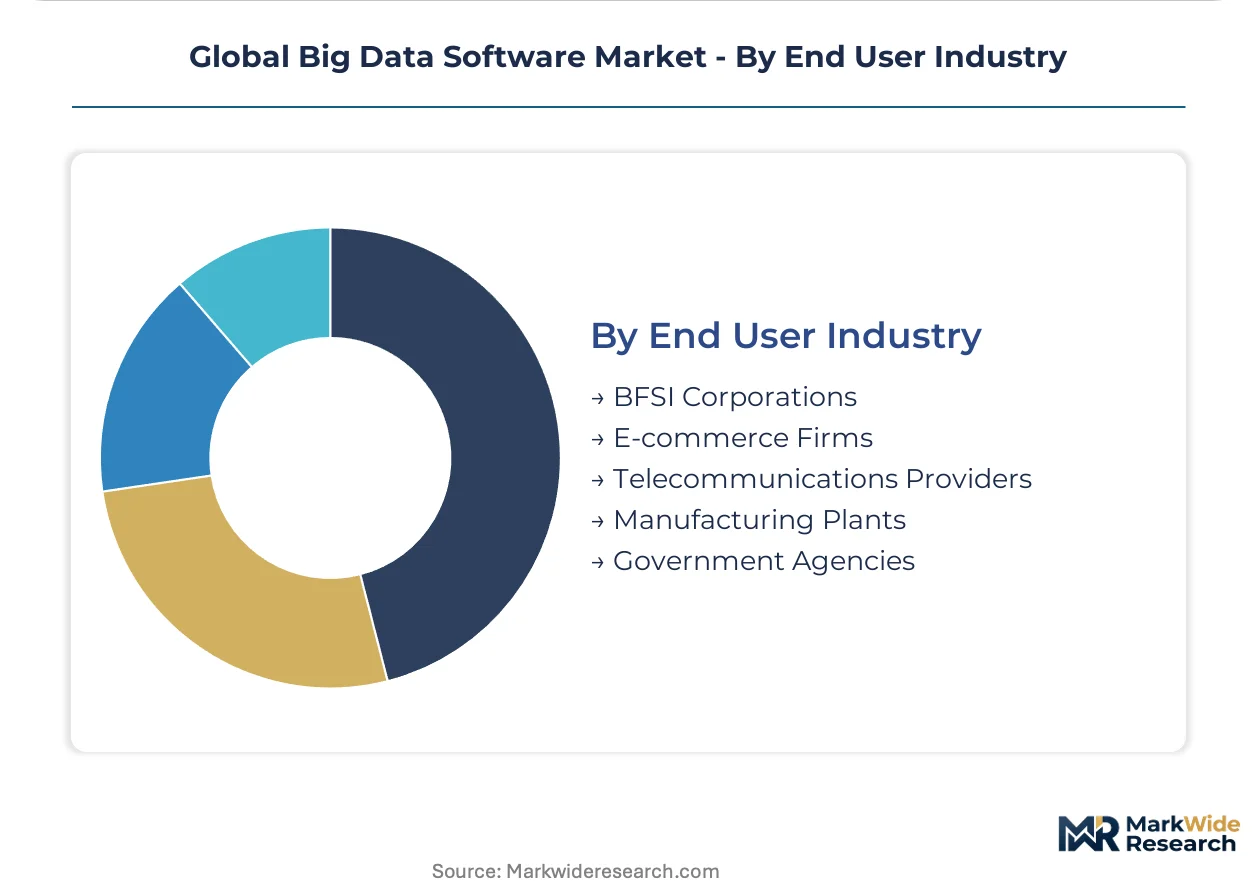
| Segmentation | Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Solution/Offering: Data Integration, Data Analytics, Data Visualization, Data Storage, Data Management Application: Customer Analytics, Risk Management, Fraud Detection, Supply Chain Optimization, Predictive Maintenance End User Industry: BFSI Corporations, E-commerce Firms, Telecommunications Providers, Manufacturing Plants, Government Agencies |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Amazon Web Services, Salesforce, Google Cloud, SAS Institute Inc., Snowflake Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Big Data Software Market Shifts & Advancements
Vectorized query execution and GPU-accelerated analytics are compressing batch processing windows from hours to minutes. These architectural advances are enabling new real-time use cases that were previously computationally prohibitive.
Apache Spark's photon engine is expanding into production workloads at Fortune 500 financial services firms, cutting infrastructure overhead by eliminating JVM garbage collection bottlenecks. Capital markets desks in New York and London are deploying this engine for tick-by-tick analytics. The technology is expanding into adjacent segments including insurance risk modeling and healthcare claims processing.
The EU AI Act's risk classification framework is mandating algorithmic impact assessments for high-stakes automated decision systems. European banks must now maintain technical documentation spanning data provenance, model architecture, and human oversight protocols. German and French regulators are conducting joint inspections of credit scoring algorithms, creating compliance templates that will propagate across the continent.
Consumption-based pricing for analytics workloads is displacing perpetual license models in enterprise procurement. Retail and logistics buyers are negotiating contracts tied to actual query volumes rather than provisioned capacity. This shift is most pronounced among mid-market firms in the United States seeking to align software costs with seasonal demand fluctuations.
Global Big Data Software Market Segmentation

Deployment architecture determines margin structure and compliance posture for big data software procurement. Solution specialization separates volume commoditization from premium analytics capabilities. Application focus and end-user vertical concentration shape vendor competitive intensity across regional markets.
Deployment:
Public cloud captures volume adoption while hybrid deployments command premium pricing through regulatory flexibility.
- On-Premises:Dedicated infrastructure within enterprise data centers provides complete data sovereignty and lowest latency for sensitive workloads. Financial institutions in Frankfurt and Zurich maintain on-premises clusters to satisfy national banking regulators' data localization mandates.
- Public Cloud:Elastic compute pools from hyperscale providers eliminate capital expenditure for variable workloads. Technology firms in California's Bay Area anchor demand for auto-scaling Spark clusters with embedded GPU acceleration.
- Private Cloud:Single-tenant virtualized environments balance control with operational flexibility. German automotive manufacturers deploy private cloud data lakes to isolate proprietary sensor telemetry from multi-tenant infrastructure.
- Hybrid Cloud:Orchestrated workloads spanning on-premises and cloud resources enable tiered data residency. US healthcare systems route de-identified analytics to public cloud while retaining patient records in HIPAA-compliant private infrastructure.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Solution/Offering:
Analytics solutions extract premium margins through embedded machine learning, while storage and management functions face commoditization pressure.
- Data Integration:Pipeline orchestration tools unify siloed ERP and CRM repositories into coherent analytics substrates. US retail conglomerates are accelerating procurement of real-time CDC streaming platforms to synchronize omnichannel transaction data.
- Data Analytics:Query engines with vectorized execution and GPU acceleration compress batch windows from hours to minutes. Capital markets desks in New York and London deploy sub-second tick analytics for algorithmic trading execution.
- Data Visualization:Dashboard and reporting layers have matured into consolidated platforms with limited differentiation. Mid-market firms in the United States negotiate consumption-based contracts tied to actual user seats rather than provisioned capacity.
- Data Storage:Columnar formats and object storage tiers optimize cost per terabyte for petabyte-scale retention. India's PLI scheme for data centers is attracting hyperscale investment in Mumbai and Hyderabad storage clusters.
- Data Management:Governance, cataloging, and lineage tools enforce EU AI Act documentation mandates for algorithmic systems. European banks must maintain technical documentation spanning data provenance and model architecture under German-French regulatory joint inspections.
Analytics commands the deepest margin pools; integration is expanding most quickly as enterprises consolidate operational repositories.
Application:
Fraud detection concentrates procurement in financial services while predictive maintenance spreads across asset-heavy industries.
- Customer Analytics:Behavioral segmentation and lifetime value scoring drive personalization engines. E-commerce firms in the United States deploy real-time recommendation systems processing clickstream data with sub-100-millisecond latency.
- Risk Management:Credit scoring and portfolio stress testing require explainable model architectures under EU AI Act high-risk system classifications. French and German regulators conduct joint inspections of automated lending algorithms.
- Fraud Detection:Stream processing frameworks enable sub-second transaction blocking for payment networks. US card issuers anchor demand for Apache Spark-based anomaly detection with embedded machine learning inference.
- Supply Chain Optimization:Demand forecasting and inventory positioning algorithms reduce working capital requirements. Manufacturing plants in Japan's automotive sector deploy digital twin simulations for supplier risk quantification.
- Predictive Maintenance:Sensor telemetry analysis prevents unplanned downtime in capital-intensive operations. Saudi Aramco's deployment of vibration analytics across upstream facilities demonstrates scaling potential for industrial IoT data lakes.
Fraud detection leads current procurement velocity; predictive maintenance shows the steepest expansion trajectory as industrial IoT sensor density increases.
End User Industry:
BFSI corporations dominate premium analytics spending while government agencies drive standardization through procurement scale.
- BFSI Corporations:Banks, insurers, and asset managers require ISO 27001 and SOC 2 Type II certifications as non-negotiable vendor selection criteria. European institutions face compressed replacement cycles under EU AI Act risk-tiered documentation mandates.
- E-commerce Firms:Digital retailers prioritize elastic compute clusters that align software costs with seasonal demand fluctuations. Consumption-based pricing models displace perpetual licenses among mid-market US buyers.
- Telecommunications Providers:Network operators analyze call detail records and cell tower telemetry for capacity planning. India's Reliance Jio anchors regional demand for petabyte-scale subscriber analytics platforms.
- Manufacturing Plants:Industrial firms unify operational technology and information technology data streams for quality optimization. Germany's Mittelstand engineering sector drives adoption of edge-to-cloud hybrid architectures.
- Government Agencies:Public sector procurement emphasizes sovereign data requirements and long-term vendor stability. China's SAMR enforcement of GB standards constrains how multinational firms architect regional data lakes for state-owned enterprise contracts.
BFSI anchors premium spending today; manufacturing plants are gaining share fastest as industrial digitalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Bay Area technology corridor anchors global demand for elastic compute clusters with embedded machine learning inference. Financial services firms in New York and London drive real-time analytics procurement for algorithmic trading. India's digital infrastructure expansion attracts hyperscale investment in Mumbai and Hyderabad data center clusters.
United States
Cloud-native enterprises in California and New York concentrate procurement of auto-scaling Spark clusters with GPU acceleration. The SEC enforces disclosure requirements for algorithmic trading systems that process market data. Capital markets desks in Manhattan deploy sub-second tick analytics for fraud detection and automated execution.
China
State-owned enterprises anchor demand for sovereign data lakes under GB standards compliance mandates. SAMR enforces cross-border data transfer rules that constrain how multinational firms architect regional deployments. Hyperscale investment clusters in Beijing and Shanghai support industrial IoT analytics for manufacturing digitalization.
Germany
Mittelstand engineering firms drive adoption of edge-to-cloud hybrid architectures for quality optimization. The EU AI Act imposes risk-tiered documentation mandates on algorithmic systems processing sensitive financial data. Frankfurt banking regulators require on-premises clusters to satisfy data localization mandates for credit scoring algorithms.
India
Reliance Jio anchors regional demand for petabyte-scale subscriber analytics platforms. The PLI scheme for data centers attracts hyperscale investment in Mumbai and Hyderabad storage clusters. Bangalore technology firms deploy real-time CDC streaming platforms to synchronize omnichannel transaction data.
United Kingdom
London capital markets desks deploy Apache Spark-based anomaly detection for payment network security. The FCA coordinates with EU regulators on algorithmic trading oversight despite post-Brexit divergence. Edinburgh financial services firms maintain hybrid deployments to balance cloud agility with legacy system integration.
Global Big Data Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscale providers anchor hybrid deployment contracts across regulated industries. The vendor base concentrates around three tiers: cloud-native platforms with consumption-based pricing, legacy enterprise software houses pivoting from perpetual licenses, and specialized analytics engines with vectorized execution. Two archetypes define competitive positioning: ecosystem integrators leveraging existing cloud relationships, and performance specialists compressing query latency through GPU acceleration. M&A activity and technology licensing agreements represent the dominant competitive moves as incumbents acquire stream processing capabilities and optimization engines.
Within the ecosystem integrator tier, Microsoft Corporation exemplifies the hybrid deployment anchor position through Azure-anchored contracts, while Amazon Web Services occupies the elastic compute pricing specialist role. Among performance-focused specialists, Snowflake Inc. represents the consumption-based analytics archetype that aligns software costs with actual query volumes rather than provisioned capacity.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Amazon Web Services |
| Salesforce |
| Google Cloud |
| SAS Institute Inc. |
| Snowflake Inc. |
| Others |
Supply & Pricing Matrix
Fortune 500 financial services procurement teams in New York and London anchor demand for consumption-based analytics contracts that eliminate upfront capital commitment. This buyer concentration enables SaaS vendors to extract premium pricing through embedded machine learning inference capabilities while forcing perpetual-license incumbents toward usage-aligned models.
Pricing Analysis
GPU compute costs and certified compliance overhead pass through to enterprise buyers via tiered subscription structures. Three-tier pricing separates SOC 2 Type II certified deployments from standard cloud tiers and economy self-managed options. Price differentiation centers on query latency guarantees and data residency controls. Cost compression in economy tiers intensifies because hyperscale providers crowd dedicated infrastructure vendors. Mid-market e-commerce firms in the United States exhibit highest price sensitivity; capital markets desks show lowest.
Supply Chain Analysis
Engineering talent scarcity in distributed systems optimization constrains pipeline velocity across Bangalore, Berlin, and San Francisco development clusters. Big data software supply draws from specialized query engine developers in the United States, stream processing specialists in Israel, and cloud infrastructure operators in Ireland and Singapore. Single-source vulnerability runs through NVIDIA's dominance in GPU acceleration hardware for vectorized analytics. Distribution runs through hyperscale marketplaces and direct enterprise field sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in big data software rests on photon-engine adoption eliminating JVM overhead and consumption-based pricing capturing seasonal demand spikes without capacity provisioning.
For Market Incumbents: Acquire stream processing capabilities to defend against Apache Flink-based entrants displacing Spark in real-time fraud detection workloads. Invest in ISO 27701 privacy certification to preempt EU AI Act documentation mandates that European banks now require. Build captive GPU capacity in Mumbai and Hyderabad to offset hyperscale spot pricing volatility. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for compliance-native documentation platforms that automate algorithmic impact assessment workflows. Target Mittelstand manufacturers in Baden-Württemberg with edge-to-cloud hybrid architectures for sensor telemetry unification. Lead with open-source query engines and monetize through managed service tiers. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, consolidating vectorized execution engines and CDC streaming platforms. Five-to-ten year viability favors vendors with embedded machine learning inference and consumption-based contract structures. Watch for inflection when European joint regulatory inspections of credit scoring algorithms propagate standardized compliance templates continent-wide.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure anchors hybrid contracts across Fortune 500 BFSI accounts requiring data residency flexibility. |
| Acquisition of Specialist Firm | Stream processing startups with sub-second latency capabilities command premium multiples from ecosystem integrators. |
| Geographic Expansion | India's PLI scheme for data centers attracts hyperscale investment in Mumbai storage clusters serving Asia-Pacific demand. |
| Product Launch | Photon-engine query execution cuts infrastructure overhead for tick-by-tick analytics at New York capital markets desks. |
| Strategic Partnership | Snowflake partners with GPU cloud providers to embed accelerated analytics without customer-managed infrastructure. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down hyperscale capex tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across California, New York, London, and Bangalore inform adoption pattern assumptions. Secondary validation draws from SEC filings, hyperscaler infrastructure expenditure disclosures, EU AI Act regulatory filings, and Apache Software Foundation release documentation. Cross-referencing consumption-based contract disclosures against provisioned capacity investments enables pricing model triangulation.
Input-output matrices map query volume growth to infrastructure deployment across deployment architecture, organization size, vertical concentration, integration complexity, and regional regulatory cluster dimensions. CAGRs derive from segment-level adoption curves weighted by compliance-driven replacement cycles. Forecast inputs include EU AI Act implementation timelines and India's data center PLI scheme investment trajectories across the analysis window.
Revisions become necessary when EU AI Act enforcement intensity diverges from modeled assumptions or when China's SAMR cross-border data rules expand beyond current GB standard scope. Forecasts reflect documented assumptions about GPU cost curves and talent availability in distributed systems engineering. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Legal Practice Management Software Market
Software & Services
Productivity Management Software Market
Software & Services
Camp Management Software Market
Software & Services
Background Removal Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Online Project Management Software Market
Software & Services
House Cleaning App Market
Software & Services
Global Translation Software Market
Software & Services
HR Saas Market
Software & Services
Software Repository Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Bankruptcy Software Market
Software & Services
Device Tracking Software Market
Software & Services
Mobile Application Development Market