
 Network Detection and Response Market | 2026-2036
Network Detection and Response Market Size, Share, and Industry Trends Forecast 2026-2036
Network Detection and Response Market Insights
The capital-intensity gap between cloud-native and appliance-centric vendors is bifurcating competitive dynamics in this space. Cisco Systems leverages its installed base of routing and switching infrastructure to embed detection capabilities at the network edge. Palo Alto Networks sustains R&D intensity across its integrated Cortex platform, anchoring its position in hybrid deployment environments.
Network Detection and Response encompasses hardware and software systems that inspect east-west and north-south traffic flows using machine learning models and protocol analysis, with typical deployment requiring 10 Gbps to 100 Gbps throughput per sensor node to support real-time threat identification and automated containment. The technology serves industrial and commercial purposes by reducing dwell time of advanced persistent threats within enterprise networks. Deployment models show hybrid architectures capturing margin pools as organizations retain on-premises sensors for regulated data while offloading analytics to cloud consoles. Behavioral analytics technology leads adoption curves, displacing signature-dependent approaches in financial and healthcare verticals where zero-day exposure dominates risk profiles.
The US SEC, NIST, and EU NIS2 Directive collectively shape product roadmaps by mandating incident disclosure timelines and supply-chain security attestations that vendors must engineer into their platforms. HIPAA security rule enforcement in healthcare and FERC CIP standards in energy utilities further segment addressable demand by compliance vertical. Stakeholders must weigh the trade-off between platform consolidation and best-of-breed specialization as attack surface expansion outpaces unified vendor innovation cycles.
Market Dynamics
Behavioral analytics engines are compressing signature-based detection architectures as financial institutions face SEC disclosure mandates requiring sub-hour incident reporting. This technology substitution is redrawing vendor competitive boundaries.
Growth Catalysts
- SEC Cybersecurity Rules:US financial services firms must disclose material breaches within four business days, forcing procurement of automated detection platforms with embedded compliance reporting.
- Healthcare HIPAA Enforcement:US hospital systems face escalating penalties for PHI exposure, driving sensor deployment across clinical networks to satisfy security rule audit requirements.
- Machine Learning Inference:GPU-accelerated threat classification at 100 Gbps line rate enables real-time east-west traffic inspection without performance degradation.
Market Restraints
- Silicon Supply Concentration:Advanced FPGA and SmartNIC components for high-throughput sensors concentrate among Taiwan and South Korea foundries, creating procurement vulnerability.
- Encryption Blind Spots:TLS 1.3 and post-quantum cipher adoption obscures payload inspection, degrading detection efficacy for encrypted lateral movement.
- FERC CIP Compliance Burden:North American electric utilities face multi-year certification cycles for critical cyber assets, elongating sales timelines.
Strategic Opportunities
- Operational Technology Convergence:IT-OT network segmentation in manufacturing plants creates demand for industrial protocol-aware sensors that understand Modbus and DNP3 traffic.
- EU NIS2 Directive:Expanded incident reporting obligations across European essential and important entities will drive continental replacement of legacy IDS infrastructure.
- Managed Detection Services:Mid-market enterprises lacking SOC staffing are outsourcing alert triage to MSSP partners, shifting vendor economics toward recurring revenue.
Industry Challenges
- Threat Intelligence Analyst Scarcity:Enterprises struggle to hire personnel capable of tuning behavioral baselines and investigating ML-generated alerts.
- Multi-vendor Integration Complexity:SOAR playbook synchronization across disparate EDR, NDR, and SIEM platforms requires costly professional services engagement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Detection and Response Market |
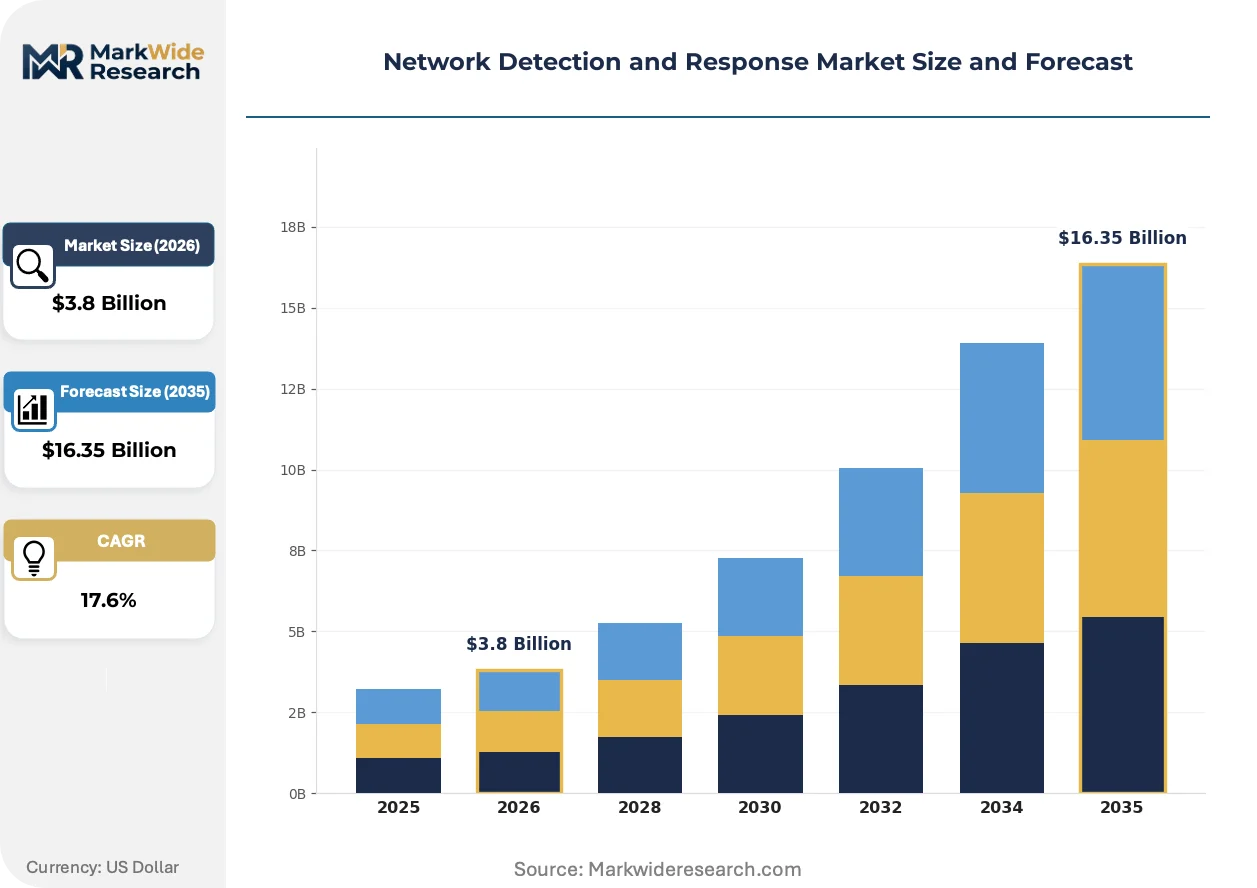
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Sensors, Threat Intelligence Platforms, Response Tools, SIEM Solutions Deployment Model: On-Premises, Cloud, Hybrid, Virtual Appliance Customer Type: Enterprises, SMEs, Government Agencies, Managed Service Providers Technology: Machine Learning, Behavioral Analytics, Signature-Based, Anomaly Detection |
| Companies Covered | Cisco Systems, Fortinet, Vectra AI, Darktrace, ExtraHop Networks, Corelight, Arista Networks, Palo Alto Networks, CrowdStrike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Detection and Response Market Trends and Innovations
Sensor hardware is collapsing into software-defined form factors while regulatory jurisdictions compete to tighten disclosure windows. Vendors are engineering platform architectures that satisfy divergent compliance regimes simultaneously.
Edge-deployed inference engines are miniaturizing detection logic into containerized micro-sensors that execute on standard server infrastructure. Manufacturing plants with distributed OT networks are adopting these lightweight agents to avoid dedicated appliance sprawl. The technology is miniaturizing capital deployment requirements for mid-market buyers previously priced out of hardware-centric solutions.
The EU NIS2 Directive mandates 24-hour incident notification for critical entities and 72-hour reporting for important entities across member states. Product roadmaps must now embed automated regulatory filing workflows that map alerts to jurisdiction-specific disclosure templates. German energy distributors and French healthcare providers are piloting these compliance-integrated consoles ahead of October enforcement deadlines.
Buyer preference is migrating from perpetual appliance licenses toward consumption-based SaaS metering tied to monitored flow volume. Channel partners are restructuring compensation to emphasize recurring attach rates rather than upfront hardware margin. This transition is most advanced in US commercial banking, where CISOs prioritize OPEX flexibility over capital budget allocation.
Network Detection and Response Market Segmentation
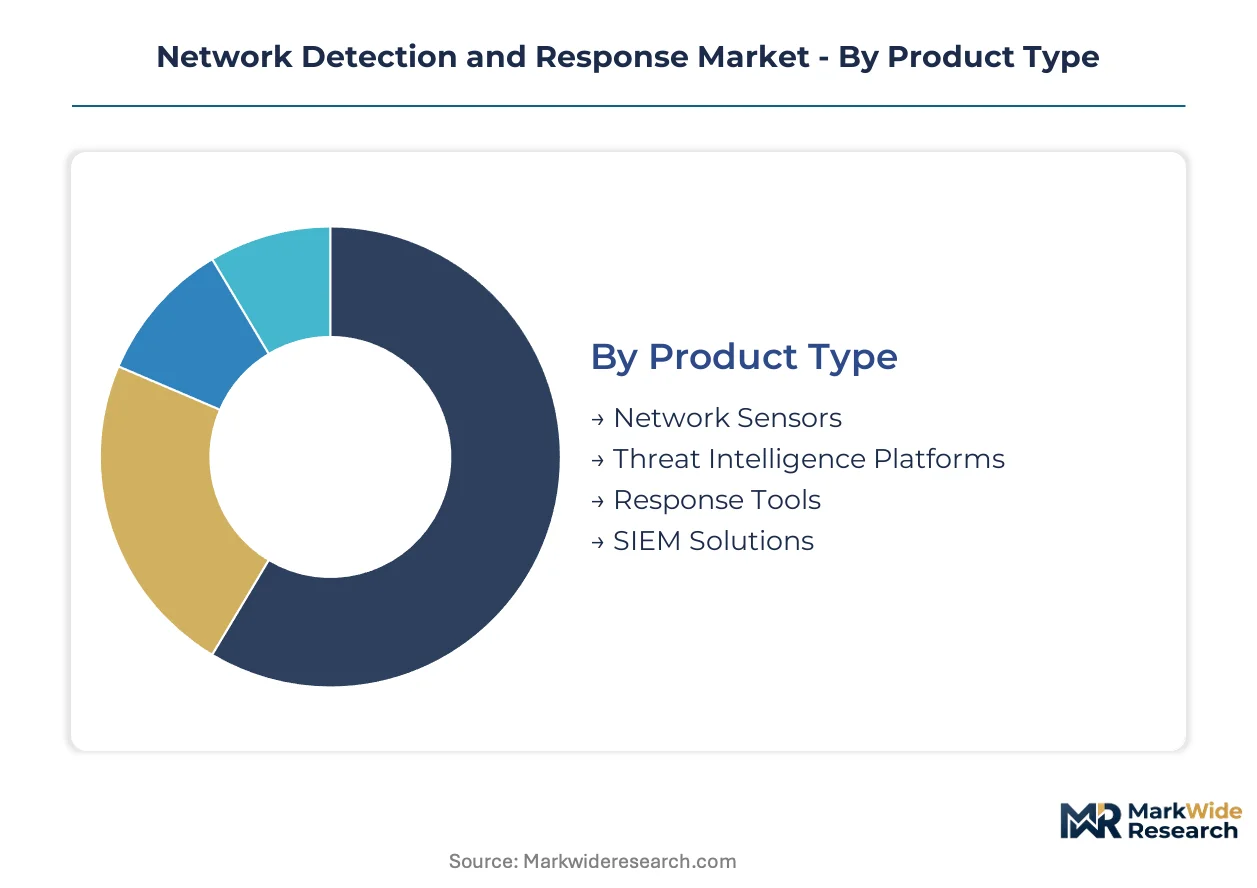
NDR procurement patterns diverge sharply across compliance verticals and infrastructure maturity levels. Buyers select product architectures based on traffic volume requirements, regulatory disclosure mandates, and existing security stack investments.
Product Type:
SEC disclosure timelines and NIST framework controls create divergent functional requirements across product categories.
- Network Sensors:Hardware and software probes inspect east-west and north-south traffic at 10-100 Gbps throughput per node. Financial services firms in the United States deploy these at network borders to satisfy four-day breach disclosure rules. These units handle the majority of throughput; Threat Intelligence Platforms are the fastest mover on share.
- Threat Intelligence Platforms:Aggregated indicator feeds and adversary attribution databases contextualize alerts with TTP mapping. Healthcare systems facing HIPAA enforcement prioritize these for PHI exposure investigations. Demand concentrates in hospital networks where dwell time reduction dominates risk mitigation.
- Response Tools:Automated containment playbooks execute device isolation and traffic blocking.
- SIEM Solutions:Log correlation engines aggregate NDR telemetry with endpoint and identity data.
Sensor hardware absorbs the largest capital allocation; intelligence platforms are climbing the fastest on deployment priority lists.
Deployment Model:
Cost tier stratification separates regulated enterprises from commercial mid-market buyers.
- On-Premises:Dedicated appliance clusters process sensitive traffic within facility boundaries. Electric utilities subject to FERC CIP certification requirements retain these for critical cyber asset segmentation. Procurement concentrates in energy infrastructure where multi-year compliance cycles extend sales timelines.
- Cloud:SaaS consoles aggregate telemetry from distributed sensors without local hardware. Commercial banking CISOs in the United States favor OPEX flexibility over capital budget allocation. This segment is expanding most quickly among buyers prioritizing elastic capacity.
- Hybrid:On-premises sensors feed cloud analytics engines, splitting processing between regulated data zones and scalable compute. Manufacturing plants with IT-OT convergence adopt this for distributed Modbus and DNP3 protocol inspection.
- Virtual Appliance:Software-defined form factors deploy on standard server infrastructure. Mid-market enterprises lacking dedicated security budgets leverage these for containerized micro-sensor deployment.
Hybrid architectures capture the largest project values; cloud deployments are gaining share fastest among new procurement.
Customer Type:
Security operations maturity dictates platform sophistication requirements and service engagement models.
- Enterprises:Global 2000 organizations operate dedicated SOCs with behavioral baseline tuning capabilities. These buyers demand 100 Gbps line-rate inspection with GPU-accelerated classification. Procurement concentrates in United States financial services where SEC mandates drive refresh cycles.
- SMEs:Resource-constrained organizations outsource alert triage to MSSP partners. These buyers prioritize consumption-based metering tied to monitored flow volume. Demand is climbing fastest in commercial segments previously priced out of hardware-centric solutions.
- Government Agencies:Federal and state entities require supply-chain security attestations and domestic component sourcing. FERC CIP standards shape procurement specifications for North American electric infrastructure.
- Managed Service Providers:Channel partners restructure compensation around recurring attach rates rather than upfront hardware margin. These intermediaries serve mid-market buyers lacking internal SOC staffing.
Enterprises deploy the highest sensor density; SMEs are the fastest-expanding customer category on volume.
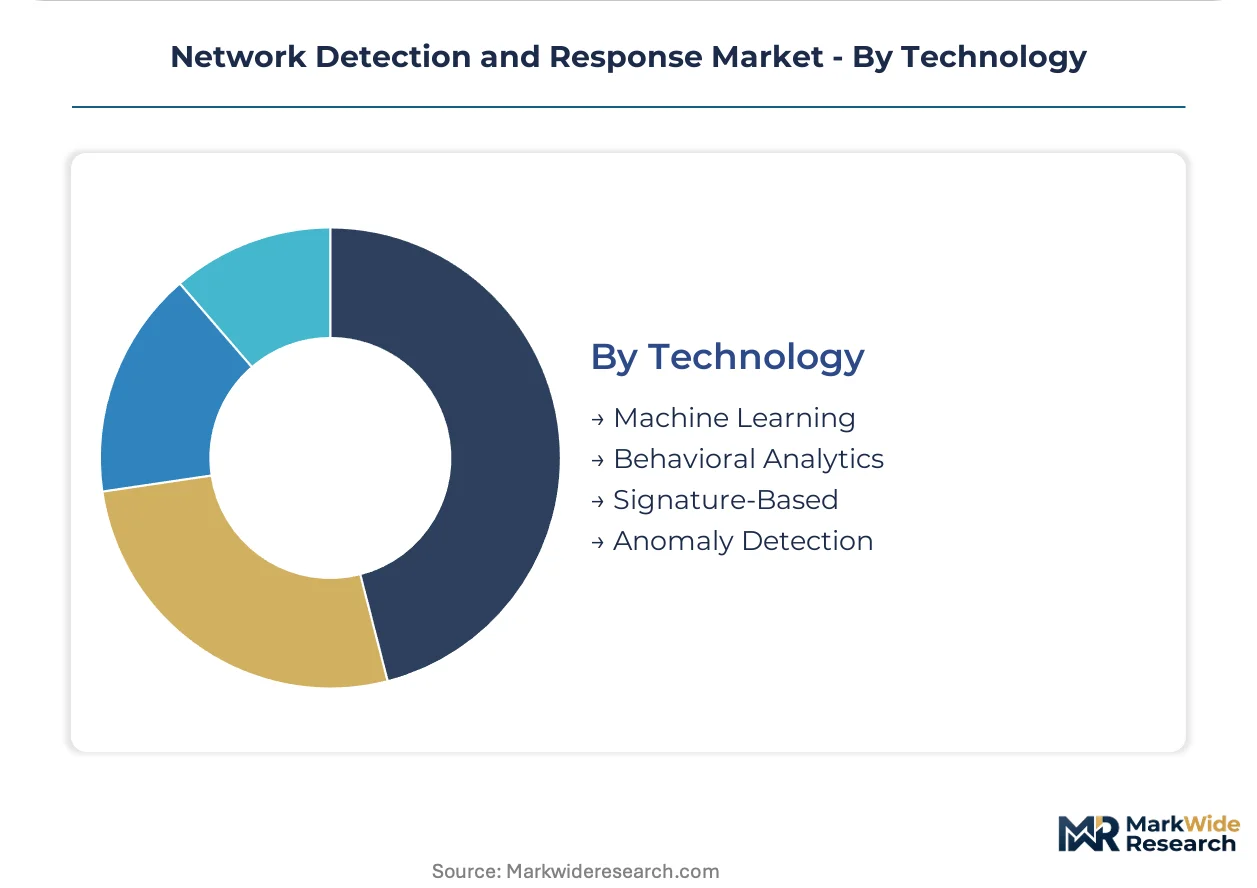
Technology:
Detection methodology maturity separates legacy infrastructure from next-generation procurement.
- Machine Learning:GPU-accelerated inference engines classify threats at line rate without performance degradation. United States financial institutions deploy these for real-time east-west traffic inspection. These systems are gaining deployment priority fastest as zero-day exposure dominates risk profiles.
- Behavioral Analytics:Baseline deviation detection identifies anomalous lateral movement without signature dependencies. Healthcare verticals facing HIPAA enforcement adopt these for PHI network segmentation. Demand concentrates where encrypted traffic obscures payload inspection.
- Signature-Based:Known-indicator matching provides deterministic detection for commodity threats.
- Anomaly Detection:Statistical outlier identification flags deviations from protocol norms.
Behavioral analytics handles the most critical threat categories; machine learning is expanding fastest on R&D investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. United States buyers prioritize real-time behavioral analytics for SEC compliance, while European procurement responds to NIS2 Directive timelines, and Asian deployments emphasize high-throughput sensor density for manufacturing-scale networks.
United States
Financial services firms dominate procurement volumes as SEC cybersecurity disclosure rules mandate four-day breach reporting. NIST framework compliance drives enterprise refresh cycles across Fortune 500 networks. New York and Chicago banking clusters deploy hybrid architectures at scale, retaining on-premises sensors for regulated data while offloading analytics to cloud consoles.
Germany
Industrial manufacturing and automotive sectors anchor demand for IT-OT converged detection platforms. EU NIS2 Directive enforcement from October creates urgency for automated regulatory filing workflows. Bavaria's automotive engineering corridor and North Rhine-Westphalia's chemical complexes pilot compliance-integrated consoles ahead of deadline.
United Kingdom
Financial services and critical national infrastructure operators lead sensor deployment. GDPR-aligned incident response requirements intersect with sector-specific regulations from the Bank of England and Ofgem. London's fintech concentration and Scotland's energy infrastructure drive hybrid procurement favoring OPEX flexibility.
Japan
Manufacturing networks and critical infrastructure operators prioritize high-throughput east-west inspection. METI cybersecurity guidelines shape vendor selection criteria for industrial protocol-aware sensors. Tokyo-Osaka manufacturing corridors deploy containerized micro-sensors for distributed OT environments.
South Korea
Semiconductor and electronics manufacturing drives demand for line-rate GPU-accelerated classification. Domestic smart factory initiatives expand sensor deployment across Busan-Ulsan industrial zones. Seoul Capital Area financial institutions adopt behavioral analytics for encrypted traffic inspection.
Network Detection and Response Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Tier-one vendors leverage routing infrastructure and cloud platform integration to embed detection at scale, while mid-tier players compete on protocol specialization and managed service attach rates. Three archetypes dominate: network infrastructure incumbents extending hardware footprints, pure-play AI-native vendors betting on behavioral differentiation, and platform consolidators bundling NDR with adjacent security stacks. Competitive moves concentrate on strategic partnerships for OT protocol coverage and portfolio diversification into managed detection services.
Among infrastructure-integrated vendors, Cisco Systems and Arista Networks exemplify the hardware-anchored archetype, leveraging installed switching bases for edge sensor placement. Palo Alto Networks occupies a position within the platform consolidation tier, representing vendors bundling NDR with broader security service edge strategies. Vectra AI and Darktrace anchor the AI-native specialist segment, exemplifying pure-play behavioral analytics positioning without legacy appliance dependencies.
| Leading Market Players |
|---|
| Cisco Systems |
| Fortinet |
| Vectra AI |
| Darktrace |
| ExtraHop Networks |
| Corelight |
| Arista Networks |
| Palo Alto Networks |
| CrowdStrike |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for advanced FPGA and SmartNIC components from Taiwan and South Korea foundries compress vendor pricing power while amplifying procurement vulnerability for appliance-centric NDR suppliers. This inventory constraint reshapes contract negotiations as cloud-native competitors exploit software-defined delivery to undercut hardware-anchored rivals on total cost of ownership.
Pricing Analysis
Contract structures bifurcate between long-term enterprise agreements with Fortune 500 financial services firms and consumption-based SaaS metering for mid-market commercial banking. Three-tier pricing stratification across premium GPU-accelerated sensors, standard throughput appliances, and economy virtual deployments reflects certification grade differentiation and volume scale commitments. Cost compression in the economy tier intensifies as containerized micro-sensors displace dedicated hardware. SMEs lacking capital budgets exhibit highest price sensitivity; regulated utilities facing FERC CIP mandates show lowest elasticity due to compliance-driven procurement timelines.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates procurement risk for high-throughput sensor silicon, with advanced FPGA fabrication anchoring in TSMC foundries and SmartNIC assembly clustering in South Korea. NDR hardware draws from specialized semiconductor wafers, GPU accelerator modules, and precision networking components. Single-source dependency on Taiwan-based foundries creates tariff exposure and geopolitical disruption risk. Distribution runs through direct enterprise sales teams for large deployments and MSSP channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network Detection and Response sits in early-cycle expansion as SEC cybersecurity disclosure mandates force four-day breach reporting adoption across US financial services, accelerating behavioral analytics procurement ahead of regulatory deadlines.
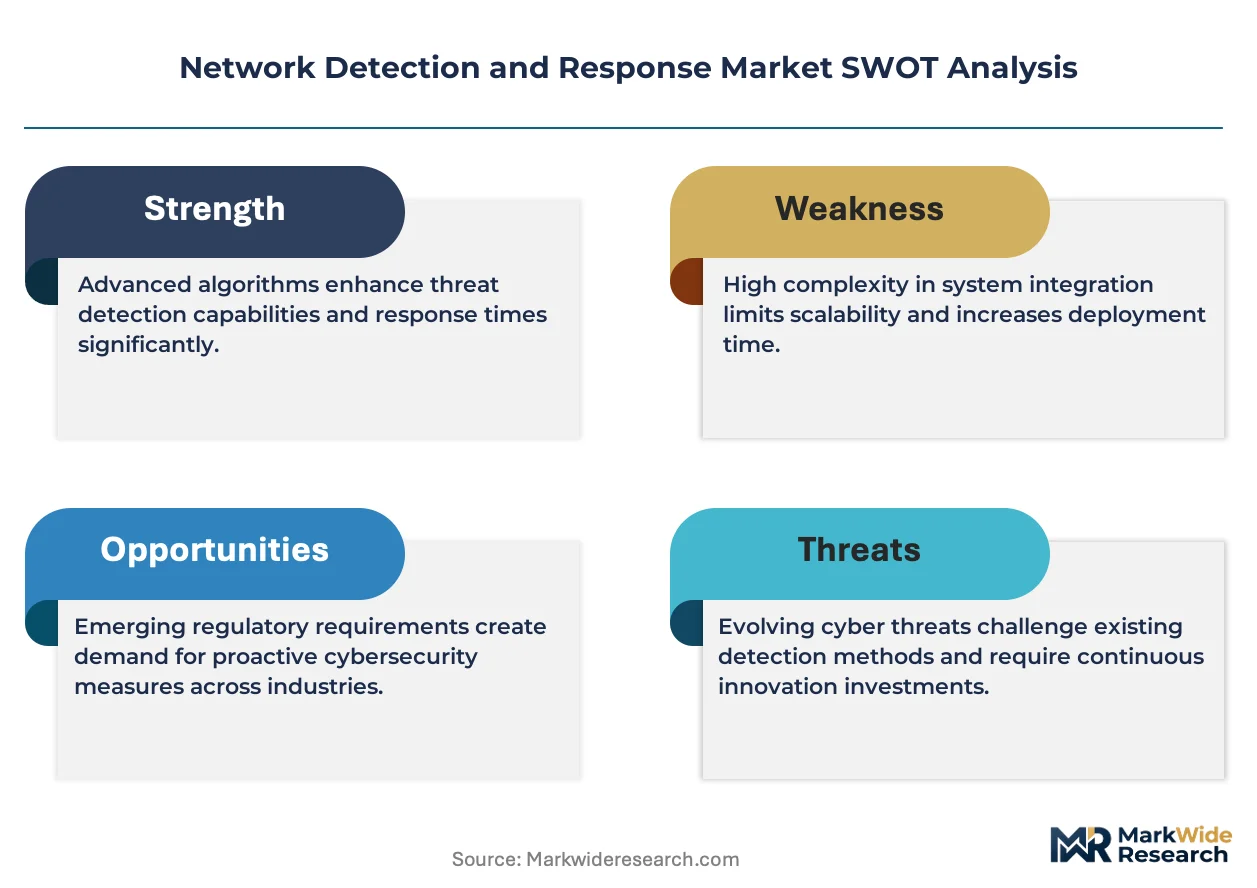
For Market Incumbents: Fortify hybrid architecture roadmaps by deepening backward integration into GPU-accelerated inference chip design, reducing Taiwan foundry dependency. Anchor cloud console development to capture OPEX-flexible commercial banking demand migrating from perpetual licenses. Defend against AI-native pure-plays by embedding compliance-automated reporting workflows that map directly to SEC and EU NIS2 disclosure templates. For New Entrants and Emerging Players: Differentiate on OT protocol specialization for manufacturing IT-OT convergence, where Modbus and DNP3 traffic inspection remains underserved by infrastructure incumbents. Target European energy distributors facing October NIS2 enforcement deadlines with compliance-integrated consoles. Pursue managed detection services attach rates with MSSP channel partners serving SOC-staffing-constrained mid-market enterprises. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-tails play because cybersecurity disclosure mandates across SEC, EU NIS2, and sector-specific frameworks create durable procurement pull-through regardless of macroeconomic cycles. Acquisition candidates with behavioral analytics IP and OT protocol libraries command strategic premium. Watch GPU supply chain normalization and post-quantum cipher adoption as inflection signals for hardware versus software-defined competitive balance.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling NDR with SASE architectures captures hybrid deployment budgets at Palo Alto Networks scale. |
| Strategic Partnership | OT protocol alliances with Schneider Electric or Siemens unlock manufacturing plant sensor deployment. |
| Acquisition of Specialist Firm | Behavioral analytics IP from AI-native vendors accelerates cloud console differentiation for incumbents. |
| Geographic Expansion | EU NIS2 compliance engineering targets German energy distributors ahead of enforcement deadlines. |
| Product Launch | Containerized micro-sensors reduce capital thresholds for mid-market buyers previously priced out. |
Research Methodology
Initial hypotheses were tested against primary input from CISOs at Fortune 500 financial services firms, SOC directors at healthcare systems, OT security engineers at manufacturing plants, and MSSP channel partners, then refined through secondary validation. Primary intelligence combined structured interviews with procurement officers and integration specialists across deployment model segments. Secondary sources encompassed SEC cybersecurity disclosure filings, NIST framework documentation, EU NIS2 directive texts, and hyperscaler security capex disclosures. Bottom-up sensor deployment estimates triangulated against top-down market sizing from vendor revenue disclosures.
Variance decomposition across the projection horizon isolates segment-specific growth contributions from product type, deployment model, customer maturity, and technology methodology dimensions. Modeled CAGRs derive from elasticity-adjusted adoption curves tied to regulatory enforcement timelines and infrastructure refresh cycles. Industry-specific forecast inputs include FERC CIP certification pipeline data for electric utilities and HIPAA audit penalty trends for healthcare verticals.
Material uncertainties — Taiwan foundry disruption, post-quantum cipher adoption degrading payload inspection, and SEC disclosure timeline revisions — sit outside the modeled envelope. Forecasts reflect assumptions about behavioral analytics substitution rates and hybrid architecture preference stability. Practitioners should keep alternative scenarios live as encryption standards and geopolitical supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
North America Cyber Security Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Latin America IoT Security Market
Cybersecurity
Cognitive Security Market
Cybersecurity
Latin America Cybersecurity Market
Cybersecurity
Qatar Cybersecurity Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
Global Ddos Protection Market
Cybersecurity
North America Software Defined Perimeter Market
Cybersecurity
Container-based Firewall Market
Cybersecurity
Canada Ransomware Protection Market
Cybersecurity
Cloud-Based IDS IPS Market
Cybersecurity
South Korea Ransomware Protection Market
Cybersecurity
E-Mail Security Market
Cybersecurity
Saas-Based IT Security Market