
 Latin America IoT Security Market | 2026-2036
Latin America IoT Security Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America IoT Security Market Foresight
Silicon-based secure element modules is hardening as the default trust anchor in Latin American IoT hardware, displacing discrete software-only credentialing across cost-sensitive device classes. Palo Alto Networks leverages cloud-native segmentation architectures to capture expanding utility and agriculture deployments in Brazil and Mexico. Fortinet anchors its regional presence through localized threat intelligence hubs that feed edge-security appliances. Cisco Systems competes by bundling network security with switching infrastructure in smart city projects across Colombia and Chile.
Latin America IoT Security encompasses cryptographic protocols, hardware trust anchors, and network monitoring systems engineered to protect connected device ecosystems against unauthorized access, data exfiltration, and operational disruption. Elliptic curve cryptography and hardware security module integration form the technical backbone, with firmware signing and over-the-air update verification serving as mandatory functional parameters for critical infrastructure protection. Cloud-Based deployment leads in revenue contribution as Brazilian and Mexican enterprises prioritize scalable subscription models over capital-intensive on-premise infrastructure. Endpoint Security captures concentrated margin pools where semiconductor-integrated trust zones command premium positioning against software-only alternatives. Smart Agriculture applications expand fastest among end-use categories as precision farming networks proliferate across Argentina and Brazil.
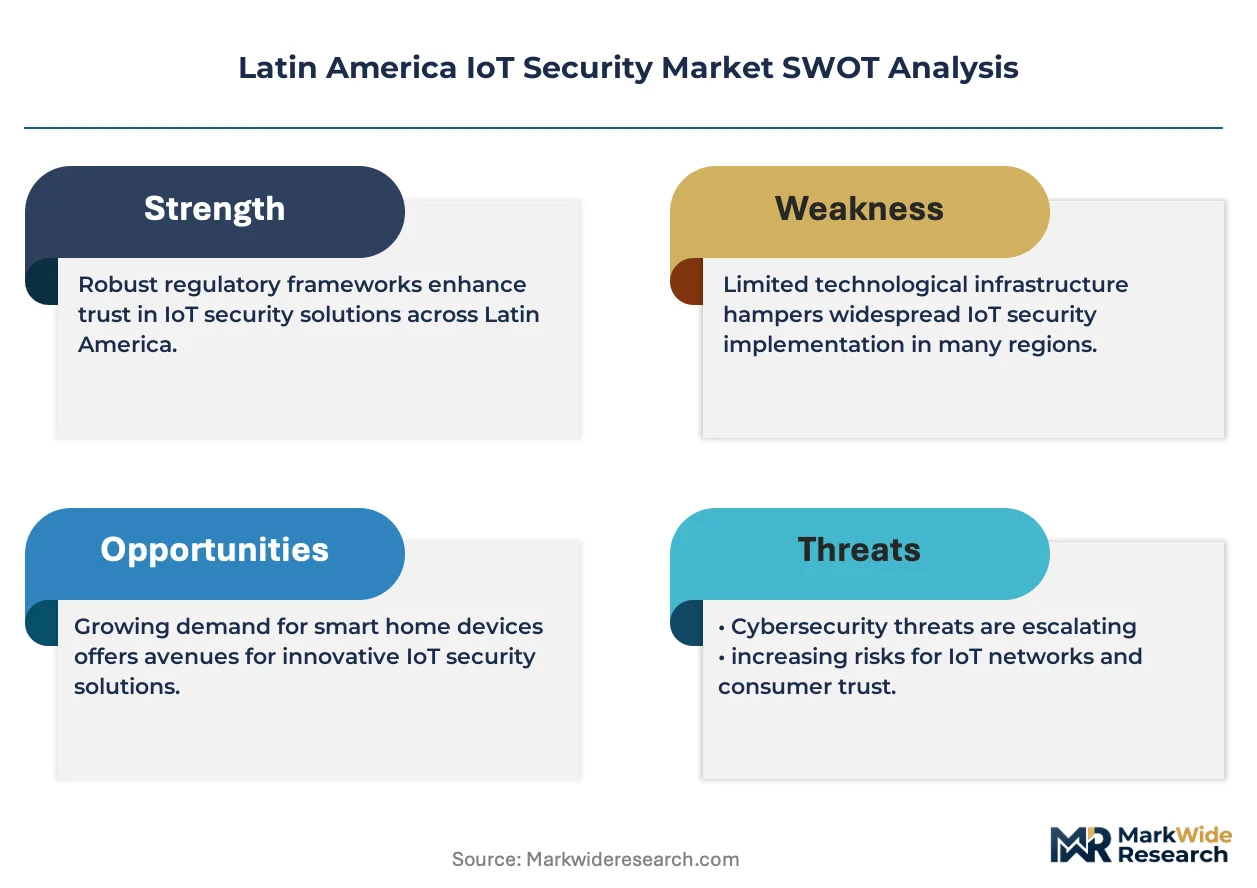
ANATEL in Brazil mandates device-level cybersecurity certification for IoT products entering critical infrastructure supply chains, directly elevating demand for pre-certified hardware modules. Mexico's IFETEL aligns spectrum licensing with minimum encryption standards, while Colombia's ICT Ministry enforces data localization provisions that shape cloud security architecture decisions. Stakeholders must weigh the trade-off between standardized certification costs and fragmented national compliance requirements as regulatory divergence deepens across the region.
Market Dynamics
ANATEL's device-level cybersecurity certification mandate for Brazilian critical infrastructure is compressing procurement timelines and forcing hardware security module integration into cost-sensitive IoT device classes previously served by software-only credentialing.
Growth Catalysts
- Smart Agriculture Networks:Precision farming deployments across Argentina and Brazil require hardware trust anchors for sensor-to-cloud data integrity, accelerating semiconductor-integrated security module adoption in cost-constrained equipment categories.
- ANATEL Certification Mandate:Brazil's telecommunications regulator now requires pre-certified security modules for IoT products entering energy and water utility supply chains, eliminating software-only alternatives from qualified vendor lists.
- Cloud-Native Segmentation:Brazilian and Mexican mid-sized utilities prioritize scalable subscription security models over capital-intensive on-premise infrastructure, expanding addressable market for managed security service providers.
Market Restraints
- Hardware Cost Premiums:Silicon-based secure elements add 15-30% to bill-of-materials for agricultural sensors and utility meters, compressing margins for device manufacturers serving price-sensitive Latin American markets.
- Regulatory Fragmentation:Divergent national certification requirements across Brazil, Mexico, Colombia, and Chile force vendors to maintain multiple hardware SKUs and compliance documentation sets, elevating operational overhead.
- Technical Limitation:Legacy SCADA systems in Colombian and Chilean utility infrastructure lack native cryptographic acceleration, requiring costly gateway retrofits to achieve ANATEL-equivalent security postures.
Strategic Opportunities
- Colombian Data Localization:The ICT Ministry's data residency provisions create captive demand for locally-hosted cloud security architectures, favoring regional service providers over global hyperscalers in smart city procurements.
- Edge-AI Security Convergence:Integration of hardware security modules with on-device machine learning inference engines opens premium positioning for agricultural drones and autonomous farming equipment in Brazil's precision agriculture expansion.
- Mid-Market Utility Gap:Mexican and Colombian utilities between 50,000-200,000 endpoints remain underserved by enterprise-focused vendors, creating white space for purpose-built, subscription-priced security platforms.
Industry Challenges
- Embedded Cryptography Talent Scarcity:Firmware signing and secure boot implementation expertise concentrates in São Paulo and Mexico City, forcing regional device manufacturers to outsource critical security architecture or accept extended development cycles.
- Multi-Jurisdiction Certification Overlap:Simultaneous pursuit of ANATEL, IFETEL, and ICT Ministry approvals creates timeline conflicts and documentation redundancy, delaying product launches by 6-12 months for hardware vendors.
- Legacy Integration Complexity:Brownfield utility deployments require security gateways that translate between modern TLS 1.3 and proprietary protocols from 1990s-era SCADA systems, elevating deployment risk and service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America IoT Security Market |
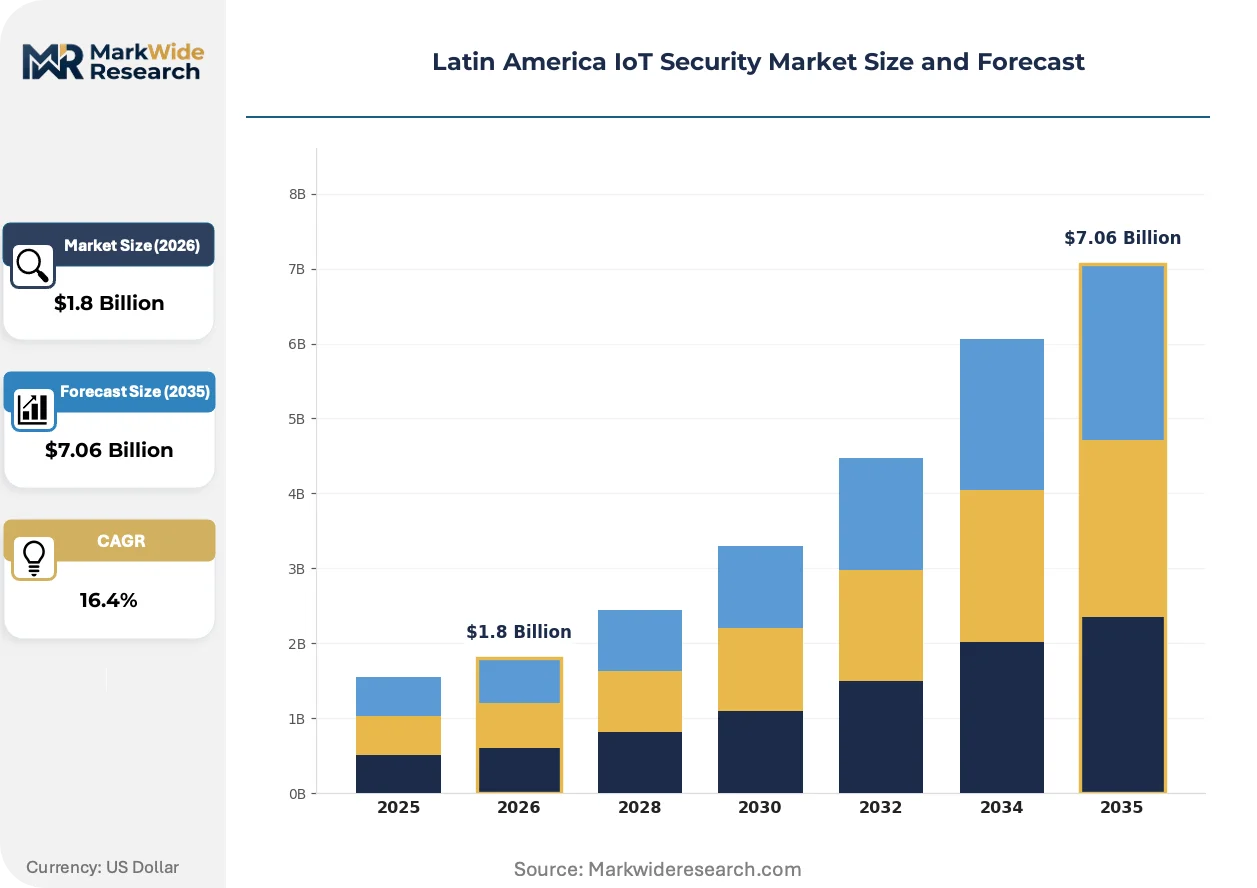
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution: Network Security, Endpoint Security, Application Security, Data Security End User: Healthcare, Manufacturing, Transportation, Smart Home Application: Smart Grids, Wearable Devices, Industrial Automation, Smart Agriculture |
| Companies Covered | Symantec Corporation, Palo Alto Networks Inc, IBM Corporation, Intel Corporation, Fortinet Inc, FireEye Inc, Cisco Systems Inc, Infineon Technologies, Trend Micro Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America IoT Security Market Shifts & Advancements
Hardware security modules are migrating from discrete components to integrated trust zones within agricultural and utility system-on-chips, compressing the attack surface while reducing unit economics for high-volume device deployments.
Post-quantum cryptographic algorithms are electrifying firmware update verification pipelines across Brazilian smart agriculture networks. Equipment manufacturers embedding lattice-based signatures into sensor firmware are securing long-duration field assets against harvest-now-decrypt-later threats. This transition is compressing competitive differentiation toward semiconductor vendors with certified post-quantum implementations.
Mexico's IFETEL has aligned spectrum licensing with minimum AES-256 encryption standards for industrial IoT bands, forcing legacy device obsolescence in manufacturing and logistics applications. Equipment refresh cycles are compressing from seven-year to four-year intervals as certificate-based authentication becomes a licensing precondition. Mid-sized Mexican manufacturers are responding by consolidating vendor relationships to reduce compliance documentation burden.
Brazilian utilities are unbundling security operations from capital equipment procurement, subscribing to managed detection and response services rather than building in-house security operations centers. Channel relationships are pivoting toward telecommunications carriers with existing fiber-to-the-utility relationships. This behavioral shift is most visible in São Paulo state's water distribution operators, where three of five major utilities have outsourced endpoint monitoring to carrier-affiliated security practices since ANATEL's certification mandate took effect.
Latin America IoT Security Market Segmentation
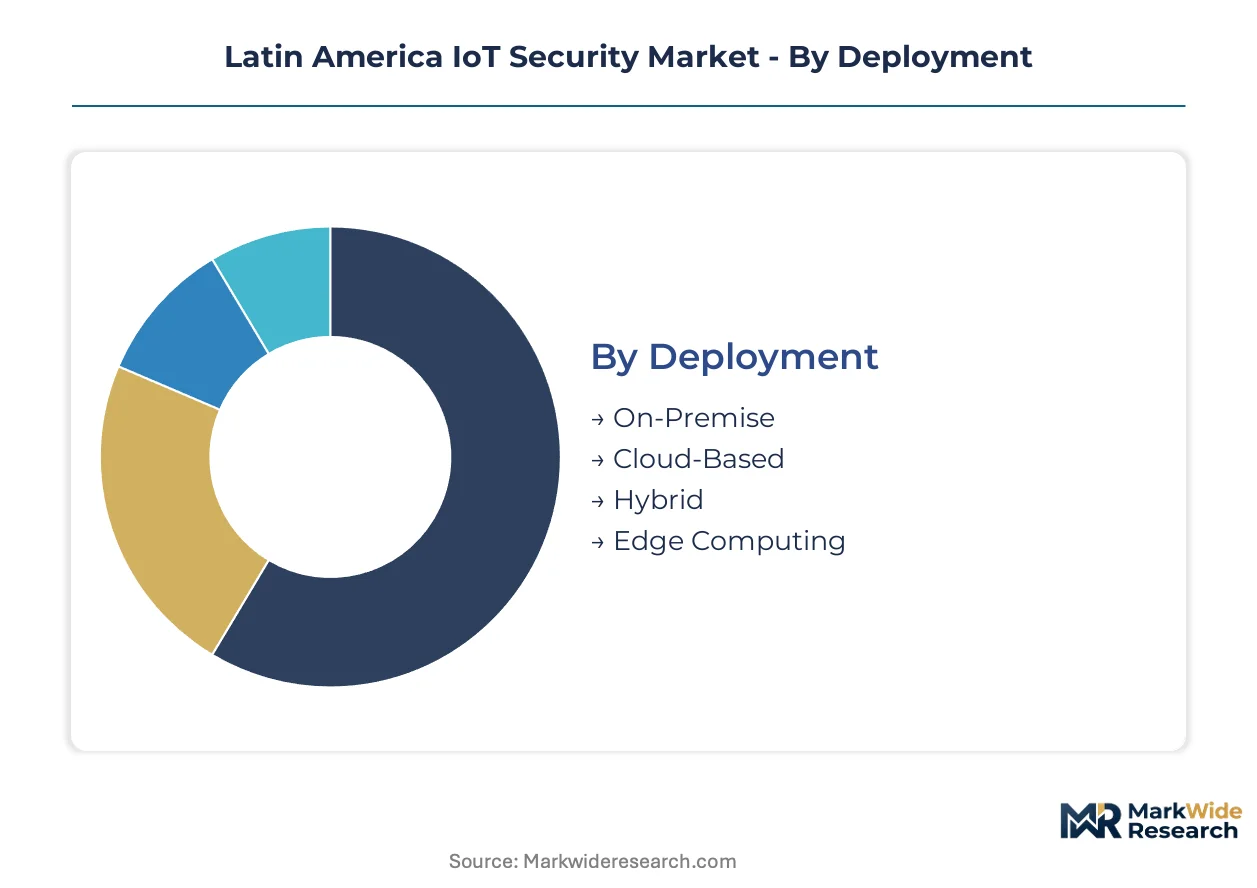
Segmentation in Latin American IoT security reveals how certification requirements fragment procurement strategies across deployment modes and end-use applications. ANATEL's hardware mandates reshape which segments absorb compliance costs versus which escape regulatory scope entirely.
Deployment:
Certification burdens concentrate heaviest in cloud and hybrid architectures where data residency rules intersect with device-level mandates, while edge deployments face lighter procedural overhead in certain national frameworks.
- Cloud-Based:Scalable subscription models host security operations for Brazilian and Mexican mid-sized utilities, with data localization provisions in Colombia forcing regional provider selection over global hyperscalers. São Paulo water operators exemplify this shift toward carrier-affiliated managed detection services.
- On-Premise:Capital-intensive infrastructure persists among Chilean and Colombian utilities with legacy SCADA investments, though ANATEL-equivalent security postures demand costly gateway retrofits for cryptographic acceleration.
- Hybrid:Split architectures balance regulatory compliance with operational flexibility, appealing to Argentine agricultural networks requiring local data processing for latency-sensitive precision farming controls.
- Edge Computing:On-device inference engines integrate hardware security modules for autonomous Brazilian agricultural drones, compressing attack surfaces without cloud dependency.
Cloud-Based sits at the top of the volume ranking, with Edge Computing climbing the fastest.
Solution:
Cost tier differentiation separates premium hardware-integrated offerings from software-only alternatives squeezed by regulatory displacement.
- Endpoint Security:Semiconductor-integrated trust zones command premium positioning against software credentialing, with smart agriculture sensor manufacturers absorbing 15-30% bill-of-materials increases for secure element modules.
- Network Security:Cloud-native segmentation architectures capture expanding utility deployments across Brazil and Mexico, bundling with existing fiber infrastructure relationships.
- Application Security:Firmware signing and over-the-air verification pipelines protect Brazilian smart agriculture networks against harvest-now-decrypt-later threats through post-quantum lattice-based signatures.
- Data Security:Encryption standards align with IFETEL's AES-256 mandates for Mexican industrial IoT spectrum licensing, forcing seven-year to four-year equipment refresh compression.
Endpoint Security leads revenue contribution, with Application Security expanding most quickly.
End User:
Application-specific regulatory exposure determines which verticals absorb mandatory hardware certification versus discretionary security investment.
- Smart Agriculture:Precision farming networks proliferate across Argentina and Brazil, requiring sensor-to-cloud integrity through hardware trust anchors in cost-constrained equipment categories previously served by software-only solutions.
- Manufacturing:Mexican mid-sized manufacturers consolidate vendor relationships to reduce IFETEL compliance documentation burden, responding to certificate-based authentication becoming a spectrum licensing precondition.
- Healthcare:Connected medical devices face emerging cybersecurity requirements from national health regulators, though certification frameworks remain less mature than ANATEL's telecommunications mandates.
- Smart Home:Consumer IoT segments escape critical infrastructure certification scope, maintaining software-based credentialing despite growing awareness of firmware vulnerability risks.
Smart Agriculture dominates end-use demand, with Manufacturing gaining share fastest.
Application:
Geographic concentration of infrastructure investment shapes which applications drive hardware security module adoption versus software alternatives.
- Smart Agriculture:Argentine and Brazilian precision farming deployments accelerate semiconductor-integrated security module adoption, with ANATEL-certified hardware eliminating software-only alternatives from qualified vendor lists for agricultural sensor manufacturers.
- Smart Grids:Brazilian and Mexican utilities between 50,000-200,000 endpoints remain underserved by enterprise-focused vendors, creating white space for subscription-priced security platforms tailored to mid-market procurement constraints.
- Industrial Automation:Colombian and Chilean brownfield deployments require security gateways translating between modern TLS 1.3 and proprietary 1990s-era SCADA protocols, elevating deployment risk and service costs.
- Wearable Devices:Fitness and health monitoring applications operate outside critical infrastructure certification requirements, preserving cost-sensitive software-only security architectures.
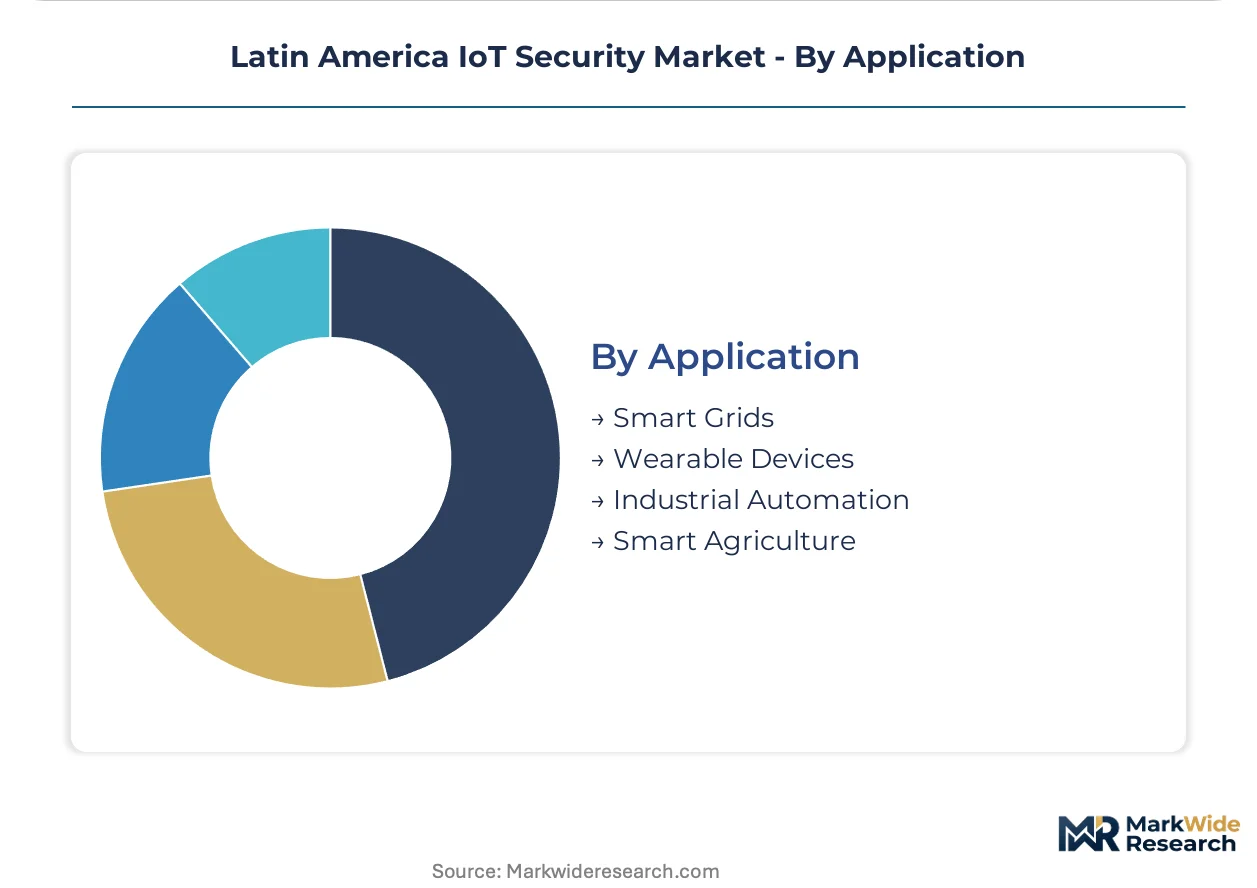
Smart Agriculture holds the steepest expansion trajectory, with Smart Grids representing the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's precision agriculture corridor anchors Latin American demand for hardware-integrated IoT security modules. Brazilian regulatory mandates reshape procurement patterns across the region's utility and farming sectors.
Brazil
Smart agriculture sensor manufacturers absorb 15-30% hardware cost premiums for ANATEL-certified secure elements. The telecommunications regulator mandates device-level cybersecurity certification for critical infrastructure supply chains. São Paulo water utilities outsource endpoint monitoring to carrier-affiliated security practices, compressing procurement timelines.
Mexico
Mid-sized utilities between 50,000-200,000 endpoints prioritize cloud-native segmentation architectures over capital-intensive infrastructure. IFETEL aligns spectrum licensing with minimum AES-256 encryption standards, forcing equipment refresh cycles from seven to four years. Mexico City manufacturers consolidate vendor relationships to reduce compliance documentation burden.
Argentina
Precision farming networks proliferate across the Pampas agricultural belt, requiring sensor-to-cloud integrity through hardware trust anchors. The national communications regulator enforces emerging IoT security guidelines for rural connectivity deployments. Buenos Aires agtech clusters drive semiconductor-integrated security module adoption in cost-constrained equipment categories.
Colombia
The ICT Ministry's data localization provisions create captive demand for regionally-hosted cloud security architectures. Smart city projects in Bogotá bundle network security with switching infrastructure, favoring regional service providers over global hyperscalers. Brownfield utility deployments require security gateways translating modern TLS 1.3 with proprietary SCADA protocols.
Chile
Legacy SCADA systems in Santiago's utility infrastructure lack native cryptographic acceleration, demanding costly gateway retrofits. The national telecommunications regulator advances cybersecurity frameworks for critical infrastructure protection. Antofagasta mining operations drive edge-computing security adoption for autonomous equipment in remote extraction sites.
Latin America IoT Security Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors navigate fragmented national certification requirements. The vendor base splits between global cybersecurity platforms, semiconductor-integrated security specialists, and telecommunications carriers with fiber infrastructure relationships. Three archetypes occupy distinct positions: cloud-native segmentation providers, hardware trust anchor manufacturers, and carrier-affiliated managed security services. M&A activity and localized threat intelligence hub establishment represent the dominant competitive moves as vendors seek ANATEL pre-certification advantages.
Within the cloud-native segmentation tier, Palo Alto Networks and Cisco Systems exemplify platform providers capturing Brazilian and Mexican utility deployments. Fortinet anchors the edge-security appliance segment through regional threat intelligence infrastructure. Semiconductor-integrated security modules concentrate around Infineon Technologies and Intel Corporation, representing hardware trust anchor manufacturers absorbing device-level certification mandates. These named entities occupy positions that reflect broader competitive dynamics without specifying individual strategic actions or market shares.
| Leading Market Players |
|---|
| Symantec Corporation |
| Palo Alto Networks Inc |
| IBM Corporation |
| Intel Corporation |
| Fortinet Inc |
| FireEye Inc |
| Cisco Systems Inc |
| Infineon Technologies |
| Trend Micro Inc |
| Others |
Supply & Pricing Matrix
Silicon-integrated secure element migration from discrete components to system-on-chip architectures compresses unit economics for high-volume agricultural sensor deployments while concentrating procurement leverage among semiconductor vendors with ANATEL pre-certification. This production-method transition simultaneously elevates hardware cost premiums for device manufacturers and reshapes supplier power dynamics across Brazilian and Mexican utility supply chains.
Pricing Analysis
Input-cost pass-through from secure element module suppliers runs through subscription-based managed detection services rather than capital equipment sales, with Brazilian water utilities absorbing recurring fees bundled into carrier fiber relationships. Price differentiation separates ANATEL-certified hardware tiers from software-only alternatives displaced from qualified vendor lists, with agricultural sensor manufacturers facing the steepest margin compression. Pricing pressure stems from 15-30% bill-of-materials increases for silicon-based trust anchors in cost-constrained equipment categories. Mid-sized Mexican utilities demonstrate highest price sensitivity through preference for scalable SaaS models, while Chilean utilities with legacy SCADA investments prove least sensitive due to gateway retrofit necessity.
Supply Chain Analysis
Certification gating through ANATEL, IFETEL, and Colombia's ICT Ministry forces hardware vendors to maintain multiple country-specific SKUs and documentation sets, fragmenting supplier relationships across national compliance boundaries. Geographic supply concentration centers on Taiwan and South Korea for semiconductor fabrication, with Germany and the USA contributing hardware security module design expertise. Raw material dependencies include silicon wafers, cryptographic co-processor IP, and secure element packaging substrates. Supply chain risk manifests as single-source vulnerability for ANATEL-certified module suppliers with pre-approved designations. Distribution runs through telecommunications carriers with existing fiber-to-utility infrastructure relationships, particularly in São Paulo state's water distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America IoT Security operates as a regulatory compounder where ANATEL's device-level cybersecurity certification mandate for Brazilian critical infrastructure continuously elevates baseline demand for pre-certified hardware modules. This regulatory milestone compresses procurement timelines while eliminating software-only alternatives from qualified vendor lists.
For Market Incumbents: Deploy localized threat intelligence hub establishment as the primary lever to anchor regional presence against emerging cloud-native segmentation providers. Fortify channel control through telecommunications carrier partnerships that bundle security operations with existing fiber infrastructure relationships. Counter margin pressure from hardware cost premiums by consolidating vendor relationships to reduce multi-jurisdiction certification documentation burden.
For New Entrants and Emerging Players: Launch via subscription-priced security platforms targeting the mid-market utility gap in Mexico and Colombia, where 50,000-200,000 endpoint operators remain underserved by enterprise-focused vendors. Penetrate Argentine precision farming networks through edge-AI security convergence for autonomous agricultural equipment. Exploit white space in post-quantum cryptographic firmware verification for long-duration field assets against harvest-now-decrypt-later threats.
For Investors and Strategic Acquirers: Valuations sit cheapest among semiconductor-integrated security specialists with ANATEL pre-certification advantages and established regional threat intelligence infrastructure. Long-term viability over the next decade hinges on positioning for post-quantum cryptographic transition and edge-AI security module integration. Monitor IFETEL spectrum licensing alignment with encryption standards as the critical inflection signal for Mexican industrial IoT equipment refresh acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Pre-Certification Investment | Hardware vendors securing ANATEL approval eliminate software-only competitors from Brazilian utility qualified vendor lists. |
| Carrier-Affiliated Security Partnership | Telecommunications carriers bundle managed detection services with fiber infrastructure to capture São Paulo water utility outsourcing. |
| Post-Quantum Cryptographic Integration | Semiconductor vendors embedding lattice-based signatures secure long-duration agricultural sensor deployments against future decryption threats. |
| Regional Threat Intelligence Hub Establishment | Edge-security appliance manufacturers anchor market presence through localized threat feeds serving Colombian and Chilean utilities. |
| Mid-Market Utility Platform Launch | Purpose-built subscription security platforms address procurement constraints for Mexican and Colombian utilities between 50,000-200,000 endpoints. |
Research Methodology
Bottom-up smart agriculture and utility deployment modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with IoT device manufacturers, telecommunications carrier security practice leads, agricultural sensor procurement officers, and national regulatory affairs specialists combined with secondary validation from ANATEL certification databases, IFETEL spectrum licensing records, and ICT Ministry data localization rulings. Trade flow analysis of secure element module imports and hyperscaler capex disclosures in Brazil and Mexico provided additional triangulation anchors.
Input-output matrices mapping hardware security module unit economics to subscription service revenue pools structured the projection framework across deployment modes, solution types, and end-use applications. Segmentation dimensions modeled include cloud versus edge deployment architecture, endpoint versus network versus application security solutions, and smart agriculture versus smart grid versus industrial automation end uses. CAGRs derived from regression analysis of historical certification mandate impacts on procurement volume shifts, with industry-specific inputs incorporating post-quantum cryptographic transition timelines and legacy SCADA gateway retrofit penetration curves.
Several conditions sit outside the modeled scope, including hypothetical harmonization of national certification requirements across Brazil, Mexico, Colombia, and Chile, and catastrophic supply disruption scenarios for Taiwanese semiconductor fabrication capacity. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hardware cost curve trajectories. A model refresh is warranted upon material change in ANATEL certification scope expansion or IFETEL encryption standard elevation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
DNS Security Market
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
Data-Centric Security Market
Cybersecurity
Secure Socket Layer (SSL) Certification Market
Cybersecurity
Artificial Intelligence in Cybersecurity Market
Cybersecurity
India Cybersecurity Market
Cybersecurity
South Africa Cybersecurity Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
Dark Web Intelligence Market
Cybersecurity
Global Sensitive Data Discovery Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Global Cloud Security Posture Management Market
Cybersecurity
Endpoint Security Market
Cybersecurity
Indonesia Cybersecurity Market
Cybersecurity
Global Sandboxing Market
Cybersecurity
Cyber Warfare Market