
 Big Data Analytics in BFSI Market | 2026-2036
Big Data Analytics in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics in BFSI Market Analysis
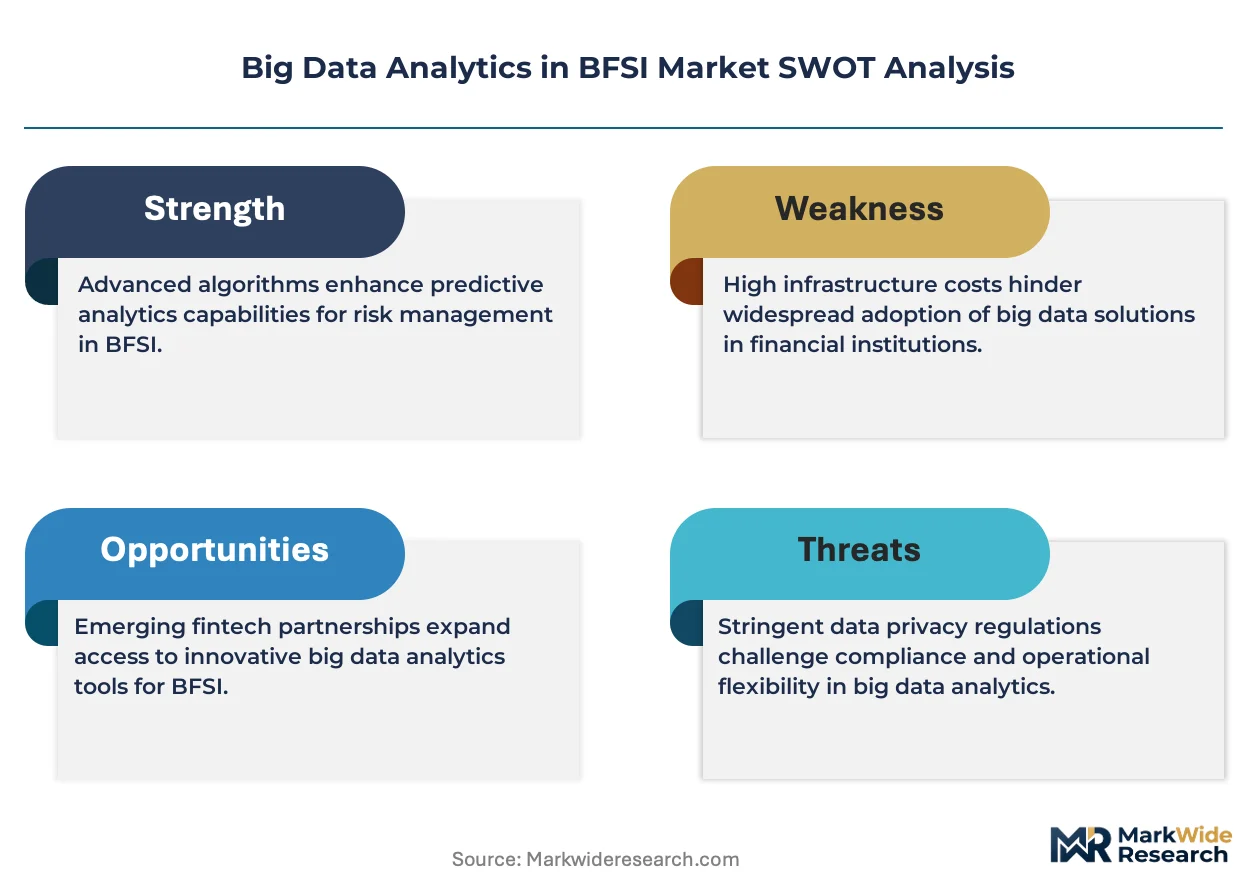
Subscription-based managed services and pay-as-you-consume cloud licensing is fragmenting traditional capital-intensive procurement models for analytics infrastructure. Microsoft Corporation leverages its Azure cloud ecosystem to anchor enterprise deployments across tier-one banks. IBM Corporation sustains competitive relevance through specialized mainframe-to-cloud migration services for legacy core banking systems. Palantir Technologies Inc. differentiates via deep integration with government-style security protocols that financial regulators increasingly favor.
Big Data Analytics in BFSI encompasses the collection, processing, and algorithmic analysis of structured and unstructured financial datasets at petabyte scale, employing distributed computing frameworks, machine learning pipelines, and real-time stream processing architectures to generate actionable intelligence. Its primary commercial purpose centers on optimizing decision velocity across credit origination, portfolio management, and operational risk mitigation. Fraud Detection applications dominate current deployment value as institutions face escalating synthetic identity schemes and authorized push payment fraud. Cloud-Based delivery models represent the fastest-expanding structural category, though On-Premises installations persist where data residency requirements under national banking charters impose hard jurisdictional boundaries. Managed Services margins concentrate in regulatory compliance verticals where specialist providers embed proprietary rule libraries for Basel III, FATCA, and evolving ESG disclosure standards.
The US Federal Reserve's enhanced cyber risk management expectations and the SEC's climate disclosure rules shape demand for auditable data lineage and governance tooling. European operators navigate ECB guidance on ICT risk concentration alongside DORA's operational resilience mandates, while China's NMPA-aligned financial regulators enforce localized data storage for consumer credit analytics. Stakeholders must monitor divergence between prescriptive sectoral rules and technology-neutral principles-based frameworks when selecting scalable architecture investments.
Market Dynamics
Real-time stream processing architectures are collapsing the latency gap between transactional data capture and actionable intelligence, forcing banks to rebuild core infrastructure around sub-second decision pipelines rather than batch-oriented legacy warehouses.
Growth Catalysts
- PSD2 open banking mandates:European regulators compel institutions to expose customer data via standardized APIs, accelerating demand for modern data governance platforms that secure consent-managed access.
- Synthetic identity fraud proliferation:Criminal networks exploit fragmented identity verification across digital channels, pulling investment into behavioral biometrics and graph analytics for entity resolution.
- Cloud-native core banking migrations:Tier-one institutions in Singapore and the UAE are retiring mainframe dependencies, creating procurement windows for distributed analytics infrastructure.
Market Restraints
- Specialized talent scarcity:Shortages of engineers fluent in both Apache Spark optimization and Basel III risk-weighting calculations constrain deployment velocity at midsize institutions.
- Cross-border data friction:China's NMPA-aligned financial regulators enforce strict data localization for consumer credit models, fragmenting cloud architecture standardization.
- Legacy system entanglement:COBOL-based core banking platforms at established institutions resist API-native integration, inflating migration costs and timeline risk.
Strategic Opportunities
- Embedded finance analytics:Non-bank platforms in Brazil and Mexico require white-labeled risk scoring, opening distribution channels beyond traditional financial institutions.
- Climate risk quantification:The SEC's disclosure rules and the EU's CSRD create compliance-driven demand for geospatial and alternative data fusion in portfolio stress testing.
- Federated learning architectures:Privacy-preserving machine learning enables consortium models across competing institutions without raw data pooling, addressing regulatory concerns about concentration risk.
Industry Challenges
- Explainability mandates:ECB guidance on model risk management requires documented algorithmic decision pathways, complicating black-box neural network deployments in credit underwriting.
- Data lineage auditability:FATCA and evolving ESG disclosure standards demand granular provenance tracking across multi-hop ETL pipelines, stretching metadata management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics in BFSI Market |
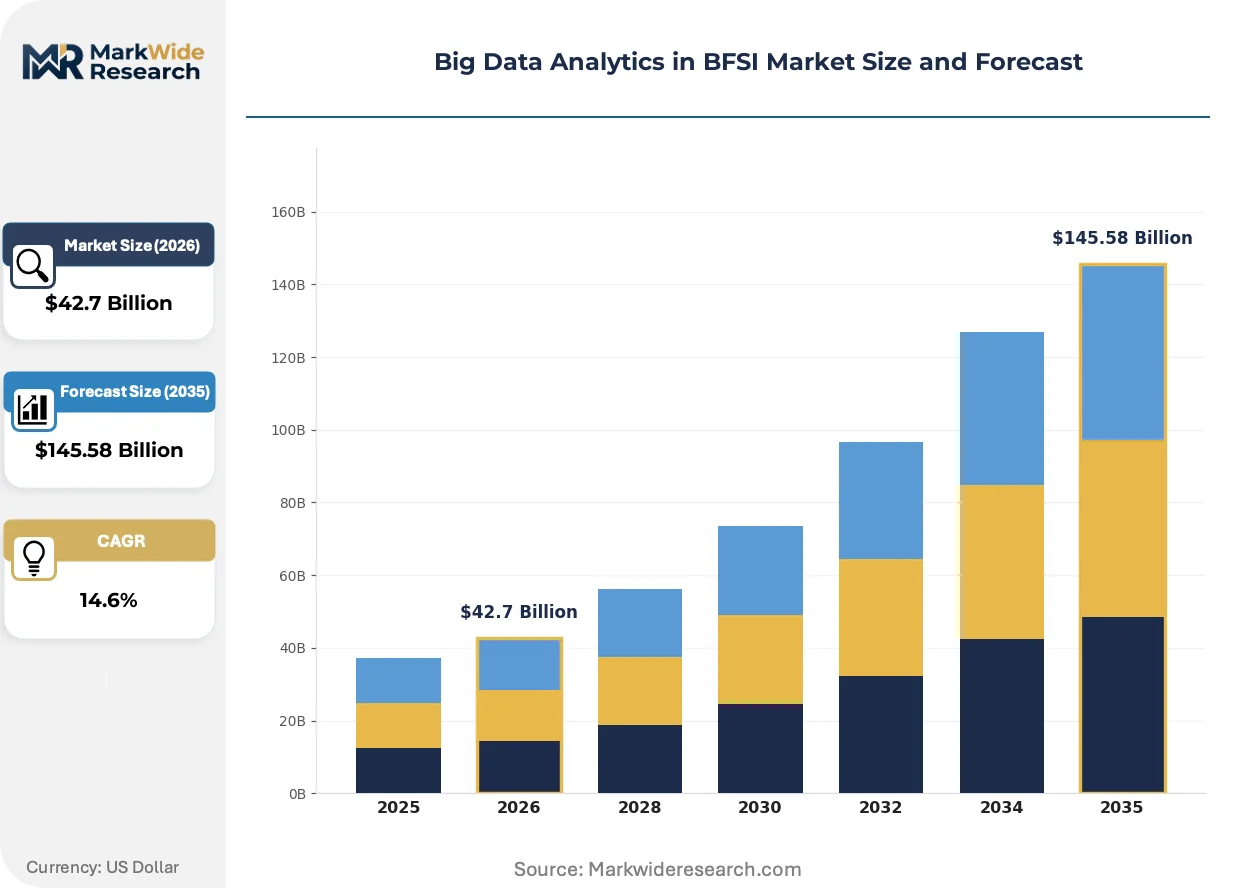
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $145.58 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Analytics, Regulatory Compliance Delivery Model: On-Premises, Cloud-Based, Hybrid Model, Managed Services End User: Banks, Insurance Companies, Investment Firms, Credit Unions Service Type: Consulting, Data Mining, Predictive Analytics, Reporting Services |
| Companies Covered | SAS Institute Inc., Dell Technologies Inc., Microsoft Corporation, Tata Consultancy Services Limited, Salesforce Inc., IBM Corporation, Accenture plc, Palantir Technologies Inc., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics in BFSI Market Emerging Trajectories
Convergence of generative AI with structured financial datasets is rewriting the economics of insight production, compressing analyst workflow cycles from days to minutes while raising new governance imperatives.
Apache Flink and Kafka Streams are collapsing the boundary between operational and analytical data processing in retail banking deployments. Tier-one institutions now embed complex event processing directly into payment authorization flows, eliminating the historical ETL latency that separated transaction systems from business intelligence. This architecture shift is collapsing the traditional data warehouse market as banks bypass centralized repositories for federated query layers.
The EU's Digital Operational Resilience Act imposes strict ICT risk concentration limits on critical third-party providers, forcing institutions to diversify cloud vendor relationships. Financial entities must now maintain exit strategies and interoperability standards for core analytics platforms. European operators are responding by negotiating multi-cloud contracts with explicit data portability clauses and redundant processing capabilities across jurisdictions.
Buyers are consolidating vendor relationships around integrated platform contracts that bundle compute, governance, and industry-specific model libraries. The previous pattern of best-of-breed point solutions is giving way to strategic commitments with cloud hyperscalers offering financial services accelerators. This concentration is most visible in the United States, where procurement teams prioritize FedRAMP-authorized environments and pre-built regulatory reporting modules over specialized analytics tools.
Big Data Analytics in BFSI Market Segmentation
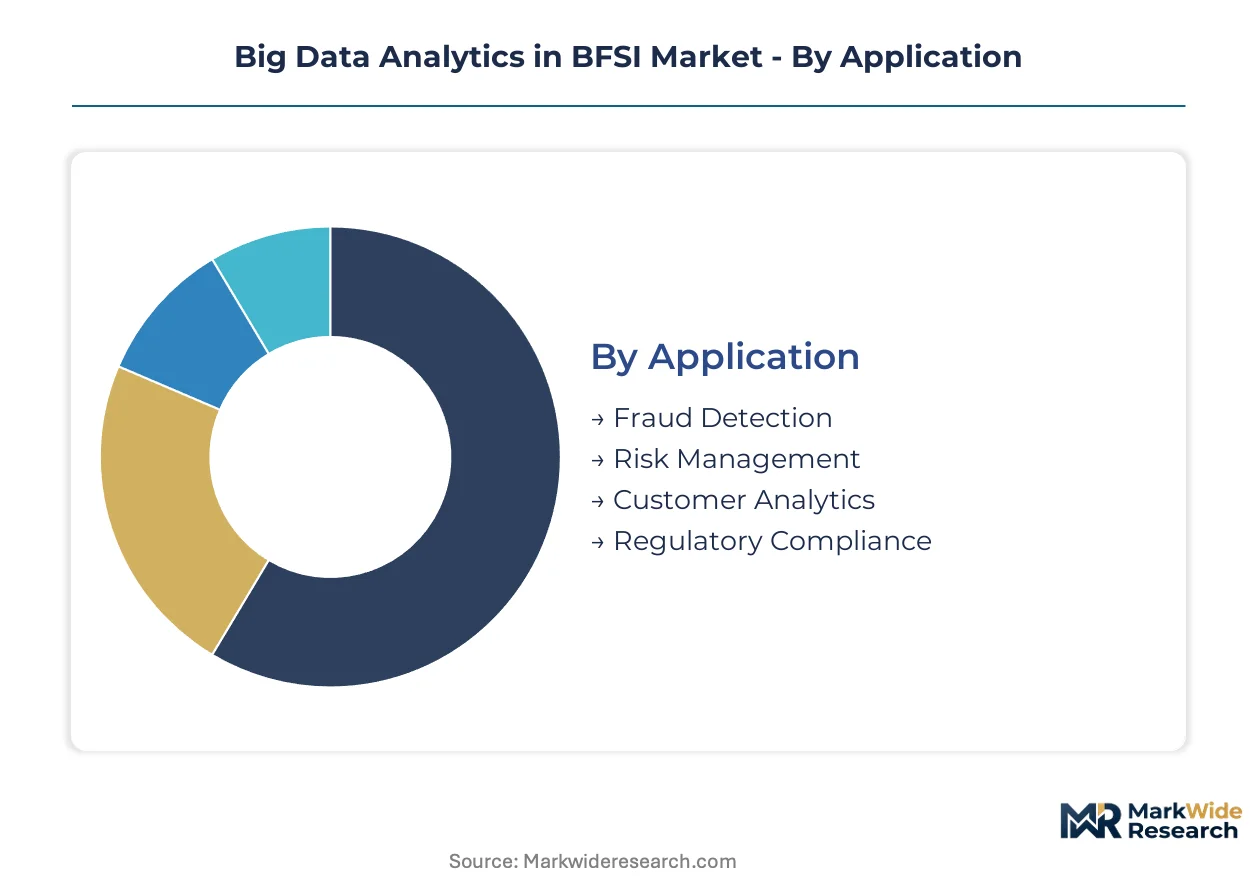
Financial institutions configure analytics procurement around deployment velocity and regulatory exposure. Segmentation reveals where capital cycles compress versus extend, guiding vendor positioning and architecture investments.
Application:
Fraud Detection platforms refresh on 18-24 month cycles as attack vectors mutate, while Regulatory Compliance systems endure 5-7 year amortization horizons under certification lock-in.
- Fraud Detection:Real-time graph analytics and behavioral biometrics process authorization streams at sub-100 millisecond latency. US retail banks drive procurement volume as synthetic identity schemes exploit digital onboarding gaps.
- Risk Management:Portfolio stress-testing engines fuse traditional credit data with alternative signals including supply chain telemetry and geospatial climate exposure. Basel III internal ratings-based approaches concentrate demand among European systemically important banks.
- Customer Analytics:Next-best-action engines unify transaction history with external data enrichment.
- Regulatory Compliance:Immutable audit trails and automated rule libraries address FATCA, CRS, and emerging ESG disclosure mandates.
Fraud Detection dominates installed base. Regulatory Compliance is where expansion concentrates as climate disclosure rules harden.
Delivery Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure flexibility, with hybrid architectures capturing institutions navigating data residency constraints.
- Cloud-Based:Serverless analytics and auto-scaling compute pools eliminate provisioning overhead for variable workloads. Singapore and UAE tier-one banks are retiring mainframe dependencies through cloud-native core migrations.
- Managed Services:Subscription models embed proprietary compliance rule libraries and dedicated security operations centers. Specialist providers capture margin in Basel III and FATCA verticals where regulatory expertise commands premium pricing.
- On-Premises:Bare-metal deployments satisfy national banking charter data localization requirements.
- Hybrid Model:Sensitive data remains on-premises while compute bursts to public cloud.
On-Premises retains installed base dominance in jurisdictions with strict data residency. Cloud-Based delivery is climbing the fastest as institutions exit mainframe technical debt.
End User:
Customer sophistication and procurement scale create distinct capability tiers across institutional types.
- Banks:Universal banks deploy unified data lakes spanning retail, commercial, and investment banking divisions. Real-time transaction monitoring and open banking API governance absorb the largest analytics capital allocations.
- Insurance Companies:Property-casualty carriers fuse IoT sensor streams with traditional actuarial models for dynamic pricing.
- Investment Firms:Quantitative strategies demand tick-by-tick market data processing at microsecond precision.
- Credit Unions:Cooperative structures prioritize member-facing analytics over back-office automation.
Banks anchor volume demand. Insurance Companies represent the steepest expansion trajectory as telematics and parametric products proliferate.
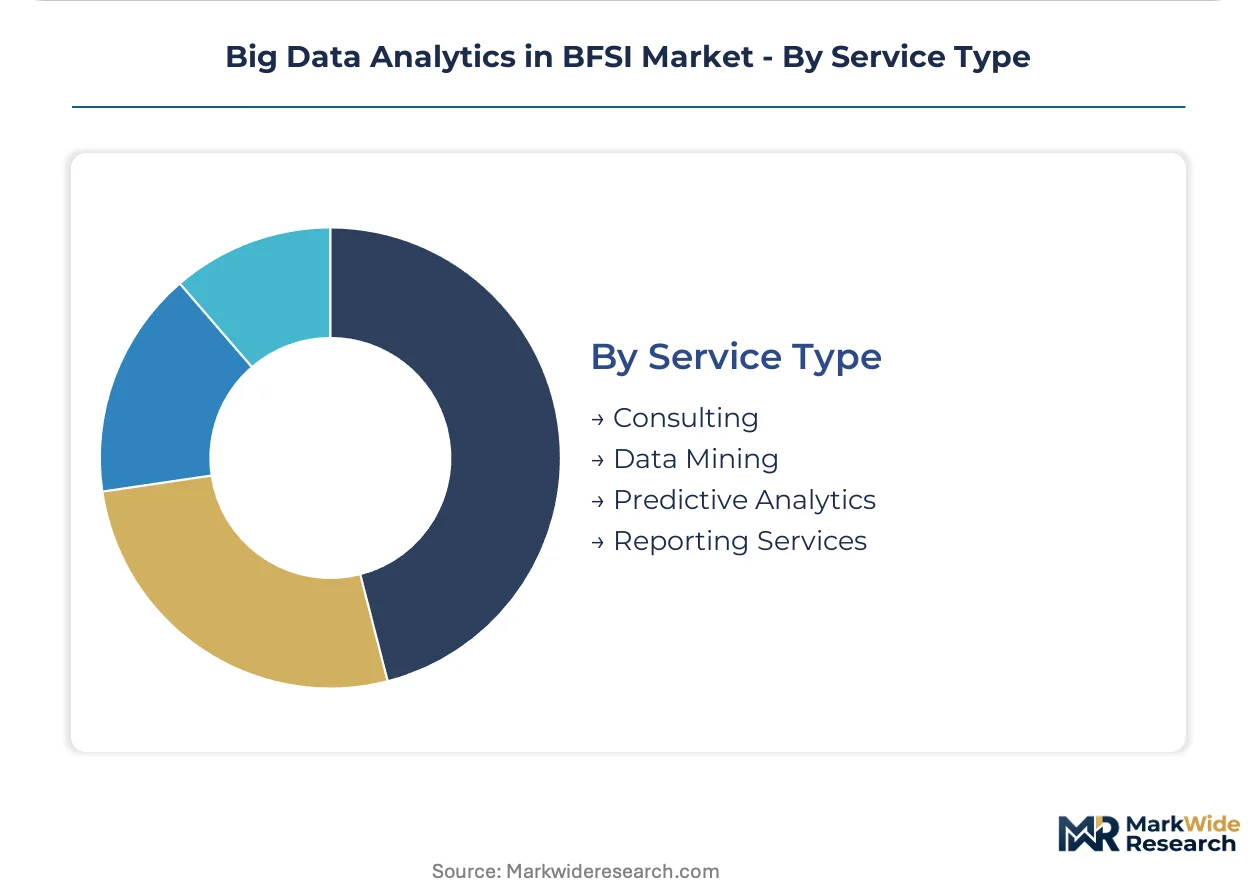
Service Type:
Margin concentration follows intellectual property intensity, with proprietary algorithms commanding premium positioning over commoditized infrastructure.
- Predictive Analytics:Machine learning pipelines for credit origination and churn prediction require continuous model retraining. Federated learning architectures enable consortium deployments across competing institutions without raw data pooling.
- Consulting:Architecture design and change management for cloud-native migrations.
- Data Mining:Entity resolution and anomaly detection across unstructured document corpora.
- Reporting Services:Automated generation of regulatory submissions and executive dashboards.
Reporting Services dominates legacy installed base. Predictive Analytics is gaining share fastest as explainable AI requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in financial analytics software and services, while importing specialized hardware infrastructure from Asian manufacturing hubs. European institutions export regulatory compliance expertise and governance frameworks. Data localization mandates in China and India constrain cross-border service flows.
United States
US retail banks drive procurement volume for real-time fraud detection and AML compliance systems. SEC climate disclosure rules and Federal Reserve cyber risk expectations shape vendor selection criteria. New York and San Francisco financial technology clusters anchor cloud-native analytics deployments at tier-one institutions.
Germany
German systemically important banks concentrate demand for Basel III internal ratings-based stress testing engines. ECB guidance on model risk management and ICT risk concentration imposes strict auditability requirements. Frankfurt's banking district hosts specialized compliance technology providers serving EU-wide institutions.
Singapore
Singaporean tier-one banks are retiring mainframe dependencies through cloud-native core migrations, creating procurement windows for distributed analytics infrastructure. Monetary Authority of Singapore digital banking licensing frameworks accelerate data architecture modernization. The city-state's fintech hub attracts regional analytics service delivery centers.
China
Chinese state-owned banks deploy petabyte-scale consumer credit analytics under NMPA-aligned data localization mandates. Strict data residency requirements for consumer credit models fragment cloud architecture standardization. Shanghai and Beijing financial districts concentrate domestic analytics platform development.
United Kingdom
UK institutions navigate post-Brexit divergence from EU regulatory frameworks while maintaining equivalence for cross-border data flows. Bank of England operational resilience expectations and FCA consumer duty rules drive governance tooling investment. London's financial services cluster sustains demand for open banking API infrastructure.
Big Data Analytics in BFSI Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform contracts that bundle compute, governance, and regulatory model libraries. Tier-one cloud hyperscalers capture procurement volume through FedRAMP-authorized environments and pre-built compliance modules. Specialist providers maintain positioning in Basel III and FATCA verticals where regulatory expertise commands premium pricing. Dominant competitive moves include strategic partnerships for multi-cloud interoperability and portfolio diversification into embedded finance analytics.
Within the cloud-native platform tier, Microsoft Corporation and IBM Corporation exemplify divergent positioning strategies. Microsoft leverages its Azure ecosystem to anchor enterprise deployments through serverless analytics and auto-scaling compute pools. IBM sustains relevance through specialized mainframe-to-cloud migration services addressing legacy technical debt at established institutions. Palantir Technologies Inc. occupies a distinct position integrating government-style security protocols that financial regulators increasingly favor for sensitive data environments.
| Leading Market Players |
|---|
| SAS Institute Inc. |
| Dell Technologies Inc. |
| Microsoft Corporation |
| Tata Consultancy Services Limited |
| Salesforce Inc. |
| IBM Corporation |
| Accenture plc |
| Palantir Technologies Inc. |
| Oracle Corporation |
| Others |
Supply Flow & Price Mechanics
Hyperscaler cloud infrastructure concentration in the United States and Western Europe anchors margin pools downstream in regulatory compliance verticals and managed services tiers. Tier-one banks negotiate multi-year enterprise agreements with FedRAMP-authorized providers, while midsize institutions face pricing power asymmetry in specialized talent markets.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing stratified across premium, standard, and economy tiers. Price differentiation hinges on certification level—FedRAMP High versus Moderate authorizations—and volume scale of petabyte-scale data ingestion. Cost compression in the standard tier is intensifying because Apache Spark optimization talent scarcity inflates implementation overhead. Regional banks and credit unions exhibit highest price sensitivity; tier-one universal banks absorb premium pricing for embedded compliance rule libraries.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware infrastructure procurement. Cloud compute capacity concentrates in the United States, Ireland, and Singapore; specialized GPU clusters for machine learning training draw from Taiwan and South Korea manufacturing. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and precision cooling systems. Distribution runs through direct enterprise sales teams and systems integrator partnerships rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time stream processing architectures are collapsing decision latency from days to milliseconds, while PSD2 open banking mandates and SEC climate disclosure rules force infrastructure replacement cycles. This dual inflection compresses procurement timelines and expands addressable spend.
For Market Incumbents: Entrench through backward integration into proprietary compliance rule libraries for Basel III and FATCA verticals where regulatory expertise commands pricing power. Acquire specialized graph analytics boutiques to counter Palantir Technologies Inc. positioning in government-style security protocols. Lock tier-one banks into multi-cloud interoperability contracts before DORA-mandated vendor diversification accelerates.
For New Entrants and Emerging Players: Latin American embedded finance markets—particularly Brazil and Mexico—offer white-label risk scoring white-space with minimal incumbent saturation. Target credit unions and regional banks underserved by hyperscaler direct sales teams. Lead with federated learning architectures that address ECB model risk management explainability mandates without requiring raw data pooling infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed managed services providers holding Basel III and ESG disclosure certification lock-in. Five-to-ten year viability hinges on cloud-native migration service capabilities rather than legacy on-premises maintenance revenue. Watch for Singapore and UAE tier-one bank mainframe retirement announcements as inflection indicators for distributed analytics infrastructure procurement windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud Interoperability Partnership | DORA compliance in the European Union forces redundant processing capabilities across Azure, AWS, and GCP environments. |
| Federated Learning Consortium Launch | Privacy-preserving machine learning addresses ECB concentration risk concerns while enabling competing bank collaboration. |
| Mainframe-to-Cloud Migration Service | Singapore and UAE tier-one institutions are retiring COBOL dependencies, creating procurement windows for specialized integrators. |
| Climate Risk Quantification Platform | SEC disclosure rules and EU CSRD mandate geospatial data fusion for portfolio stress testing across asset classes. |
| Regulatory Compliance Rule Library Acquisition | Proprietary Basel III and FATCA content locks in 5-7 year amortization horizons with certification-dependent switching costs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief data officers at tier-one banks, cloud platform engineers at hyperscalers, regulatory compliance officers at systemically important institutions, and procurement leads at credit unions. Secondary validation drew from SEC 10-K filings, ECB guidance documents, MAS digital banking licensing frameworks, and FedRAMP authorization databases. Bottom-up deployment sizing across application segments was triangulated against top-down IT spend benchmarks from financial services sector aggregates.
Calibration against historical cloud migration timelines and regulatory implementation cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include application type, delivery model, end-user institution category, and service type complexity tier. CAGRs were derived from slope analysis of adoption curve inflection points, with specific inputs from open banking API penetration rates and synthetic identity fraud incident reporting trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or unexpected regulatory harmonization would shift outcomes. Macroeconomic contraction in capital markets, accelerated data localization mandates, or breakthroughs in quantum-resistant encryption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Analytics Software Market
Analytics
Data Preparation Market
Analytics
Customer Data Platform Market
Analytics
Document Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Weather Data Services Market
Analytics
SME Big Data Market
Analytics
Spend Analytics Software Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Global Operational Analytics Market
Analytics
Global Recommendation Engine Market
Analytics
North America Location Analytics Market
Analytics
Global Analytics Market
Analytics
Imagery Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Automated Analytics Market