
 Chile Cybersecurity Market | 2026-2036
Chile Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Cybersecurity Market Outlook
Platform bundling is consolidating buyer choice across the Chile Cybersecurity Market, as enterprises favor integrated suites over point solutions. Cisco Systems leverages its networking-hardware installed base to anchor security subscription revenue. Palo Alto Networks competes through cloud-native platform unification. Fortinet sustains market presence via operating-system consolidation across firewall, SD-WAN, and zero-trust access.
Cybersecurity encompasses technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with functional parameters including mean-time-to-detect below 200 milliseconds and encryption standards of AES-256 or higher. Its primary commercial purpose is preserving confidentiality, integrity, and availability of information assets against unauthorized access or disruption. Network Security occupies the mature margin pool among solution types, while Cloud-Based deployment models represent the fastest-growing structural segment as Chilean enterprises migrate critical workloads. Managed Security services command premium pricing in the finance and government end-user segments where regulatory audit frequency intensifies.
Chile's data protection authority and central bank cybersecurity norms shape vendor certification requirements and product standards for financial sector procurement. The country's national computer security incident response team coordinates breach disclosure protocols that influence enterprise security spending thresholds. Stakeholders must monitor evolving regulatory alignment between Chilean frameworks and international standards such as ISO 27001 to anticipate compliance-driven procurement cycles.
Market Dynamics
Platform consolidation is compressing vendor margins across Chile's cybersecurity sector as enterprises abandon point solutions for integrated suites. Santiago's financial district and Valparaíso's port corridor concentrate procurement authority, amplifying buyer leverage in contract negotiations.
Growth Catalysts
- Zero-trust architecture mandates:Chile's central bank cybersecurity norms now require financial institutions to demonstrate continuous verification protocols, accelerating enterprise procurement cycles.
- Data protection law enforcement:The country's data protection authority has intensified audit frequency, compelling organizations to upgrade compliance infrastructure.
- Cloud workload migration:Chilean enterprises moving critical systems to cloud environments are expanding security spending on cloud-native protection layers.
Market Restraints
- Certified talent scarcity:Santiago's cybersecurity labor pool remains insufficient for ISO 27001 implementation demands, inflating specialist compensation.
- Import dependency:Hardware security modules and advanced firewall appliances concentrate sourcing from US and European suppliers, exposing buyers to currency volatility.
- Legacy system integration friction:Decades-old core banking infrastructure in Chilean financial institutions resists API-based security overlay deployment.
Strategic Opportunities
- Managed security services expansion:Regulatory audit intensity in Chile's government sector creates demand for outsourced continuous monitoring.
- AI-driven threat detection convergence:Machine learning behavioral analytics combined with SIEM platforms offers differentiation for domestic service providers.
- Valparaíso logistics corridor penetration:Port operators and shipping companies remain undersecured relative to financial services, presenting greenfield deployment potential.
Industry Challenges
- Multi-framework compliance burden:Chilean enterprises must simultaneously satisfy national data protection law, central bank cybersecurity norms, and ISO 27001 alignment, stretching governance resources.
- Skills pipeline gaps:University cybersecurity programs in Santiago and Concepción graduate insufficient practitioners for SOC analyst and incident response roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Cybersecurity Market |
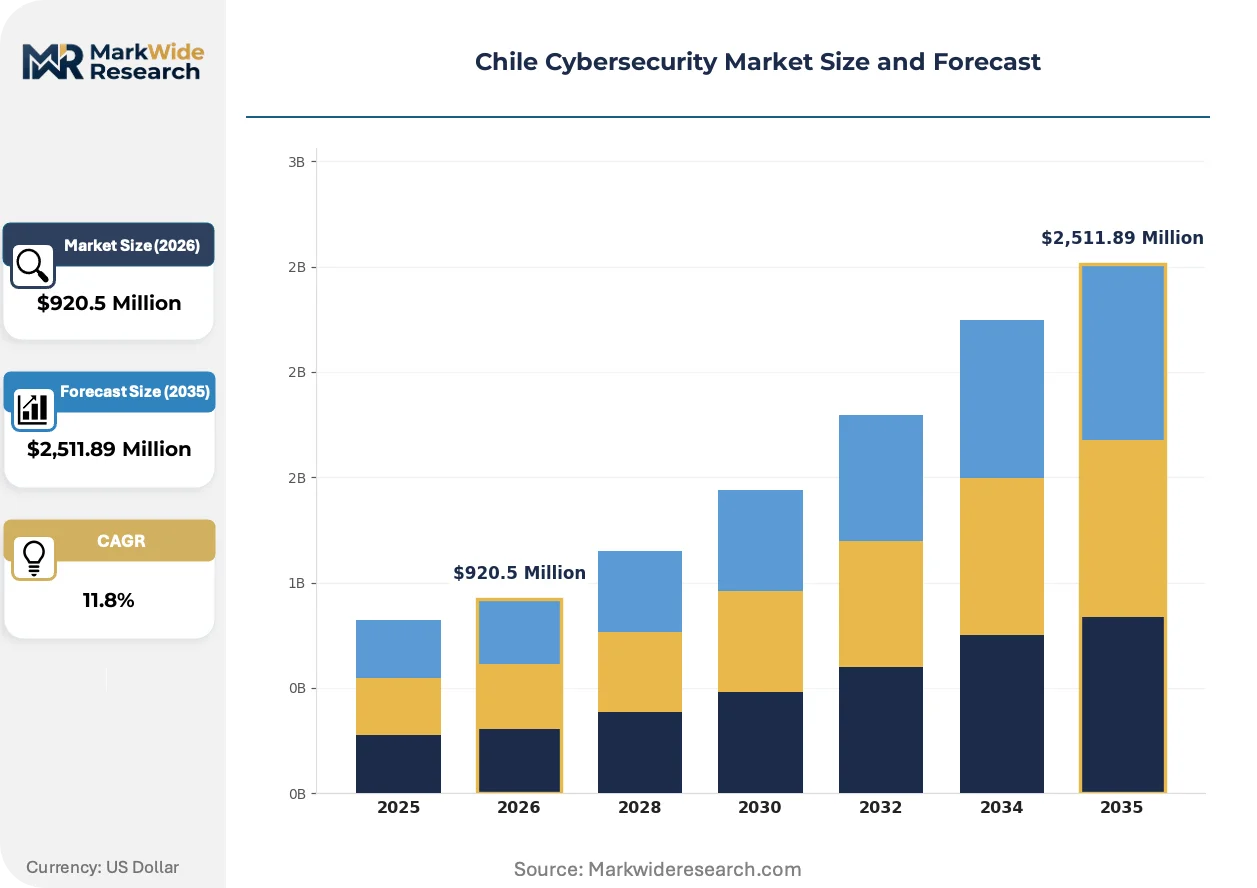
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,511.89 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Identity Management, Threat Intelligence, Incident Response, Network Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Finance, Retail, Government Service Type: Consulting, Managed Security, Training, Support |
| Companies Covered | Check Point Software Technologies, NovaRed, Cisco Systems, iSentinel, Hackmetrix, Palo Alto Networks, IBM Corporation, Cut Security, Fortinet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Cybersecurity Market Strategic Shifts
Automation is displacing manual security operations across Chilean enterprise environments. Three developments are restructuring competitive positioning: AI-driven detection systems, regulatory harmonization pressures, and procurement centralization among large buyers.
Extended detection and response platforms are automating threat investigation workflows that previously required tier-1 analyst intervention. Chilean banks with Santiago headquarters are deploying these systems at scale, compressing mean-time-to-response from hours to minutes. This automation is eliminating margin for standalone endpoint security vendors unable to integrate broader telemetry.
Chile's data protection authority is aligning enforcement practices with GDPR precedent, creating compliance templates for multinational enterprises. The central bank has synchronized cybersecurity norm revisions with Basel operational risk frameworks, reducing interpretation variance for financial institutions. This regulatory convergence favors vendors with existing European certification portfolios entering the Chilean market.
Consolidated procurement functions in Santiago's financial district are unbundling implementation services from software licensing. Large buyers now separate security architecture design from product acquisition, forcing vendors to compete purely on platform capability. This pattern is most pronounced among retail banking groups with centralized technology governance functions.
Chile Cybersecurity Market Segmentation
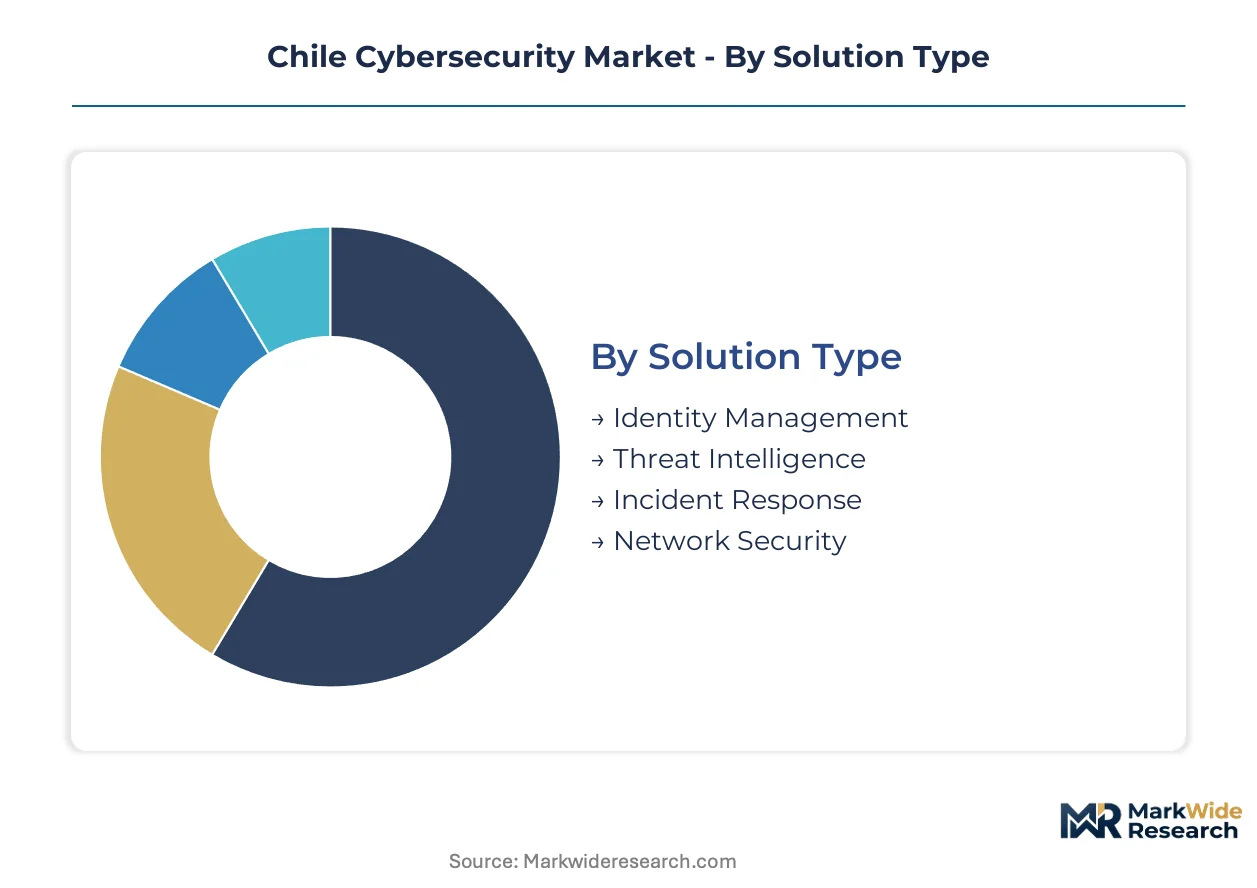
Segmentation in Chile's cybersecurity market reflects divergent procurement patterns across Santiago's financial district versus regional enterprise clusters. Buyers prioritize integrated platforms in high-regulation verticals while cost-constrained organizations retain fragmented point solutions.
Solution Type:
Network Security commands the mature revenue base, while Identity Management captures premium pricing from zero-trust mandates.
- Network Security:Firewalls, intrusion detection systems, and secure access controls form the technical backbone of perimeter defense. Santiago's financial institutions deploy these systems at scale under central bank cybersecurity norm requirements, though margin compression intensifies as platform bundling displaces standalone appliances.
- Identity Management:Multi-factor authentication, privileged access management, and identity governance platforms enable continuous verification architectures. Chilean banks accelerating zero-trust procurement concentrate spending here, with implementation timelines compressing from eighteen months to under nine months for cloud-native deployments.
- Threat Intelligence:Real-time threat feeds and adversary tracking services feed SOC automation workflows.
- Incident Response:Retainer-based breach containment and forensic investigation services address regulatory disclosure timelines.
Mature deployment sits with Network Security. Newer deployment is concentrated in Identity Management.
Deployment Model:
Cloud-Based configurations expand most quickly as workload migration accelerates, while On-Premises retains dominance in classified government systems.
- Cloud-Based:SaaS-delivered security controls and cloud-native protection layers scale with elastic infrastructure consumption. Chilean enterprises migrating critical systems to AWS, Azure, and regional cloud providers drive procurement, with deployment friction lowest among retail sector buyers lacking legacy mainframe dependencies.
- Managed Services:Outsourced SOC operations and continuous monitoring address certified talent scarcity in Santiago's labor market. Government agencies facing intensified audit frequency represent the fastest-expanding customer segment for these services.
- On-Premises:Hardware appliances and locally-hosted software persist in air-gapped environments.
- Hybrid:Split architectures balancing cloud agility with on-premises control for regulated data classes.
Procurement authority concentrates with Cloud-Based buyers in Santiago and Valparaíso. Hybrid architectures dominate mid-market enterprises managing transition risk.
End User:
Finance generates the highest per-entity security spend, while Healthcare presents greenfield expansion opportunity.
- Finance:Retail banks, insurance carriers, and capital markets firms operate under central bank cybersecurity norm enforcement with mandatory incident reporting. Santiago's financial district concentrates procurement authority, with large banking groups unbundling implementation services from software licensing to drive vendor competition.
- Government:Ministries, municipal authorities, and state-owned enterprises face data protection law compliance deadlines. Regulatory audit intensity creates sustained demand for managed security services and compliance automation tooling.
- Healthcare:Hospital networks and clinic chains lag in security maturity relative to financial services.
- Retail:E-commerce platforms and physical retail chains prioritize payment card industry compliance.
Contract values peak in Finance. Implementation complexity peaks in Government.
Service Type:
Managed Security commands recurring revenue premiums, while Consulting engagements concentrate in compliance-driven transformation cycles.
- Managed Security:24/7 SOC operations, threat hunting, and vulnerability management delivered under subscription models. Chilean enterprises lacking internal ISO 27001 implementation capacity outsource these functions, with government and finance segments representing the highest contract values.
- Consulting:Security architecture design, risk assessment, and compliance readiness engagements support regulatory deadline pressure. The data protection authority's intensified audit frequency compresses project timelines and elevates day rates for certified practitioners.
- Training:Workforce certification programs address skills pipeline gaps in SOC analyst and incident response roles.
- Support:Maintenance contracts and technical assistance for deployed security infrastructure.
Revenue stability favors Managed Security. Margin volatility concentrates in Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile consumes more cybersecurity solutions than it produces locally, creating import dependency for hardware security modules and advanced firewall appliances. Domestic service providers concentrate in Santiago and Valparaíso, while software licensing revenue flows predominantly to US-based platform vendors.
Santiago Metropolitan Region
Chile's financial district concentrates procurement authority for zero-trust architecture mandates. The central bank's cybersecurity norms require continuous verification protocols for banks headquartered here. Large retail banking groups with centralized technology governance unbundle implementation services from software licensing to intensify vendor competition.
Valparaíso Region
Port operators and shipping companies along the logistics corridor remain undersecured relative to financial services, presenting greenfield deployment potential. The national computer security incident response team coordinates breach disclosure protocols that influence enterprise security spending thresholds. Maritime logistics firms are accelerating cloud-based security procurement as cargo digitization expands.
Biobío Region
Concepción's university cybersecurity programs graduate insufficient practitioners for SOC analyst roles, exacerbating certified talent scarcity. Regional enterprises rely on managed security services from Santiago-based providers. Manufacturing and energy sector buyers here prioritize hybrid deployment models balancing cloud agility with on-premises control.
Antofagasta Region
Mining operations drive demand for industrial control system security and air-gapped network protection. The data protection law's extraterritorial reach compels multinational mining firms to upgrade compliance infrastructure. Remote operational sites contract managed security services to address 24/7 monitoring requirements without local specialist hiring.
Chile Cybersecurity Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Chile's cybersecurity sector, creating tiered competitive dynamics. Platform bundling compresses margins for standalone appliance vendors while favoring integrated suite providers. Three strategic archetypes dominate: networking-hardware incumbents leveraging installed base advantages, cloud-native platform specialists, and domestic managed service providers. M&A activity concentrates on acquiring ISO 27001-certified implementation teams, while geographic expansion targets the Valparaíso logistics corridor.
Among global platform vendors, Cisco Systems, Palo Alto Networks, and Fortinet occupy distinct positioning archetypes. Cisco leverages its networking-hardware installed base to anchor security subscription revenue. Palo Alto Networks competes through cloud-native platform unification. Fortinet sustains market presence via operating-system consolidation across firewall, SD-WAN, and zero-trust access. Domestic specialists including NovaRed, iSentinel, Hackmetrix, and Cut Security represent the managed services tier, addressing certified talent scarcity through outsourced SOC operations.
| Leading Market Players |
|---|
| Check Point Software Technologies |
| NovaRed |
| Cisco Systems |
| iSentinel |
| Hackmetrix |
| Palo Alto Networks |
| IBM Corporation |
| Cut Security |
| Fortinet |
| Others |
Value Chain & Pricing Dynamics
Chile's central bank cybersecurity norm revisions gate qualified supply access for hardware security modules and advanced firewall appliances, while simultaneously segmenting premium-tier pricing for vendors holding ISO 27001 implementation certifications. This regulatory filtering concentrates procurement leverage among Santiago's financial district buyers who unbundle implementation services from software licensing.
Pricing Analysis
Margin tightening in cloud-native security tiers reflects platform bundling compression as Cisco Systems, Palo Alto Networks, and Fortinet consolidate subscription revenue around integrated suites. Three-tier pricing structure across premium, standard, and economy levels separates vendors with central bank certification from uncertified competitors, with ISO 27001 implementation capacity commanding 40-60% day-rate premiums over standard consulting. Cost-down pressure on on-premises hardware accelerates because import dependency exposes buyers to Chilean peso volatility against US dollar and euro sourcing. Government agencies show least price sensitivity due to regulatory audit intensity, while regional mid-market enterprises outside Santiago exhibit highest sensitivity to implementation service costs.
Supply Chain Analysis
Freight costs from US and European manufacturing hubs amplify landed pricing for hardware security modules and next-generation firewall appliances destined for Santiago's financial district and Valparaíso's port corridor. Supply concentrates in the United States, Germany, and Israel for advanced cybersecurity hardware, while software licensing revenue flows predominantly to US-based platform vendors with negligible Chilean domestic production. Raw material dependencies span specialized semiconductor components for encryption processing, rare earth elements for hardware module fabrication, and proprietary threat intelligence feed licensing. Single-source vulnerability concentrates in certified hardware security module suppliers where central bank norms mandate specific FIPS 140-2 compliance tiers. Distribution runs through Santiago-based systems integrators who anchor implementation service margins for regional enterprise deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's cybersecurity market operates as a supply-constrained environment where certified ISO 27001 implementation capacity props premium-tier pricing and limits vendor scalability. Santiago's talent scarcity for SOC analyst and incident response roles creates persistent capacity bottlenecks that defend margins for qualified service providers.
For Market Incumbents: Acquire ISO 27001-certified implementation teams to defend against margin compression from platform bundling by Cisco Systems and Palo Alto Networks. Expand managed security service capacity in Valparaíso's logistics corridor where port operators remain undersecured relative to financial services. Central bank cybersecurity norm enforcement creates regulatory deadline pressure that sustains demand for certified compliance automation tooling. For New Entrants and Emerging Players: Begin with AI-driven threat detection convergence targeting Biobío Region manufacturing and energy sector buyers who prioritize hybrid deployment models. Valparaíso's maritime logistics firms present the most penetrable segment given greenfield security maturity relative to Santiago's saturated financial district. Partner with Santiago-based systems integrators to bypass direct certification requirements while accessing government procurement channels. For Investors and Strategic Acquirers: Intensified audit frequency by Chile's data protection authority is the leading indicator that managed security services contract values will sustain premium pricing. Long-term viability centers on domestic providers with captive ISO 27001 implementation capacity and established relationships with central bank-regulated financial institutions. Watch for central bank norm alignment with Basel operational risk frameworks as the signal for European-certified vendors entering Chile with transferable compliance portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of ISO 27001-Certified Implementation Teams | Addresses Santiago's certified talent scarcity while defending margin position against platform bundling. |
| Geographic Expansion into Valparaíso Logistics Corridor | Captures greenfield deployment potential among undersecured port operators and shipping companies. |
| AI-Driven Threat Detection Platform Integration | Differentiates domestic service providers through machine learning behavioral analytics combined with SIEM. |
| Managed Security Service Capacity Buildout | Meets government sector demand intensified by data protection authority audit frequency. |
| Regulatory Harmonization Certification Investment | Aligns product portfolios with central bank cybersecurity norms and GDPR precedent convergence. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with CISOs at Santiago-headquartered banks, government IT procurement officers, managed security service provider executives, and systems integrators serving Valparaíso's logistics sector. Secondary validation drew from Chilean central bank cybersecurity norm documentation, data protection authority enforcement disclosures, ISO 27001 certification registries, and hyperscaler capex disclosures for regional cloud infrastructure. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators for the Chilean technology sector.
Data-stream reconciliation across deployment model, end-user vertical, solution type, and regional adoption pattern dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted spending trajectories by regulated financial institutions and government agencies, incorporating cloud workload migration velocity and zero-trust architecture procurement cycle compression observed across Santiago's financial district.
Underlying measurement precision varies by segment; cloud-based deployment and finance vertical estimates carry tighter precision than healthcare and retail sector projections where security maturity lags disclosure. Forecasts incorporate assumptions regarding central bank norm enforcement consistency and data protection authority audit intensity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
North America Extended Detection and Response Market
Cybersecurity
North America Digital Forensics Market
Cybersecurity
Poland Cybersecurity Market
Cybersecurity
Penetration Testing Market
Cybersecurity
Asia-Pacific Cloud DLP Market
Cybersecurity
Domain Name System (DNS) Firewall Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
Global Internet Security Market
Cybersecurity
Network Security Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Bahrain Cybersecurity Market
Cybersecurity
Quantum Cryptography Market
Cybersecurity
Cybersecure Vehicle Control Unit Gateway Systems Market
Cybersecurity
Mainframe Security Market
Cybersecurity
Asia Pacific Digital Forensics Market