
 Medical Record Management System Market | 2026-2036
Medical Record Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Record Management System Market Insights
The 21st Century Cures Act information-blocking provisions is expanding compliance obligations for health IT vendors. Epic Systems Corporation leverages deep integration with academic medical centers to sustain platform dominance. Oracle Health anchors enterprise-scale deployments across multi-hospital systems. MEDITECH competes on total cost of ownership for community hospital segments.
A medical record management system constitutes software infrastructure for capturing, storing, retrieving, and exchanging patient health information across care settings, typically built on HL7 FHIR APIs for interoperability and SQL or NoSQL database architectures supporting concurrent access by thousands of clinical users. The primary purpose centers on reducing medical errors, streamlining care coordination, and enabling population health analytics through longitudinal patient data. Electronic Health Record platforms occupy the largest revenue pool given their central role in clinical workflows, while Cloud-based deployment models represent the fastest-expanding segment as health systems exit capital-intensive data center commitments. Telehealth Solutions integration within record systems is maturing rapidly following pandemic-era adoption spikes.
FDA oversight of software as a medical device intersects with HIPAA security rule mandates from HHS to shape product development roadmaps and liability frameworks for vendors serving US providers. The ONC certification program creates gatekeeping standards that determine Medicare reimbursement eligibility for participating hospitals. Stakeholders must monitor evolving state-level privacy laws that patchwork beyond federal baselines and assess whether modular API architectures or monolithic suites better align with emerging interoperability enforcement.
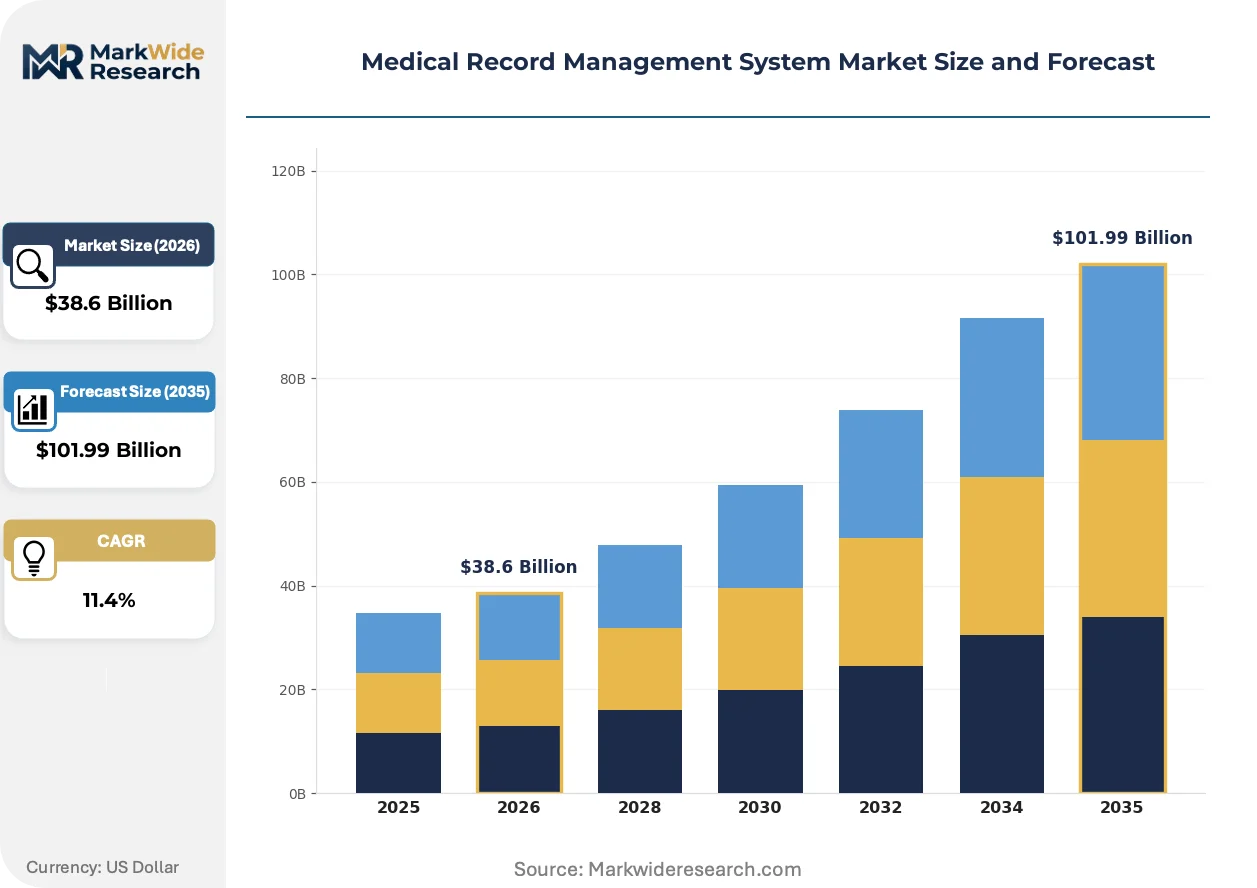
Market Dynamics
The 21st Century Cures Act's information-blocking provisions are restructuring vendor competitive dynamics by mandating HL7 FHIR API interoperability, forcing incumbents to open previously proprietary data architectures and enabling modular best-of-breed substitution.
Growth Catalysts
- Interoperability Mandates:The ONC certification program creates Medicare reimbursement gatekeeping that compels hospital system upgrades. Health systems must achieve compliance to maintain federal payment eligibility.
- Cloud Migration:Health systems are exiting capital-intensive data center commitments. Subscription models reduce upfront infrastructure spend and accelerate deployment timelines for mid-size hospital networks.
- Academic Medical Center Consolidation:Integrated delivery networks in the United States are standardizing platforms across acquired facilities. Epic Systems leverages deep clinical workflow integration to anchor these multi-hospital deployments.
Market Restraints
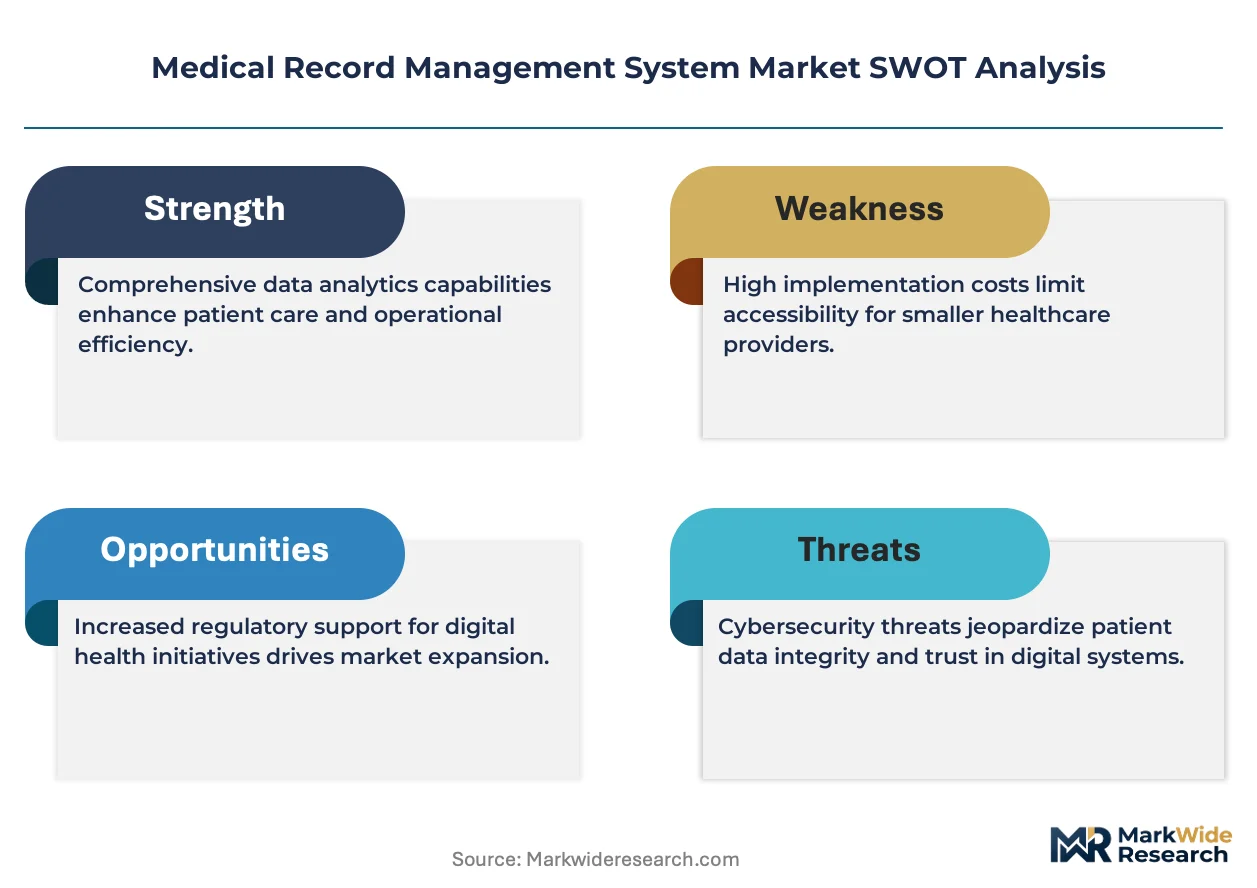
- Legacy System Entrenchment:Decades of customized EHR configurations create switching costs that lock community hospitals into aging platforms. Data migration complexity extends implementation timelines.
- Cybersecurity Insurance Surge:Ransomware attacks against health systems have driven liability premiums upward. HIPAA security rule enforcement from HHS amplifies compliance-driven operational overhead.
- Specialized Talent Scarcity:Health informaticists with dual clinical and technical training command premium compensation. Rural hospital systems struggle to recruit qualified implementation specialists.
Strategic Opportunities
- Telehealth-Native Architectures:Pandemic-era virtual care adoption created permanent hybrid care models. Vendors embedding synchronous video and asynchronous messaging directly into record workflows capture workflow integration premiums.
- Population Health Analytics:Payers and risk-bearing provider organizations demand longitudinal patient data for outcome measurement. Cloud data warehouses enabling SQL-based cohort analysis represent expansion white space.
- API-First Modular Suites:The FDA's software as a medical device oversight intersects with interoperability mandates to favor composable architectures. Best-of-breed vendors can wedge into specific clinical domains.
Industry Challenges
- State Privacy Law Fragmentation:California's CCPA and emerging state-level statutes patchwork beyond HIPAA baselines. Multi-state health systems face conflicting consent and breach notification requirements.
- Clinical Workflow Integration Complexity:Physician resistance to documentation burden increases with each new module deployment. User experience degradation drives shadow IT and workaround adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Record Management System Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Record, Personal Health Record, Health Information Exchange, Telehealth Solutions End User: Hospitals, Physician Practices, Specialty Clinics, Long-term Care Facilities Deployment Model: Cloud-based, On-premise, Hybrid, Mobile-based Service Type: Implementation, Integration, Maintenance, Consulting Services |
| Companies Covered | Epic Systems Corporation, Oracle Health, MEDITECH, Veradigm, athenahealth, GE Healthcare, Siemens, 3M, eClinicalWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Record Management System Market Trends and Innovations
Artificial intelligence documentation tools and ambient clinical intelligence are compressing the physician-computer interface, while regulatory pressure on algorithmic transparency reshapes product roadmaps. These forces are converging to redefine core platform value propositions.
Generative AI scribing tools are rewriting the economics of clinical documentation. Hospital-employed physician groups are deploying ambient listening systems that auto-populate structured EHR fields. This technology is compressing the after-hours documentation burden that drives physician burnout and turnover.
The FDA's software as a medical device framework is tightening oversight of clinical decision support algorithms. Algorithm developers must now document validation datasets and performance across demographic subgroups. AI-embedded EHR modules face extended certification timelines that delay commercialization.
Subscription-based platform economics are displacing perpetual license models in health system procurement. Chief information officers favor operational expenditure treatment for financial flexibility. This shift is most visible among nonprofit hospital systems managing capital constraint cycles.
Medical Record Management System Market Segmentation
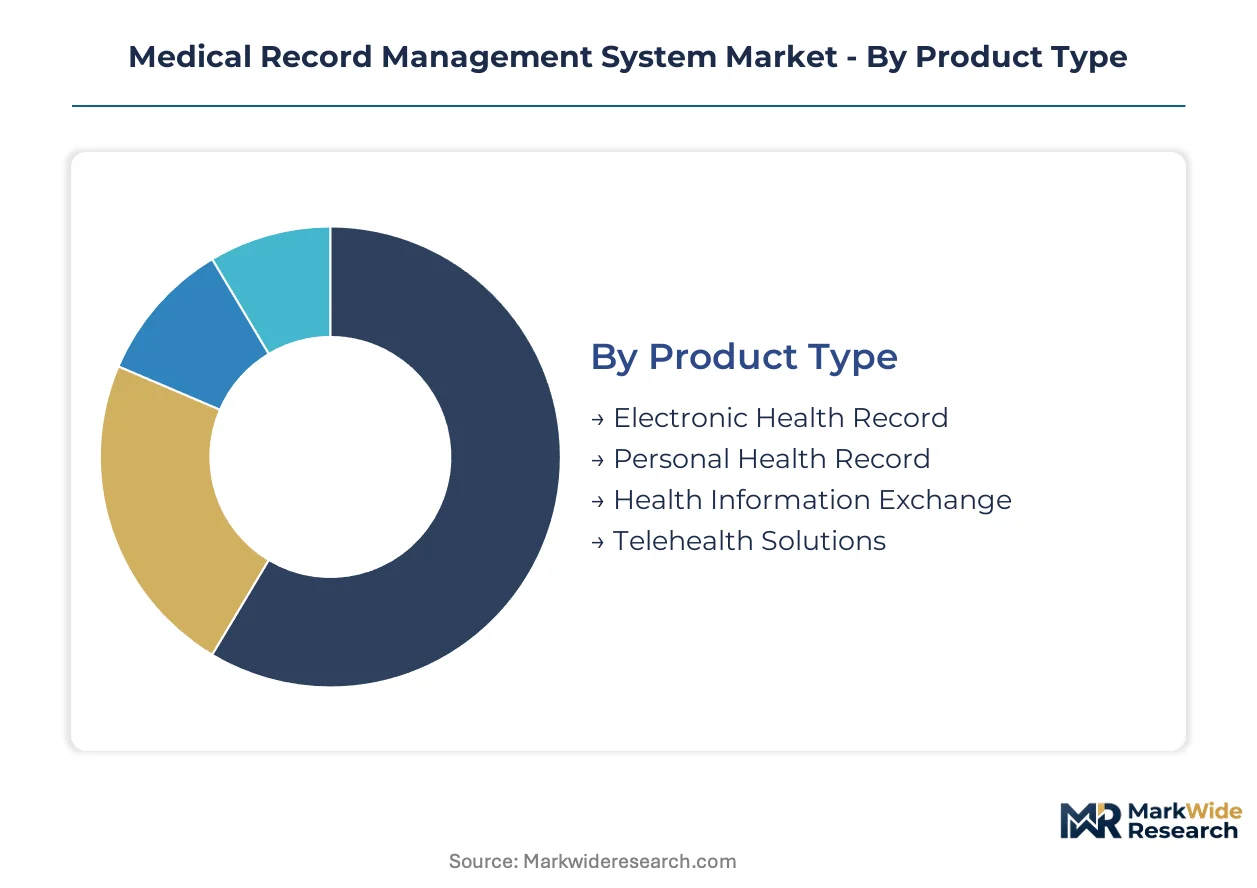
Segmentation in medical record management systems reveals how procurement priorities diverge across care settings and infrastructure maturity. Cloud-native architectures command premium positioning in academic medical centers, while cost-constrained community hospitals prioritize implementation services over platform sophistication.
Product Type:
Integration depth varies sharply: Electronic Health Record platforms anchor enterprise-wide clinical workflows, while Telehealth Solutions embed as modular add-ons or standalone virtual care suites.
- Electronic Health Record:Core clinical data repositories built on HL7 FHIR APIs support concurrent access by thousands of users across inpatient and ambulatory settings. Hospital networks in the United States standardize on Epic or Oracle Health deployments to unify acquired facilities under single platforms.
- Telehealth Solutions:Synchronous video and asynchronous messaging modules embed directly into EHR workflows or operate as best-of-breed complements. Pandemic-era hybrid care models drive permanent integration demand among integrated delivery networks seeking workflow cohesion.
- Personal Health Record:Patient-facing portals enabling direct data access and appointment scheduling.
- Health Information Exchange:Interoperability infrastructure connecting disparate provider systems across competitive boundaries.
Electronic Health Record leads volumes today; Telehealth Solutions is gaining share fastest.
End User:
Cost tier segmentation maps to reimbursement complexity and IT staffing depth, with hospitals absorbing full platform costs while smaller sites purchase targeted modules.
- Hospitals:Enterprise-scale deployments spanning emergency departments, surgical suites, and specialty units require 24/7 uptime guarantees and disaster recovery protocols. Multi-hospital systems in North America consolidate onto single vendor platforms to reduce interface maintenance burden.
- Physician Practices:Ambulatory-focused configurations emphasize documentation efficiency and revenue cycle integration. Group practices with fifty-plus providers negotiate subscription terms that rival hospital pricing through collective purchasing organizations.
- Specialty Clinics:Domain-specific templates for cardiology, oncology, or orthopedics with procedure coding automation.
- Long-term Care Facilities:Medication administration tracking and regulatory compliance reporting for skilled nursing operators.
Hospitals dominate procurement value; Physician Practices show steepest expansion trajectory among ambulatory segments.
Deployment Model:
Customer type preferences split between capital-constrained nonprofits favoring operational expenditure treatment and security-sensitive systems retaining on-premise control.
- Cloud-based:Multi-tenant architectures with automatic patching and elastic compute scaling eliminate data center capital commitments. Mid-size hospital networks accelerate migration timelines as subscription models preserve balance sheet capacity for clinical equipment.
- Hybrid:Sensitive patient data remains on-premise while analytics workloads shift to public cloud infrastructure. Academic medical centers partition workloads to satisfy HIPAA security rule requirements without sacrificing machine learning compute access.
- On-premise:Dedicated hardware installations with full administrative control for critical access hospitals.
- Mobile-based:Native applications enabling bedside documentation and secure messaging for roaming clinical staff.
Cloud-based leads current deployments; Hybrid is climbing the fastest as security-conscious sites adopt partitioned architectures.
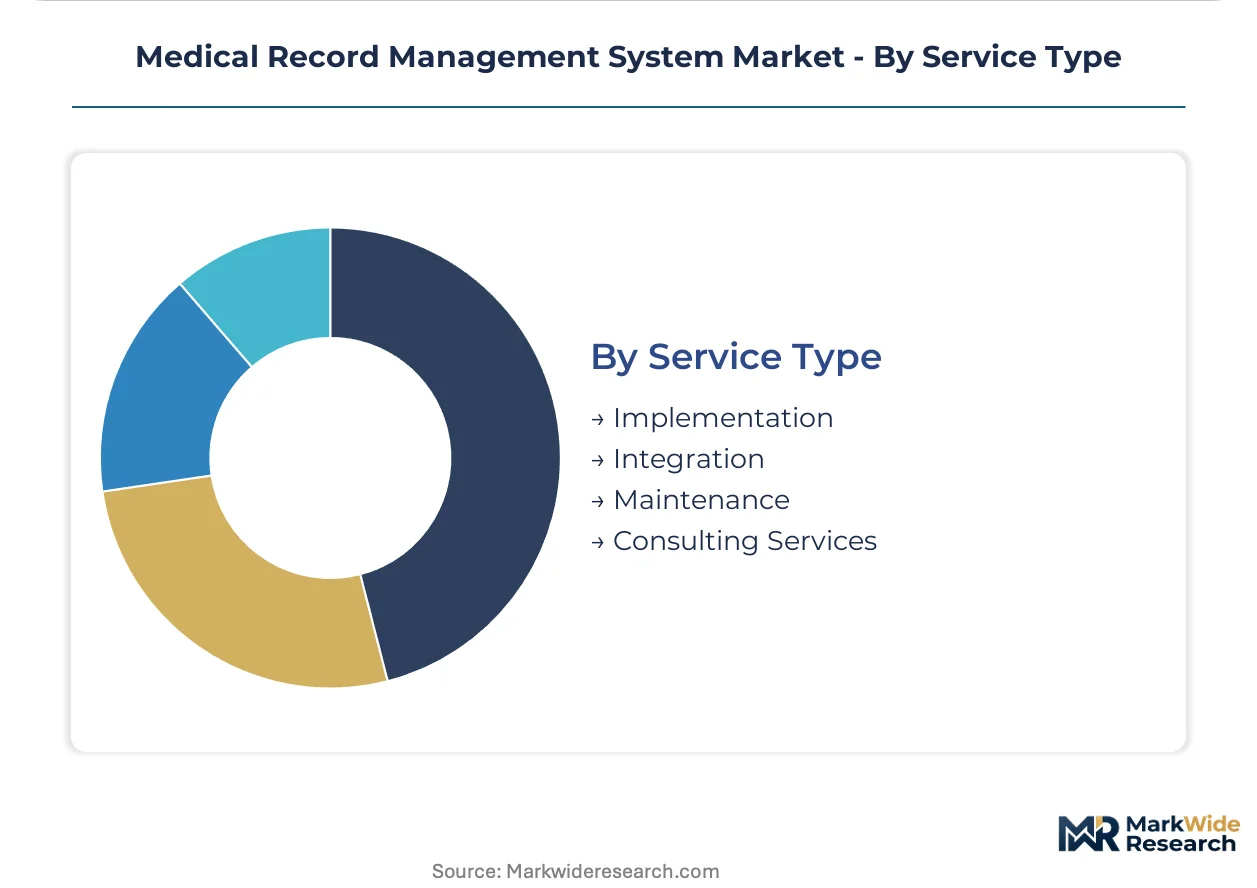
Service Type:
Margin concentration sits in recurring revenue streams, with implementation representing one-time capture and maintenance generating multi-year annuity profiles.
- Implementation:Data migration from legacy systems, workflow configuration, and user training programs spanning twelve to eighteen month timelines. Epic Systems and Oracle Health command premium day rates for certified deployment specialists.
- Maintenance:24/7 technical support, security patching, and version upgrade management under annual contracts. Health systems prioritize maintenance attach rates above ninety percent to ensure regulatory compliance continuity.
- Integration:HL7 interface development connecting EHR platforms to laboratory, radiology, and pharmacy systems.
- Consulting Services:Optimization audits and change management for clinical workflow redesign initiatives.
Maintenance leads recurring revenue today; Consulting Services is expanding most quickly as health systems pursue optimization post-implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered electronic health record commercialization through federal incentive programs, establishing the regulatory and technical frameworks that now propagate across developed health systems worldwide.
United States
Hospital network consolidation and the 21st Century Cures Act interoperability mandates drive procurement intensity. The ONC certification program gates Medicare reimbursement eligibility, compelling platform upgrades. Integrated delivery networks in the Boston-Cambridge corridor and the Research Triangle anchor Epic Systems deployments across multi-facility standardization projects.
Germany
The Hospital Future Act (Krankenhauszukunftsgesetz) allocates federal funds for digital infrastructure modernization. The EU AI Act and GDPR impose layered compliance obligations on algorithmic clinical tools. Berlin and Munich host concentrated health IT vendor ecosystems serving university hospital networks pursuing FHIR-based interoperability.
United Kingdom
NHS England's Federated Data Platform procurement reshapes national-scale record integration priorities. The UK GDPR and NHS data security standards create stringent vendor qualification barriers. London's digital health cluster and Greater Manchester's devolved health system pilot modular EHR architectures.
Japan
Aging demographics and Ministry of Health, Labour and Welfare digitization targets accelerate hospital IT investment. The PMDA regulates clinical decision support software under revised medical device frameworks. Tokyo-Osaka hospital chains deploy cloud-native systems to address rural physician shortages through telehealth integration.
India
The Ayushman Bharat Digital Mission builds national health stack infrastructure for longitudinal patient records. CDSCO oversight of software as medical device intersects with state-level hospital digitization programs. Hyderabad and Bengaluru health IT clusters serve domestic hospital chains and GCC market export contracts.
Medical Record Management System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across implementation complexity and workflow integration depth. The vendor structure concentrates around three archetypes: academic medical center specialists, enterprise multi-hospital platform providers, and cost-optimized community hospital suppliers. Consolidation pressures favor acquisition of niche workflow modules over greenfield development. Strategic partnerships between cloud infrastructure providers and clinical application vendors reshape deployment economics.
Within the academic medical center tier, Epic Systems Corporation and Oracle Health occupy positions defined by deep clinical workflow integration and enterprise-scale infrastructure capacity. MEDITECH anchors the community hospital segment through total cost of ownership positioning. These three entities exemplify how vendor archetypes map to hospital system scale and IT sophistication tiers.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| MEDITECH |
| Veradigm |
| athenahealth |
| GE Healthcare |
| Siemens |
| 3M |
| eClinicalWorks |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure compute pricing indices cascade through medical record management system supply chains, compressing margins for vendors while enabling subscription-tier differentiation that segments hospital buyers by IT sophistication and capital availability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with Epic Systems and Oracle Health commanding premium positioning through ONC certification depth and workflow integration density while MEDITECH anchors economy tiers via total cost of ownership optimization. Price differentiation rests on FHIR API maturity and implementation service bundling, with academic medical centers exhibiting lowest price sensitivity due to federal research funding cushions and community hospitals facing acute budget constraints from Medicare reimbursement pressures. Cost compression in mid-market subscriptions is intensifying because hyperscaler cloud partnerships are reducing infrastructure overhead for second-tier vendors.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-vendor qualification for critical system components, spreading risk across cloud infrastructure providers and implementation service partners. Software development concentrates in the United States, India, and Germany, with Hyderabad and Bengaluru clusters feeding engineering talent into global vendor R&D operations. Raw material dependencies center on semiconductor processors for server hardware, optical fiber for data center connectivity, and lithium-ion battery systems for backup power infrastructure. Single-source vulnerability in specialized health informaticist labor pools threatens implementation timelines. Distribution runs through direct enterprise sales teams and group purchasing organizations serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical record management system expansion functions as a geographic-arbitrage play, with vendors capturing margin premiums in the United States under HIPAA-enforced compliance barriers while cost-optimized deployments penetrate India's Ayushman Bharat Digital Mission infrastructure buildout.
For Market Incumbents: Anchor platform dominance through backward integration into cloud infrastructure partnerships that reduce hyperscaler dependency, while hardening FHIR API interoperability to preempt modular substitution threats from best-of-breed challengers. Certification investment in FDA software-as-medical-device pathways creates regulatory moats that delay entrant commercialization timelines. For New Entrants and Emerging Players: The mid-tier price-point gap between Epic Systems enterprise deployments and MEDITECH community hospital offerings creates white-space opportunity for API-first modular vendors targeting physician practices with fifty-plus providers. Telehealth-native architectures represent the most penetrable segment given pandemic-era workflow permanence. Go-to-market execution should emphasize direct subscription sales through collective purchasing organizations bypassing incumbent channel lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical decision support algorithm developers possessing validated training datasets across demographic subgroups. Long-term viability hinges on FDA clearance timelines and hospital system partnership density. The signal to watch is ONC certification backlog duration as inflection indicator for vendor commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Modularization | Enables best-of-breed substitution under 21st Century Cures Act mandates. |
| Cloud Infrastructure Partnership | Reduces capital expenditure burden for nonprofit hospital system buyers. |
| Ambient Clinical Intelligence Integration | Compresses physician documentation burden driving burnout reduction. |
| Population Health Analytics Platform | Captures payer demand for longitudinal outcome measurement capabilities. |
| Hospital System Consolidation Play | Standardizes multi-facility deployments across integrated delivery networks. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East-Africa, with primary inputs from each region combined through structured interviews with hospital CIOs, health informaticists, GPO contracts managers, and EHR implementation specialists. Secondary validation drew from FDA 510(k) filings, ONC certification databases, CMS Medicare reimbursement data, and hospital procurement contract disclosures. Bottom-up facility-level deployment tracking and top-down vendor revenue analysis enable triangulation across independent estimation paths.
Rate-of-change decomposition isolates volume and value drivers across the projection horizon, with segmentation modeling spanning deployment model, end-user scale tier, service type attach rates, and regional regulatory cluster complexity. CAGRs derive from logistic adoption curves fitted to historical EHR penetration patterns and cloud migration velocity benchmarks. Forecast inputs incorporate hospital network consolidation timelines and interoperability mandate compliance deadlines.
Caveats apply where cybersecurity insurance market dislocation or state-level privacy law fragmentation could materially shift the outlook. Deviation in FDA software-as-medical-device enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
US Mobile Health Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Hospital Management Software Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Population Health Management Solutions Market