
 Patient Data Management Software Market | 2026-2036
Patient Data Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Data Management Software Market Insights
Cloud-native architecture is reconfiguring how patient data platforms are deployed and scaled across health systems. Epic Systems leverages deep integration with clinical workflows to anchor its position in large academic medical centers. Oracle competes through aggressive cloud infrastructure investments that extend its database dominance into healthcare verticals. Siemens Healthineers AG specializes in bridging imaging data with enterprise records, differentiating its offering through device-to-software connectivity.
Patient data management software encompasses systems that collect, store, process, and exchange clinical and administrative information across healthcare delivery organizations, typically operating through HL7 FHIR APIs and ISO 27001-certified security frameworks to enable real-time care coordination and population health analytics. Cloud-based deployments now lead the product type category as hospitals prioritize scalability and reduced capital expenditure, while artificial intelligence within the technology dimension represents the fastest-expanding segment as predictive analytics applications mature. The end user landscape tilts toward hospitals, where margin pools concentrate around enterprise-wide implementations that consolidate multiple legacy systems.
The FDA oversees software-as-a-medical-device classifications that determine premarket review requirements for clinical decision support tools embedded within these platforms. HIPAA security rules and the Office of the National Coordinator for Health IT certification standards shape product development priorities and create compliance barriers for new entrants. Stakeholders must monitor evolving interoperability mandates and artificial intelligence governance frameworks to anticipate procurement specification shifts.
Market Dynamics
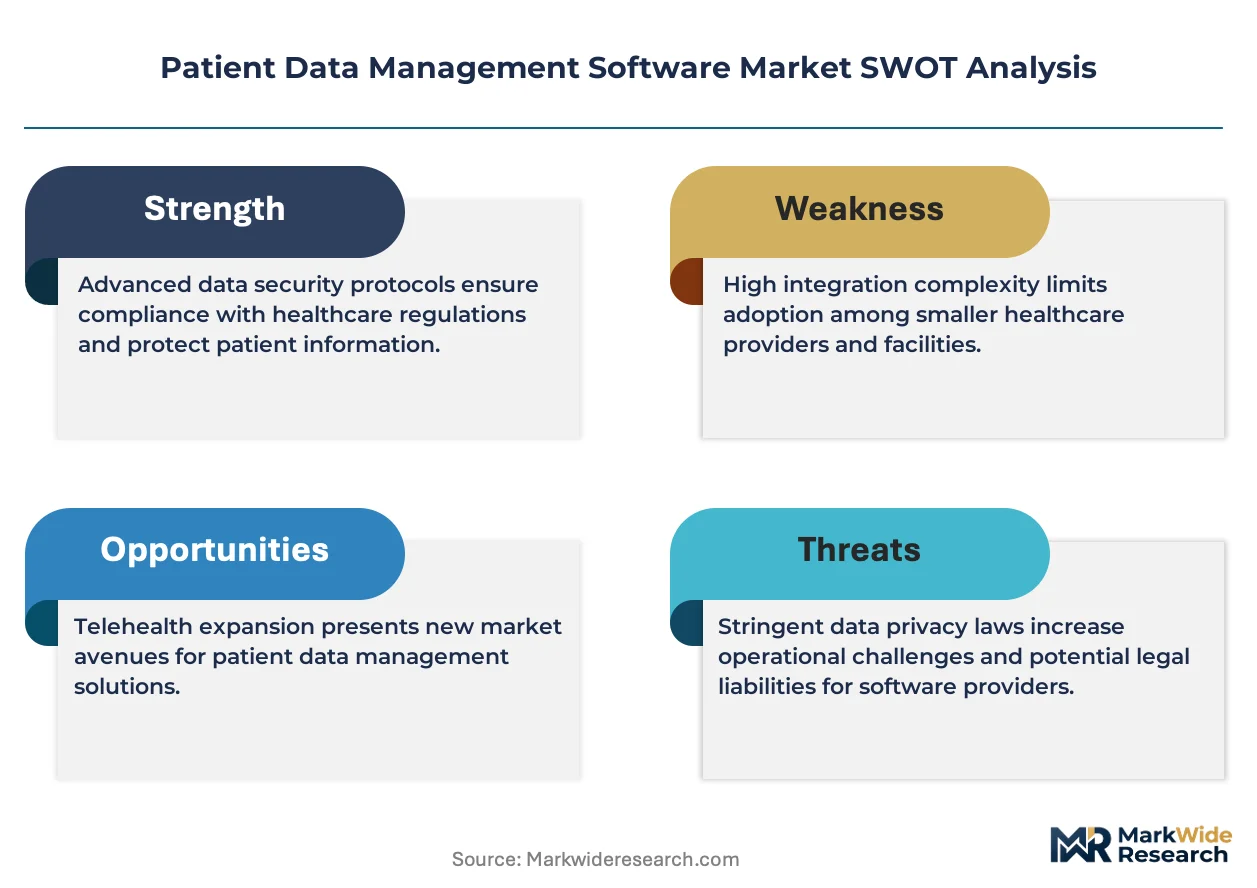
Cloud-native architecture is compressing deployment timelines while the FDA's 21st Century Cures Act interoperability mandates force legacy system replacements, creating a structural squeeze between technical modernization and regulatory compliance timelines.
Growth Catalysts
- FHIR API standardization:The Office of the National Coordinator for Health IT certification requirements now mandate HL7 FHIR interoperability, accelerating platform consolidation across hospital systems.
- Hospital margin pressure:Health systems facing operational cost constraints are prioritizing SaaS deployments that convert capital expenditure to operational expenditure.
- Artificial intelligence integration:Predictive analytics for clinical decision support is expanding addressable use cases within existing electronic health record footprints.
Market Restraints
- Data localization requirements:China's NMPA and Personal Information Protection Law impose strict cross-border data transfer restrictions, fragmenting cloud architecture strategies.
- Legacy system entrenchment:Decades of customized on-premise installations create technical debt that resists standardized migration paths.
- Cybersecurity insurance costs:Rising ransomware attack frequency against health systems is elevating operational risk premiums and procurement scrutiny.
Strategic Opportunities
- Rural health network expansion:Federally qualified health centers in underserved US counties present greenfield implementation opportunities without legacy displacement costs.
- Remote patient monitoring convergence:Integration of wearable device data streams with enterprise records creates new data monetization pathways.
- EU AI Act compliance services:Risk classification requirements for clinical decision support tools create adjacent revenue streams for governance tooling.
Industry Challenges
- Interoperability engineer scarcity:Specialized expertise in HL7 FHIR implementation and health data exchange protocols commands premium compensation, constraining deployment velocity.
- Multi-cloud orchestration complexity:Health systems operating across AWS, Azure, and Google Cloud environments face integration testing burdens that extend go-live timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Data Management Software Market |
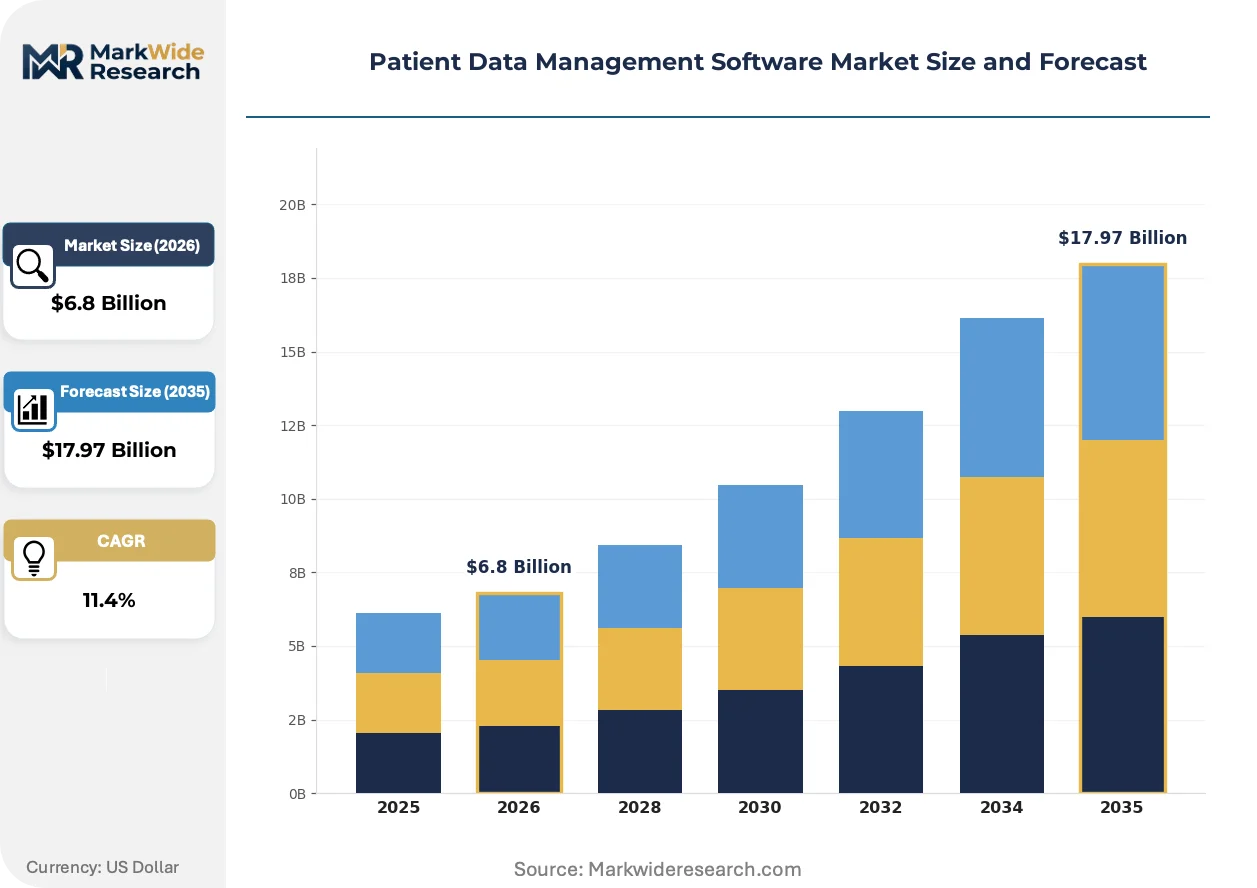
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile End User: Hospitals, Clinics, Research Institutions, Laboratories Technology: Artificial Intelligence, Machine Learning, Blockchain, Data Analytics Application: Patient Engagement, Compliance Tracking, Data Security, Resource Management |
| Companies Covered | IBM, IQVIA Holdings Inc., Health Catalyst Inc., Oracle, UnitedHealth Group, Epic Systems, Abbott Laboratories, Danaher Corporation, Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Data Management Software Market Trends and Innovations
Artificial intelligence is embedding into clinical workflows at an accelerating pace, while regulatory frameworks on both sides of the Atlantic are hardening compliance requirements for algorithmic decision tools.
Natural language processing engines are hybridizing structured and unstructured clinical documentation, extracting diagnostic codes from physician notes without manual abstraction. Large academic medical centers are piloting these tools in emergency departments and specialty clinics. This hybridizing capability is compressing revenue cycle timelines while reducing administrative staffing ratios.
The EU AI Act's risk-based classification system is redefining premarket obligations for clinical decision support software across European markets. High-risk algorithmic tools now require conformity assessments and post-market monitoring protocols. German university hospitals and French public hospital groups are restructuring procurement specifications to mandate CE marking under the new Medical Device Regulation and AI Act combined frameworks.
Subscription-based licensing is displacing perpetual license models as the dominant commercial structure for enterprise health IT procurement. Health system CFOs are prioritizing predictable operational expenditure over capital allocation flexibility. This shift is most pronounced in the United States, where Medicare reimbursement volatility makes multi-year SaaS commitments attractive for budget forecasting stability.
Patient Data Management Software Market Segmentation
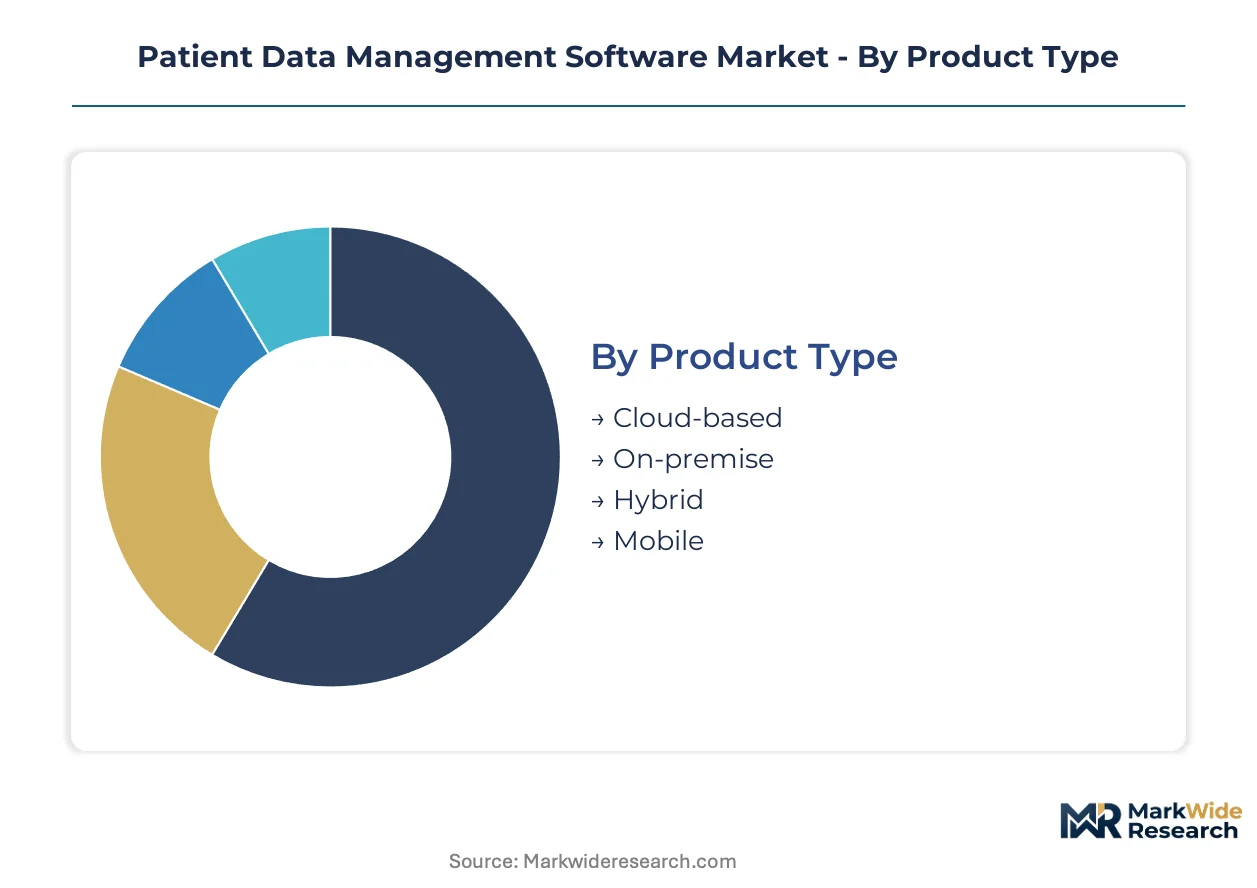
Patient data management software segments along deployment architecture, clinical setting, intelligence layer, and functional purpose. Procurement patterns diverge sharply across these dimensions as hospitals prioritize interoperability while ambulatory settings favor cost containment.
Product Type:
Deployment models span the maturity spectrum from established on-premise installations to emerging edge-native mobile architectures.
- Cloud-based:Multi-tenant SaaS platforms with ISO 27001 certification and HL7 FHIR APIs enable elastic scaling across health system networks. United States hospital systems facing Medicare reimbursement volatility favor these deployments for predictable operational expenditure conversion.
- On-premise:Dedicated hardware installations within hospital data centers maintain full custody of protected health information. German university hospitals and French public hospital groups specify these for EU AI Act high-risk algorithmic processing requirements.
- Hybrid:Federated architectures split sensitive workloads on-premise while bursting analytics to public cloud. China's NMPA data localization mandates drive this configuration for multinational pharmaceutical trials.
- Mobile:Native iOS and Android applications for bedside documentation and remote patient monitoring. Federally qualified health centers in rural United States counties deploy these for physician extenders without workstation infrastructure.
Cloud-based deployments handle the majority of throughput; Mobile is gaining share fastest among greenfield implementations.
End User:
Customer concentration follows margin pools from enterprise hospital systems through distributed laboratory networks.
- Hospitals:Academic medical centers and integrated delivery networks consolidate multiple legacy systems through enterprise-wide EHR platforms. Epic Systems anchors these implementations with deep clinical workflow integration in large United States facilities.
- Clinics:Ambulatory practices prioritize lightweight SaaS configurations with subscription licensing. Oracle's cloud infrastructure investments target this segment for cost-sensitive independent physician associations.
- Research Institutions:National Institutes of Health-funded centers and European Research Council grantees require specialized data governance for multi-site clinical trials. HIPAA and GDPR dual compliance frameworks shape procurement specifications.
- Laboratories:Clinical and anatomic pathology operations demand LIS-EHR interoperability for specimen tracking and results distribution. Siemens Healthineers bridges imaging and enterprise records through device-to-software connectivity.
Hospitals command the dominant procurement volume; Research Institutions are expanding most quickly on federal funding acceleration.
Technology:
Intelligence capabilities stratify by algorithmic sophistication and regulatory scrutiny intensity.
- Artificial Intelligence:Clinical decision support tools with FDA software-as-a-medical-device classification requirements. Predictive analytics for sepsis detection and readmission risk scoring concentrate demand in United States academic medical centers.
- Machine Learning:Supervised learning models for diagnostic imaging classification and natural language processing of clinical documentation. German university hospitals pilot these for emergency department coding automation.
- Blockchain:Distributed ledger architectures for immutable audit trails and patient consent management. Pilot implementations in United Arab Emirates MOHAP-regulated health information exchanges test interoperability frameworks.
- Data Analytics:Descriptive and diagnostic dashboards for population health management and quality reporting. United States federally qualified health centers deploy these for Medicaid accountable care organization performance tracking.
Artificial Intelligence absorbs the largest development investment; Machine Learning is climbing the fastest on deployment velocity.
Application:
Functional modules align with operational priorities from revenue cycle through cybersecurity posture.
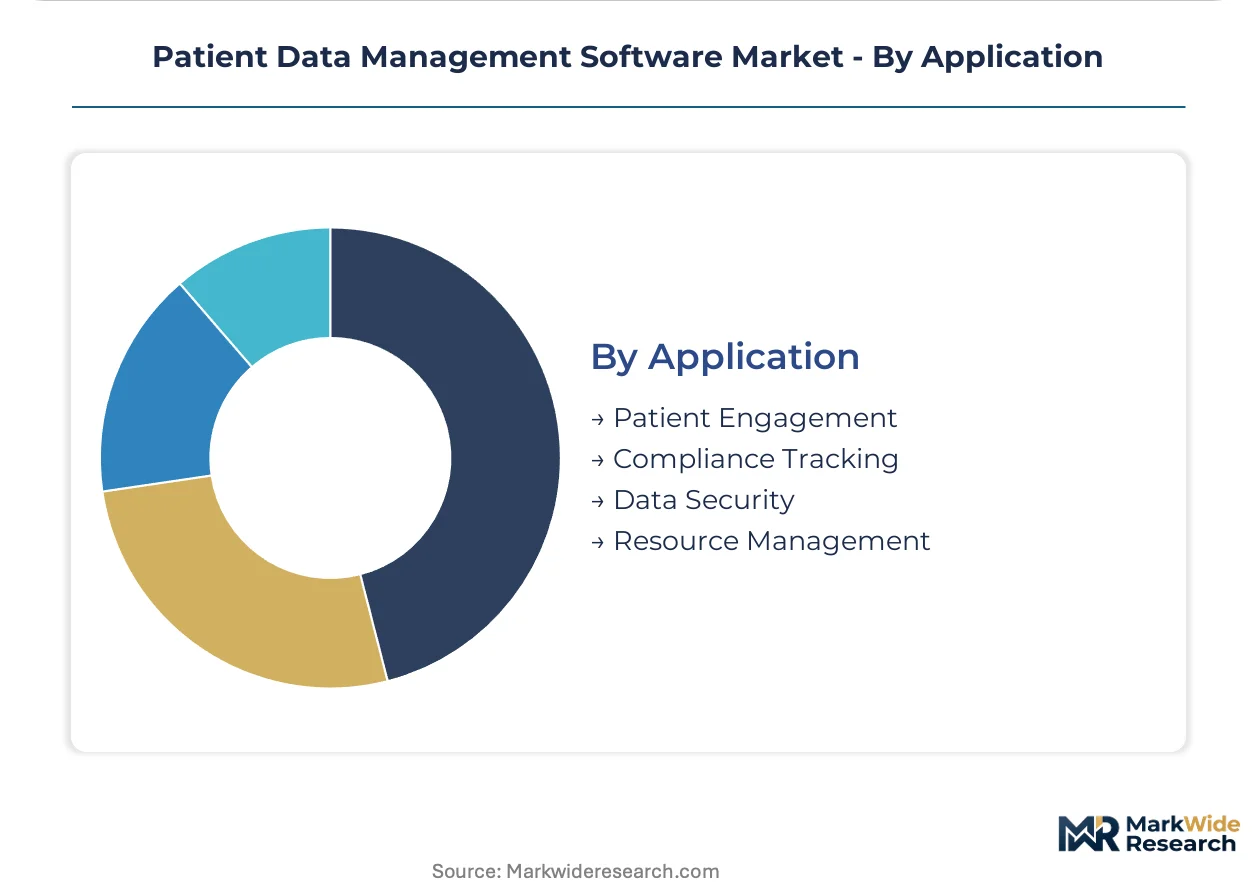
- Patient Engagement:Portal platforms and mobile applications for appointment scheduling, prescription refill, and secure messaging. United States hospital systems deploy these for Medicare meaningful use incentive compliance.
- Compliance Tracking:Automated audit logging and reporting for HIPAA security rule and FDA 21st Century Cures Act interoperability mandates. Health system legal departments prioritize these for OCR investigation readiness.
- Data Security:Encryption, access control, and intrusion detection systems for ransomware defense. Rising cyber insurance premiums in United States markets elevate procurement priority for these modules.
- Resource Management:Scheduling, inventory, and capacity optimization for operating rooms and clinical staff. French public hospital groups implement these for emergency department overcrowding mitigation.
Patient Engagement captures the broadest installed base; Data Security is expanding most steeply on threat environment deterioration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in health information technology services, exporting SaaS platforms and clinical workflow systems while importing specialized hardware components and embedded medical device software from German and Japanese manufacturers. Cross-border data flows now constitute a critical trade consideration as jurisdictions impose divergent localization mandates.
United States
Federal meaningful use incentive programs and Medicare reimbursement volatility drive hospital system procurement of cloud-native platforms. The Office of the National Coordinator for Health IT mandates HL7 FHIR interoperability certification for all federally reimbursed deployments. Epic Systems anchors enterprise implementations across academic medical centers in Boston, Palo Alto, and Durham, consolidating multiple legacy systems through deep clinical workflow integration.
Germany
University hospitals prioritize on-premise installations for EU AI Act high-risk algorithmic processing compliance. The country's national medical device regulator enforces Medical Device Regulation conformity assessments for clinical decision support tools. Siemens Healthineers bridges imaging and enterprise records through device-to-software connectivity in Erlangen and Berlin hospital clusters.
China
NMPA data localization mandates and Personal Information Protection Law restrictions fragment cloud architecture strategies for multinational pharmaceutical trials. The national medical products administration imposes strict cross-border data transfer limitations on clinical trial management systems. Shanghai and Beijing health information exchanges pilot hybrid federated architectures that split sensitive workloads on-premise while bursting analytics to domestic cloud providers.
United Arab Emirates
MOHAP-regulated health information exchanges test distributed ledger architectures for immutable audit trails and patient consent management. The ministry of health and prevention drives interoperability framework pilots across Dubai and Abu Dhabi hospital networks. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City anchor enterprise platform deployments serving medical tourism and domestic population health management simultaneously.
France
Public hospital groups restructure procurement specifications to mandate combined CE marking under Medical Device Regulation and EU AI Act frameworks. ANSM and CNIL jointly oversee algorithmic conformity assessments for clinical decision support software. Assistance Publique-Hôpitaux de Paris and university hospitals in Lyon and Marseille implement resource management modules for emergency department overcrowding mitigation.
Patient Data Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated platform vendors with deep clinical workflow expertise and cloud infrastructure scale. Epic Systems and Oracle occupy divergent strategic positions—one through proprietary EHR dominance, the other through database-to-cloud vertical extension. Three archetypes define competitive positioning: legacy EHR incumbents with workflow lock-in, cloud hyperscalers extending infrastructure dominance, and medical device manufacturers bridging hardware-software connectivity. M&A activity concentrates on AI-enabled clinical decision support acquisitions and interoperability middleware consolidation.
Within the legacy EHR tier, Epic Systems exemplifies workflow-anchored market position through deep integration with academic medical center operations. Oracle occupies the cloud infrastructure extension archetype, leveraging database dominance into healthcare verticals through aggressive capital deployment. Siemens Healthineers AG represents the device-to-software connectivity specialist, bridging imaging hardware with enterprise records through proprietary integration layers. These three anchors illustrate the structural segmentation between clinical workflow depth, cloud scale, and hardware-software convergence.
| Leading Market Players |
|---|
| IBM |
| IQVIA Holdings Inc. |
| Health Catalyst Inc. |
| Oracle |
| UnitedHealth Group |
| Epic Systems |
| Abbott Laboratories |
| Danaher Corporation |
| Siemens Healthineers AG |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cloud hyperscalers for infrastructure-as-a-service determines both pricing tier spreads and supply chain shape in patient data management software. Hospital systems facing Medicare reimbursement volatility compress procurement cycles when AWS, Azure, or Google Cloud experience capacity constraints or geographic availability restrictions.
Pricing Analysis
Hospital procurement committees anchor subscription-based SaaS pricing across three tiers: enterprise-wide deployments with full clinical workflow integration, departmental modules with limited interoperability, and lightweight ambulatory configurations. Price differentiation rests on HL7 FHIR certification level and customization depth for legacy system migration. Cost compression in the mid-tier is intensifying because Oracle and Epic Systems compete aggressively for health system CFO attention. Federally qualified health centers in rural United States counties exhibit the highest price sensitivity, while academic medical centers prioritize workflow depth over license cost.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers now stretch to ninety days for health system implementations, easing cash flow for SaaS vendors competing on operational expenditure conversion. Software development concentrates in the United States, Germany, and India, with clinical workflow engineering anchored in Boston and Palo Alto health technology clusters. Raw material dependencies include GPU compute capacity from NVIDIA supply allocations, encrypted storage arrays from Western Digital and Seagate, and API middleware from specialized HL7 FHIR implementation shops. Single-source vulnerability concentrates in NVIDIA data center GPU supply for AI-enabled clinical decision support training. Distribution runs through direct enterprise sales teams supplemented by GPO contracts for hospital system network purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient data management software functions as a service-attach opportunity where implementation consulting and ongoing interoperability maintenance expand faster than core license revenue. Recurring revenue from FHIR API integration services and cybersecurity posture management now exceeds initial deployment fees for cloud-native platforms.
For Market Incumbents: Insulate enterprise positions by deepening clinical workflow integration in Epic Systems-anchored academic medical centers and acquiring specialized HL7 FHIR implementation shops to constrain engineer scarcity. Threats from Oracle's cloud infrastructure investments demand defensive certification acceleration for FDA software-as-a-medical-device classifications. Capacity addition in Germany for EU AI Act compliance services extends workflow lock-in into European markets.
For New Entrants and Emerging Players: Build out rural health network implementations in federally qualified health centers across underserved United States counties, where legacy displacement costs are minimal and greenfield SaaS deployments face limited incumbent resistance. The most penetrable segment converges remote patient monitoring data streams with enterprise records for Medicaid accountable care organization performance tracking. A channel partnership strategy with regional health information exchanges accelerates trust establishment without direct hospital sales force investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized interoperability middleware and AI-enabled clinical decision support acquisitions over horizontal platform bets. Long-term viability over the next decade hinges on regulatory compliance service attach rates expanding faster than license growth. Acquisition target archetypes include HL7 FHIR implementation specialists with hospital system reference contracts and natural language processing engines for emergency department coding automation. The signal to watch is FDA premarket review queue length for software-as-a-medical-device classifications, which indicates competitive pressure intensity for algorithmic tools.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Acceleration | ONC certification requirements now mandate interoperability standards for all federally reimbursed deployments. |
| AI Governance Tooling Development | EU AI Act risk classification creates adjacent revenue streams for clinical decision support compliance services. |
| Rural Health Network Partnership | Federally qualified health centers present greenfield opportunities without legacy system displacement burdens. |
| Hybrid Cloud Architecture Deployment | China's NMPA data localization mandates drive federated architectures for multinational pharmaceutical trials. |
| Natural Language Processing Integration | German university hospitals pilot emergency department coding automation to compress revenue cycle timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital CIOs, health system procurement committees, HL7 FHIR implementation engineers, and biomedical informatics directors; and secondary validation against FDA 510(k) filings, ONC certification databases, CMS Medicare reimbursement data, and hospital GPO contract disclosures. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against health IT capital expenditure surveys anchored market sizing.
Forecast inputs span deployment architecture, health system size tier, clinical setting concentration, AI integration depth, and regional regulatory framework intensity across the projection horizon. Segmentation modeling incorporates cloud-native versus on-premise versus hybrid configurations, academic medical center versus community hospital versus ambulatory clinic end-use, and artificial intelligence versus machine learning versus data analytics technology layers. CAGRs derive from elasticity-adjusted adoption curves calibrated against historical EHR replacement cycles and interoperability mandate compliance deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive cloud infrastructure pricing moves by Oracle or Microsoft Azure would shift outcomes toward faster SaaS conversion. Macroeconomic deviation in Medicare reimbursement rates, regulatory acceleration of FDA software-as-a-medical-device classifications, or breakthrough advances in federated learning architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Healthcare Data Interoperability Market