
 Europe Prebiotics Market | 2026-2036
Europe Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Prebiotics Market Insights
Belgian chicory root processors are shifting extraction capacity toward higher-purity inulin grades. BENEO GmbH leverages its vertical integration from chicory farming to refined oligosaccharides, sustaining cost leadership across the Rhine-Ruhr manufacturing corridor. Cargill competes through supply chain control over South American agave sources, while Roquette Frères specializes in pea-derived prebiotic fibers for plant-based dairy alternatives.
Prebiotics are non-digestible carbohydrate compounds, typically comprising fructans or galactans with degrees of polymerization from two to sixty units, that selectively stimulate beneficial colonic microbiota. Manufacturers produce these ingredients through enzymatic hydrolysis of plant polysaccharides or controlled fermentation, yielding powders with minimum 90% dry matter purity for food-grade applications. Inulin dominates ingredient volumes in dairy and bakery systems due to its fat-mimetic and texturizing functionality, while galacto-oligosaccharides command premium positioning in infant formula segments where EFSA health claim authorizations apply. Dietary supplements in capsule and sachet formats represent the fastest-growing end-user channel, driven by direct-to-consumer subscription models through online stores and specialty retailers.
EFSA evaluates all prebiotic health claims under Regulation 1924/2006, with approved claims limited to specific bowel function and blood glucose outcomes, while the EU Green Deal pressures manufacturers toward lower-carbon extraction processes and sustainable sourcing certifications. REACH compliance governs novel prebiotic intermediates not listed on the EU inventory, creating regulatory barriers for Asian entrants without European substance registrations. Stakeholders must monitor EFSA's evolving guidance on microbiome-related claims, as pending opinions on immune and mental health endpoints could reshape permissible marketing language and R&D prioritization across the value chain.
Market Dynamics
EFSA's restrictive health claim framework under Regulation 1924/2006 is compressing permissible marketing language, forcing manufacturers to pivot R&D toward bowel function and blood glucose endpoints while abandoning broader microbiome claims pending regulatory clarity.
Growth Catalysts
- EU Green Deal farm-to-fork strategy:The policy mandates lower-carbon extraction processes and sustainable sourcing certifications, accelerating clean-label ingredient transitions across German and French functional food manufacturers.
- Dairy fortification programs:Benelux and Scandinavian processors are expanding prebiotic incorporation into yogurt and fermented milk systems, driven by consumer preference for gut-health positioning in chilled dairy aisles.
- Enzymatic hydrolysis advances:Novel biocatalysts enable higher-purity inulin extraction from chicory root, reducing refining stages and improving yield economics for European processors.
Market Restraints
- Chicory root supply concentration:Belgian and Dutch processors dominate raw material sourcing, creating geographic concentration risk for inulin-dependent formulations.
- REACH compliance barriers:Novel oligosaccharide intermediates require substance registration, blocking Asian entrants lacking European inventory listings.
- Plant protein fiber competition:Pea and oat-derived fibers are capturing formulation share in plant-based dairy alternatives, pressuring traditional prebiotic positioning.
Strategic Opportunities
- Polish and Romanian retail expansion:Eastern European markets show underpenetrated dietary supplement distribution, creating whitespace for direct-to-consumer subscription models.
- Infant formula premiumization:Galacto-oligosaccharide applications in specialized nutrition command authorized EFSA health claims, supporting margin expansion in pharmaceutical-channel products.
- Controlled fermentation technology:Precision bioprocessing platforms enable custom oligosaccharide profiles, opening bespoke ingredient services for personalized nutrition startups.
Industry Challenges
- Microbiome claim substantiation:Pending EFSA opinions on immune and mental health endpoints require extensive clinical investment without guaranteed authorization timelines.
- Dual certification complexity:Organic and non-GMO verification叠加 creates documentation burdens for multi-source supply chains serving premium retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Prebiotics Market |
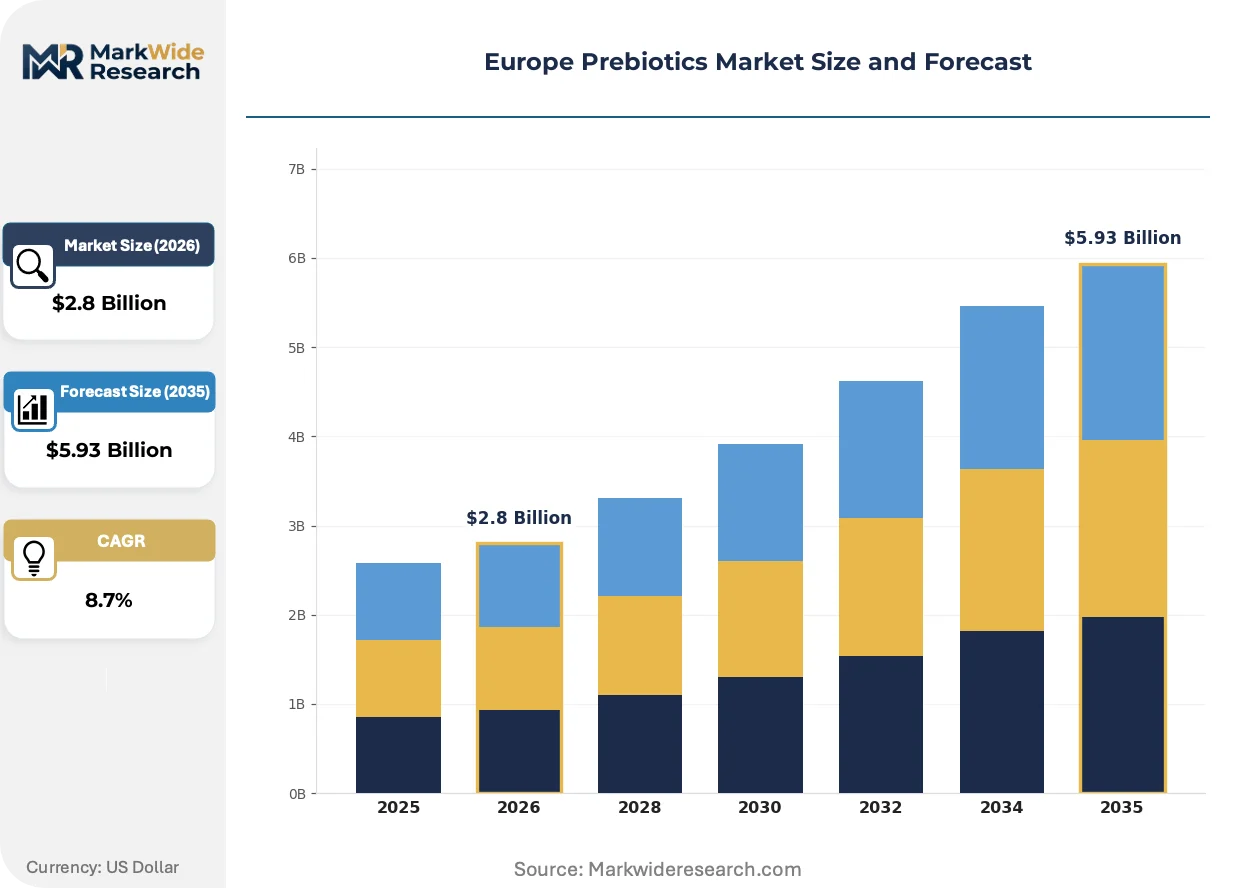
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galacto-oligosaccharides, Xylo-oligosaccharides End User: Dairy Products, Functional Foods, Dietary Supplements, Beverages Form: Powder, Liquid, Granular, Tablet Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Retailers |
| Companies Covered | BENEO GmbH, Cargill, Ingredion Incorporated, Tereos SA, Südzucker Group, Royal FrieslandCampina, Kerry Group plc, Roquette Frères, Chr. Hansen Holding A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Prebiotics Market Trends and Innovations
Clean-label extraction technologies and precision fermentation platforms are reshaping ingredient purity standards, while regulatory pressure on health claims is redirecting innovation toward substantiated physiological endpoints.
Membrane filtration systems for inulin refinement are consolidating production economics for European chicory processors. German manufacturers are retrofitting extraction lines with ceramic nanofiltration modules, reducing solvent use and energy intensity. This technology is consolidating competitive advantage for vertically integrated operators with captive raw material supply.
EFSA's evolving guidance on microbiome-related claims is compressing permissible marketing language across the value chain. The regulator's pending opinions on immune and cognitive endpoints are forcing manufacturers to abandon unsubstantiated positioning. Infant formula and medical nutrition segments are responding by concentrating R&D budgets on bowel function and glycemic response studies with higher authorization probability.
Direct-to-consumer subscription models are displacing traditional pharmacy and supermarket channels for prebiotic supplements. Nordic consumers are adopting monthly sachet deliveries through specialized wellness platforms, bypassing conventional retail markups. This shift is most visible in Denmark and Sweden, where digital health engagement rates exceed continental averages.
Europe Prebiotics Market Segmentation
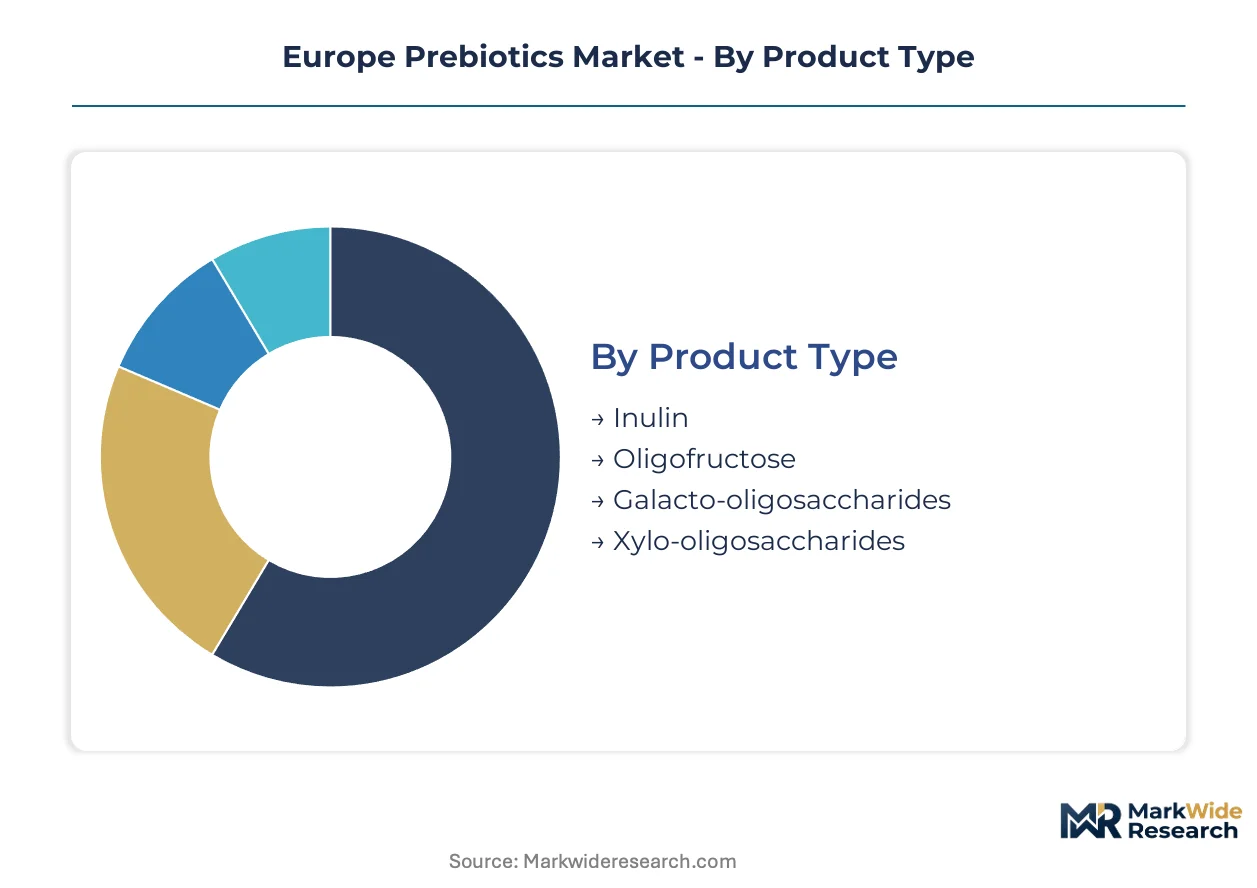
Prebiotic ingredient purchasing in Europe stratifies sharply across formulation requirements, regulatory pathways, and channel economics. Manufacturers configure product portfolios around EFSA claim authorizations and dairy processor specifications, while end-user segmentation reveals divergent margin structures between commodity bulk supply and premium finished goods.
Product Type:
Supply concentration for chicory-derived ingredients in Belgium and the Netherlands shapes competitive dynamics across all four product categories, with enzymatic processing capabilities determining purity grades and pricing tiers.
- Inulin:Long-chain fructan polymers with degrees of polymerization exceeding ten units deliver fat-mimetic texture and water-binding functionality. German and French dairy processors dominate demand for standard-grade material in yogurt and spread applications, constrained by Belgian chicory root harvest volatility.
- Galacto-oligosaccharides:Disaccharide to pentasaccharide structures derived from lactose feedstocks command premium positioning in infant formula segments. Dutch and Irish pharmaceutical-channel manufacturers drive volume, supported by EFSA-authorized health claims for bowel function outcomes.
- Oligofructose:Short-chain fructans with polymerization below ten units serve bakery and confectionery systems requiring lower viscosity.
- Xylo-oligosaccharides:Hemicellulose-derived compounds from cereal processing byproducts target emerging applications in precision fermentation platforms.
Today's leader: Inulin. Tomorrow's challenger: Galacto-oligosaccharides.
End User:
Cost tier differentiation separates commodity bulk ingredient sales from value-added finished formulations, with regulatory investment requirements creating distinct competitive moats across the four end-use categories.
- Dairy Products:Fermented milk systems and yogurt bases incorporate inulin at 3-8% inclusion rates for texture modification and gut-health positioning. Benelux and Scandinavian processors lead formulation adoption, pressured by retailer clean-label requirements and EU Green Deal carbon accounting mandates.
- Dietary Supplements:Capsule, sachet, and stick-pack formats target direct-to-consumer subscription models through Nordic wellness platforms. Danish and Swedish consumers show highest penetration rates for monthly delivery services bypassing traditional pharmacy markups.
- Functional Foods:Bakery, cereal, and savory applications utilize lower-purity grades with cost-driven procurement.
- Beverages:Shelf-stable and chilled drink systems require high-solubility oligosaccharide variants with clarified sensory profiles.
Margin concentration favors dietary supplements. Volume scale concentrates in dairy products.
Form:
Application requirements and handling economics segment the market across four physical formats, with powder dominance giving way to differentiated delivery systems in premium channels.
- Powder:Spray-dried or crystallized materials with 90%+ dry matter purity constitute the baseline specification for food-grade applications. German and French ingredient distributors handle bulk tonnage for manufacturing customers, with Rhine-Ruhr logistics hubs consolidating regional supply.
- Liquid:Aqueous solutions or syrups enable direct pumping into continuous dairy processing lines without rehydration stages. Dutch dairy cooperatives favor liquid inulin for fermented milk production, reducing powder handling infrastructure.
- Granular:Agglomerated particles improve flow properties for tableting operations and dry-mix applications.
- Tablet:Compressed solid-dose formats target pharmacy and health food retail channels with precise unit-dose convenience.
Processing efficiency sustains powder leadership. Consumer convenience drives tablet expansion.
Distribution Channel:
Customer type segmentation separates institutional procurement from retail-facing transactions, with digital platforms disrupting traditional wholesale structures across European markets.
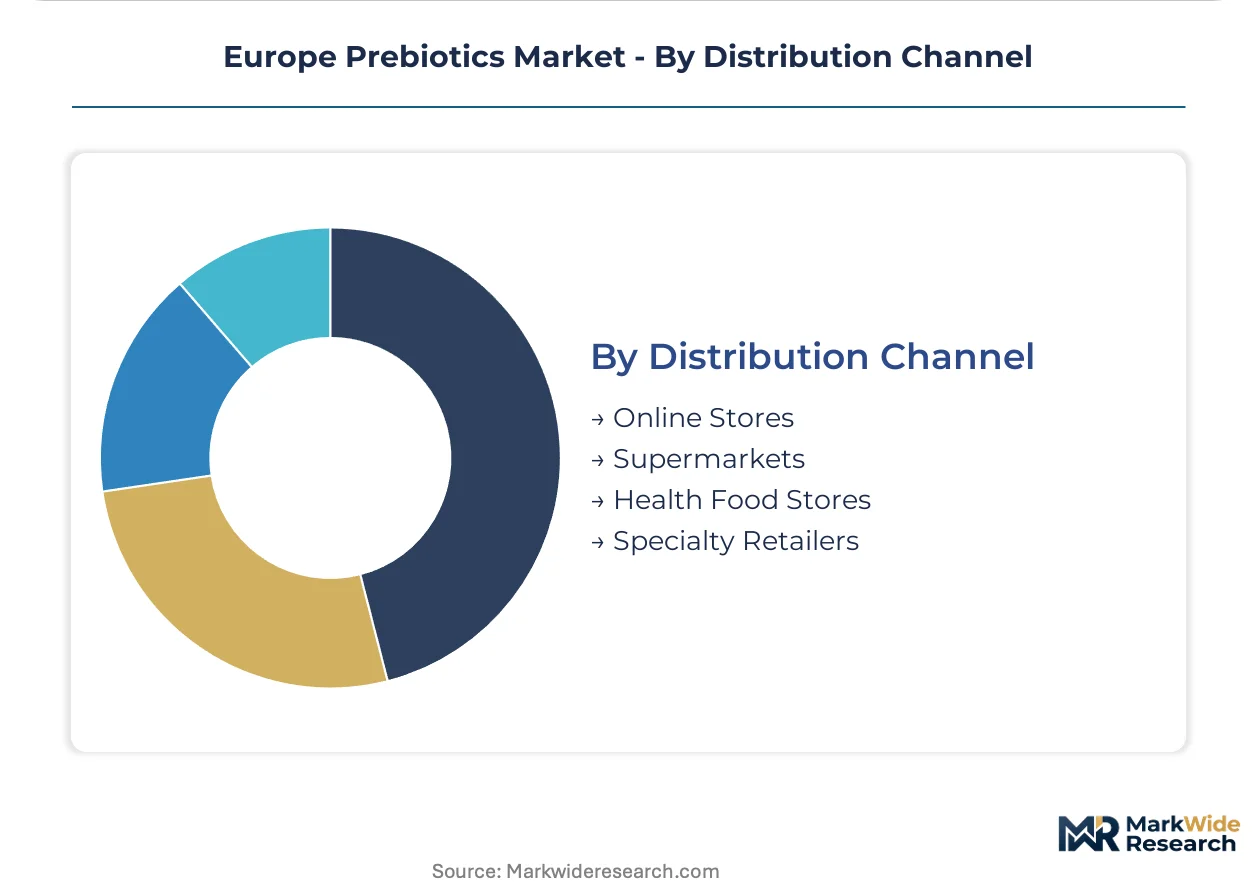
- Online Stores:Direct-to-consumer platforms and B2B ingredient marketplaces are capturing share fastest from conventional distributors. Nordic subscription services and German specialized wellness sites bypass retail markups, supported by GDPR-compliant customer data utilization for personalized recommendations.
- Supermarkets:Mass-market retail chains in France and Germany stock finished prebiotic supplements alongside functional dairy aisles, with private-label programs pressuring branded supplier margins.
- Health Food Stores:Independent and chain specialty retailers emphasize organic and non-GMO certified products with premium positioning.
- Specialty Retailers:Pharmacy and medical nutrition channels serve infant formula and clinical dietary segments with professional recommendation dependencies.
Volume flows through supermarkets. Value creation shifts toward online stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate enzymatic processing capacity toward jurisdictions with streamlined EFSA novel food pathways and lower carbon-accounting compliance costs. Belgium and the Netherlands retain raw material dominance, while Germany and France capture value-added formulation.
Germany
Rhine-Ruhr manufacturing corridor processors expand chicory-derived inulin refining for dairy fortification programs. EFSA Regulation 1924/2006 compliance investments concentrate in North Rhine-Westphalia, where BENEO GmbH operates captive extraction infrastructure from farm-gate to refined oligosaccharides.
France
Roquette Frères anchors pea-derived prebiotic fiber production for plant-based dairy alternatives in the Hauts-de-France region. The EU Green Deal farm-to-fork strategy pressures Paris Basin manufacturers toward lower-carbon extraction certifications.
Netherlands
Dutch dairy cooperatives drive liquid inulin demand for continuous fermented milk processing lines. Tereos SA and Royal FrieslandCampina coordinate supply chain control across Friesland and Gelderland, leveraging Rotterdam logistics hubs for Benelux distribution.
Belgium
Chicory root harvest volatility concentrates extraction capacity in Flanders, where processors shift toward higher-purity inulin grades. REACH compliance for novel oligosaccharide intermediates creates regulatory moats against Asian entrants lacking European substance registrations.
Denmark
Chr. Hansen Holding A/S anchors pharmaceutical-channel galacto-oligosaccharide production for infant formula segments with EFSA-authorized health claims. Copenhagen-based subscription wellness platforms bypass traditional pharmacy markups through direct-to-consumer sachet deliveries.
Europe Prebiotics Market Competitive Landscape
Belgian and Dutch producers anchor one tier through captive chicory supply; German and French specialists hold another through enzymatic processing scale. The vendor base stratifies across three strategic archetypes: vertically integrated agricultural processors, diversified ingredient conglomerates, and precision fermentation technology providers. Capacity expansion and portfolio diversification dominate competitive moves as participants defend margin position against plant protein fiber substitution.
Within the integrated-processor tier, BENEO GmbH exemplifies backward integration from chicory farming to refined oligosaccharides, while Roquette Frères occupies a position specializing in pea-derived alternatives for plant-based applications. Cargill represents the diversified conglomerate archetype with supply chain control over non-European raw material sources. These three anchors collectively illustrate the geographic and technological fault lines shaping procurement decisions across German and French dairy manufacturing corridors.
| Leading Market Players |
|---|
| BENEO GmbH |
| Cargill |
| Ingredion Incorporated |
| Tereos SA |
| Südzucker Group |
| Royal FrieslandCampina |
| Kerry Group plc |
| Roquette Frères |
| Chr. Hansen Holding A/S |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EFSA-authorized health claim tiers and commodity bulk grades manifests in divergent margin structures and sourcing configurations across the European prebiotics value chain. Pharmaceutical-channel galacto-oligosaccharides command substantial premia through authorized bowel function claims, while standard-grade inulin for dairy fortification competes on extraction yield and logistics efficiency from Belgian chicory processors.
Pricing Analysis
Distributor margin layers in dietary supplement channels absorb 35-45 point markups before reaching Nordic direct-to-consumer platforms, compressing manufacturer netbacks against pharmacy retail alternatives. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized infant formula grades from clean-label dairy fortification and commodity bakery inputs. Pricing pressure stems from plant protein fiber substitution in plant-based dairy alternatives, with pea and oat fibers capturing formulation share. Dietary supplement subscription buyers show lowest price sensitivity due to wellness platform loyalty, while functional food manufacturers negotiate aggressively on volume contracts.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp consolidate hub-and-spoke patterns for Rhine-Ruhr manufacturing corridors, with liquid inulin pumped directly into Dutch dairy cooperative processing lines. Geographic supply concentration centers on Belgium, the Netherlands, and France for chicory root and pea-derived feedstocks. Raw material dependencies rest on South American agave for diversified oligosaccharide sources and lactose feedstocks for galacto-oligosaccharide production. Single-source vulnerability from Belgian chicory harvest volatility creates supply risk for inulin-dependent formulations. Distribution runs through specialized ingredient distributors for bulk food-grade supply, with direct-to-consumer platforms bypassing traditional wholesale tiers for finished supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe prebiotics market functions as a regulatory compounder where EFSA health claim authorizations under Regulation 1924/2006 determine permissible marketing language and R&D prioritization across the value chain.
For Market Incumbents: Lock in captive chicory supply through long-term farming contracts in Flanders and backward integration into extraction infrastructure, defending against Asian entrants blocked by REACH compliance barriers. Prioritize enzymatic processing capacity additions for higher-purity inulin grades that sustain margin differentiation from commodity alternatives. Certification investment in EU Green Deal carbon accounting creates competitive moats as clean-label requirements intensify across German and French dairy manufacturing corridors. For New Entrants and Emerging Players: Specialized wellness platforms in Poland and Romania represent the most penetrable channel layer, with underpenetrated direct-to-consumer subscription models offering whitespace beyond saturated Nordic markets. Precision fermentation technology providers should target bespoke oligosaccharide services for personalized nutrition startups seeking custom microbiome profiles. Go-to-market execution through GDPR-compliant digital health engagement enables bypass of established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA regulatory investment requirements exceed standalone R&D budgets for microbiome claim substantiation. Long-term viability favors vertically integrated operators with captive raw material supply and authorized health claim portfolios spanning bowel function and glycemic response endpoints. Acquisition target archetype: mid-scale enzymatic processors with novel food approval pipelines. Signal to watch: EFSA pending opinions on immune and cognitive health endpoints that would reshape permissible marketing language and authorization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Authorization Investment | Regulatory clarity on microbiome-related endpoints unlocks premium positioning in infant formula and medical nutrition channels. |
| Backward Integration into Chicory Farming | Captive raw material supply in Flanders secures cost leadership against agave-dependent competitors for standard-grade inulin. |
| Precision Fermentation Platform Development | Custom oligosaccharide profiles enable bespoke ingredient services for emerging personalized nutrition startups. |
| Direct-to-Consumer Subscription Launch | Nordic wellness platforms demonstrate bypass of retail markups through GDPR-compliant digital health engagement. |
| EU Green Deal Carbon Certification | Lower-carbon extraction credentials meet farm-to-fork strategy mandates from German and French dairy processors. |
Research Methodology
Bottom-up dairy and dietary supplement modeling reconciled against top-down chicory root harvest and enzymatic processing capacity tracking forms the analytical core of this study. Primary interviews with functional food R&D directors, EFSA regulatory affairs consultants, Dutch dairy cooperative procurement managers, and Nordic direct-to-consumer platform operators combined with secondary validation from EFSA novel food approval databases, EU customs trade statistics, REACH substance inventory listings, and industry association production surveys.
Input-output matrices segment volume and value projections across product type, end-use application, physical form, and distribution channel dimensions throughout the forecast period. CAGRs derive from modeled adoption curves for EFSA-authorized health claim tiers against commodity bulk substitution rates, with sensitivity analysis for chicory root harvest volatility and plant protein fiber competitive encroachment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pending EFSA opinions on microbiome-related claims and EU Green Deal carbon accounting implementation timelines. Outputs reflect documented assumptions around regulatory authorization probabilities and raw material supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Very Low Calorie Desserts Market