
 Marine Functional Ingredients Market | 2026-2036
Marine Functional Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Functional Ingredients Market Analytics
Pharmaceutical-grade omega-3 concentrates is reorganizing competitive dynamics across the marine functional ingredients landscape. Aker BioMarine leverages Antarctic krill traceability to dominate premium phospholipid-bound omega-3 supply. DSM sustains technology leadership in algal-derived EPA/DHA fermentation, while Croda specializes in high-purity lipid formulations for clinical nutrition applications.
Marine functional ingredients comprise bioactive compounds extracted from aquatic organisms, including long-chain polyunsaturated fatty acids with minimum 90% EPA/DHA ethyl ester concentration, hydrolyzed collagen peptides under 3000 daltons, and sulfated polysaccharides from red algae, serving targeted physiological functions in human and animal health. Omega-3 fatty acids anchor the value pool through established cardiovascular and cognitive health claims, while marine collagen generates accelerating demand in dermal regeneration and sports recovery applications. Carrageenan occupies mature volume positions in food texture modification, whereas algal oil extends the source base beyond wild fisheries toward controlled cultivation systems.
EMA guidelines on novel food safety assessments, REACH substance registration for marine-derived imports, and EU Green Deal due diligence requirements collectively tighten compliance thresholds for European market access. FDA GRAS notifications and FSSAI functional food approvals create parallel regulatory pathways in North America and India, respectively. Stakeholders must monitor evolving maximum residue limits for ocean pollutants and invest in alternative aquaculture feedstocks to secure long-term ingredient certification.
Market Dynamics
Antarctic krill traceability systems and algal fermentation platforms are compressing sourcing timelines while EU Green Deal due diligence mandates force ingredient suppliers to document every vessel and cultivation batch.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Wild-caught fish derivative suppliers must install blockchain-tracked provenance systems. French and German nutraceutical manufacturers now require batch-level ocean origin documentation.
- South Korea functional food sector expansion:Marine-derived omega-3 fortification in ready-to-drink beverages has created a mainstream retail category. Domestic beverage conglomerates are locking multi-year phospholipid supply contracts.
- Algal oil fermentation technology:Controlled cultivation systems bypass wild fishery volatility entirely. DSM and specialty biotech firms are scaling photobioreactor capacity for pharmaceutical-grade EPA/DHA.
Market Restraints
- Polar cod and Antarctic krill supply concentration:Aker BioMarine controls the majority of traceable krill phospholipid output. Any vessel certification suspension creates immediate premium segment shortages.
- REACH substance registration costs:European manufacturers face escalating compliance expenditures for novel marine peptide imports. Small-batch hydrolyzed collagen suppliers are exiting the EU market entirely.
- Plant-derived omega-3 substitution:Flaxseed and ahiflower oil formulations are capturing economy-tier supplement shelf space. Price-sensitive consumers accept lower bioavailability for 40% cost reduction.
Strategic Opportunities
- Indian functional food regulatory pathway:FSSAI functional food approvals for marine collagen remain underutilized. Domestic Ayurveda-nutraceutical hybrids present white space for joint health positioning.
- Sports recovery application expansion:Hydrolyzed marine collagen peptides under 3000 daltons are penetrating endurance athlete nutrition. Powder sachet formats are displacing gelatin-based alternatives in triathlon and cycling segments.
- EMA novel food safety assessment streamlining:Accelerated evaluation pathways for red algae sulfated polysaccharides would unlock clinical nutrition applications. Early movers in carrageenan-derived therapeutics gain 18-24 month market exclusivity.
Industry Challenges
- Marine biotechnology talent scarcity:Phycologists with industrial fermentation expertise command 40% salary premiums. European universities produce insufficient graduates for expanding algal oil capacity.
- Ocean pollutant residue testing backlogs:Maximum residue limit certification for heavy metals and microplastics now requires 90-120 day laboratory queues. Inventory carrying costs are compressing working capital for mid-tier traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Functional Ingredients Market |
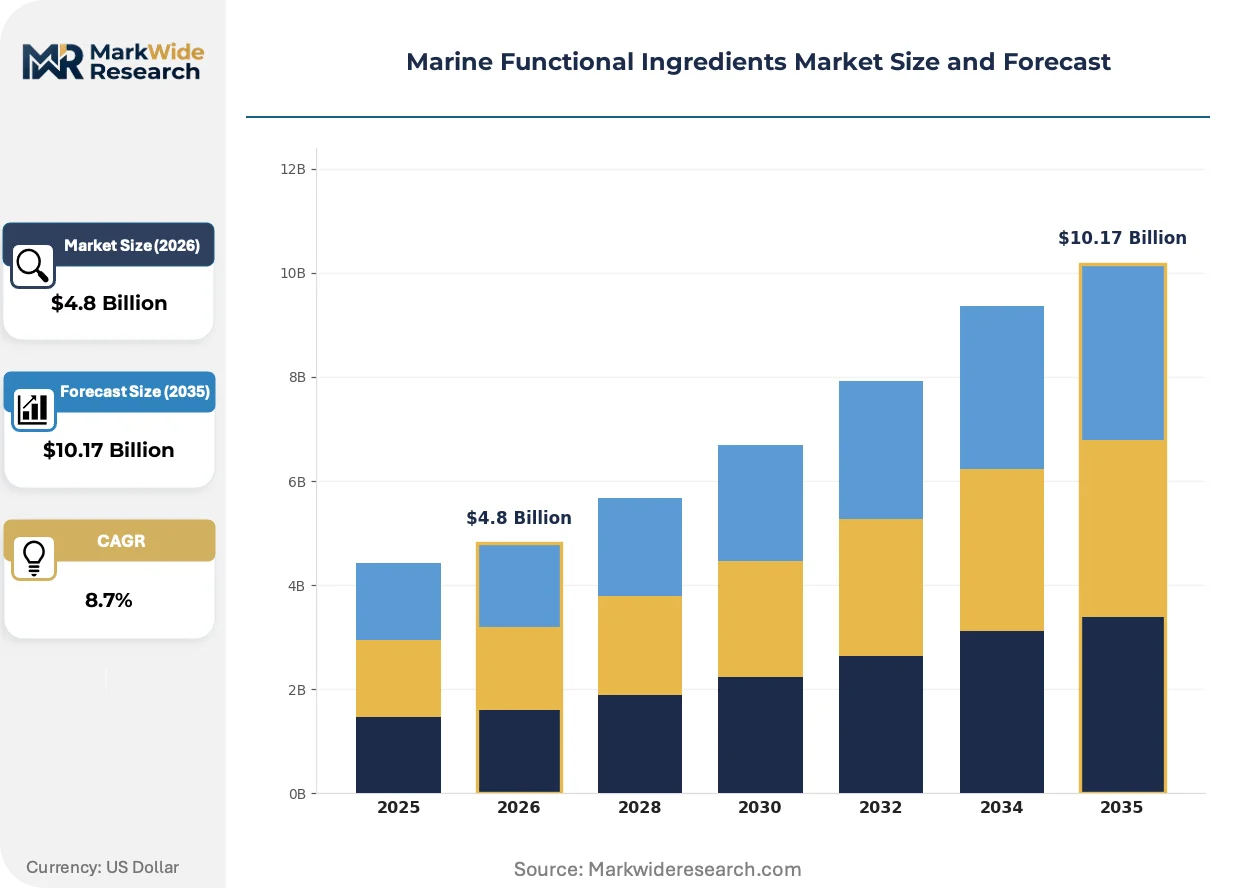
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
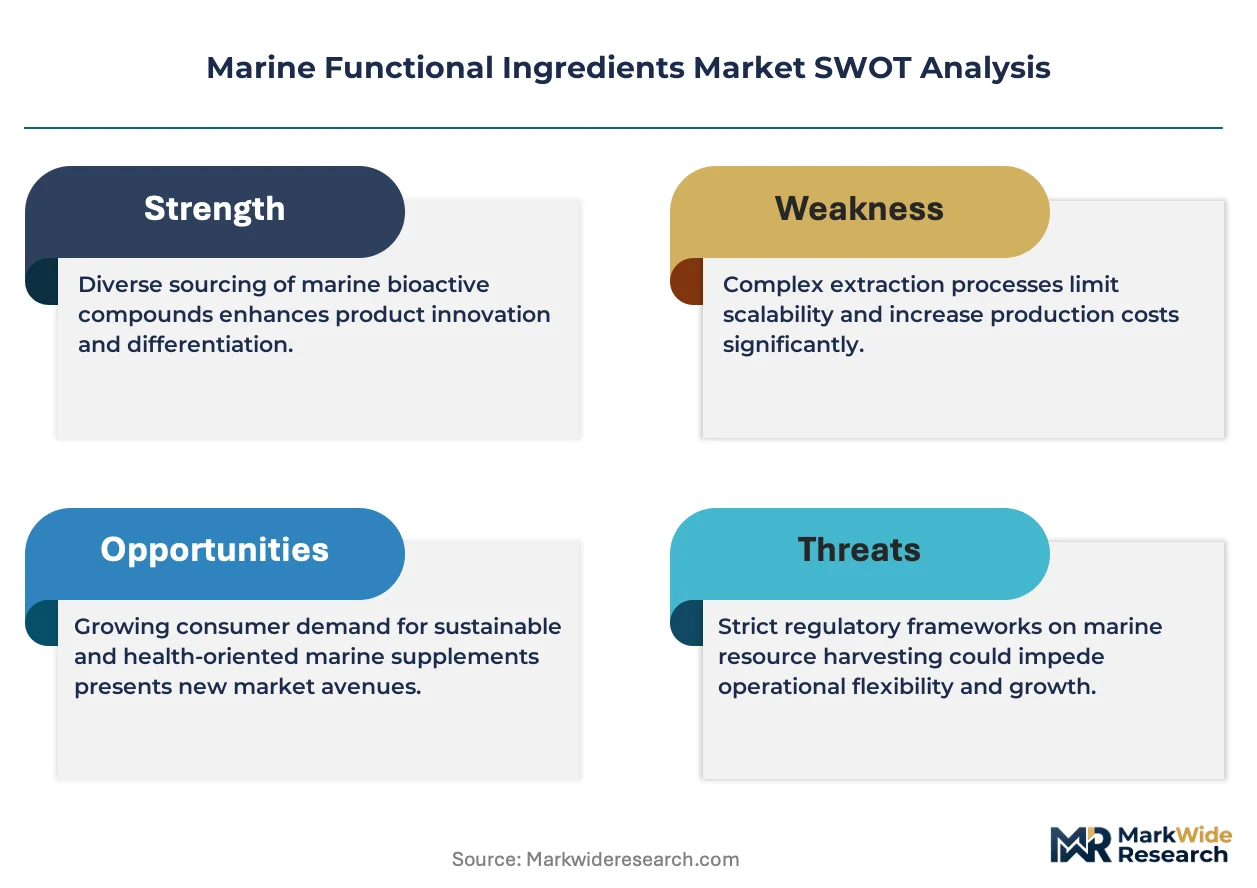
| Segmentation | Product Type: Omega-3 Fatty Acids, Marine Collagen, Carrageenan, Algal Oil Application: Dietary Supplements, Functional Foods, Personal Care, Animal Nutrition Source: Fish, Seaweed, Shellfish, Krill End User: Food Industry, Pharmaceutical Sector, Cosmetics Industry, Nutraceuticals |
| Companies Covered | Aker BioMarine, DSM, BASF, Croda, Nitta Gelatin, Nippon Suisan, Gelita, Golden Omega, Rousselot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Functional Ingredients Market Evolving Landscape
Enzymatic hydrolysis and precision fermentation are collapsing traditional extraction economics while regulatory data requirements force suppliers to rebuild quality infrastructure from vessel to vial.
Sub-critical water extraction technology is decomposing conventional organic solvent processing for sulfated polysaccharide recovery. Red algae processors in Brittany and Nova Scotia are retrofitting facilities to eliminate hexane residual concerns. This shift is decomposing the cost advantage of legacy Asian solvent-based operations that lack EFSA-compliant documentation systems.
EMA guidelines on novel food safety assessments now mandate 90-day toxicology studies for all new marine peptide entrants. European contract research organizations have tripled capacity for aquatic-derived ingredient evaluation. Clinical nutrition and infant formula segments are absorbing these validation costs fastest, while sports nutrition brands delay launches pending dossier completion.
Direct-to-brand procurement is consolidating previously fragmented krill oil purchasing. Antarctic vessel operators now bypass trading houses to contract directly with German and South Korean finished goods manufacturers. This disintermediation is most visible in Seoul, where functional beverage conglomerates have installed dedicated procurement teams in Punta Arenas sourcing offices.
Marine Functional Ingredients Market Segmentation
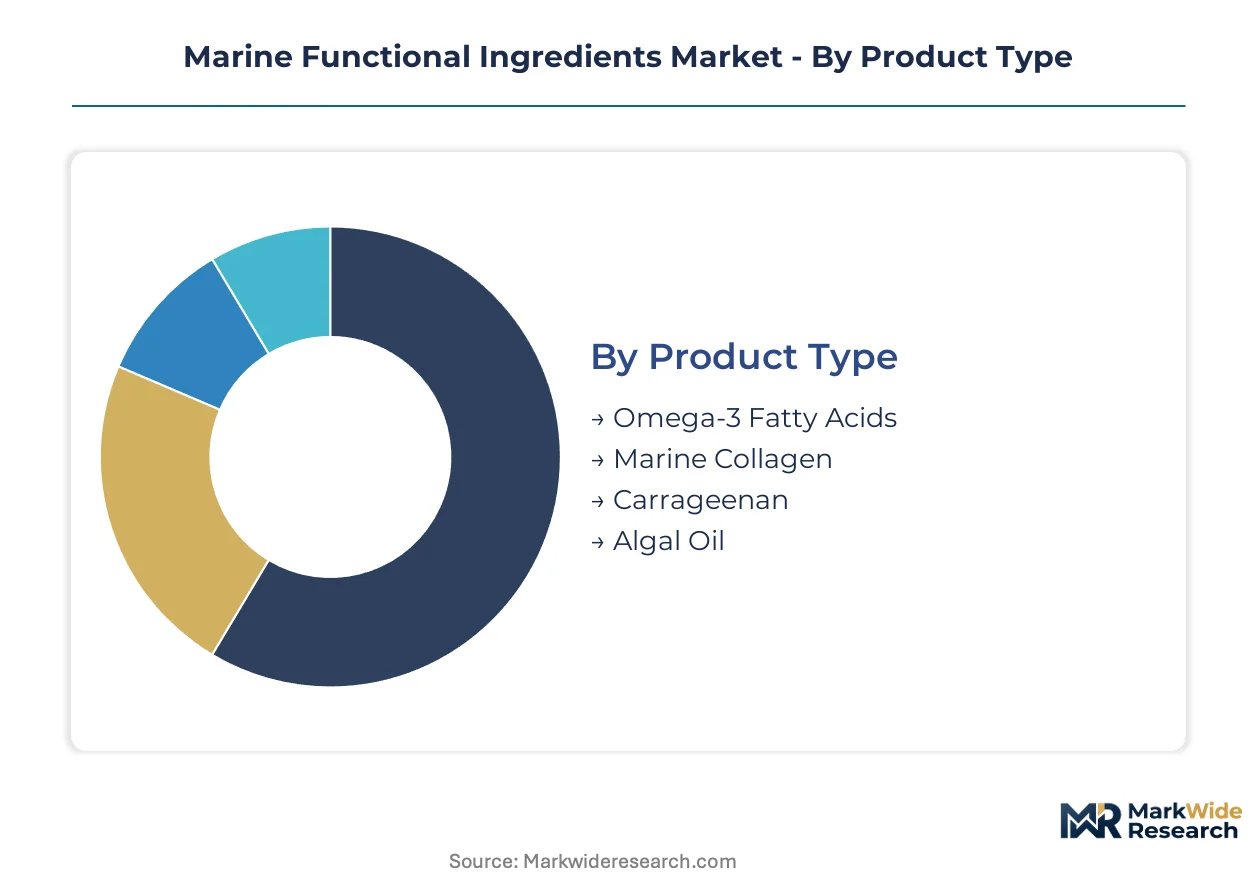
Marine functional ingredients traverse highly divergent commercial pathways depending on molecular complexity and certification requirements. Pharmaceutical-grade lipids command dedicated distribution infrastructure, while commodity hydrocolloids flow through bulk ingredient traders.
Product Type:
Channel mix varies sharply: omega-3 concentrates move through pharmaceutical distributors and direct-to-manufacturer contracts, whereas carrageenan ships via commodity chemical traders.
- Omega-3 Fatty Acids:Long-chain polyunsaturated fatty acids with minimum 90% EPA/DHA ethyl ester concentration anchor premium positioning. Demand concentrates in German and South Korean nutraceutical manufacturing, where cardiovascular health claims drive formulation decisions. EMA novel food assessments and MFDS functional food approvals create parallel compliance pathways.
- Marine Collagen:Hydrolyzed peptides under 3000 daltons penetrate sports recovery and dermal regeneration segments. French and German manufacturers are expanding procurement for joint health formulations, while FSSAI approvals in India remain underutilized for Ayurveda-nutraceutical hybrids.
- Carrageenan:Sulfated polysaccharides from red algae serve mature food texture modification applications.
- Algal Oil:Controlled cultivation systems bypass wild fishery volatility through photobioreactor platforms.
By volume, carrageenan leads. By growth pace, algal oil is expanding most quickly.
Application:
Cost tier stratification separates clinical nutrition from mass-market fortification, with certification grade determining margin structure.
- Dietary Supplements:Softgel and liquid formulations dominate cardiovascular and cognitive health positioning. South Korean beverage conglomerates are locking multi-year phospholipid supply contracts for ready-to-drink omega-3 fortification.
- Functional Foods:Ready-to-drink beverages and fortified dairy represent the fastest-climbing application trajectory. Seoul-based procurement teams now source directly from Antarctic vessel operators, bypassing traditional trading houses.
- Personal Care:Dermal regeneration claims drive marine collagen peptide incorporation.
- Animal Nutrition:Aquaculture feedstock applications face EU Green Deal sustainable sourcing mandates.
Pharmaceutical-grade specifications command triple the margin of food-grade alternatives.
Source:
Supply concentration creates divergent risk profiles: wild-catch fisheries face traceability mandates while controlled cultivation offers batch consistency.
- Fish:Wild-caught anchovy and sardine derivatives require blockchain-tracked provenance systems under EU Green Deal due diligence. French manufacturers now mandate batch-level ocean origin documentation.
- Krill:Antarctic vessel operations dominate traceable phospholipid-bound omega-3 supply. Direct-to-brand procurement is consolidating previously fragmented purchasing.
- Seaweed:Red algae cultivation in Brittany and Nova Scotia is retrofitting for sub-critical water extraction.
- Shellfish:Chitin and chitosan derivatives serve niche biomedical applications.
Wild sources retain volume leadership; fermentation platforms gain share fastest.
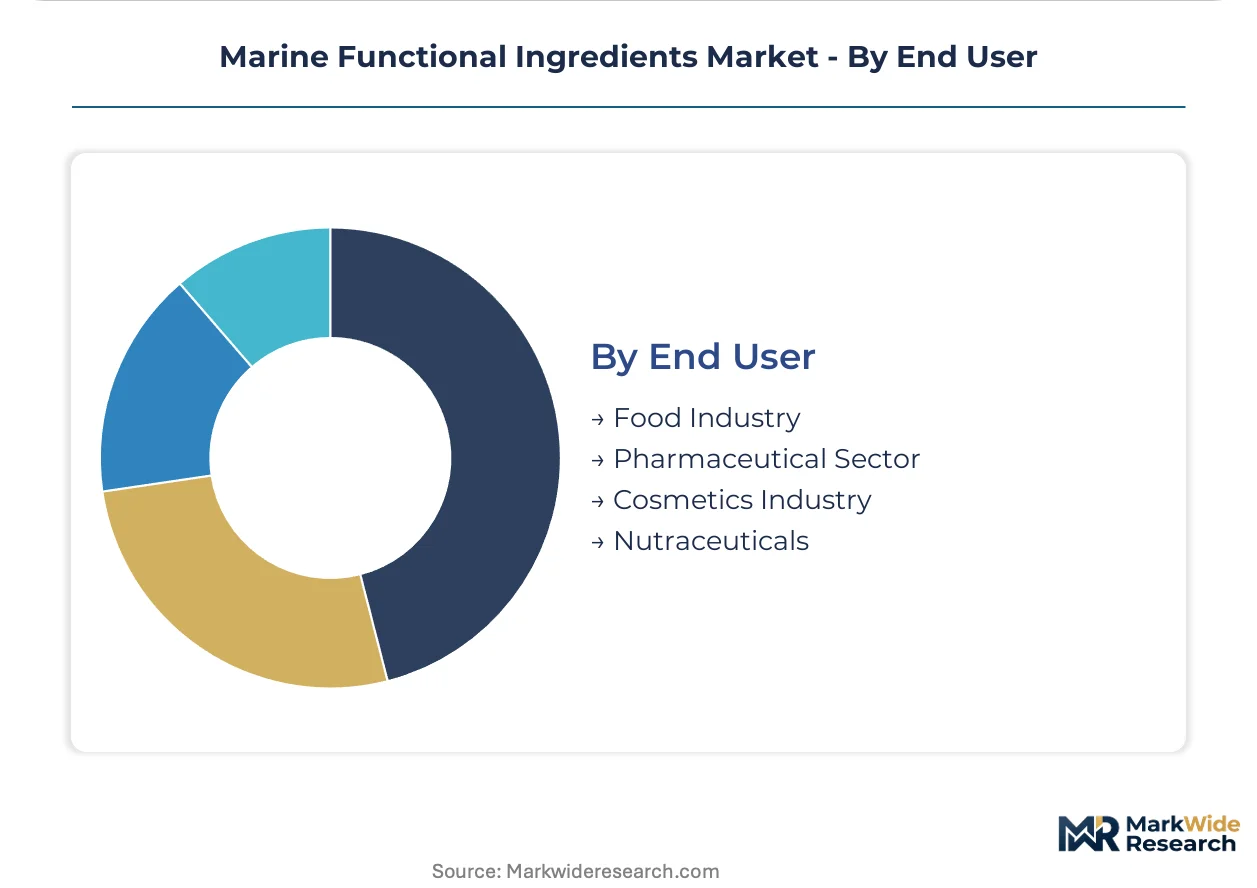
End User:
Customer type determines specification stringency: pharmaceutical buyers enforce pharmacopeial compliance while cosmetics manufacturers prioritize sensory attributes.
- Pharmaceutical Sector:Clinical nutrition and infant formula segments absorb EMA toxicology validation costs fastest. High-purity lipid formulations for enteral feeding require dedicated manufacturing infrastructure.
- Nutraceuticals:Sports nutrition brands delay peptide launches pending 90-day dossier completion, while endurance athlete powder sachets displace gelatin alternatives.
- Food Industry:Texture modification and fortification applications span mature carrageenan use.
- Cosmetics Industry:Dermal regeneration marketing drives marine collagen incorporation.
Pharmaceutical buyers pay certification premiums; nutraceuticals represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antarctic krill harvesting concentrates in Norwegian-controlled vessel operations, while algal fermentation platforms cluster in Dutch and German biotechnology corridors. Traceability mandates from Brussels reshape procurement patterns across every major demand center.
South Korea
Seoul-based beverage conglomerates drive phospholipid-bound omega-3 demand through ready-to-drink fortification. MFDS functional food approvals streamline novel marine peptide market entry. Dedicated procurement teams now operate from Punta Arenas sourcing offices, bypassing traditional trading intermediaries entirely.
Germany
Nutraceutical manufacturers in Hamburg and Frankfurt expand marine collagen peptide procurement for joint health formulations. EU Green Deal due diligence mandates require blockchain-tracked provenance documentation from every vessel. The Baden-Württemberg biotechnology cluster hosts expanding photobioreactor capacity for pharmaceutical-grade algal oil.
United States
FDA GRAS notifications create a parallel regulatory pathway for novel marine-derived ingredients. Clinical nutrition manufacturers absorb EMA-equivalent toxicology validation costs fastest. Boston and San Diego harbor the dominant contract research organization capacity for aquatic-derived ingredient safety assessment.
France
Brittany's red algae processors retrofit facilities for sub-critical water extraction to eliminate hexane residual concerns. ANSM enforces REACH substance registration compliance for hydrolyzed collagen imports. Rousselot and Nitta Gelatin maintain production presence in the Angers industrial zone for dermal regeneration peptide supply.
India
FSSAI functional food approvals for marine collagen remain underutilized relative to market potential. Domestic Ayurveda-nutraceutical hybrids present white space for joint health positioning. Maharashtra and Gujarat house the dominant bulk ingredient trading infrastructure for Southeast Asian hydrocolloid re-exports.
Marine Functional Ingredients Market Competitive Landscape
Concentration sits with Antarctic krill harvesters and algal fermentation specialists who control traceable supply of premium phospholipid-bound omega-3. Three archetypes dominate: vertically integrated harvester-processors, biotechnology platform operators, and hydrolyzed peptide specialists. Capacity expansion in photobioreactor infrastructure and direct-to-brand procurement consolidation represent the dominant competitive vectors reshaping intermediary economics.
Among Norwegian and Dutch biotechnology platforms, Aker BioMarine exemplifies the harvester-processor archetype through Antarctic vessel traceability systems. DSM represents controlled cultivation fermentation leadership with pharmaceutical-grade EPA/DHA platforms. Croda occupies the high-purity lipid formulation tier for clinical nutrition applications. These three anchors illustrate how technology specialization and geographic sourcing control stratify competitive positioning across premium, standard, and economy certification grades.
| Leading Market Players |
|---|
| Aker BioMarine |
| DSM |
| BASF |
| Croda |
| Nitta Gelatin |
| Nippon Suisan |
| Gelita |
| Golden Omega |
| Rousselot |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with Antarctic vessel operators lock phospholipid-bound omega-3 supply for German and South Korean nutraceutical manufacturers while anchoring price visibility against wild fishery volatility. These arrangements concentrate procurement power among beverage conglomerates and clinical nutrition formulators who can commit to multi-year volume minimums.
Pricing Analysis
EU Green Deal due diligence mandates dictate the pricing tier structure across marine functional ingredients. Certification grade and volume scale separate pharmaceutical-grade EPA/DHA concentrates from economy-tier algal oil alternatives. Cost compression in commodity hydrocolloids intensifies as Asian solvent-based carrageenan processors lack EFSA-compliant documentation. Sports nutrition brands exhibit highest price sensitivity, while infant formula manufacturers absorb validation premiums without volume reduction.
Supply Chain Analysis
Port congestion at Punta Arenas and container availability constraints on the Asia-South America trade lane elevate inbound logistics costs for Antarctic krill derivatives. Supply concentrates in Norway, the Netherlands, and South Korea, with raw material dependencies on wild-caught polar cod, photobioreactor algae feedstock, and red algae biomass from Brittany. Single-source vulnerability around Aker BioMarine's vessel certification creates immediate shortage risk. Distribution runs through direct-to-manufacturer contracts that displace traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated finished goods manufacturers who deploy dedicated procurement teams at source, fragmenting leverage among mid-tier ingredient traders who lack vessel relationships or fermentation capacity.
For Market Incumbents: Shield premium positioning by deepening captive supply of traceable Antarctic krill phospholipids before algal fermentation platforms achieve cost parity. Invest in EMA-compliant toxicology dossiers for novel marine peptides to extend certification moats against emerging biotech entrants. Channel control through direct-to-brand contracts in Seoul and Hamburg reinforces pricing power. For New Entrants and Emerging Players: FSSAI functional food fast-tracks for marine collagen offer the most penetrable regulatory pathway into India's underdeveloped Ayurveda-nutraceutical hybrid segment. Target sports recovery powder sachets for endurance athletes as the go-to-market angle, leveraging lower REACH compliance burdens by sourcing from non-EU hydrolysis facilities. For Investors and Strategic Acquirers: Algal oil fermentation specialists with photobioreactor capacity and pharmaceutical-grade EPA/DHA certifications represent the priority acquisition archetype for long-term viability across the analysis window. Watch for MFDS accelerated approval pathways for novel marine peptides as the inflection signal indicating regulatory arbitrage opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antarctic Vessel Operations | Captive supply secures traceability documentation required by EU Green Deal mandates. |
| Photobioreactor Capacity Expansion | Controlled cultivation bypasses wild fishery volatility and ocean pollutant residue testing backlogs. |
| EMA Novel Food Dossier Investment | Accelerated toxicology validation unlocks 18-24 month exclusivity in clinical nutrition applications. |
| Direct-to-Brand Procurement Consolidation | Bypassing trading houses captures margin compression from Seoul-based beverage conglomerates. |
| Sub-Critical Water Extraction Retrofit | Eliminates hexane residual concerns for EFSA compliance in red algae sulfated polysaccharides. |
Research Methodology
Cross-validation between primary interviews with Antarctic vessel operators, algal fermentation R&D directors, and nutraceutical procurement leads anchors the qualitative findings against secondary validation from EMA novel food submission databases, FSSAI functional food approval registries, and EU customs trade records. Bottom-up triangulation across ingredient-grade volume estimates and top-down demand modeling from finished goods manufacturers ensures convergence.
Sensitivity analysis around regulatory approval timelines and wild fishery catch quota volatility shapes the analytical framework across the projection horizon. Segmentation dimensions include molecular complexity tier, certification grade, source type, and end-use application intensity. CAGRs derive from historical volume trajectories adjusted for algal fermentation capacity buildout and EU traceability mandate compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or breakthroughs in plant-derived omega-3 bioavailability enhancement would require recalibration. Forecasts reflect assumptions around REACH registration cost trajectories and maximum residue limit certification queue durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Asia-Pacific Functional Water Market