
 Low Fat Protein Market | 2026-2036
Low Fat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Protein Market Analytics
FDA nutrition labeling reforms is decoupling legacy formulations from shelf eligibility, forcing reformulation investments that favor scaled manufacturers. Cargill leverages its integrated oilseed processing network to secure cost-advantaged soy protein isolate supply. Kerry Group anchors its position through flavor-mask technology that improves palatability of reduced-fat protein systems. Glanbia plc specializes in grass-fed whey sourcing, differentiating its ingredient catalog for premium sports nutrition contracts.
Low fat protein denotes protein isolates and concentrates processed to contain reduced lipid content, typically achieving less than two percent fat by dry weight through membrane filtration or solvent extraction methods, serving primarily as functional ingredients in fortified foods and performance nutrition. Whey protein dominates volume due to its complete amino acid profile and rapid absorption kinetics, while pea protein captures accelerating demand from allergen-free and vegan formulation pipelines. The application split reveals sports nutrition as the established margin pool, whereas health foods represents the fastest-growing channel as mainstream retailers expand functional shelf space.
USDA organic certification, FDA GRAS self-affirmation requirements, and EU EFSA health claim authorization collectively determine which protein products achieve retail distribution and marketing legitimacy in major economies. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established regulatory dossiers and analytical capabilities. Stakeholders must monitor evolving protein content verification protocols and emerging sustainability disclosure obligations as these criteria increasingly filter procurement decisions across food and beverage value chains.
Market Dynamics
Membrane filtration cost curves and FDA nutrition labeling reforms are forcing simultaneous capital deployment and reformulation cycles across whey and plant protein supply chains.
Growth Catalysts
- EU EFSA health claim authorization:Substantiated protein quality claims unlock premium shelf positioning in German and French retail channels, accelerating isolate procurement.
- Sports nutrition contract consolidation:Performance nutrition brands now specify grass-fed whey and allergen-free pea isolates in multi-year supply agreements.
- Membrane filtration scale-up:Cross-flow microfiltration technology reduces lipid content below two percent at unit costs that displace solvent extraction in new capacity installations.
Market Restraints
- Organic dairy input volatility:Grass-fed whey supply depends on pasture-availability cycles in New Zealand and Ireland, creating protein concentrate price spikes.
- Soy protein supply concentration:North American oilseed processing infrastructure concentrates isolate production among three integrated agribusiness networks.
- Flavor-mask technology dependency:Reduced-fat protein systems require Kerry Group's proprietary palatability solutions, creating single-source formulation risk.
Strategic Opportunities
- China fitness retail expansion:Tier-one city gym chains and e-commerce platforms are building dedicated functional nutrition sections with imported isolate SKUs.
- USDA organic certification tailwind:Federal procurement preferences and retailer slotting fee waivers reward certified organic protein suppliers.
- Precision fermentation convergence:Microbial protein platforms combined with AI-driven strain optimization promise lipid-free protein without agricultural feedstock constraints.
Industry Challenges
- GRAS self-affirmation timeline compression:Novel protein sources face eighteen-to-twenty-four-month FDA safety dossier preparation cycles that delay commercialization.
- Multi-certification stacking costs:Simultaneous pursuit of USDA organic, Non-GMO Project, and B Corp status strains mid-tier processor administrative bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Protein Market |
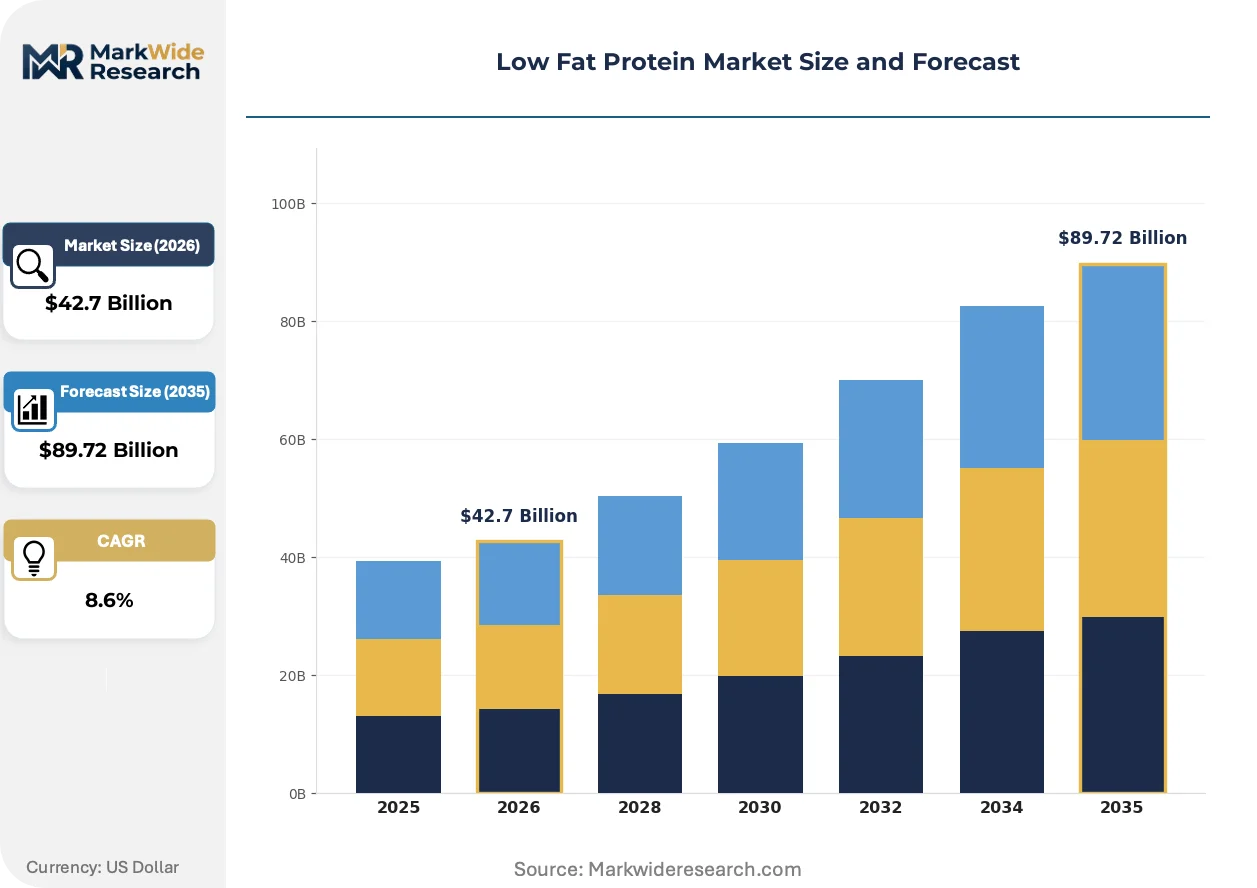
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Sports Nutrition, Dietary Supplements, Food & Beverages, Health Foods End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Bodybuilders Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Koninklijke DSM N.V., Archer Daniels Midland Company, Cargill, Kerry Group, Tate & Lyle PLC, Glanbia plc, Ingredion, Roquette Frères, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Protein Market Evolving Landscape
Automation of quality verification and tightening regulatory substantiation requirements are compressing product development timelines while elevating analytical capability thresholds across the value chain.
Cross-flow ceramic membrane systems is automating lipid separation in whey processing facilities, enabling real-time fat-content monitoring that eliminates batch-rework cycles. Sports nutrition contract manufacturers in the United States and Germany are retrofitting existing plants with these systems at twelve-to-eighteen-month payback periods. The technology is automating quality-control labor out of isolate production while tightening specification bands to under one percent residual fat.
EU EFSA health claim substantiation rules now require randomized controlled trials for protein-specific physiological benefit claims, forcing ingredient suppliers to sponsor clinical research programs. This regulatory burden filters marketing legitimacy toward incumbents with established dossiers and analytical laboratories. Premium sports nutrition brands targeting German and French consumers are reformulating around EFSA-approved protein quality metrics.
Direct-to-consumer subscription models are displacing traditional sports nutrition wholesale distribution in North American and European urban markets. Performance-focused consumers now expect personalized protein dosing algorithms and flavor rotation delivered through mobile-optimized replenishment platforms. This channel shift concentrates customer data ownership with isolate suppliers who integrate fulfillment technology, particularly visible in California and London metropolitan clusters.
Low Fat Protein Market Segmentation
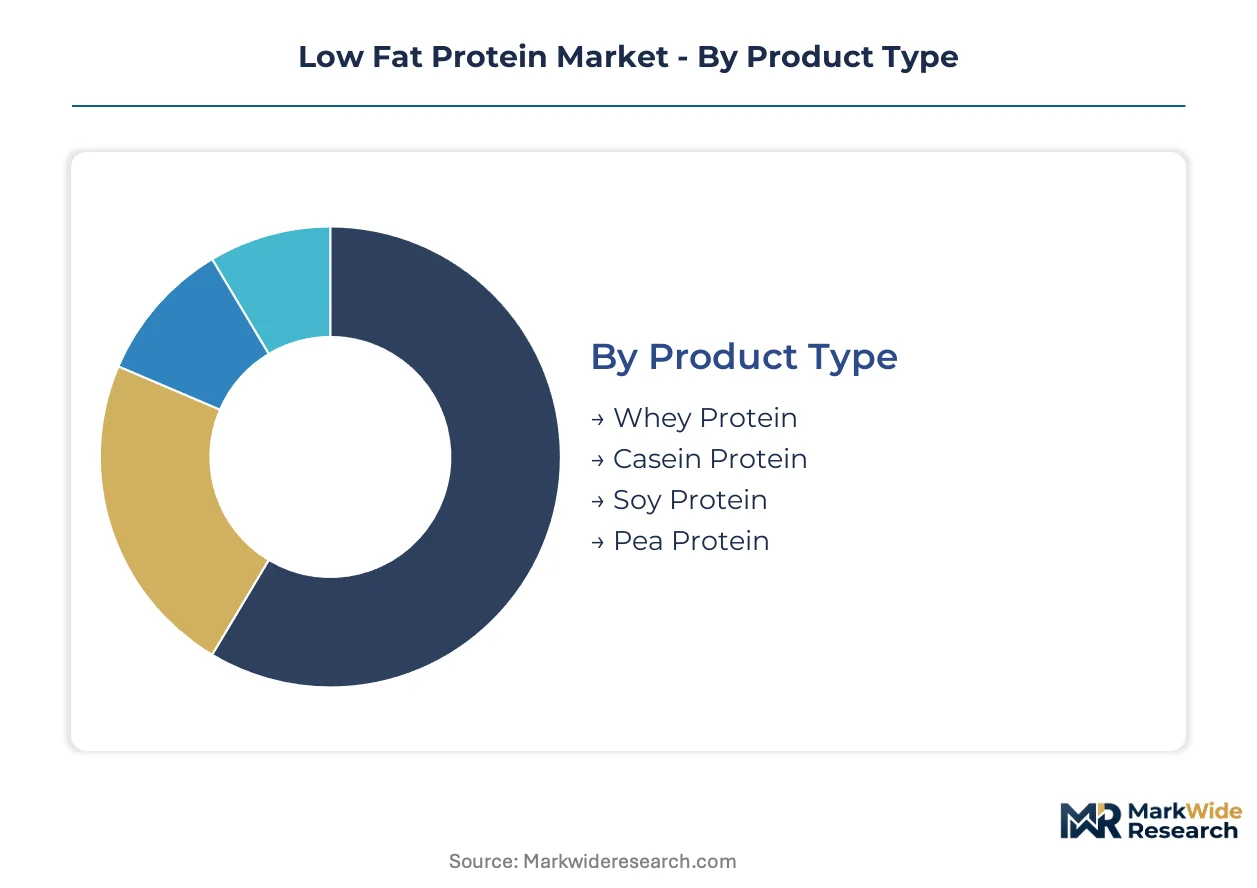
Low fat protein procurement patterns diverge sharply across product chemistry, end-use application, and channel structure. Each segmentation axis reveals distinct margin pools, regulatory exposure, and supply chain concentration that determine competitive positioning.
Product Type:
Membrane filtration scale-up and solvent extraction economics concentrate supply among integrated processors with captive dairy or oilseed infrastructure.
- Whey Protein:Rapid-absorption isolate with complete essential amino acid profile achieves under two percent residual fat through cross-flow microfiltration. Sports nutrition contract manufacturers in the United States and Germany specify this grade in multi-year procurement agreements, though grass-fed supply volatility in New Zealand and Ireland creates price spikes.
- Pea Protein:Allergen-free isolate extracted via wet-milling and air-classification serves vegan formulation pipelines and clean-label positioning. Health-conscious consumers in California and London metropolitan clusters drive accelerating demand through direct-to-consumer subscription channels.
- Casein Protein:Slow-digesting micellar structure supports overnight recovery formulations with extended amino acid release kinetics.
- Soy Protein:Cost-advantaged isolate from North American oilseed processing networks dominates economy-tier fortified foods.
Today's leader: Whey Protein. Tomorrow's challenger: Pea Protein.
Application:
Channel-specific regulatory requirements and formulation complexity create tiered margin structures that favor specialized suppliers over commodity processors.
- Sports Nutrition:Performance-oriented powders, bars, and ready-to-drink formats require EFSA-substantiated protein quality claims for German and French retail placement. FDA GRAS self-affirmation timelines compress product development cycles for novel isolate blends entering this channel.
- Health Foods:Functional positioning in mainstream retail expansion captures fitness-adjacent consumers seeking fortified snacks and beverages. China tier-one city gym chains and e-commerce platforms are building dedicated sections with imported isolate SKUs, expanding most quickly among application categories.
- Dietary Supplements:Capsule and tablet formats prioritize protein density and shelf stability over palatability optimization.
- Food & Beverages:Beverage fortification and bakery applications demand flavor-mask technology integration for consumer acceptance.
Sports Nutrition commands premium positioning. Health Foods is climbing the fastest.
End User:
Usage intensity and nutritional literacy stratify purchasing behavior from institutional procurement to individual replenishment platforms.
- Athletes:Performance-optimized dosing protocols and batch-tested certification requirements dominate procurement criteria for competitive and professional segments.
- Fitness Enthusiasts:Regular gym attendance drives subscription-based replenishment through mobile-optimized platforms with personalized flavor rotation.
- Health-Conscious Consumers:Clean-label priorities and allergen avoidance steer formulation preferences toward organic-certified and plant-derived isolates.
- Bodybuilders:High-volume protein consumption prioritizes cost-per-gram efficiency and leucine content maximization.
Athletes anchor volume commitment. Health-Conscious Consumers are gaining share fastest.
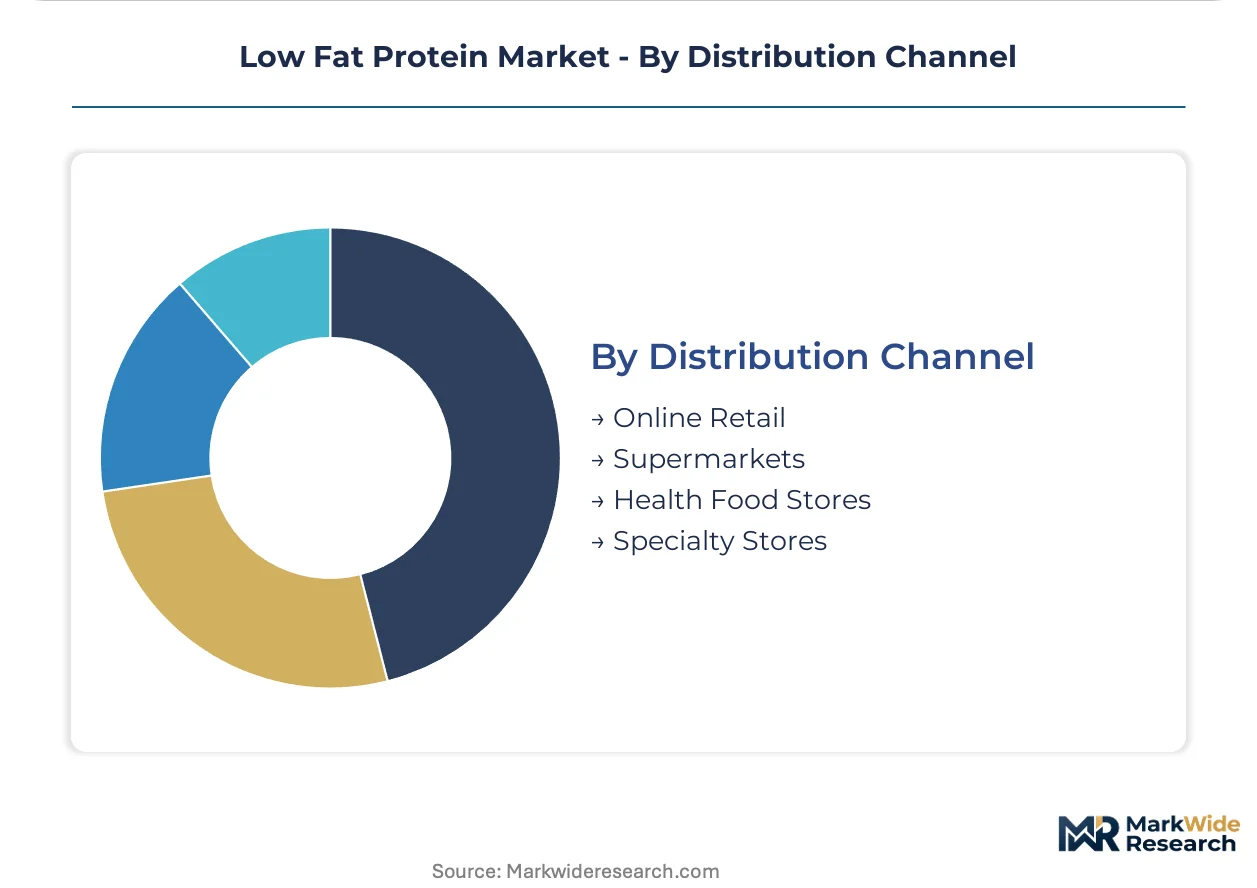
Distribution Channel:
Fulfillment technology ownership and customer data capture are restructuring channel economics toward vertically integrated isolate suppliers.
- Online Retail:Direct-to-consumer platforms concentrate customer relationship ownership and enable personalized dosing algorithms. Specialty isolate suppliers integrating fulfillment technology capture margin pools previously allocated to wholesale distributors.
- Supermarkets:Mainstream retail slotting fees and functional shelf space expansion create access barriers for mid-tier processors lacking established brand recognition.
- Health Food Stores:Curated assortment and staff consultation support premium positioning for certified organic and grass-fed protein isolates.
- Specialty Stores:Gym-affiliated retail and sports performance boutiques emphasize third-party tested and banned-substance-certified products.
Online Retail owns customer data. Health Food Stores defend premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food scientists and protein formulation chemists concentrate in the United States, Germany, and China, anchoring innovation pipelines and regulatory navigation capabilities for scaled isolate production.
United States
Fitness-oriented consumers in California and Texas metropolitan clusters drive direct-to-consumer subscription demand for grass-fed whey isolates. FDA nutrition labeling reforms force reformulation investments that favor manufacturers with established GRAS self-affirmation dossiers. Chicago and Denver processing facilities retrofit cross-flow microfiltration systems to achieve sub-one-percent residual fat specifications for sports nutrition contracts.
Germany
EFSA health claim substantiation requirements concentrate premium isolate procurement among suppliers with randomized controlled trial backing. German gym chains and functional food retailers specify EFSA-approved protein quality metrics for shelf placement. Bavaria and North Rhine-Westphalia host contract manufacturing clusters serving French and Benelux export channels with certified organic isolates.
China
Tier-one city gym chains in Shanghai and Beijing expand dedicated functional nutrition sections with imported whey and pea protein SKUs. SAMR protein content verification protocols tighten import documentation requirements for isolate distributors. Yangtze River Delta e-commerce platforms build proprietary fulfillment infrastructure for personalized protein subscription services targeting fitness enthusiasts.
Ireland
Grass-fed dairy herds in Munster and Leinster supply premium whey concentrate feedstock for sports nutrition brands specifying pasture-raised provenance. EU organic certification requirements align with USDA equivalency agreements for transatlantic export eligibility. Cork and Limerick processing sites face pasture-availability volatility that creates protein concentrate price cyclicality.
Netherlands
Integrated oilseed processing infrastructure in Rotterdam and Groningen concentrates soy protein isolate supply for economy-tier fortified food applications. REACH chemical registration requirements shape solvent extraction technology deployment in new capacity installations. Wageningen University research clusters anchor precision fermentation development programs for lipid-free microbial protein platforms.
Low Fat Protein Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness networks with captive dairy or oilseed processing infrastructure. Mid-tier specialists occupy flavor-mask technology and organic certification niches that command premium positioning. Three archetypes dominate: diversified ingredient conglomerates with global sourcing networks, regional dairy cooperatives with grass-fed supply contracts, and precision fermentation startups targeting lipid-free protein platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves, with incumbents retrofitting membrane filtration assets while newcomers license microbial strain optimization capabilities.
Within the diversified ingredient tier, Koninklijke DSM N.V., Archer Daniels Midland Company, and Cargill exemplify scale-driven archetypes with integrated supply chain control. DSM's Dutch corporate structure positions it within European regulatory navigation expertise. ADM's Chicago-based operations represent North American oilseed processing concentration. Cargill's privately held structure enables long-term capacity deployment without quarterly earnings pressure. Kerry Group and Glanbia plc occupy specialist positions, with Kerry's Irish origins signaling flavor technology heritage and Glanbia's dairy cooperative roots exemplifying grass-fed supply chain anchoring. Tate & Lyle, Ingredion, and Roquette Frères represent regional European and North American processing specialists with starch and plant-protein diversification.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Archer Daniels Midland Company |
| Cargill |
| Kerry Group |
| Tate & Lyle PLC |
| Glanbia plc |
| Ingredion |
| Roquette Frères |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Membrane filtration equipment depreciation costs cascade through whey and plant protein value chains, compressing margins at mid-tier processors while scaled operators capture pricing power through captive dairy and oilseed infrastructure. Sports nutrition contract manufacturers in Germany and the United States absorb these capital burdens differently, with EFSA-substantiated isolate suppliers commanding premium positioning against commodity-grade competitors facing price erosion.
Pricing Analysis
Unbundled ingredient supply separates from flavor-mask technology licensing, creating divergent margin structures across isolate procurement contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification stacking intensity, with USDA organic and EFSA health claim authorization driving spreads between tiers. Pricing pressure stems from grass-fed whey supply volatility in New Zealand and Ireland, which spikes concentrate costs unpredictably. Health-conscious consumers in direct-to-consumer channels show least price sensitivity, while economy-tier fortified food manufacturers face acute cost-per-gram pressure.
Supply Chain Analysis
Dual-sourcing requirements from sports nutrition contract manufacturers mandate multi-supplier qualification for both whey and pea protein isolates, preventing single-source lock-in. Supply concentrates in the United States, Germany, and China, with each hub serving distinct regulatory and channel requirements. Raw material dependencies center on grass-fed dairy herds in Ireland and New Zealand, North American oilseed crushing capacity, and yellow pea cultivation in Canada and France. Tariff exposure on Chinese isolate imports into the United States creates structural risk for distributors lacking alternative qualification pathways. Distribution runs through vertically integrated suppliers owning direct-to-consumer fulfillment technology, displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where FDA nutrition labeling reforms and EU EFSA health claim authorization create escalating compliance thresholds that concentrate demand among dossier-rich incumbents. These frameworks transform formulation legitimacy into a scarce asset, rewarding analytical capability investment while filtering marginal competitors from premium channel access.
For Market Incumbents: Cement analytical laboratory capabilities and regulatory dossier depth as defensive moats against precision fermentation entrants. Expand membrane filtration capacity in the United States and Germany to capture sports nutrition contract consolidation. Prioritize backward integration into grass-fed dairy supply through long-term pasture-availability agreements in Ireland and New Zealand, insulating against input price cyclicality that threatens margin stability.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel wedge, as fitness enthusiasts in California and London metropolitan clusters prioritize personalized replenishment over incumbent brand loyalty. Target health foods application growth in China tier-one cities, where gym chain expansion outpaces established supplier relationships. Lead with AI-driven flavor optimization to circumvent Kerry Group's proprietary palatability lock-in.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier organic-certified processors because USDA equivalency agreements and retailer slotting fee waivers create scalable platform value from fragmented regional operators. Five-to-ten year viability hinges on positioning for precision fermentation convergence without stranded asset exposure to agricultural feedstock volatility. Watch SAMR protein content verification protocol tightening as the inflection signal for import distributor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Cross-flow microfiltration retrofits in Chicago and Denver achieve sub-one-percent fat specifications for sports nutrition contracts. |
| EFSA Health Claim Dossier Investment | Randomized controlled trial sponsorship secures premium shelf positioning in German and French retail channels. |
| Grass-Fed Supply Contracting | Long-term pasture-availability agreements in Munster and Leinster stabilize whey concentrate feedstock costs. |
| Direct-to-Consumer Platform Integration | Proprietary fulfillment technology captures customer data and margin pools from wholesale distributors. |
| Precision Fermentation Partnership | Microbial protein platform licensing positions for lipid-free production without agricultural input constraints. |
Research Methodology
Coverage spans the United States, Germany, China, Ireland, and the Netherlands, with primary inputs from each market informing regional divergence in regulatory navigation and channel structure. The research combines structured interviews with sports nutrition brand procurement directors, contract manufacturing plant managers, flavor technology R&D leads, and EU regulatory affairs specialists with secondary validation from FDA GRAS notification databases, EFSA health claim registers, SAMR import documentation records, and USDA organic certification listings. Bottom-up isolate volume modeling triangulates against top-down sports nutrition and health foods market sizing.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, isolating membrane filtration cost curve effects from premium positioning drivers. Segmentation dimensions include protein chemistry type, application channel, end-user intensity tier, and distribution structure, with additional modeling of certification stacking patterns. CAGRs derive from regression analysis against historical isolate procurement data, incorporating sports nutrition contract renewal rates and China fitness retail expansion trajectories as industry-specific forecast inputs.
Revisions become necessary when FDA GRAS self-affirmation timelines extend beyond standard preparation cycles, EU EFSA substantiation requirements tighten clinical evidence thresholds, or SAMR protein verification protocols disrupt import documentation flows. Deviation in grass-fed dairy pasture availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Functional Flavor Market