
 Functional Dairy Products Market | 2026-2036
Functional Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Dairy Products Market Analysis
A shift from single-source milk procurement to multi-source supplier networks is recalibrating cost structures across the industry. Danone leverages its European cooperative partnerships to secure consistent whey protein supplies. Nestle anchors its competitive stance through captive dairy farms in Latin America. Fonterra dominates oceania-origin ingredient sourcing for probiotic strains.
Functional dairy products are formulated milk-based goods enhanced with bioactive compounds, live cultures, or fortified micronutrients that deliver targeted physiological benefits beyond basic nutrition; manufacturers employ cold-chain fermentation, microencapsulation, and strain-specific culturing to preserve viability and bioactivity through shelf life. Probiotic yogurt commands the largest revenue pool due to established clinical validation and repeat purchase frequency. Immune support formulations now attract the fastest margin expansion as post-pandemic health vigilance persists. Online retail channels capture disproportionate growth in subscription-based probiotic delivery models.
The EU EFSA and FDA both enforce stringent health claim substantiation protocols that determine which functional benefits manufacturers may communicate on-label. China's SAMR implements national food safety standards for fermented dairy that dictate strain registration and production facility certification. Stakeholders must monitor evolving strain patent expirations and regulatory harmonization efforts between major dairy importing blocs to anticipate competitive entry timing.
Market Dynamics
Multi-source supplier networks are recalibrating cost structures across functional dairy manufacturing, as cold-chain fermentation and microencapsulation technologies demand precise strain viability management through shelf life.
Growth Catalysts
- Sports Nutrition Absorption:Probiotic yogurt volumes now flow disproportionately into athletic recovery formulations, with protein-fortified fermented milks capturing repeat purchase frequency among fitness-focused consumers.
- EFSA Health Claim Pathways:The EU's tightened substantiation requirements create competitive moats for manufacturers with clinical validation libraries, advantaging established players over speculative entrants.
- China Tier-One Premiumization:Shanghai and Beijing consumers demonstrate deepening penetration of immune-support fermented products, driving margin expansion in high-probiotic-count SKUs.
Market Restraints
- Whey Protein Input Volatility:Multi-source procurement exposes margins to oceania-origin ingredient price swings, particularly Fonterra-dominated strain supply channels.
- SAMR Facility Certification:China's national food safety standards for fermented dairy impose 18-24 month production facility approval timelines, freezing capacity expansion for unregistered entrants.
- Plant-Based Fermentation Substitution:Oat and coconut yogurt alternatives with added probiotics capture label-conscious consumers seeking dairy-free positioning.
Strategic Opportunities
- Subscription Direct-to-Consumer Models:Online retail channels capture disproportionate growth in recurring probiotic delivery, bypassing traditional cold-chain retail markup structures.
- Strain Patent Expiration Windows:Lactobacillus rhamnosus GG and comparable proprietary cultures approaching off-patent status enable generic formulation entry for cost-optimized competitors.
- Immune Support Formulation White Space:Post-pandemic health vigilance persists in vitamin D-fortified kefir and zinc-enhanced fermented milks, commanding fastest margin expansion across functional categories.
Industry Challenges
- Microbiome Sequencing Talent Scarcity:Strain-specific culturing expertise concentrates among European and North American research clusters, constraining R&D velocity for emerging market manufacturers.
- Cold-Chain Integrity Capex Burden:Live culture viability preservation demands continuous refrigeration infrastructure investment from fermentation through last-mile delivery.
- Regulatory Harmonization Friction:Divergent EFSA-FDA-SAMR health claim substantiation protocols force parallel clinical study investments for multi-territory product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Dairy Products Market |
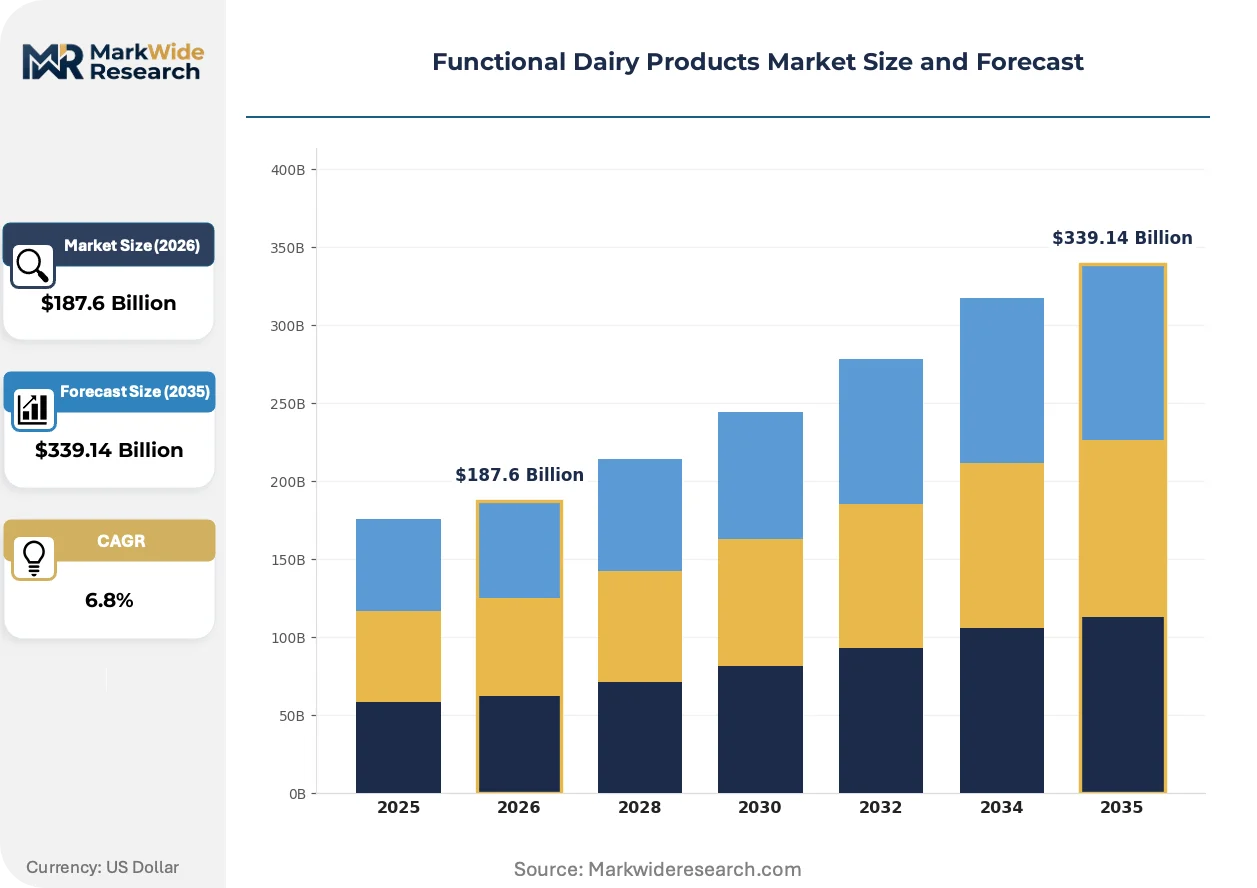
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Cheese, Milk, Butter Health Benefit: Probiotic, Nutrient-Rich, Weight Management, Immune Support End User: Health-Conscious Consumers, Athletes, Families, Seniors Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops |
| Companies Covered | Arla Foods, Yili Group, Danone, Dairy Farmers of America, Mengniu Dairy, Nestle, Fonterra, Saputo Inc., Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Dairy Products Market Emerging Trajectories
Live culture preservation technologies and claim substantiation protocols are compressing formulation-to-shelf timelines, while channel fragmentation rewards manufacturers with flexible fulfillment architectures.
Microencapsulation via spray-drying and lipid-coating technologies is electrifying probiotic survival rates through gastric transit. Sports nutrition manufacturers adopt these formats for powder-based recovery products. The structural consequence is shelf-stable strain delivery that bypasses traditional refrigerated yogurt dependence.
EFSA's 2023 updated guidance on gut health and immune function claims tightens acceptable scientific evidence thresholds. Manufacturers must now submit human intervention studies with defined biomarker endpoints. Probiotic yogurt segments in Germany and France face reformulation pressure as legacy claims lose authorization.
Chinese consumers in Shenzhen and Guangzhou demonstrate accelerating preference for subscription-based fermented milk delivery over hypermarket purchase. Digital-native brands capture this behavioral pivot through temperature-controlled logistics partnerships. The shift compresses traditional dairy distributor margins while rewarding direct consumer data ownership.
Functional Dairy Products Market Segmentation
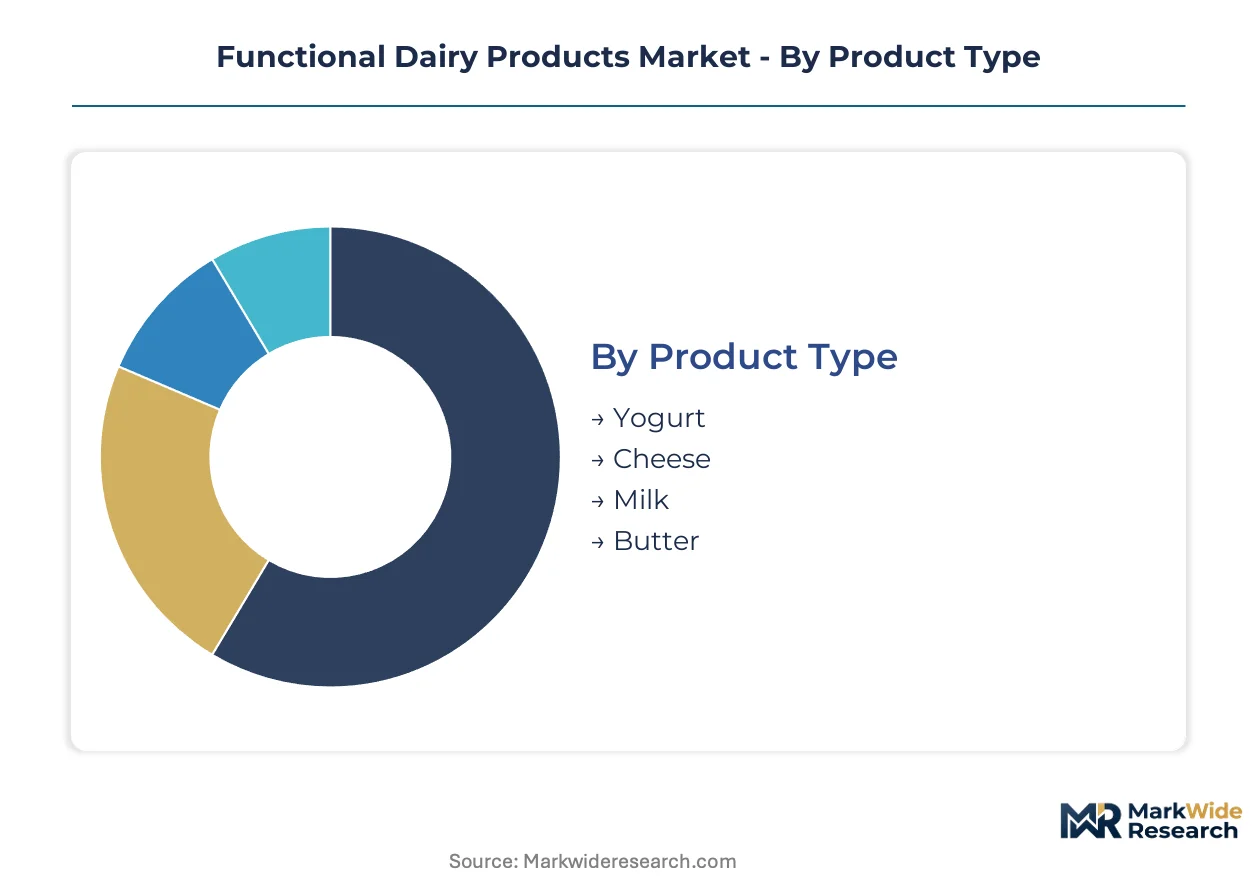
Functional dairy manufacturers calibrate formulation complexity and cold-chain investment against distinct buyer willingness-to-pay thresholds. Segmentation reveals where probiotic viability requirements, health claim substantiation costs, and channel margin structures align profitably.
Product Type:
Buyers in this category differentiate by fermentation infrastructure requirements and live culture shelf-life demands.
- Yogurt:Fermented milk products carrying defined probiotic strain counts dominate refrigerated case space. Sports nutrition applications in Germany and France absorb protein-fortified Greek yogurt volumes for athletic recovery formulations.
- Milk:Vitamin D and omega-3 fortified fluid milk serves family breakfast occasions with established micronutrient delivery. Chinese tier-one cities show deepening penetration of high-protein UHT variants with extended ambient stability.
- Cheese:Probiotic-enhanced fresh cheeses target digestive health positioning in European markets. EFSA health claim substantiation requirements constrain on-label communication for mature cheese categories with limited live culture survival.
- Butter:Spreadable formats with added plant sterols occupy premium positioning in heart-health segments. Functional butter remains niche due to fat-content perception barriers among health-conscious buyers.
Volume sits with yogurt; growth tilts toward milk.
Health Benefit:
Margin structures in this category diverge sharply based on clinical validation investment and regulatory authorization pathways.
- Probiotic:Live culture formulations with strain-specific CFU counts command repeat purchase frequency through gut health positioning. SAMR strain registration requirements in China freeze 18-24 month approval timelines for new entrants.
- Immune Support:Vitamin D and zinc fortification in kefir and fermented milks captures post-pandemic health vigilance. Shanghai and Beijing consumers demonstrate accelerating preference for high-count probiotic SKUs with immune positioning.
- Nutrient-Rich:Calcium and protein fortification targets bone health and satiety applications across age demographics. Standard fortification faces commoditization pressure from private-label competition.
- Weight Management:High-protein, reduced-fat formulations serve calorie-conscious buyers with portion-controlled formats. Clinical substantiation for weight claims remains weaker than probiotic or immune categories.
Probiotic captures the revenue base; immune support climbs the fastest.
End User:
Purchase frequency and price sensitivity in this category map to life-stage health priorities and household decision-making structures.
- Health-Conscious Consumers:Label-attentive buyers with above-average willingness-to-pay for organic certification and strain transparency. Subscription direct-to-consumer models in Shenzhen and Guangzhou capture this behavioral pivot through temperature-controlled logistics.
- Athletes:Protein-fortified fermented products with recovery positioning drive repeat purchase in sports nutrition channels. Powder-based probiotic formats with microencapsulation technology bypass traditional refrigerated dependence.
- Families:Multi-serve formats with child-friendly flavor profiles prioritize convenience and value positioning. Nutrient-rich milk and yogurt dominate this segment with established breakfast occasion penetration.
- Seniors:Bone health and digestive wellness formulations target aging populations with texture-modified products. EFSA tightened substantiation requirements challenge legacy claims in German and French markets.
Health-conscious consumers anchor volume; athletes expand most quickly.
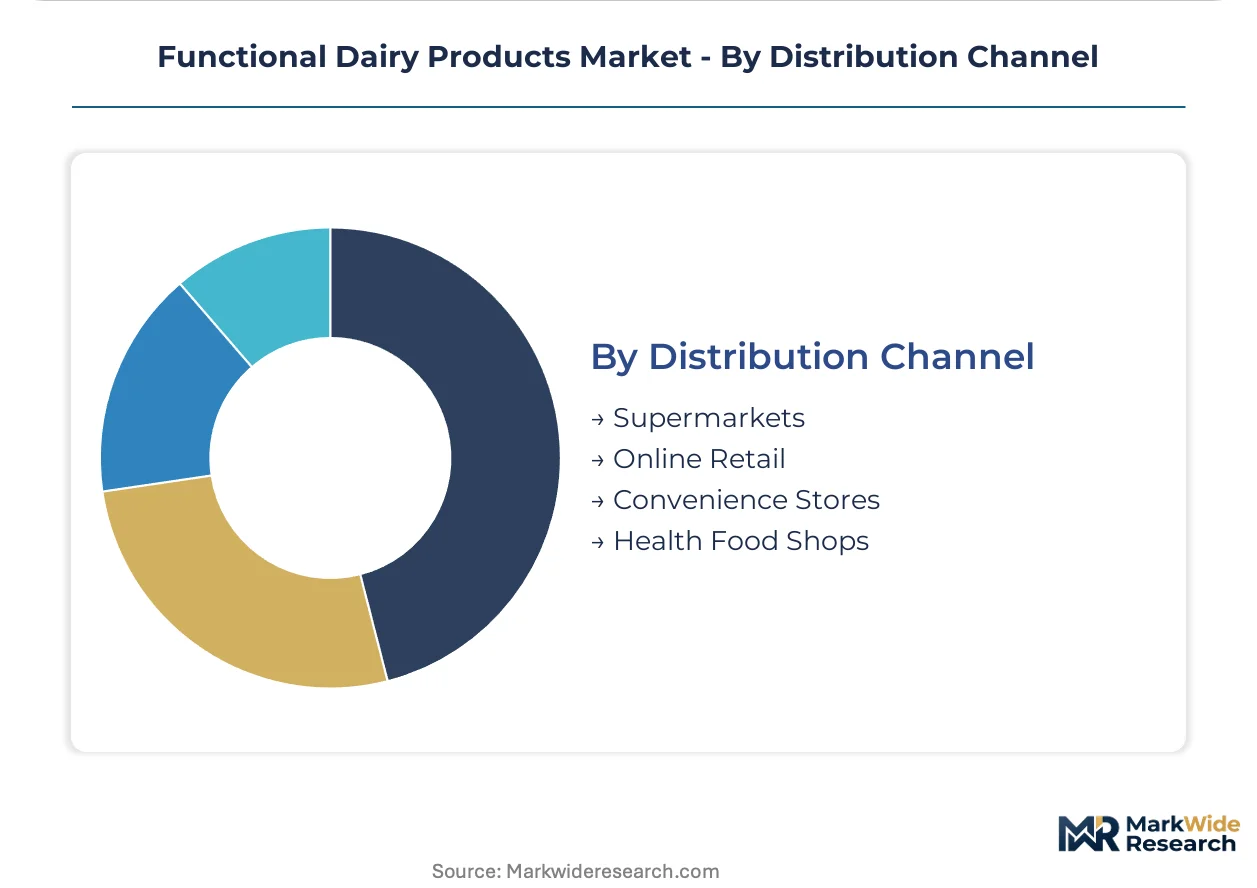
Distribution Channel:
Cold-chain integrity requirements and margin extraction potential separate channel economics in this category.
- Supermarkets:Refrigerated case placement with established foot traffic drives impulse purchase for mainstream probiotic yogurt. Traditional distributor margins compress as digital-native brands capture direct consumer relationships.
- Online Retail:Subscription-based recurring delivery models bypass retail markup structures and enable temperature-controlled last-mile logistics. Chinese digital-native brands leverage consumer data ownership for personalized strain recommendations.
- Convenience Stores:Grab-and-go single-serve formats serve immediate consumption occasions with limited shelf-space competition. Live culture viability constraints restrict SKU complexity in ambient storage environments.
- Health Food Shops:Premium positioning with organic and specialty strain differentiation targets dedicated wellness buyers. Smaller format constraints limit volume scale despite superior per-unit margins.
Supermarkets hold volume; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oceania-origin whey protein and probiotic strain supplies anchor manufacturing cost structures across major functional dairy markets. New Zealand's cooperative processing infrastructure and European fermentation expertise shape ingredient flow patterns. Chinese tier-one cities drive premiumization velocity through subscription-based delivery models.
United States
Sports nutrition applications absorb significant probiotic yogurt volumes for athletic recovery formulations. The FDA enforces stringent health claim substantiation protocols that determine on-label functional benefit communication. California and Colorado host specialized fermentation facilities serving powder-based probiotic recovery products with microencapsulation technology.
China
Shanghai and Beijing consumers demonstrate deepening penetration of immune-support fermented products with high-probiotic-count SKUs. SAMR implements national food safety standards for fermented dairy that dictate 18-24 month strain registration timelines. Shenzhen and Guangzhou digital-native brands capture subscription-based delivery growth through temperature-controlled logistics partnerships.
Germany
Probiotic yogurt segments face reformulation pressure as EFSA's 2023 updated guidance tightens acceptable scientific evidence thresholds for gut health claims. The country's national pharmaceutical regulator aligns with EU Nutrition and Health Claims Regulation enforcement. Bavaria concentrates strain-specific culturing expertise among European research clusters serving R&D-intensive manufacturers.
France
Immune support formulations in kefir and fermented milks command fastest margin expansion as post-pandemic health vigilance persists. EFSA human intervention study requirements with defined biomarker endpoints constrain legacy claim authorization. The Paris basin anchors dairy cooperative partnerships securing consistent whey protein supplies for functional formulation.
Australia
Premium fermented milk penetration deepens among health-conscious consumers with above-average willingness-to-pay for organic certification. The country's national pharmaceutical regulator enforces parallel clinical study investments for multi-territory product launches. Victoria and New South Wales processing infrastructure dominates oceania-origin ingredient sourcing for probiotic strains.
Functional Dairy Products Market Vendor Landscape
Global majors compete with regional champions across strain registration capabilities and cold-chain infrastructure ownership. The functional dairy sector exhibits tiered concentration where cooperative-backed European processors face Asian scale players and North American dairy conglomerates. Three archetypes dominate: vertically integrated dairy cooperatives with captive ingredient supply, multinational nutrition conglomerates with clinical validation libraries, and digital-native direct-to-consumer brands with subscription logistics. Competitive moves concentrate on multi-source supplier network expansion and microencapsulation technology licensing.
Within the cooperative-backed tier, Arla Foods and Fonterra exemplify vertically integrated structures with oceania-origin strain supply control. Danone occupies a position bridging European fermentation expertise with multi-territory health claim authorization capabilities. Among Asian scale players, Yili Group and Mengniu Dairy represent the premiumization-focused archetype targeting Chinese tier-one city demand through high-probiotic-count SKU development.
| Leading Market Players |
|---|
| Arla Foods |
| Yili Group |
| Danone |
| Dairy Farmers of America |
| Mengniu Dairy |
| Nestle |
| Fonterra |
| Saputo Inc. |
| Lactalis |
| Others |
Supply Flow & Price Mechanics
Cooperative-backed dairy processors with captive ingredient supply anchor pricing discipline through strain ownership advantages that compress competitor margins. Cold-chain fermentation requirements and EFSA substantiation costs feed directly into tiered pricing structures, while multi-source whey procurement exposes unintegrated players to Fonterra-dominated supply volatility.
Pricing Analysis
Warranty-equivalent shelf-stability guarantees separate premium probiotic SKUs from commodity yogurt tiers, with microencapsulation technology bundling gastric-survival assurance into higher price points. Three-tier pricing structure across premium, standard, and economy levels reflects strain-specific CFU counts, organic certification, and cold-chain integrity investment. Cost compression in economy-tier private-label segments is intensifying because of plant-based fermentation substitution. Families purchasing multi-serve formats demonstrate highest price sensitivity, while health-conscious subscribers in Chinese tier-one cities accept recurring premium payments for strain-transparency guarantees.
Supply Chain Analysis
SAMR facility certification and EFSA health claim authorization function as qualification gates that freeze capacity expansion for unregistered entrants. New Zealand, Denmark, and the Netherlands concentrate oceania-origin whey protein and probiotic strain production. Raw material flows draw from Fonterra-dominated dairy cooperatives, European fermentation expertise clusters, and Latin American captive farm networks. Single-source vulnerability runs through oceania-origin ingredient channels exposed to climate-driven production swings. Distribution runs through temperature-controlled logistics partnerships that bypass traditional retail markup structures in subscription-direct models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's 2023 tightened substantiation requirements construct a cost-of-compliance moat where clinical validation libraries become non-substitutable assets. This regulatory barrier advantages established players with parallel FDA-EFSA-SAMR study investments while freezing speculative entrants.
For Market Incumbents: Deepen strain-specific culturing expertise concentration in Bavaria and North American research clusters to accelerate R&D velocity against microbiome sequencing talent scarcity. Expand backward integration into oceania-origin whey supply through cooperative partnerships that mirror Danone's European sourcing architecture. Priority defensive moves include locking multi-year strain licensing agreements before Lactobacillus rhamnosus GG patent expirations enable generic entry, and preemptively reformulating legacy gut health claims to meet EFSA biomarker endpoint requirements. For New Entrants and Emerging Players: SAMR strain registration timelines in China open a window for white-space capture through digital-native direct-to-consumer models in Shenzhen and Guangzhou, bypassing 18-24 month facility approval barriers that freeze traditional manufacturing entry. Target immune support formulation gaps in vitamin D-fortified kefir where post-pandemic health vigilance outpaces incumbent SKU development. Subscription-based temperature-controlled logistics partnerships offer the most penetrable go-to-market angle, compressing traditional distributor margins while capturing consumer data ownership. For Investors and Strategic Acquirers: Strain patent expiration windows approaching for proprietary Lactobacillus cultures is the leading indicator that generic formulation entry will accelerate competitive pressure on premium pricing tiers. Long-term viability across the analysis window favors acquisition targets with captive cold-chain infrastructure and multi-territory health claim authorization libraries. Watch EFSA-FDA-SAMR regulatory harmonization progress as the inflection signal determining whether parallel clinical study investments consolidate competitive advantage or become stranded cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Shelf-stable strain delivery bypasses refrigerated dependence, opening sports nutrition powder formats. |
| Subscription Direct-to-Consumer Launch | Temperature-controlled logistics partnerships in Chinese tier-one cities compress traditional retail margins. |
| Multi-Territory Health Claim Authorization | Parallel EFSA-FDA-SAMR study investments create regulatory moats against unvalidated competitors. |
| Strain Patent Portfolio Acquisition | Pre-expiration licensing of proprietary cultures blocks generic entry before off-patent windows open. |
| Backward Integration into Whey Supply | Cooperative partnerships with Fonterra-dominated oceania-origin channels secure input cost stability. |
Methodological Framework
Multi-period observation of strain registration timelines, cold-chain infrastructure deployment, and subscription adoption rates anchored the trend analysis, supplemented by interviews with fermentation R&D directors, SAMR regulatory consultants, dairy cooperative procurement leads, and sports nutrition brand managers. Secondary validation drew from EFSA health claim authorization databases, SAMR facility certification records, Fonterra cooperative supply disclosures, and Nielsen retail audit data. Bottom-up SKU-level demand modeling and top-down category value triangulation converged on segment-specific growth trajectories.
Input-output matrices mapped probiotic strain supply flows through processing infrastructure to end-use absorption across sports nutrition, family breakfast, and senior wellness occasions. Segmentation dimensions modeled included product type, health benefit positioning, end-user archetype, and distribution channel structure alongside regional regulatory cluster differentiation. CAGRs were derived from trend-line extrapolation of historical penetration rates adjusted for SAMR approval timeline constraints and EFSA claim authorization shifts. Industry-specific forecast inputs incorporated microencapsulation technology adoption curves and subscription logistics partnership expansion rates.
The model assumes a particular technology adoption path for cold-chain integrity preservation; alternative pathways for ambient-stable microencapsulation formats would alter the outlook toward shelf-stable dominance over refrigerated dependence. Forecasts reflect assumptions about regulatory harmonization progress and strain patent expiration sequencing. A model refresh is warranted upon material change in EFSA-FDA-SAMR claim substantiation protocol alignment or Fonterra cooperative supply restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Beauty Drinks Market