
 Soluble Beta Glucan Market | 2026-2036
Soluble Beta Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Soluble Beta Glucan Market Analytics
Subscription-based technical support for beta glucan extraction systems is consolidating what equipment vendors sell alongside raw ingredients. Tate & Lyle PLC leverages its global sweetener and fiber infrastructure to anchor soluble beta glucan distribution across multiple continents. DSM NV sustains R&D intensity in yeast cell wall derivatives, competing on purity benchmarks that pharmaceutical buyers require. Kerry Group PLC specializes in integrated flavor-nutrition systems, differentiating its beta glucan offerings through formulation partnerships with finished goods manufacturers.
Soluble beta glucan comprises glucose polymers—primarily beta-1,3/1,6 linkages in yeast and beta-1,3/1,4 in cereal sources—that form viscous aqueous solutions at concentrations above 0.5% w/v, functioning as immunomodulatory biopolymers and soluble dietary fibers. Industrial production employs alkaline extraction from Saccharomyces cerevisiae cell walls or aqueous processing of oat bran, followed by spray-drying to achieve standardized beta-glucan content of 70-85%. The nutraceuticals application segment leads current volume as immune health positioning drives capsule and tablet formulations, while functional foods represent the fastest-expanding margin pool where powder formats integrate into beverages and baked goods. Pharmaceutical-grade standardized formulations command premium positioning due to lot-to-lot consistency requirements that customized variants rarely satisfy.
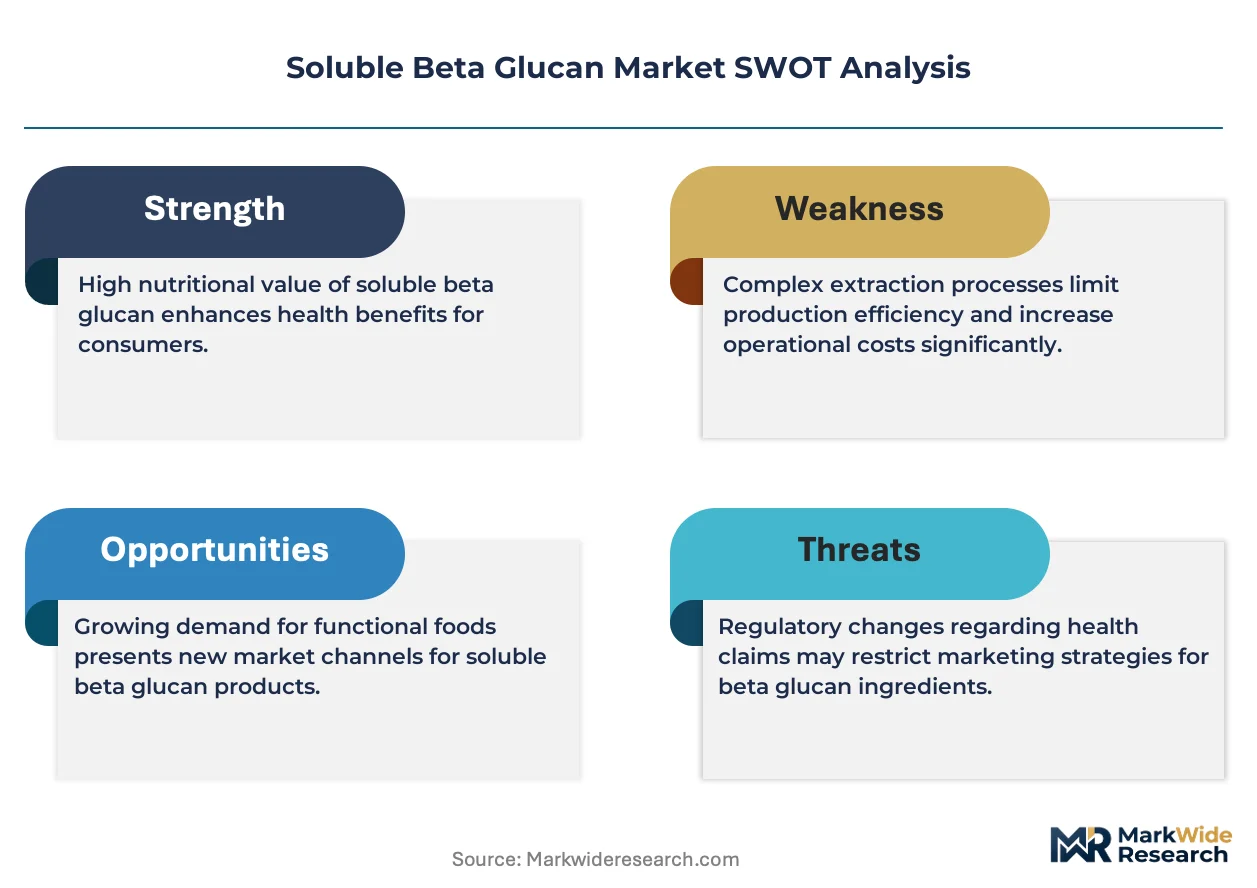
FDA GRAS notifications and EFSA novel food opinions govern yeast beta glucan entry into US and European food matrices, while China's NMPA and SAMR regulate health food claims for domestic immune-positioned products. These frameworks elevate compliance costs for new entrants but simultaneously protect incumbent suppliers with established dossiers and analytical methodologies. Stakeholders must monitor evolving immunomodulatory claim restrictions and adapt clinical substantiation strategies accordingly.
Market Dynamics
Regulatory divergence between FDA GRAS pathways and EFSA novel food opinions is fragmenting approval timelines for yeast-derived beta glucan, forcing suppliers to maintain parallel dossier strategies and regional analytical protocols.
Growth Catalysts
- EFSA Immune Health Claims:The 2023 EFSA opinion on yeast beta-1,3/1,6-glucan substantiation is unlocking functional food positioning across EU member states for beverage fortification.
- Alkaline Extraction Efficiency:Continuous processing improvements in Saccharomyces cerevisiae cell wall hydrolysis are reducing solvent consumption and yield variability for pharmaceutical-grade output.
- German Nutraceutical Pipelines:Contract manufacturers in Bavaria and Baden-Württemberg are expanding dedicated beta glucan tableting capacity to serve immune supplement brands.
Market Restraints
- Oat Supply Concentration:Nordic and Canadian oat milling consolidation limits beta-1,3/1,4-glucan feedstock diversification for North American functional food formulators.
- China NMPA Dossier Costs:Blue hat health food registration requirements for immune claims demand multi-year clinical investment that excludes mid-tier ingredient suppliers.
- Enzymatic Hydrolysis Yields:Current cellulase and xylanase cocktails achieve incomplete beta glucan liberation from cereal bran matrices, capping extraction economics.
Strategic Opportunities
- Personalized Nutrition Platforms:Direct-to-consumer microbiome testing services in the United States are creating demand for precision-dosed beta glucan sachets tailored to immune markers.
- Japan FOSHU Route:The Foods for Specified Health Uses approval pathway offers a regulatory template for immune-modulatory beta glucan claims in functional beverages.
- Plant Cell Culture:Recombinant production of fungal beta glucan in Nicotiana benthamiana hosts is bypassing yeast supply constraints and allergen labeling requirements.
Industry Challenges
- Lot-to-Lot Purity Variance:Pharmaceutical buyers reject beta glucan batches below 85% purity with endotoxin thresholds under 10 EU/g, compressing supplier margins for non-conforming material.
- Cross-Functional Formulation Expertise:Immune positioning requires simultaneous mastery of mucosal immunology, beverage stability, and regulatory substantiation—talent pools remain thin outside DSM and Kerry technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soluble Beta Glucan Market |
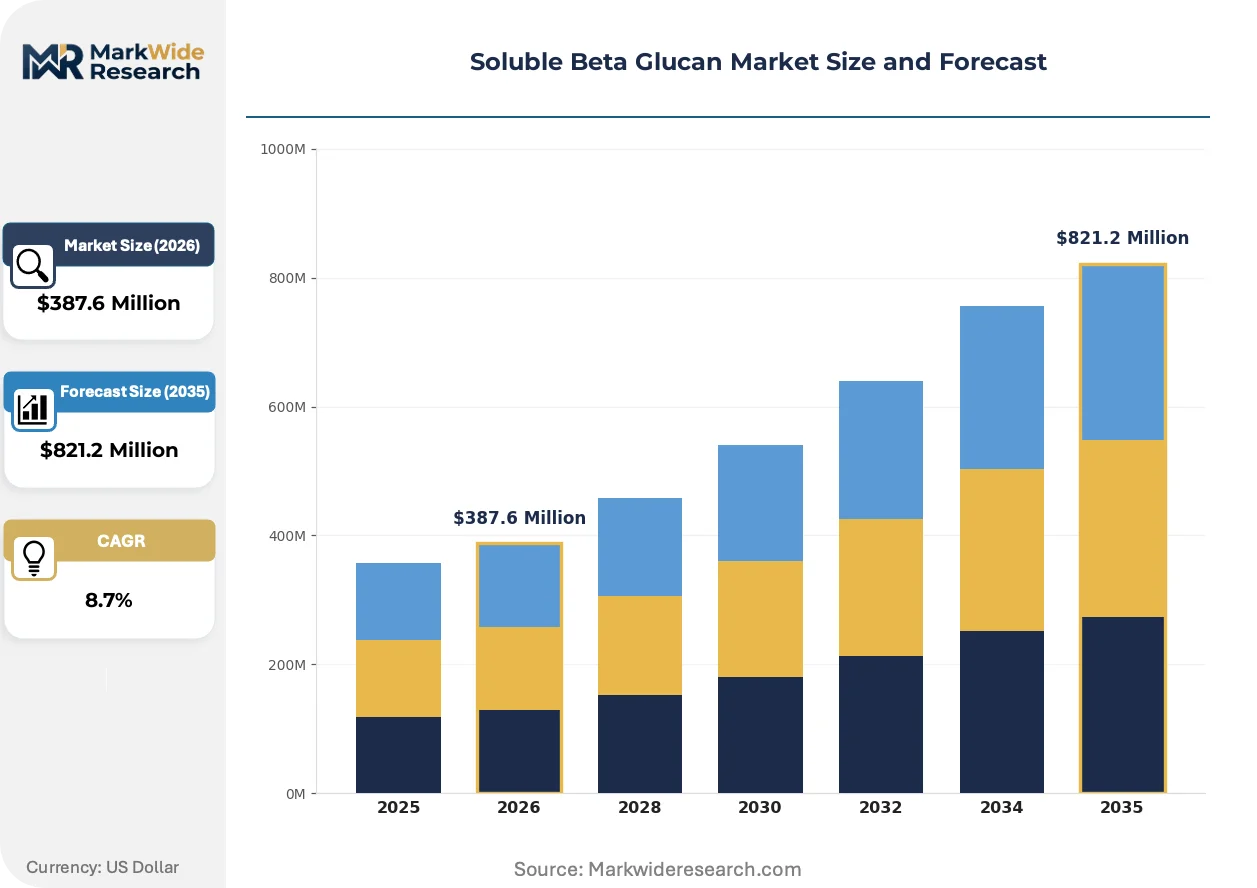
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets Application: Nutraceuticals, Functional Foods, Animal Feed, Pharmaceuticals Formulation: Organic, Non-Organic, Standardized, Customized Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Tate & Lyle PLC, DSM NV, Super Beta Glucan Inc, Ceapro Inc, Cargill Incorporated, Lesaffre Group, Kerry Group PLC, Garuda International Inc, BENEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soluble Beta Glucan Market Evolving Landscape
Process intensification and claim substantiation automation are compressing development cycles for beta glucan-enabled products. Suppliers now compete on analytical transparency and clinical data packages rather than commodity purity alone.
Membrane filtration cascades replacing solvent precipitation in yeast beta glucan recovery are electrifying downstream processing economics. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting ceramic microfiltration trains that cut processing time by half while preserving triple-helix structural integrity for receptor binding assays. This shift is compressing capital recovery periods for dedicated beta glucan facilities.
REACH registration requirements for novel yeast-derived biopolymers are tightening impurity disclosure thresholds across EU manufacturing sites. Industrial producers must now submit full analytical profiles on mannoprotein co-extracts and nucleic acid residues, elevating QC documentation burdens. Functional food brands sourcing from non-EU suppliers face extended due diligence timelines to maintain EU Green Deal supply chain transparency mandates.
Ingredient buyers are consolidating supplier relationships around dual-source beta glucan strategies that split yeast and cereal origins. Large North American nutraceutical brands now mandate redundant approval dossiers from at least two extraction technologies to mitigate single-source regulatory risk. This preference shift is most visible among direct-to-consumer immune supplement marketers in California and Colorado who face liability exposure from supply interruptions.
Soluble Beta Glucan Market Segmentation
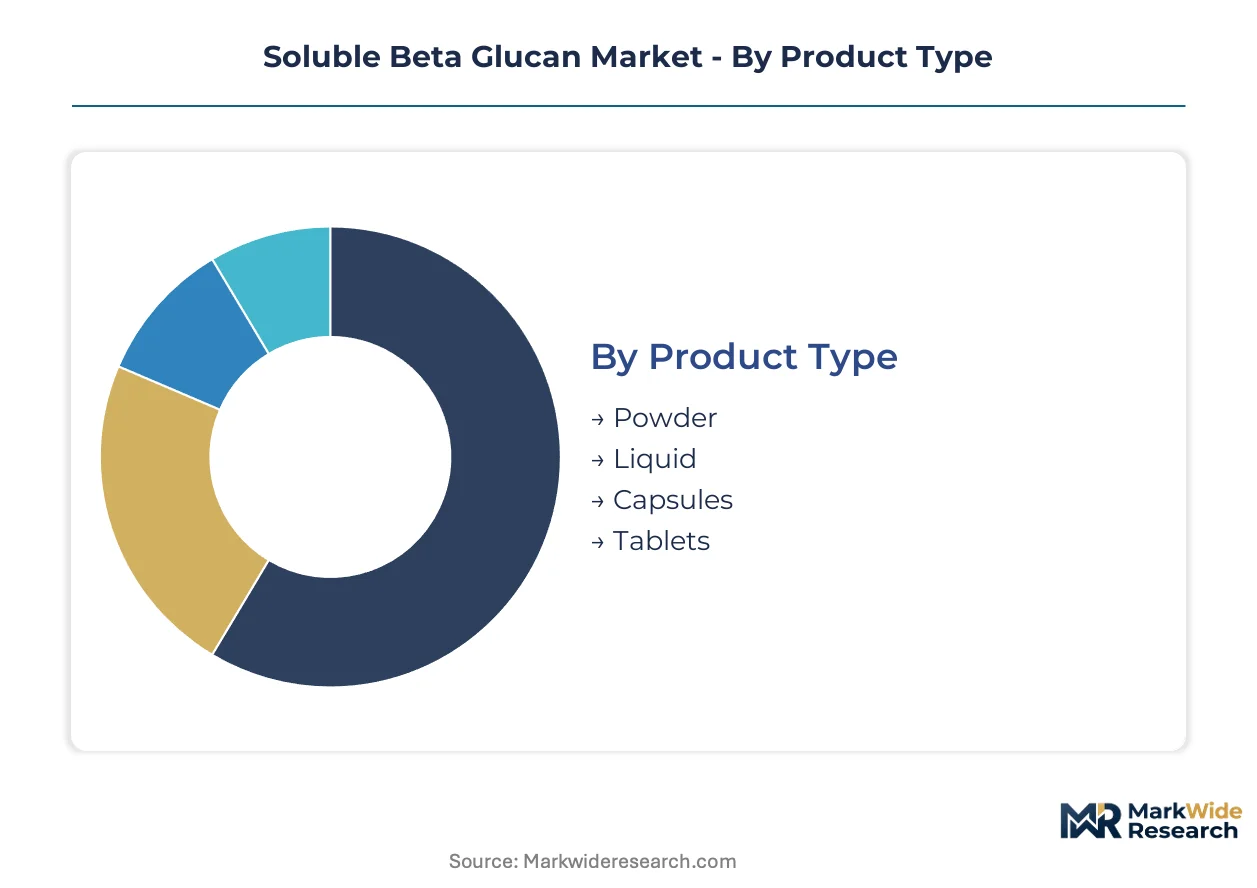
Segmentation in the Soluble Beta Glucan Market reveals how extraction technology, regulatory pathways, and end-use specifications fragment both supply capabilities and buyer procurement strategies across distinct commercial tiers.
Product Type:
Supply concentration in powder formats dominates extraction facility output, with liquid processing requiring specialized aqueous stability infrastructure that limits viable supplier pools.
- Powder:Spray-dried beta glucan at 70-85% standardized content serves as the baseline format for beverage fortification and baked goods integration. German and US nutraceutical formulators in Bavaria and Colorado drive procurement volumes for immune-positioned supplements.
- Liquid:Aqueous suspensions above 0.5% w/v viscosity enable direct incorporation into ready-to-drink functional beverages without reconstitution steps. Demand concentrates among North American beverage brands seeking clean-label texture solutions.
- Capsules:Hard-shell gelatin and vegetarian encapsulation formats target precision-dosed immune supplement positioning.
- Tablets:Compressed powder formulations with excipient matrices suit high-volume contract manufacturing runs.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Cost tier differentiation separates pharmaceutical-grade specifications from commodity functional food grades, with purity thresholds and analytical documentation requirements determining viable supplier participation.
- Nutraceuticals:Capsule and tablet formulations for immune health positioning command premium pricing due to EFSA and FDA substantiation requirements. German contract manufacturers in Baden-Württemberg expand dedicated tableting capacity to serve this segment.
- Functional Foods:Beverage fortification and baked goods integration represent the steepest expansion trajectory, driven by EFSA's 2023 yeast beta-1,3/1,6-glucan opinion unlocking EU beverage claims.
- Animal Feed:Beta glucan from Saccharomyces cerevisiae cell walls supports gut health positioning in poultry and aquaculture formulations.
- Pharmaceuticals:Injectable and topical applications demand lot-to-lot consistency below 10 EU/g endotoxin thresholds with triple-helix structural integrity verification.
Nutraceuticals command the highest margin pool; functional foods are climbing the fastest.
Formulation:
Customer type stratification separates institutional pharmaceutical buyers seeking standardized certifications from direct-to-consumer brands pursuing organic positioning for premium shelf placement.
- Organic:Certified oat-sourced beta-1,3/1,4-glucan from Nordic milling operations targets clean-label functional food positioning in California and Colorado direct-to-consumer channels.
- Non-Organic:Conventional yeast-derived extraction from Saccharomyces cerevisiae supplies cost-sensitive animal feed and mass-market nutraceutical applications.
- Standardized:Pharmaceutical-grade specifications with 85%+ purity and full analytical dossiers satisfy FDA GRAS and EFSA novel food compliance requirements.
- Customized:Tailored viscosity profiles and particle size distributions address specific beverage stability or encapsulation performance needs.
Standardized formulations absorb the bulk of pharmaceutical procurement; organic is gaining share fastest among functional food entrants.
Distribution Channel:
Geography of buyer concentration shapes channel viability, with direct sales relationships dominating pharmaceutical procurement while online channels fragment nutraceutical brand access.
- Online:Direct-to-consumer immune supplement marketers in California leverage e-commerce platforms for precision-dosed beta glucan sachets paired with microbiome testing services.
- Retail:Mass-market placement in pharmacy and grocery channels requires finished goods manufacturers with established shelf-space negotiation capabilities.
- Wholesale:Ingredient distributors aggregate smaller nutraceutical formulator demand across multiple regional markets.
- Direct Sales:Pharmaceutical contract manufacturers in Switzerland and Germany establish captive supply agreements with dedicated beta glucan extraction facilities.
Direct sales absorb the bulk of pharmaceutical-grade volume; online is expanding most quickly among emerging nutraceutical brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction capacity clusters in Germany and Switzerland while consumption concentrates in North American functional food channels. This geographic split forces suppliers to maintain dual regulatory dossiers for FDA GRAS and EFSA novel food compliance. Logistics networks must bridge this production-consumption divide with temperature-controlled powder handling infrastructure.
United States
California and Colorado direct-to-consumer brands drive demand for precision-dosed immune supplements paired with microbiome testing services. FDA GRAS notifications govern yeast beta glucan entry into beverage matrices, with 2023 submission volumes rising for oat-sourced variants. Denver-Boulder corridor contract manufacturers expand dedicated tableting capacity to serve this segment.
Germany
Bavarian and Baden-Württemberg nutraceutical formulators deepen dietary supplement pipelines with immune-positioned beta glucan capsules. EFSA's 2023 opinion on yeast beta-1,3/1,6-glucan substantiation unlocks functional food positioning across EU member states. Mannheim-Ludwigshafen chemical processing cluster hosts membrane filtration adoption for pharmaceutical-grade output.
Switzerland
Pharmaceutical contract manufacturers in Basel and Zurich establish captive supply agreements with dedicated extraction facilities. Swissmedic oversees injectable-grade specifications demanding lot-to-lot consistency below 10 EU/g endotoxin thresholds. Swiss-German border region concentrates ceramic microfiltration train adoption preserving triple-helix structural integrity.
China
Domestic immune health claim registrations through NMPA and SAMR concentrate in Shanghai and Beijing health food corridors. Blue hat registration requirements demand multi-year clinical investment that excludes mid-tier ingredient suppliers. Yangtze River Delta milling operations supply oat beta glucan for regional functional food brands.
Canada
Health Canada and PMRA regulate natural health product claims for prairie-sourced oat beta glucan positioning. Prairie Provinces oat milling consolidation limits beta-1,3/1,4-glucan feedstock diversification for North American formulators. Winnipeg and Saskatoon processing facilities face capacity constraints amid cross-border demand spillover.
Soluble Beta Glucan Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across the value chain. The supplier base fragments between extraction technology owners and finished goods integrators. Three archetypes dominate: integrated sweetener-fiber conglomerates leveraging global distribution infrastructure; yeast biotechnology specialists competing on purity benchmarks; and flavor-nutrition systems providers differentiating through formulation partnerships. Competitive moves concentrate on dual-source approval dossiers and membrane filtration capacity expansion.
Among integrated ingredient conglomerates, Tate & Lyle PLC and Kerry Group PLC exemplify archetypes spanning extraction through finished goods formulation. DSM NV represents the biotechnology-specialist tier with Saccharomyces cerevisiae cell wall derivative focus. These three anchors illustrate how scale-driven infrastructure, R&D intensity, and formulation integration respectively define competitive positioning in this market.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| DSM NV |
| Super Beta Glucan Inc |
| Ceapro Inc |
| Cargill Incorporated |
| Lesaffre Group |
| Kerry Group PLC |
| Garuda International Inc |
| BENEO |
| Others |
Value Network & Pricing Analysis
EU Green Deal supply chain transparency mandates gate qualified supplier status and premium-tier pricing access for beta glucan producers, forcing non-EU extraction facilities into costly documentation upgrades or exclusion from high-margin pharmaceutical procurement pools.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects REACH registration burdens and lot-to-lot purity verification costs that smaller extraction facilities cannot absorb. Three-tier pricing structure across pharmaceutical, nutraceutical, and animal feed grades separates buyers by endotoxin thresholds and analytical dossier depth. Cost-down pressure on oat-sourced variants accelerates because Nordic milling consolidation limits feedstock negotiation leverage. Animal feed buyers exhibit highest price sensitivity; pharmaceutical contract manufacturers accept premiums for Swissmedic-compliant consistency.
Supply Chain Analysis
Single-source vulnerability sits with Saccharomyces cerevisiae cell wall suppliers concentrated in Germany and Switzerland, where membrane filtration capacity constraints create pharmaceutical-grade bottlenecks. Raw material dependencies span yeast biomass from fermentation facilities, Nordic oat bran, and ceramic filtration membranes. Regulatory restriction risk looms as REACH tightens impurity disclosure thresholds. Distribution runs through captive supply agreements for pharmaceutical tiers and ingredient distributors for nutraceutical volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration capacity scarcity props pricing power for incumbent beta glucan suppliers, constraining volume growth despite EFSA claim substantiation unlocking functional food demand.
For Market Incumbents: Cement dual-source approval dossiers spanning yeast and cereal extraction technologies to mitigate single-source regulatory risk from FDA or EFSA pathway disruptions. Expand Baden-Württemberg tableting capacity to capture German nutraceutical pipeline growth. Vertical integration into ceramic microfiltration trains preserves triple-helix structural integrity premiums against commodity extraction competitors. For New Entrants and Emerging Players: Plant cell culture production in Nicotiana benthamiana hosts offers a technology-first wedge bypassing yeast allergen labeling requirements and supply constraints. Target California direct-to-consumer immune supplement channels with precision-dosed sachet formats paired with microbiome testing services. Pursue Japan FOSHU approval as a differentiated regulatory pathway for functional beverage positioning. For Investors and Strategic Acquirers: EFSA's 2023 yeast beta-1,3/1,6-glucan opinion is the leading indicator that functional food claim substantiation will concentrate procurement around dossier-complete suppliers. Five-to-ten year viability favors acquisition targets with established FDA GRAS notifications and membrane filtration assets. Watch NMPA blue hat registration approval timelines as the signal for China market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Ceramic microfiltration trains in Swiss-German border facilities halve processing time while preserving receptor-binding structural integrity. |
| Dual-Source Dossier Development | Parallel yeast and cereal approval pathways mitigate FDA-EFSA regulatory divergence risks for North American nutraceutical brands. |
| Plant Cell Culture Scale-Up | Recombinant Nicotiana benthamiana production bypasses Saccharomyces cerevisiae allergen labeling and supply bottlenecks. |
| EFSA Novel Food Compliance Investment | Full analytical profiles on mannoprotein co-extracts satisfy EU Green Deal transparency mandates for functional food positioning. |
| Captive Supply Agreement Structuring | Basel pharmaceutical contract manufacturers lock in lot-to-lot consistency below Swissmedic endotoxin thresholds. |
Research Methodology
Independent corroboration across extraction facility technical directors, nutraceutical contract manufacturing procurement leads, and pharmaceutical quality assurance managers underwrites the qualitative findings. Secondary validation draws from FDA GRAS notification databases, EFSA novel food opinion registers, and customs trade data on yeast-derived biopolymer flows. Bottom-up capacity assessments triangulate with top-down consumption estimates across powder, liquid, and encapsulated format demand.
Comparable-period anchoring to historical extraction yield improvements and regulatory approval timelines structures the projection horizon. Segmentation dimensions span product type, application tier, formulation grade, and distribution channel, with extraction technology source as an industry-specific cross-cut. CAGRs derive from installed capacity expansion schedules, EFSA claim adoption curves, and pharmaceutical-grade purity premium persistence. Forecast inputs incorporate membrane filtration adoption rates and NMPA registration pipeline velocity.
Several conditions sit outside the modeled scope, including unforeseen immunomodulatory claim restrictions, abrupt oat supply disruptions from climate events, and breakthrough recombinant production scale-ups. Forecasts reflect documented assumptions on regulatory pathway stability and buyer consolidation behavior. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Emergency Hangover Product Market