
 Low-Fat and Low Cholesterol Diet Market | 2026-2036
Low-Fat and Low Cholesterol Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat and Low Cholesterol Diet Market Foresight
Dietitian workforce shortages across clinical and retail channels is collapsing the ability of food manufacturers to validate health claims at scale. Nestlé S.A. leverages its in-house nutrition science infrastructure to sustain credibility in heart-health positioning. Danone S.A. anchors its competitive stance through specialized low-fat dairy fermentation capabilities. General Mills, Inc. competes by controlling shelf-space allocation in supermarket heart-health aisles.
Low-fat and low cholesterol diets restrict total fat intake to approximately twenty to thirty percent of caloric consumption while limiting dietary cholesterol below three hundred milligrams daily, primarily through modified processing techniques such as fat replacement with hydrocolloid stabilizers and lean protein extraction. These formulations serve cardiovascular risk reduction and metabolic disorder management in both preventive and therapeutic contexts. Plant-based foods within the product type dimension are capturing accelerated growth as ingredient technology improves mouthfeel parity with conventional fats. The meal replacement application commands premium margin pools due to its integration with supervised clinical protocols and subscription-based delivery models.
The FDA governs health claim substantiation for cholesterol-reduction labeling under the Nutrition Labeling and Education Act, while the USDA sets school meal standards that directly institutionalize low-fat procurement quotas. EFSA in Europe enforces stricter evidence thresholds for cardiovascular benefit claims, compressing market access for unsubstantiated entrants. Stakeholders must monitor evolving jurisprudence between self-regulated industry pledges and binding statutory limits on fat-content descriptors.
Market Dynamics
Hospital nutrition programs are expanding adoption of prescribed low-cholesterol meal plans, institutionalizing clinical procurement channels that bypass conventional retail distribution. The FDA's updated dietary guidelines on saturated fat labeling are simultaneously reshaping product formulation requirements across packaged food manufacturing.
Growth Catalysts
- FDA Saturated Fat Labeling:The FDA's updated dietary guidelines mandate clearer saturated fat disclosure, forcing manufacturers to reformulate products and creating certified demand for compliant ingredient systems.
- German Cardiac Rehabilitation Centers:Germany's dense network of cardiac rehabilitation facilities drives institutional procurement of certified low-fat food systems at volumes exceeding retail channel growth.
- Plant-Based Ingredient Technology:Advanced hydrocolloid stabilizers and fermentation-derived fat mimics now achieve mouthfeel parity with conventional fats, unlocking formulation flexibility previously constrained by sensory limitations.
Market Restraints
- Lean Protein Input Volatility:Egg white and whey protein concentrate prices fluctuate with feed grain markets, compressing margin predictability for low-fat dairy and bakery applications.
- EFSA Evidence Thresholds:EFSA enforces stricter substantiation requirements for cardiovascular benefit claims than FDA equivalents, blocking market access for unsubstantiated entrants seeking European distribution.
- Full-Fat Natural Positioning:Clean-label consumer segments increasingly favor full-fat minimally processed foods as wellness signifiers, creating substitution pressure against reduced-fat positioning.
Strategic Opportunities
- Subscription Clinical Meal Delivery:Supervised cardiac rehabilitation protocols integrate with direct-to-patient subscription models, capturing premium margin pools through recurring revenue structures.
- USDA School Meal Standards:USDA procurement quotas institutionalize low-fat food volumes through K-12 nutrition programs, creating predictable offtake for compliant manufacturers.
- Precision Fermentation Convergence:Combining precision fermentation with enzymatic fat modification enables novel lipid structures with targeted metabolic profiles, opening therapeutic nutrition applications.
Industry Challenges
- Dietitian Workforce Scarcity:Clinical and retail channels face collapsing capacity to validate health claims at scale, constraining manufacturer credibility assurance.
- Dual Jurisprudence Navigation:Stakeholders must simultaneously satisfy FDA health claim substantiation under NLEA and EFSA's divergent evidence frameworks, multiplying compliance architecture costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat and Low Cholesterol Diet Market |
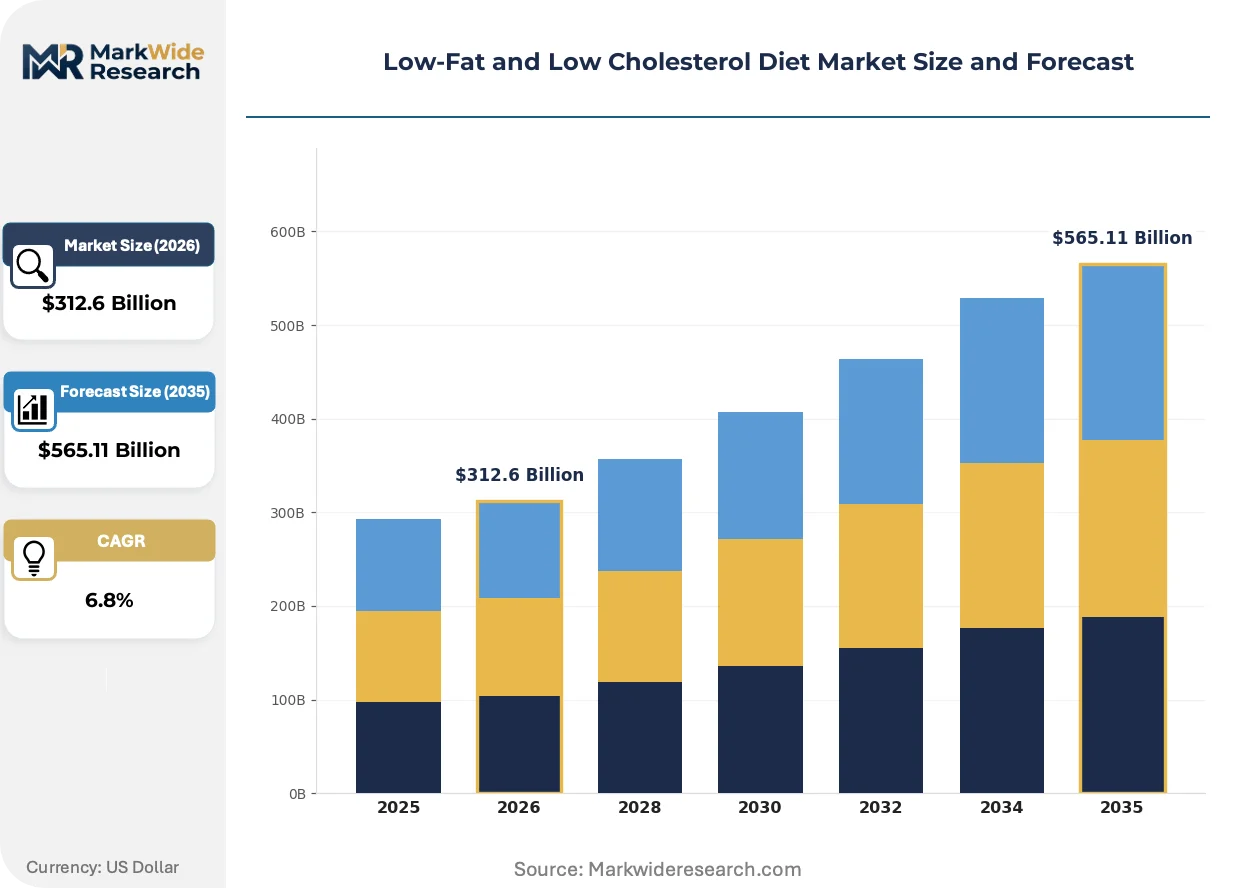
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Fat Dairy, Low-Fat Meat, Plant-Based Foods, Snack Bars Application: Weight Management, Heart Health, Nutritional Supplements, Meal Replacement End User: Health-Conscious Consumers, Diet Enthusiasts, Medical Patients, Fitness Followers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Nestlé S.A., Danone S.A., Unilever plc, General Mills, Inc., Kellogg Company, PepsiCo, Inc., The Kraft Heinz Company, Campbell Soup Company, Tyson Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat and Low Cholesterol Diet Market Shifts & Advancements
Formulation science and procurement channel structure are actively reshaping competitive position in low-fat and low-cholesterol nutrition. Three developments dominate the analysis window.
Enzymatic interesterification is decomposing the technical trade-off between saturated fat reduction and shelf stability in bakery and confectionery applications. Large-scale food manufacturers are adopting enzymatic processes at commercial scale to replace partial hydrogenation. This technology is decomposing the historical premium commanded by palm oil and fully hydrogenated shortenings in clean-label positioning.
EFSA's tightened cardiovascular health claim requirements are compressing formulation freedom for European market entrants. Manufacturers must now generate human intervention trial data for cholesterol-reduction claims that previously relied on surrogate biomarkers. Specialized low-fat dairy segments face the steepest compliance cost escalation, accelerating consolidation around in-house nutrition science capabilities.
Hospital procurement departments are consolidating vendor relationships through multi-year sole-source contracts for therapeutic meal systems. Group purchasing organizations are displacing fragmented supplier relationships with centralized cardiac nutrition programs. This concentration is most visible in German hospital networks, where procurement standardization now precedes product registration decisions.
Low-Fat and Low Cholesterol Diet Market Segmentation
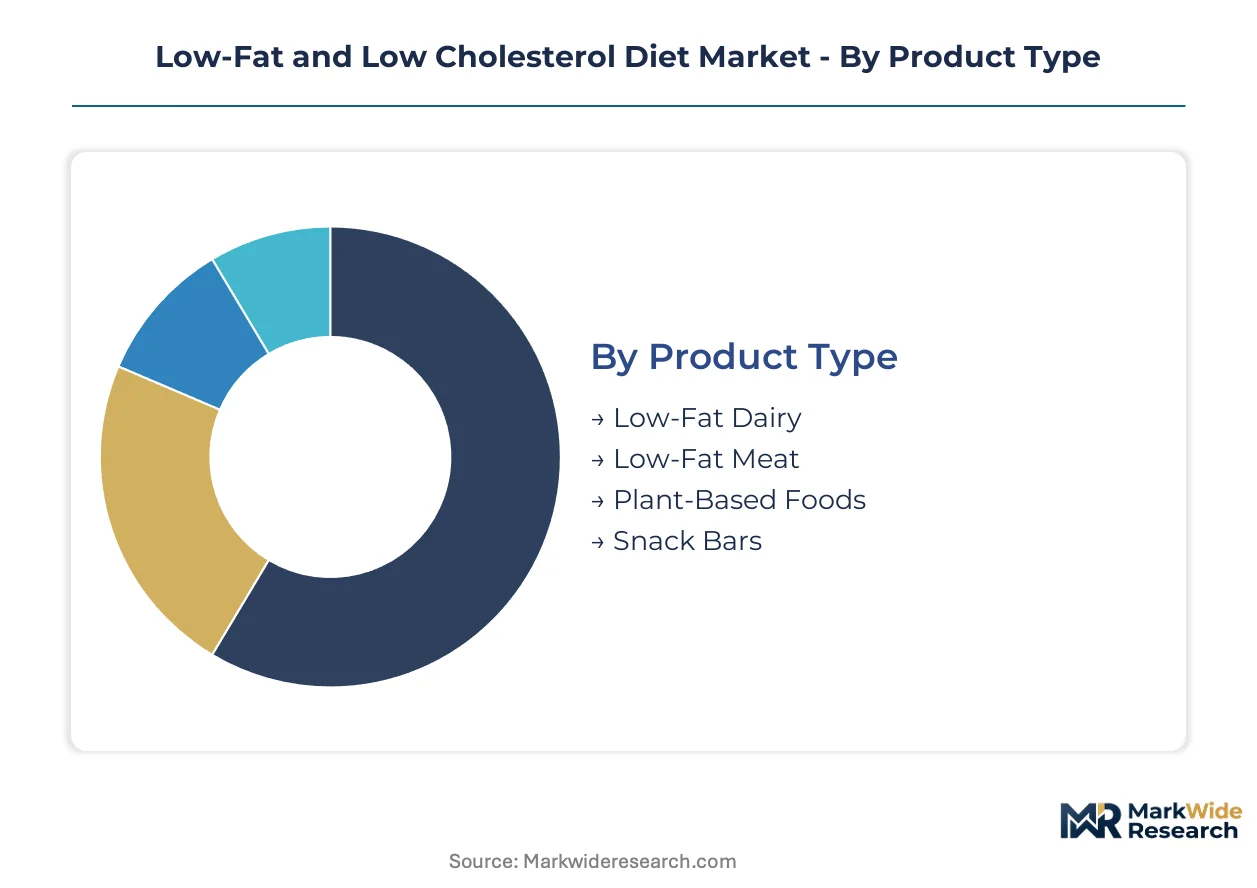
Segmentation in the low-fat and low cholesterol diet market determines formulation priorities and channel investment. Product type dictates manufacturing technology requirements, while application segments govern regulatory substantiation burdens and margin capture potential.
Product Type:
Margin pools concentrate in segments where enzymatic modification and hydrocolloid stabilization create formulation moats.
- Low-Fat Dairy:Specialized fermentation capabilities and fat-mimetic protein structures define competitive position. German cardiac rehabilitation centers and USDA school meal programs drive institutional procurement volumes for certified low-fat dairy systems.
- Plant-Based Foods:Advanced hydrocolloid stabilizers and fermentation-derived lipid analogs now achieve sensory parity with conventional fats. Accelerated growth concentrates in European markets where EFSA cardiovascular claim substantiation creates compliance barriers for conventional entrants.
- Low-Fat Meat:Lean protein extraction and texture modification technologies serve metabolic disorder management protocols.
- Snack Bars:Meal replacement positioning captures premium pricing through subscription-based clinical delivery models.
Low-fat dairy holds installed capacity. Plant-based foods is rotating up the share rankings.
Application:
Application segments stratify by clinical integration depth and recurring revenue structure.
- Meal Replacement:Supervised cardiac rehabilitation protocols integrate with direct-to-patient subscription models. Premium margin pools concentrate here through recurring revenue structures tied to clinical monitoring.
- Heart Health:FDA cholesterol-reduction claim substantiation under NLEA and EFSA's stricter evidence thresholds govern market access. Hospital nutrition programs institutionalize procurement bypassing retail distribution.
- Weight Management:Consumer-direct positioning competes on sensory acceptance and clean-label credentials.
- Nutritional Supplements:Functional ingredient concentration enables targeted metabolic profile delivery.
Meal replacement commands the steepest expansion trajectory. Heart health maintains the largest addressable patient population.
End User:
End user segments separate by clinical prescription authority versus self-directed purchasing behavior.
- Medical Patients:Prescribed low-cholesterol meal plans through hospital nutrition programs create captive demand. Procurement concentrates in German cardiac rehabilitation networks and US clinical meal delivery systems.
- Health-Conscious Consumers:Clean-label preferences increasingly favor full-fat minimally processed alternatives, creating substitution pressure on reduced-fat positioning.
- Diet Enthusiasts:Macro-tracking and self-quantification drive trial of novel fat replacement technologies.
- Fitness Followers:Body composition goals align with lean protein extraction products and portion-controlled formats.
Medical patients anchor volume predictability. Health-conscious consumers present the highest churn risk to conventional low-fat positioning.
Distribution Channel:
Channel structure determines margin capture and health claim validation requirements.
- Direct Sales:Clinical subscription models bypass retail margin extraction. German hospital group purchasing organizations consolidate vendor relationships through multi-year sole-source contracts for therapeutic meal systems.
- Supermarkets:Shelf-space allocation in heart-health aisles requires controlling category captaincy. General Mills and Nestlé compete through space allocation dominance and in-store nutrition counseling infrastructure.
- Online Retail:Direct-to-consumer models enable precision targeting of dietitian-validated claims.
- Health Food Stores:Staff nutrition expertise substitutes for scarce clinical dietitian capacity in claim validation.
Direct sales locks in recurring revenue. Online retail is climbing the fastest as subscription clinical models scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cardiac rehabilitation centers command institutional pricing premiums that US school meal programs cannot match. This asymmetry concentrates margin capture in European clinical procurement while compressing North American retail margins.
Germany
Cardiac rehabilitation networks in Bavaria and North Rhine-Westphalia institutionalize multi-year sole-source contracts for therapeutic meal systems. EFSA enforces stricter cardiovascular health claim substantiation than FDA equivalents, filtering unsubstantiated entrants from European distribution. Berlin-based group purchasing organizations now precede product registration with centralized vendor consolidation.
United States
USDA school meal standards institutionalize low-fat procurement quotas through K-12 nutrition programs, creating predictable offtake volumes. FDA cholesterol-reduction claim substantiation under NLEA governs packaged food labeling requirements. Hospital nutrition programs in Texas and California expand prescribed low-cholesterol meal plans that bypass conventional retail distribution.
France
ANSM and DGCCRF coordinate enforcement of cardiovascular benefit claims alongside EFSA evidence thresholds. Paris and Lyon cardiac centers drive institutional demand for certified low-fat dairy systems. French clean-label consumer segments increasingly favor full-fat minimally processed alternatives, creating substitution pressure on reduced-fat positioning.
United Kingdom
NHS England procurement frameworks standardize therapeutic nutrition specifications across hospital trusts. The Competition and Markets Authority monitors group purchasing concentration in clinical meal supply. London and Manchester rehabilitation networks consolidate vendor relationships through centralized cardiac nutrition programs.
Japan
METI promotes functional food claims through Foods with Function Claims registration, distinct from EFSA and FDA pathways. Tokyo and Osaka metabolic disorder management protocols integrate prescribed low-fat meal systems. Japanese consumers demonstrate higher acceptance of enzymatically modified fat structures than European markets.
Low-Fat and Low Cholesterol Diet Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the low-fat and low cholesterol diet market. Multinational packaged food conglomerates with in-house nutrition science infrastructure dominate clinical claim validation, while specialized dairy and plant-based fermentation specialists capture premium formulation margins. Two strategic archetypes define competitive position: integrated nutrition science platforms that sustain credibility in heart-health positioning, and shelf-space allocation controllers that secure heart-health aisle dominance in supermarket channels. M&A activity concentrates around precision fermentation capabilities, while strategic partnerships bridge the dietitian workforce scarcity gap.
Among Swiss and French nutrition science conglomerates, Nestlé S.A. exemplifies the integrated platform archetype through captive nutrition research infrastructure. Danone S.A. occupies a position within specialized low-fat dairy fermentation, anchoring competitive stance through protein structure capabilities. General Mills, Inc. represents shelf-space allocation dominance in North American retail channels. These three entities collectively illustrate the technology-cost bifurcation structuring competitive dynamics.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Unilever plc |
| General Mills, Inc. |
| Kellogg Company |
| PepsiCo, Inc. |
| The Kraft Heinz Company |
| Campbell Soup Company |
| Tyson Foods, Inc. |
| Others |
Supply & Pricing Matrix
Enzymatic interesterification of palm oil alternatives is redrawing ingredient sourcing maps while collapsing the premium once attached to fully hydrogenated shortenings. German cardiac rehabilitation centers now capture pricing premiums that US school meal programs cannot match, as institutional procurement bypasses retail margin extraction entirely.
Pricing Analysis
German hospital group purchasing organizations command 15-25% price premiums over North American retail channels for certified low-fat therapeutic meal systems. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated clinical formulations from supermarket heart-health aisle products and commodity private-label alternatives. Cost compression in standard-tier dairy applications is intensifying because egg white and whey protein concentrate prices fluctuate with feed grain volatility. Health-conscious consumer segments demonstrate highest price sensitivity, while medical patients under prescribed protocols show lowest elasticity due to third-party reimbursement structures.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites European palm oil dependency, though enzymatic modification facilities in the Netherlands and Germany are displacing Asian feedstock reliance. Supply concentrates in Germany, the United States, and France for finished therapeutic meal systems, while hydrocolloid stabilizer production draws from Thailand, Indonesia, and Brazil. Single-source vulnerability characterizes precision fermentation-derived fat mimics, where capacity remains tethered to Danish and Californian biotech clusters. Distribution runs through hospital group purchasing organizations in Europe and USDA-administered K-12 procurement frameworks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around German hospital networks and US school district purchasing cooperatives, fragmenting supplier pricing leverage across institutional channels.
For Market Incumbents: Fortify EFSA cardiovascular claim substantiation capabilities before regulatory thresholds tighten further, and secure multi-year sole-source contracts with Bavarian cardiac rehabilitation networks. Nestlé-style in-house nutrition science infrastructure represents the critical defensive moat against precision fermentation specialists threatening premium dairy positioning.
For New Entrants and Emerging Players: Lead with subscription-based clinical meal delivery models targeting Texas and California hospital nutrition programs, where prescribed low-cholesterol protocols bypass saturated retail shelf-space competition. USDA school meal procurement quotas offer the most penetrable volume anchor for compliant manufacturers lacking brand recognition.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platforms with enzymatic fat modification capabilities, as these assets command scarcity premia in therapeutic nutrition applications. Watch for EFSA evidentiary rulemaking as the signal indicating when consolidation around clinical claim validation infrastructure accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Cardiovascular Claim Investment | Human intervention trial data now gates European market access for cholesterol-reduction positioning. |
| Hospital GPO Sole-Source Contracting | Berlin-based purchasing organizations consolidate vendor relationships before product registration decisions. |
| Precision Fermentation Capacity Buildout | Danish and Californian biotech clusters control novel lipid structure production for metabolic disorder protocols. |
| USDA School Meal Compliance Certification | K-12 procurement quotas institutionalize predictable offtake volumes for low-fat dairy manufacturers. |
| Direct-to-Patient Subscription Launch | Texas cardiac rehabilitation networks integrate supervised protocols with recurring revenue capture models. |
Research Methodology
Desk research of FDA NLEA filings, EFSA health claim registers, USDA school meal procurement databases, and German hospital GPO contract disclosures preceded structured interviews with cardiac rehabilitation nutrition directors, supermarket category buyers, precision fermentation R&D leads, and clinical dietitian workforce planners. Bottom-up demand modeling across patient prescription volumes and institutional procurement quotas was triangulated against top-down manufacturer capacity disclosures.
Variance decomposition separated volume drivers from pricing dynamics across the projection horizon. Segmentation dimensions included product type, application, end-user archetype, and distribution channel, with regulatory jurisdiction clusters modeled as a cross-cutting dimension. CAGRs were derived from slope-intercept analysis of historical procurement trajectories, incorporating hydrocolloid stabilizer cost curves and dietitian workforce density as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside current EFSA evidentiary frameworks or USDA procurement continuity would require recalibration. Practitioners should keep alternative scenarios live as FDA saturated fat labeling enforcement and German hospital network consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market