
 North America Collagen-Based Supplements Market | 2026-2036
North America Collagen-Based Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Collagen-Based Supplements Market Analytics
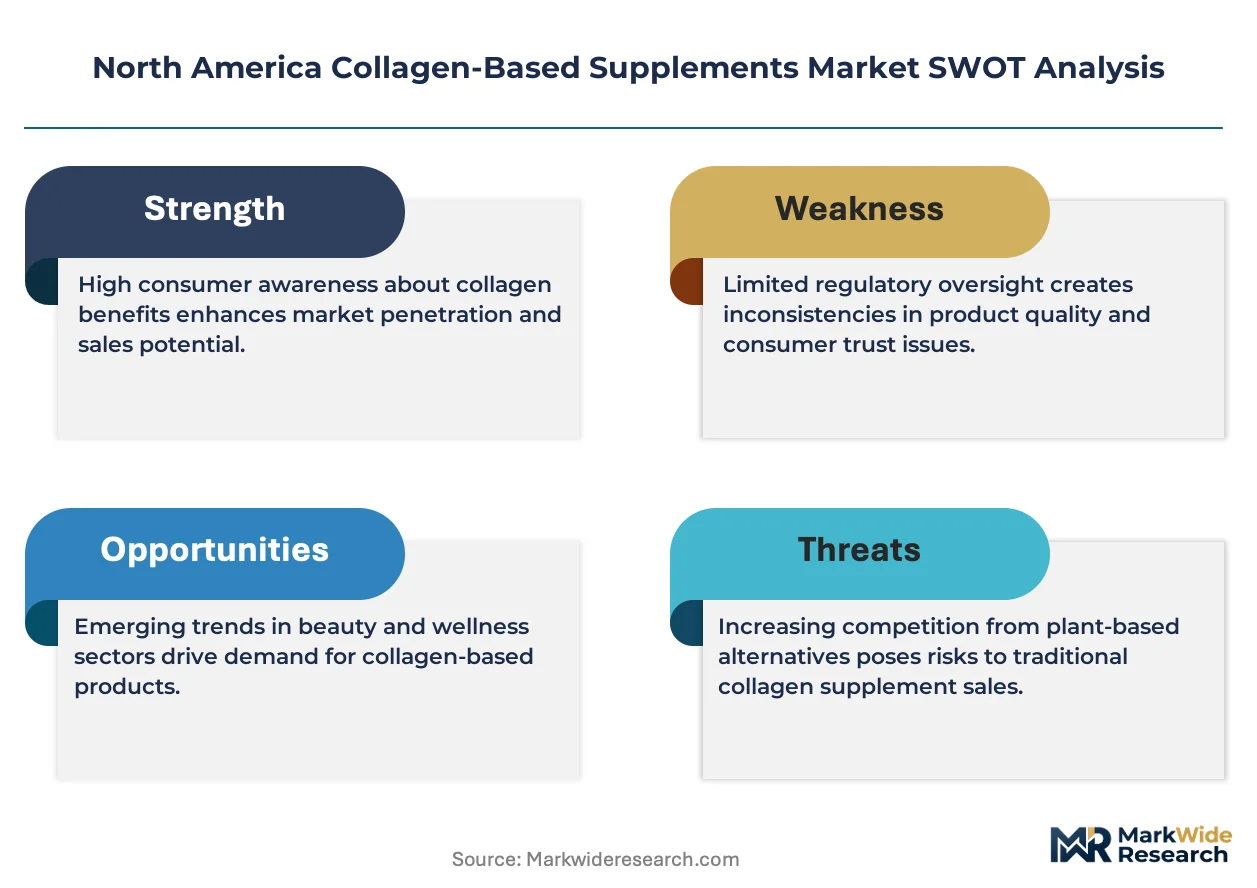
California's SB 343 truth-in-labeling mandates for recyclability claims is decoupling cosmetic-grade collagen positioning from verifiable sourcing documentation. Gelita AG leverages its Peptan bioactive peptide platform to sustain premium positioning across North American nutraceutical channels. Vital Proteins LLC anchors the direct-to-consumer segment with marine and bovine collagen specialization. Rousselot BV differentiates through gelweave technology leadership in pharmaceutical-grade applications.
Collagen-based supplements comprise hydrolyzed animal or marine-derived proteins processed through enzymatic hydrolysis to yield peptides with molecular weights typically below 10 kilodaltons, formulated for dermal matrix support, connective tissue maintenance, and exercise recovery applications. Hydrolyzed collagen dominates current production volumes due to superior bioavailability and neutral sensory profiles in beverage applications. Collagen peptides represent the fastest-expanding category as sports nutrition brands integrate them into ready-to-drink formulations. The gummy format is gaining shelf space in mass retail channels, though powder maintains margin concentration through subscription replenishment models.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements and Health Canada's Natural and Non-prescription Health Products Directorate standards govern ingredient purity, label substantiation, and adverse event reporting across the North American trade corridor. The FTC's endorsement guidelines further constrain influencer marketing claims, compelling brands to build clinical evidence portfolios. Stakeholders must monitor pending DSHEA modernization legislation and provincial variations in natural health product licensing to anticipate compliance cost trajectories and competitive repositioning requirements.
Market Dynamics
FDA's evolving DSHEA modernization discussions are compelling North American collagen manufacturers to build clinical substantiation portfolios ahead of stricter label claim requirements, reshaping R&D allocation and competitive positioning across the value chain.
Growth Catalysts
- Sports nutrition integration:Professional athletic programs and wellness clinics across California and Toronto are embedding collagen peptides into joint recovery protocols, creating institutional procurement pull.
- FTC endorsement guideline enforcement:The FTC's tightened influencer marketing standards are filtering out unsubstantiated claims, rewarding brands with clinical evidence and consolidating consumer trust toward verified products.
- Enzymatic hydrolysis refinement:Advances in targeted protease applications are yielding sub-10 kilodalton peptide fractions with improved bioavailability, expanding formulation possibilities in ready-to-drink beverages.
Market Restraints
- Bovine collagen supply concentration:North American bovine hide sourcing depends on regional meatpacking capacity, exposing peptide producers to livestock cycle volatility and rendering plant bottlenecks.
- Marine collagen cost structure:Wild-caught marine feedstock from North Atlantic fisheries carries premium extraction and sustainability certification costs that compress margin at mid-tier price points.
- Health Canada licensing timelines:Natural Health Product Directorate review periods for novel collagen delivery formats extend commercialization cycles by 18-24 months versus US notification pathways.
Strategic Opportunities
- Functional food channel expansion:California's functional food cluster offers co-manufacturing partnerships for collagen-fortified snacks targeting the state's health-conscious demographic concentration.
- Gummy format mass retail penetration:Shelf space expansion in US mass retail channels for chewable collagen formats addresses convenience-seeking consumers outside core supplement buyers.
- Provincial natural health product harmonization:Pending alignment between Health Canada and select US state-level requirements could streamline cross-border labeling and reduce compliance fragmentation.
Industry Challenges
- Peptide characterization expertise gap:Analytical chemists capable of validating molecular weight distributions and bioactivity markers command premium compensation, constraining mid-scale manufacturer quality teams.
- Clinical trial design complexity:Substantiating dermal matrix support claims requires dermatological endpoint validation that extends study duration and raises capital requirements for evidence generation.
- Subscription fulfillment infrastructure:Powder format replenishment models demand specialized packaging automation and cold-chain logistics that strain legacy contract manufacturer capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Collagen-Based Supplements Market |
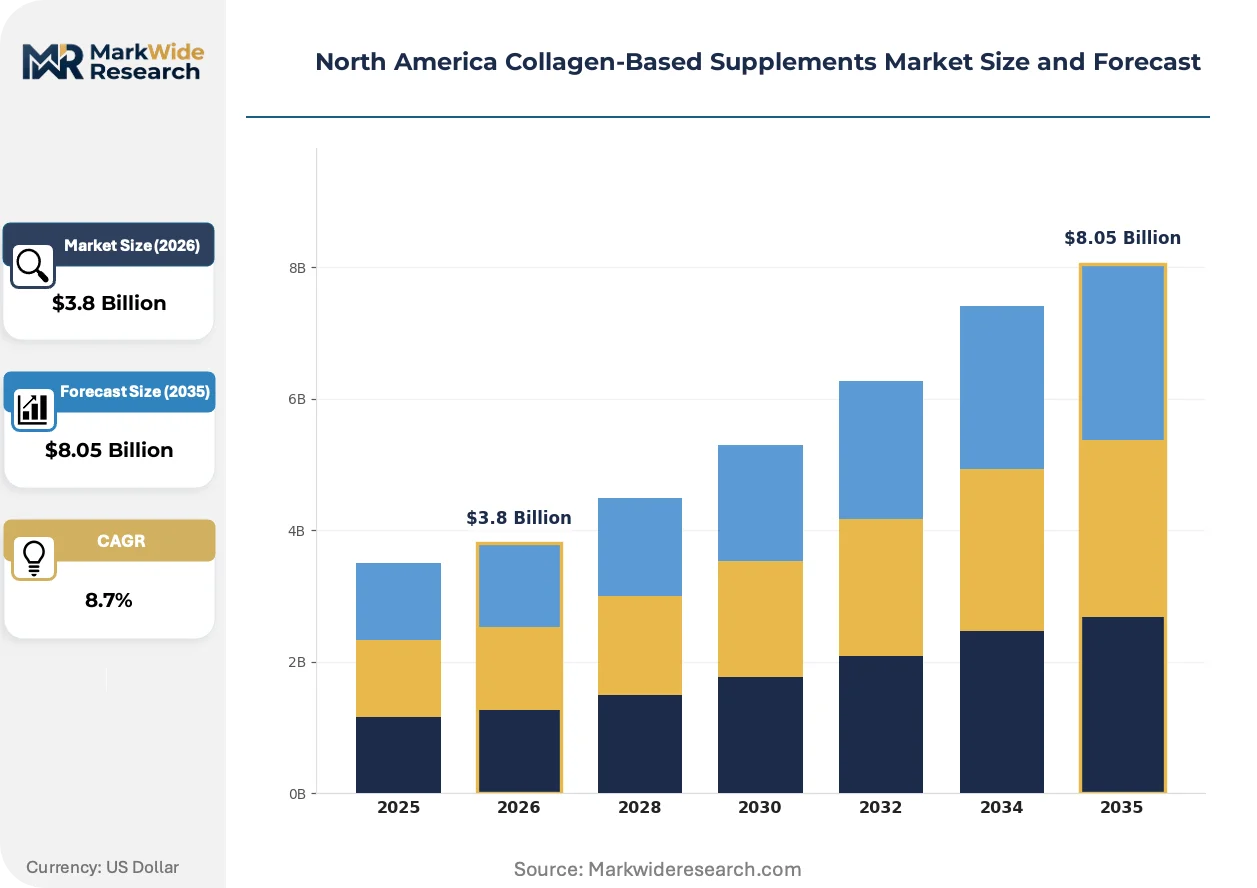
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Undenatured Collagen Form: Powder, Capsule, Liquid, Gummy Target Audience: Fitness Enthusiasts, Aging Population, Beauty Conscious Consumers, Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Gelita AG, Nestlé SA, Vital Proteins LLC, Glanbia Plc, Amway Corp., Rousselot BV, Nitta Gelatin Inc., Great Lakes Wellness, NeoCell LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Collagen-Based Supplements Market Evolving Landscape
Enzymatic processing advances and regulatory disclosure requirements are compressing product development timelines while elevating transparency standards across North American collagen value chains.
Precision fermentation of recombinant collagen mimics is automating quality control consistency in peptide production. Biotech startups in Boston and San Diego are piloting microbial expression systems that bypass animal sourcing entirely. This technology is automating batch-to-batch uniformity while reducing dependence on rendering supply cycles.
California's SB 343 truth-in-labeling mandates for recyclability claims are forcing cosmetic-grade collagen suppliers to decouple from unverifiable sourcing narratives. Brands must now document supply chain provenance to maintain shelf access in the state's retail channels. The functional food cluster is responding by adopting blockchain-tracked marine certifications.
Direct-to-consumer subscription models are displacing traditional retail replenishment patterns among millennial and Gen-Z buyers. Vital Proteins and similar specialists capture recurring revenue through personalized dosing algorithms and flavor customization. This behavioral shift concentrates most visibly in metropolitan California and greater Toronto, where digital-native consumers prioritize convenience over in-store discovery.
North America Collagen-Based Supplements Market Segmentation
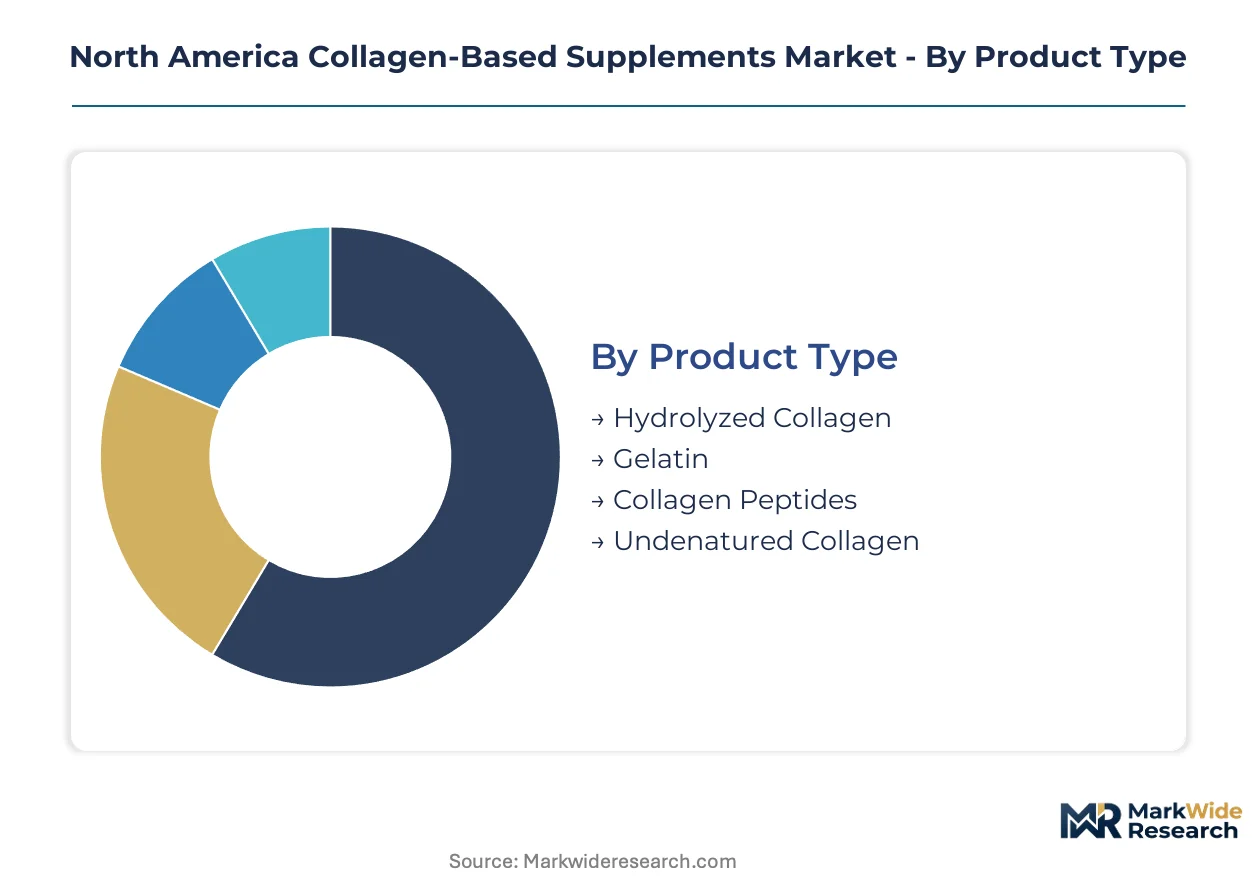
Collagen supplement manufacturers deploy distinct formulation and positioning strategies across product architectures, delivery formats, consumer psychographics, and channel economics. Segmentation clarity exposes where R&D investment concentrates versus where margin compression threatens incumbent positioning.
Product Type:
Standardization dominates enzymatic processing outputs, yet premium tiers command pricing power through molecular weight specificity and bioactivity certification.
- Hydrolyzed Collagen:Enzymatic hydrolysis yields peptides below 10 kilodaltons with neutral sensory profiles that integrate seamlessly into ready-to-drink beverages. Sports nutrition procurement across California's functional food cluster drives volume concentration, though margin pressure intensifies as commodity peptide suppliers expand capacity.
- Collagen Peptides:Fractionated bioactive sequences demonstrate validated absorption kinetics in dermatological and orthopedic endpoints. Wellness clinics in the greater Toronto metropolitan area embed these into joint recovery protocols, creating institutional demand pull that sustains premium positioning against generic hydrolyzed alternatives.
- Gelatin:Partially hydrolyzed collagen retains gelling functionality for food matrix applications rather than direct supplementation.
- Undenatured Collagen:Native triple-helix preservation targets specific immunomodulatory mechanisms with narrower clinical indication scope.
Most installed capacity flows through Hydrolyzed Collagen. Expansion is steepest in Collagen Peptides.
Form:
Convenience premiums and subscription economics reshape format preference hierarchies across generational cohorts and channel strategies.
- Powder:Bulk dosing flexibility and flavor customization anchor direct-to-consumer replenishment models with recurring revenue concentration. Subscription fulfillment infrastructure demands specialized packaging automation that strains legacy contract manufacturers serving California and Toronto metropolitan demand clusters.
- Gummy:Chewable delivery captures shelf space expansion in US mass retail channels, converting convenience-seeking consumers outside core supplement buyer demographics. FTC endorsement guideline enforcement filters unsubstantiated claims, rewarding brands with clinical evidence portfolios in this high-visibility format.
- Capsule:Standardized unit dosing serves pharmacy and professional channel distribution with compliance advantages.
- Liquid:Ready-to-drink positioning targets on-the-go consumption occasions with higher per-serving logistics costs.
Margin concentration remains highest in Powder through subscription lock-in. Gummy formats gain share fastest in mass retail penetration.
Target Audience:
Demographic-specific positioning determines clinical substantiation requirements and influencer marketing compliance exposure.
- Fitness Enthusiasts:Exercise recovery and connective tissue maintenance claims dominate peptide integration into sports nutrition formulations. California's athletic program procurement and Toronto wellness clinic protocols institutionalize demand, though dermatological endpoint validation requirements extend evidence generation timelines.
- Aging Population:Joint mobility and dermal matrix support claims require longitudinal study designs that raise capital requirements for label substantiation. FDA DSHEA modernization discussions compel manufacturers to build clinical portfolios ahead of stricter requirements, reshaping competitive positioning toward evidence-rich brands.
- Beauty Conscious Consumers:Cosmetic-grade positioning faces California SB 343 truth-in-labeling mandates that decouple unverifiable sourcing narratives from shelf access.
- Athletes:Professional program embedding creates institutional procurement pull with batch testing and contamination control specifications.
Procurement institutionalization runs deepest through Fitness Enthusiasts. Evidence investment requirements escalate fastest for Aging Population positioning.
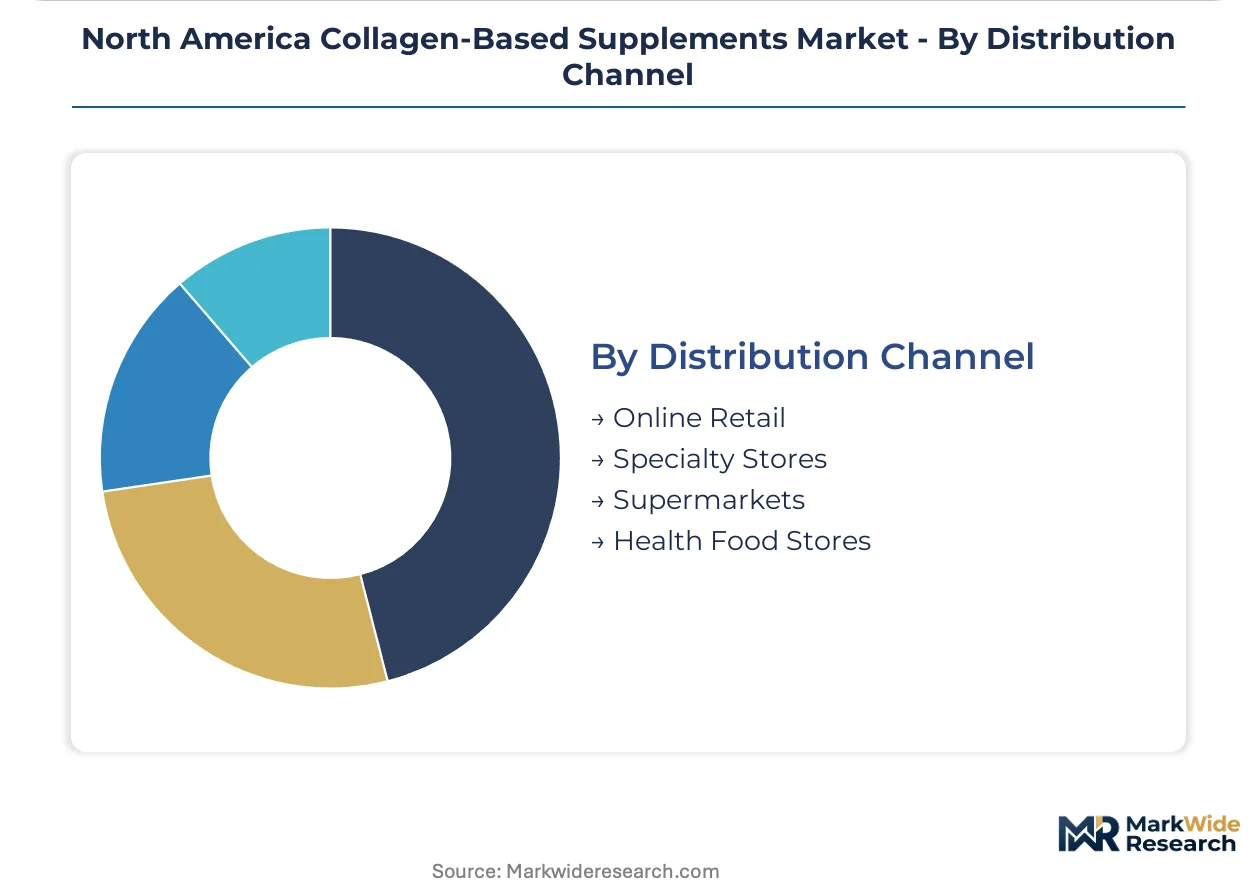
Distribution Channel:
Channel selection determines compliance burden, margin structure, and consumer data capture capabilities across the North American trade corridor.
- Online Retail:Direct-to-consumer models concentrate in California and greater Toronto where digital-native millennials and Gen-Z buyers prioritize convenience over in-store discovery. Personalized dosing algorithms and flavor customization capture recurring revenue, though subscription fulfillment infrastructure demands specialized logistics automation.
- Specialty Stores:Curated assortment and staff expertise sustain premium positioning for clinically substantiated peptide formulations. Health Canada Natural Health Product Directorate licensing timelines for novel delivery formats extend commercialization cycles versus US notification pathways, compressing margin for cross-border inventory strategies.
- Supermarkets:Mass retail shelf space expansion for gummy formats democratizes access but intensifies price competition.
- Health Food Stores:Natural positioning alignment serves clean-label preference segments with regional clustering in California's functional food corridor.
Recurring revenue concentration flows through Online Retail. Regulatory complexity escalates fastest in Specialty Stores serving cross-border demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The collagen-based supplements industry traces its North American scaling to post-war gelatin processing infrastructure repurposed for nutraceutical applications during the 1990s functional food wave.
United States
California's functional food cluster anchors formulation innovation, while Texas meatpacking corridors supply bovine hide feedstock for enzymatic processing. The FDA's DSHEA modernization discussions are compelling manufacturers to build clinical substantiation portfolios ahead of stricter label claim requirements. Greater Los Angeles and San Diego biotech corridors are piloting precision fermentation alternatives to animal-derived collagen.
Canada
Toronto's wellness clinic networks institutionalize collagen peptide procurement for joint recovery protocols, creating stable institutional demand. Health Canada's Natural and Non-prescription Health Products Directorate licensing timelines extend commercialization cycles for novel delivery formats by 18-24 months versus US pathways. Vancouver's coastal proximity supports marine collagen extraction facilities serving Pacific Northwest distribution channels.
Mexico
Bovine hide rendering capacity in Guadalajara's leather processing district supplies raw material for cross-border peptide production. Mexico's Federal Commission for the Protection against Sanitary Risk (COFEPRIS) dietary supplement regulations are harmonizing with US FDA notification pathways to streamline export certification. Monterrey's industrial corridor hosts contract manufacturing facilities serving US brand private-label requirements.
North America Collagen-Based Supplements Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American collagen value chain. Vertically integrated rendering-to-peptide operators command supply security advantages, while specialized brands concentrate on clinical substantiation and direct-to-consumer channel control. The market structures around three archetypes: multinational ingredient suppliers with enzymatic processing scale, wellness-focused consumer brands with subscription infrastructure, and pharmaceutical-grade specialists with bioactivity certification capabilities. Dominant competitive moves include backward integration into rendering capacity and strategic partnerships with sports nutrition formulators.
Among German-origin ingredient suppliers, Gelita AG exemplifies the enzymatic processing archetype through its Peptan bioactive peptide platform. Vital Proteins LLC occupies the direct-to-consumer specialist tier with marine and bovine collagen diversification. Rousselot BV represents the pharmaceutical-grade segment through gelweave technology positioning.
| Leading Market Players |
|---|
| Gelita AG |
| Nestlé SA |
| Vital Proteins LLC |
| Glanbia Plc |
| Amway Corp. |
| Rousselot BV |
| Nitta Gelatin Inc. |
| Great Lakes Wellness |
| NeoCell LLC |
| Others |
Value Network & Pricing Analysis
Bovine hide commodity indices from Texas and Kansas meatpacking corridors cascade through enzymatic processing tiers, compressing margins at standard-grade peptide suppliers while amplifying premium capture for bioactivity-certified alternatives. This feedstock-cost transmission splits the market into subscription-anchored powder formats, mass-retail gummy penetrations, and pharmaceutical-grade gelweave applications with divergent margin structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Peptan-certified bioactive peptides from generic hydrolyzed alternatives and unbranded commodity powders. Price differentiation hinges on molecular weight validation and FDA-compliant label substantiation, with clinical evidence portfolios commanding subscription premiums. Pricing pressure stems from livestock cycle volatility exposing mid-tier bovine collagen producers to margin compression. Fitness enthusiasts demonstrate lowest price sensitivity through institutional procurement, while mass-market gummy buyers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-consumer channels handle subscription replenishment demand across California and Toronto metropolitan clusters, while specialty retail and mass merchandising serve intermittent purchasers. Geographic supply concentration centers on Texas bovine rendering, North Atlantic marine fisheries, and Guadalajara leather processing districts feeding cross-border peptide production. Raw material dependencies include enzymatic protease inputs, pharmaceutical-grade gelatin precursors, and wild-caught marine feedstock with sustainability certification requirements. Supply chain risk concentrates in single-source vulnerability to livestock cycle disruptions and rendering plant bottlenecks. Distribution runs through vertically integrated rendering-to-peptide operators, specialized contract manufacturers, and direct-to-consumer fulfillment infrastructure with cold-chain logistics demands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American collagen supplements rests on enzymatic hydrolysis efficiency gains and clinical evidence portfolios that sustain premium positioning against commodity peptide expansion.
For Market Incumbents: Deploy backward integration into Texas and Kansas rendering capacity to secure bovine hide supply against livestock cycle volatility. Fortify peptide characterization expertise through analytical chemist recruitment and molecular weight validation infrastructure, defending against precision fermentation substitutes from Boston and San Diego biotech corridors. Channel control through subscription infrastructure locks in recurring revenue against mass-retail price erosion. For New Entrants and Emerging Players: Enter via functional food co-manufacturing partnerships in California's innovation cluster, targeting white-space in collagen-fortified snacks and ready-to-drink beverages outside core supplement demographics. Provincial natural health product harmonization between Health Canada and US state requirements offers regulatory arbitrage opportunities for novel delivery formats. A direct-to-consumer launch with personalized dosing algorithms captures millennial and Gen-Z buyers in greater Toronto and California metropolitan markets. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade specialists possessing gelweave technology and bioactivity certification capabilities. Long-term viability favors assets with clinical substantiation portfolios positioned ahead of FDA DSHEA modernization requirements. The signal to watch is Health Canada licensing timeline compression for novel delivery formats, indicating regulatory pathway maturation and cross-border scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | FDA DSHEA modernization discussions compel evidence generation ahead of stricter label claim requirements. |
| Backward Integration into Rendering | Texas and Kansas meatpacking corridor control secures bovine hide supply against livestock cycle volatility. |
| Precision Fermentation Piloting | Boston and San Diego biotech corridors automate batch uniformity while reducing animal sourcing dependence. |
| Direct-to-Consumer Infrastructure | California and Toronto metropolitan subscription models capture recurring revenue through personalized dosing algorithms. |
| Provincial Regulatory Harmonization | Health Canada and US state alignment streamlines cross-border labeling and reduces compliance fragmentation. |
Research Methodology
Bottom-up sports nutrition and wellness clinic procurement modeling reconciled against top-down enzymatic processing capacity tracking forms the analytical core of this study. Primary interviews with peptide manufacturing executives, sports nutrition formulators, Health Canada licensing consultants, and California functional food cluster managers combined with secondary validation from FDA docket filings, SEC 10-K disclosures from ingredient suppliers, and Health Canada Natural Health Product Directorate approval databases. Triangulation between demand-side institutional procurement patterns and supply-side rendering capacity utilization ensures statistical integrity across the analysis window.
Historical trendline analysis of collagen peptide integration into joint recovery protocols and ready-to-drink beverage formulations established baseline growth trajectories. Segmentation modeling across product type, delivery format, target audience psychographics, and distribution channel economics generated volume and value outputs throughout the forecast period. CAGRs were derived from enzymatic hydrolysis capacity expansion announcements, subscription replenishment velocity metrics, and mass retail shelf space allocation trends in California and Toronto demand clusters.
Inputs from FDA DSHEA modernization dockets and Health Canada licensing timelines were available through the study window; gaps in precision fermentation commercialization schedules introduce uncertainty bands around microbial collagen mimic adoption curves. Forecasts reflect assumptions regarding regulatory pathway harmonization and clinical evidence portfolio buildout rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Dextrose Monohydrate Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market