
 Digestive and Intestinal Remedies Market | 2026-2036
Digestive and Intestinal Remedies Market Size, Share, and Industry Trends Forecast 2026-2036
Digestive and Intestinal Remedies Market Intelligence
Subscription-based probiotic replenishment services is repositioning how consumers maintain gastrointestinal wellness, shifting single-transaction purchases into recurring revenue relationships. Bayer AG leverages its established consumer health infrastructure to sustain pharmacy shelf presence across multiple continents. Sanofi competes through specialized gastrointestinal prescription-to-OTC transition capabilities. Takeda Pharmaceutical Company Limited anchors its position in Japan and select Asian markets through deep expertise in acid-related disorders.
Digestive and intestinal remedies encompass pharmacological and biologically active preparations formulated to alleviate dyspepsia, motility disorders, acid imbalance, and microbial dysbiosis, typically delivered through tablets, capsules, powders, or liquid suspensions with defined active ingredient concentrations. These products serve both acute symptom relief and chronic condition management in outpatient and self-care settings. Probiotics represents the fastest-expanding category as live-culture stability technologies improve shelf-life and gastric survivability. Antacids occupies the largest revenue pool due to immediate symptom relief and universal recognition, though margin compression from private-label competition intensifies. Laxatives maintains steady demand among elderly populations, with formulation innovation toward osmotic and stimulant combinations driving modest premiumization.
The FDA's OTC monograph reform and the EMA's evolving guidance on live biotherapeutic products create dual compliance pathways that shape formulation investment and labeling claims across North American and European markets. BIS certification requirements in India and CDSCO oversight of probiotic health claims add further territorial complexity for multinational portfolios. Stakeholders must monitor regulatory divergence between jurisdictions where probiotics are classified as foods versus drugs, as this classification determines distribution channels, marketing freedom, and clinical substantiation burdens.
Market Dynamics
Prescription-to-OTC regulatory switches are compressing the traditional physician-mediated pathway, forcing incumbents to rebuild go-to-market capabilities around direct consumer engagement and pharmacy chain negotiations.
Growth Catalysts
- FDA OTC Monograph Reform:Accelerated reclassification timelines for acid suppression therapies expand addressable populations beyond prescription-only access barriers.
- Live-culture stabilization advances:Improved gastric survivability and ambient shelf-life stability unlocks probiotic distribution through conventional retail without cold-chain dependency.
- Employer wellness programs:Large US corporations now subsidize digestive health subscriptions as preventive care cost-containment measures, creating institutional procurement channels.
Market Restraints
- Private-label margin compression:CVS Health and Walgreens Boots Alliance shelf-space dominance in antacids erodes branded pricing power through captive sourcing.
- Strain-specific IP limitations:Probiotic composition patents face narrow claim construction, enabling rapid follower formulations without licensing.
- CDSCO health claim substantiation:India's dual food-drug classification creates compliance ambiguity that delays product registration and marketing authorization.
Strategic Opportunities
- Chronic condition management platforms:Integrated irritable bowel syndrome monitoring apps paired with personalized probiotic protocols capture recurring revenue beyond single-SKU sales.
- EMA live biotherapeutic guidance:Harmonized European pathways for microbiome-based therapeutics reduce regulatory fragmentation for cross-border launches.
- Direct-to-consumer microbiome testing:At-home gut health diagnostics create upstream data capture that funnels consumers into subscription replenishment programs.
Industry Challenges
- Clinical trial recruitment bottlenecks:Heterogeneous symptom reporting in functional gastrointestinal disorders complicates endpoint standardization for regulatory submissions.
- Legacy ERP integration:Pharmaceutical batch record systems require substantial modification to accommodate live-culture manufacturing variability and stability tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestive and Intestinal Remedies Market |
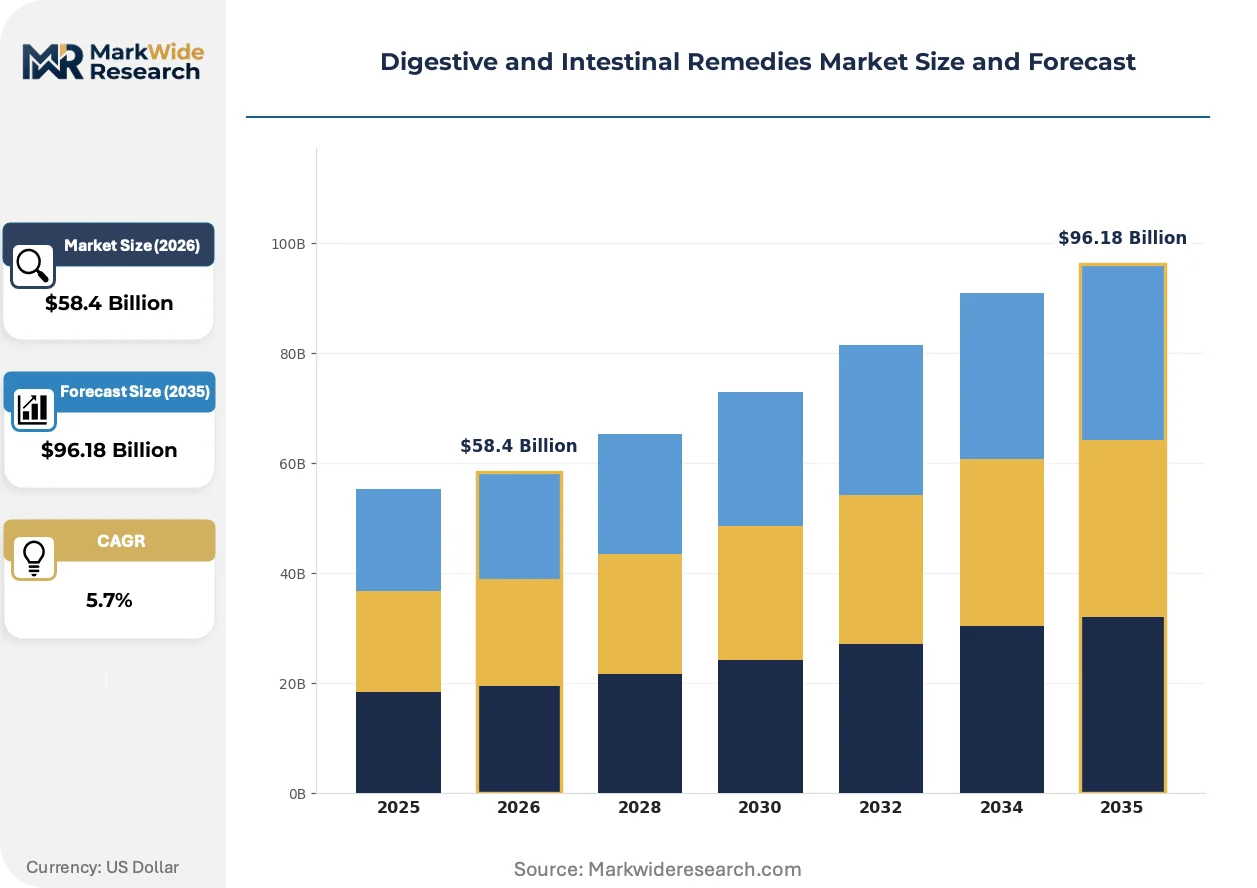
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $96.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, Laxatives, Probiotics, Digestive Enzymes Application: Acid Reflux, Constipation, Diarrhea, Bloating End User: Adults, Children, Elderly, Pregnant Women Distribution Channel: Pharmacies, Online Retail, Supermarkets, Hospitals |
| Companies Covered | Procter & Gamble, Boehringer Ingelheim GmbH, Bayer AG, Abbott, Reckitt Benckiser Group PLC, Johnson & Johnson Services Inc., Sanofi, Takeda Pharmaceutical Company Limited, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestive and Intestinal Remedies Market Strategic Shifts & Innovations
Microbiome science is migrating from academic research into commercial formulation, rewiring how manufacturers substantiate efficacy claims and structure clinical development programs.
Encapsulation technologies using alginate-based matrix systems are rewriting probiotic delivery economics. Retail pharmacies in Germany and the Netherlands now stock room-temperature stable formulations previously restricted to refrigerated health-food channels. This thermal tolerance expansion collapses distribution cost structures and enables shelf placement adjacent to traditional antacids.
REACH compliance obligations for novel excipient introductions are tightening formulation flexibility across European manufacturing. ECHA substance evaluation timelines now extend development cycles by 18-24 months for innovative coating materials. Contract manufacturers in Italy and Spain are consolidating to spread regulatory compliance overhead across larger production volumes.
Subscription auto-replenishment is displacing episodic pharmacy purchasing for maintenance-category digestive products. Direct-to-consumer platforms in the United States capture longitudinal consumption data that informs personalized strain rotation protocols. Employer benefits administrators now treat these subscriptions as eligible flexible spending account expenditures, accelerating household penetration.
Digestive and Intestinal Remedies Market Segmentation
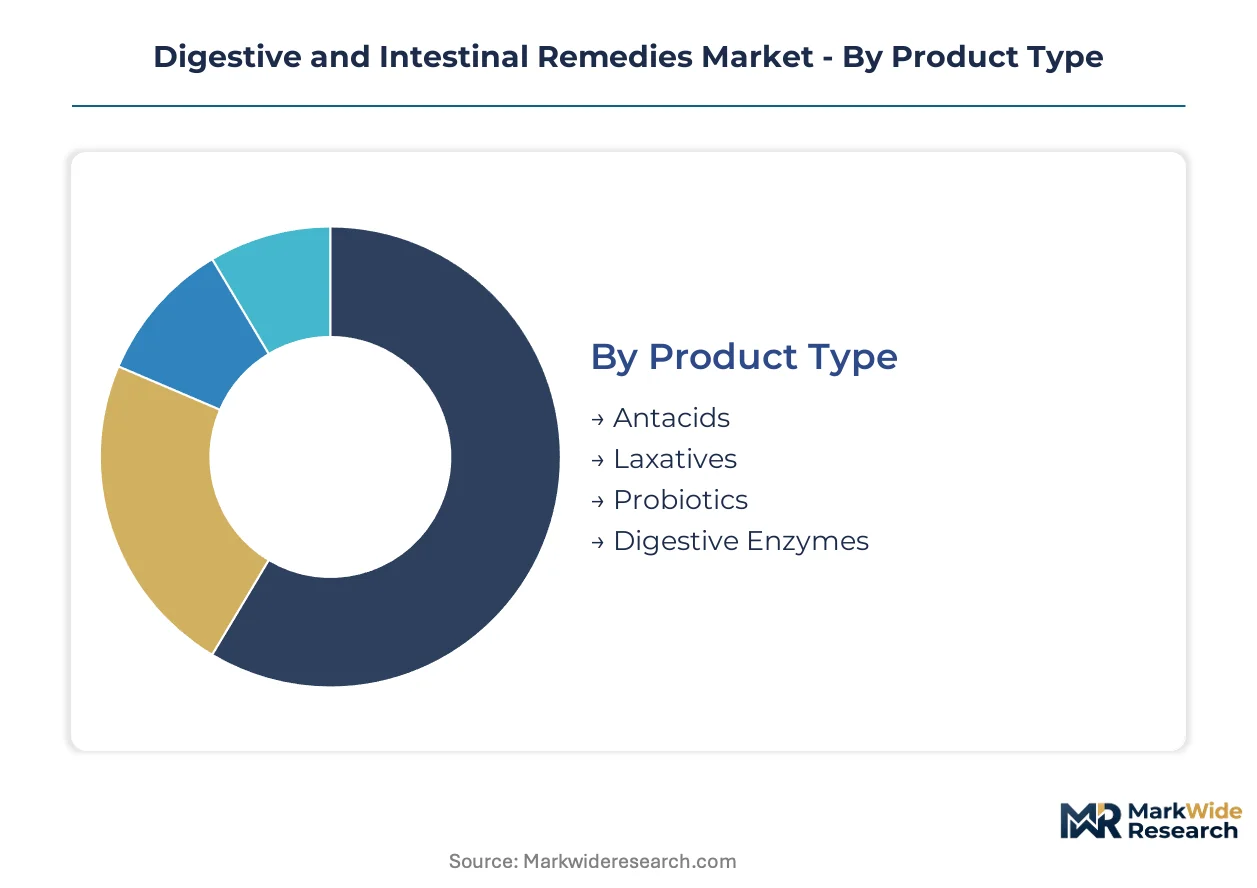
Segmentation in digestive and intestinal remedies determines which regulatory pathways manufacturers must navigate, from FDA OTC monograph compliance for antacids to live biotherapeutic product frameworks for probiotics. Understanding these divisions reveals where formulation investments concentrate and which distribution channels offer the highest margin capture.
Product Type:
FDA OTC monograph reform applies differentially across this category, with acid suppression therapies facing accelerated reclassification timelines while live-culture products encounter evolving EMA guidance on microbiome-based claims.
- Antacids:Aluminum, magnesium, or calcium-based neutralizing agents delivered through chewable tablets, liquids, or effervescent powders. Demand concentrates in the United States through pharmacy chain private-label programs, though margin compression from CVS Health and Walgreens Boots Alliance captive sourcing erodes branded pricing power.
- Probiotics:Live microbial cultures formulated for gastric survivability through alginate-based encapsulation or freeze-dried stabilization. Demand concentrates in Germany and the Netherlands where room-temperature stable formulations now occupy conventional retail shelves, collapsing cold-chain distribution costs and enabling placement adjacent to traditional digestive remedies.
- Laxatives:Osmotic, stimulant, or bulk-forming agents addressing motility disorders. Elderly populations in Japan drive steady demand for combination formulations.
- Digestive Enzymes:Pancreatic or fungal-derived proteins facilitating macronutrient breakdown. Specialized applications in post-surgical recovery protocols create niche premium positioning.
Leading the category by volume: Antacids. Growing fastest: Probiotics.
Application:
Symptom-specific formulations command distinct pricing tiers based on whether they target acute relief or chronic condition management platforms.
- Acid Reflux:Proton pump inhibitors and H2 receptor antagonists transitioning from prescription to OTC status under FDA accelerated reclassification. Employer wellness programs in the United States increasingly subsidize preventive acid suppression as cost-containment measures.
- Constipation:Osmotic and stimulant combination therapies with formulation innovation toward gentle overnight relief. Elderly demographics in aged-care facilities sustain recurring procurement contracts.
- Diarrhea:Loperamide-based suppression or probiotic restoration protocols. Travel medicine channels and institutional food-service settings generate concentrated bulk purchasing.
- Bloating:Simethicone-based gas relief or targeted probiotic strain combinations. Direct-to-consumer microbiome testing funnels consumers into personalized subscription protocols.
Acid Reflux generates the largest revenue pool. Bloating shows the steepest expansion trajectory as personalized gut health platforms proliferate.
End User:
Age and physiological status determine dosage formulation, packaging safety requirements, and marketing claim substantiation burdens.
- Adults:Standard-strength tablets and capsules dominating pharmacy and online retail channels. Subscription auto-replenishment platforms capture longitudinal consumption data for personalized strain rotation.
- Elderly:Modified-release formulations and liquid suspensions addressing polypharmacy interactions. Aged-care procurement in Japan and Germany sustains stable demand for gentle laxative and acid suppression therapies.
- Children:Palatable liquid formulations with precise dosing mechanisms. Pediatric claim substantiation requires separate clinical trial endpoints, extending development timelines.
- Pregnant Women:Calcium-based antacids and fiber-based laxatives with established safety profiles. Pharmacy counseling requirements create consultative purchase environments.
Adults constitute the primary volume base. Elderly segments climb the fastest as population aging intensifies across developed markets.
Distribution Channel:
Channel selection determines cold-chain requirements, shelf-life constraints, and whether subscription replenishment models can operate.
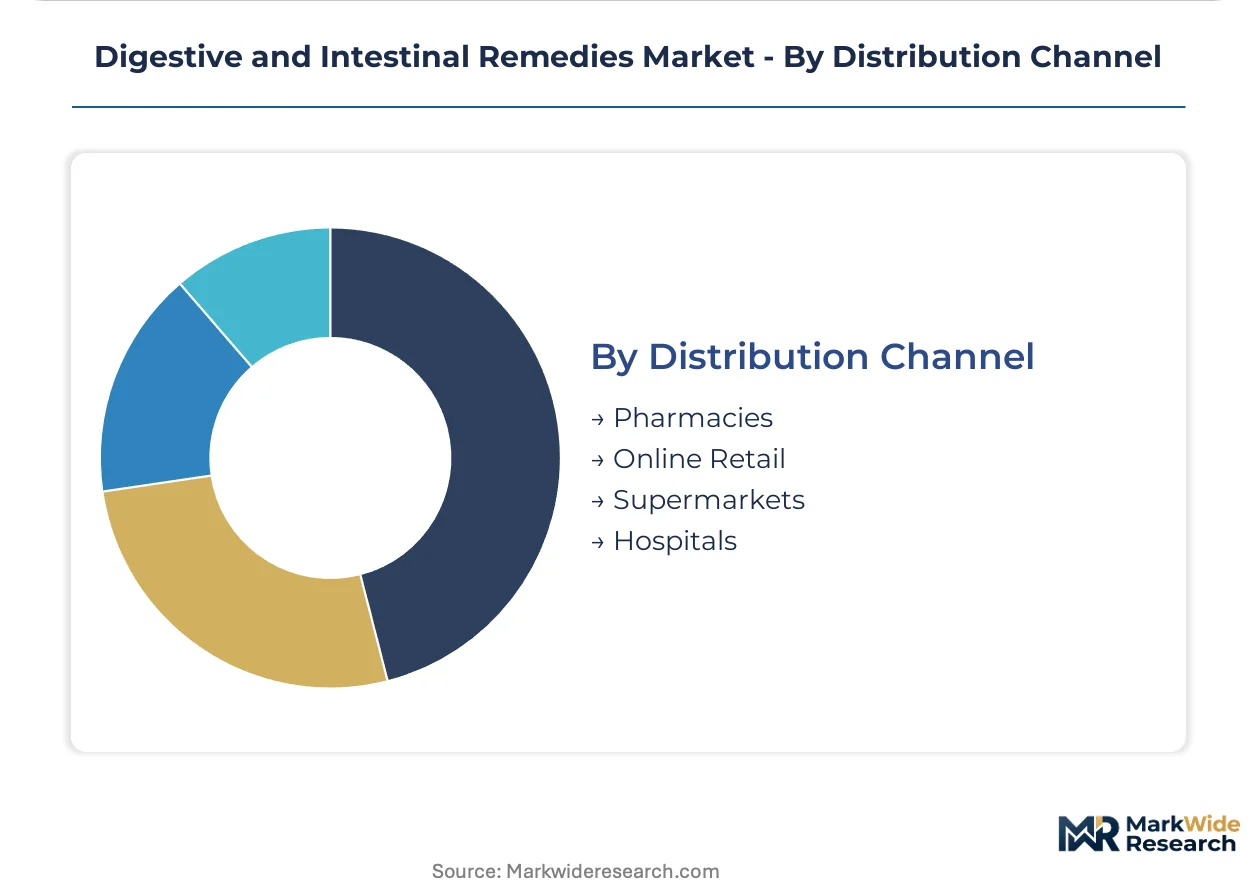
- Pharmacies:Professional counseling environments for condition-specific product selection. Germany and the Netherlands now stock ambient-stable probiotics previously restricted to health-food channels.
- Online Retail:Direct-to-consumer platforms enabling subscription auto-replenishment and microbiome test integration. United States employer benefits administrators treat these subscriptions as flexible spending account eligible.
- Supermarkets:Mass-market antacids and basic fiber supplements. Private-label penetration concentrates here, compressing branded margins.
- Hospitals:Institutional procurement for post-surgical enzyme replacement or acute diarrhea management. Formulary inclusion requires health-economic evidence packages.
Pharmacies lead by volume. Online Retail gains share fastest as personalized gut health platforms consolidate subscription relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Switzerland while consumption concentrates in the United States and Japan. This divergence creates trade dependencies in active pharmaceutical ingredients and finished formulations.
United States
Employer wellness programs and direct-to-consumer probiotic subscriptions drive recurring purchase behavior. FDA OTC monograph reform accelerates prescription-to-OTC switches for acid suppression therapies. Boston and Research Triangle Park host clinical trial infrastructure for microbiome-based therapeutic development.
Germany
Pharmacy chains expand private-label digestive health portfolios while room-temperature stable probiotic formulations enter conventional retail. EMA guidance on live biotherapeutic products shapes regional compliance pathways. Frankfurt and Munich anchor formulation manufacturing for cross-border European distribution.
Japan
Aging demographics sustain steady demand for gentle laxative and acid suppression therapies in aged-care facilities. PMDA oversight of functional food-drug boundary classifications determines marketing authorization pathways. Tokyo and Osaka concentrate probiotic strain development and fermentation manufacturing.
India
Domestic consumption rises for affordable antacid and enzyme formulations amid expanding pharmacy retail networks. CDSCO health claim substantiation requirements and BIS certification create dual compliance hurdles. Hyderabad and Ahmedabad host contract manufacturing clusters serving export markets.
Netherlands
Retail pharmacies stock ambient-stable probiotics previously restricted to refrigerated health-food channels, collapsing cold-chain distribution costs. REACH compliance obligations for novel excipients tighten formulation flexibility. Rotterdam and Eindhoven concentrate encapsulation technology development and contract manufacturing.
Digestive and Intestinal Remedies Market Key Industry Players
Capital-heavy producers compete with asset-light designers across formulation and branding dimensions. The market exhibits tiered concentration: global consumer health conglomerates dominate shelf space, mid-sized specialists capture premium probiotic niches, and private-label manufacturers erode margin pools in commoditized antacids. Strategic archetypes include integrated pharmaceutical-to-consumer health converters, microbiome-focused biotechnology platforms, and retail-captive sourcing operations. Competitive moves center on prescription-to-OTC transition capabilities and subscription-based recurring revenue models.
Among diversified consumer health conglomerates, Bayer AG and Sanofi occupy positions spanning pharmacy shelf presence and regulatory transition expertise. Takeda Pharmaceutical Company Limited anchors the Asia-Pacific vector through acid-related disorder specialization. These three exemplify distinct strategic postures: infrastructure-led geographic coverage, prescription-to-OTC conversion capability, and regional therapeutic depth.
| Leading Market Players |
|---|
| Procter & Gamble |
| Boehringer Ingelheim GmbH |
| Bayer AG |
| Abbott |
| Reckitt Benckiser Group PLC |
| Johnson & Johnson Services Inc. |
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| GSK plc |
| Others |
Cost & Logistics Intelligence
Encapsulation chemistry specialists in the Netherlands and Germany command wage premiums that propagate into three-tier pricing spreads separating premium alginate-matrix probiotics from standard freeze-dried formulations and economy bulk powders. Labor-cost differentials between Swiss contract manufacturers and Indian bulk suppliers drive tiered margin structures that branded players exploit through geographic sourcing arbitrage.
Pricing Analysis
Margin tightening in antacids traces to CVS Health and Walgreens Boots Alliance private-label shelf-space dominance, which erodes branded pricing power through captive sourcing programs. Three-tier pricing structure across premium, standard, and economy levels stratifies by gastric survivability certification and cold-chain independence, with room-temperature stable formulations commanding 40-60% premiums over refrigerated alternatives. Cost-down pressure on economy laxatives accelerates because Indian contract manufacturers compete on volume scale rather than formulation innovation. Institutional buyers in aged-care facilities show lowest price sensitivity due to formulary stickiness, while supermarket consumers exhibit highest elasticity, switching to private-label within single percentage-point price differentials.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for pharmaceutical manufacturing reshape API sourcing away from concentrated Chinese suppliers toward Hyderabad and Ahmedabad fermentation clusters. Finished formulation supply concentrates in Germany, Switzerland, and Japan, drawing from Indian and Chinese bulk probiotic cultures, aluminum hydroxide precursors, and specialized alginate excipients. Single-source vulnerability in live-culture strain banks creates systemic risk should contamination events propagate through master cell repositories. Distribution runs through pharmacy chains in developed markets and expanding retail networks in India, with direct-to-consumer platforms capturing subscription replenishment relationships in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity in clinical-grade probiotic manufacturing props pricing premiums across the analysis window, constraining volume expansion for microbiome-based entrants lacking validated production partnerships.
For Market Incumbents: Anchor shelf presence through exclusive pharmacy chain partnerships that block private-label substitution in antacids, while backward integration into alginate encapsulation technology defends margin pools against commoditization. Bayer AG and Sanofi should prioritize cold-chain-independent formulation investments that collapse distribution costs and enable retail placement expansion. Regulatory transition capabilities for prescription-to-OTC switches remain the critical lever for volume capture in acid suppression therapies. For New Entrants and Emerging Players: Room-temperature stable probiotic delivery platforms offer a technology-first wedge against incumbent refrigerated infrastructure. Target employer wellness program procurement channels in the United States, where benefits administrators seek preventive digestive health subscriptions as FSA-eligible cost-containment measures. Direct-to-consumer microbiome testing integration creates upstream data capture that funnels consumers into personalized replenishment protocols with higher lifetime value than transactional pharmacy purchases. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with validated live-culture manufacturing and EMA live biotherapeutic product pathway progress. Long-term viability hinges on regulatory moats in microbiome-based claims rather than formulation novelty alone. Watch FDA OTC monograph reform acceleration as the inflection signal for prescription-to-OTC transition arbitrage opportunities in acid suppression categories.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Transition | FDA monograph reform unlocks pharmacy shelf expansion beyond physician-mediated access barriers. |
| Live-Culture Stabilization Investment | Alginate encapsulation patents collapse cold-chain dependency and enable ambient retail distribution. |
| Employer Wellness Program Partnership | Institutional procurement channels in the United States convert episodic purchases into recurring revenue. |
| Direct-to-Consumer Microbiome Platform | At-home diagnostics create data-driven subscription funnels with higher retention than traditional retail. |
| Regulatory Pathway Harmonization | EMA live biotherapeutic guidance reduces cross-border launch fragmentation for microbiome therapeutics. |
Research Approach
Document review covered FDA OTC monograph filings, EMA live biotherapeutic product guidance, and ClinicalTrials.gov microbiome study registrations, complemented by interviews with regulatory affairs leads at consumer health conglomerates, pharmacy chain category buyers, and employer benefits administrators. Secondary validation drew from formulary databases, Nielsen retail audit data, and customs records of probiotic culture imports. Bottom-up demand modeling triangulated against top-down market sizing from pharmaceutical trade associations.
Segmentation outputs across product type, application, end user, and distribution channel were projected over the analysis window using patient population demographics, regulatory transition timelines, and employer wellness program penetration curves. CAGRs were derived from fitted growth curves incorporating live-culture stabilization technology adoption rates and prescription-to-OTC switch probability assessments. Forecast inputs included aging demographic trajectories in Japan and Germany, and CDSCO registration delay distributions for probiotic health claims in India.
Several conditions sit outside the modeled scope, including unforeseen FDA monograph reform reversals, probiotic strain-specific safety events triggering regulatory reclassification, and macroeconomic shocks to employer wellness program budgets. Forecasts reflect documented assumptions about technology diffusion rates and regulatory pathway stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotics Market
Probiotic Supplements
South America Probiotics Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
Single-Strain Probiotics Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
Brazil Probiotics Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Psychobiotic Supplements Market
Probiotic Supplements
Shelf Stable Probiotics Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Global Probiotic Based Dietary Supplements Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Digestion Aids Market