
 Europe BBQ Charcoal Market | 2026-2036
Europe BBQ Charcoal Market Size, Share, and Industry Trends Forecast 2026-2036
Europe BBQ Charcoal Market Insights
Modular packaging formats is pivoting buyer choice across Europe, with retailers now bundling starter kits that combine charcoal, firelighters, and disposable grills into single SKUs. Profagus leverages its Polish production base to supply private-label modular sets across Central European discounters. Gryfskand anchors Nordic market share through specialized birch charcoal packaged in weather-resistant tubs for year-round outdoor cooking.
Europe BBQ charcoal comprises carbonized biomass—primarily hardwood, softwood, or coconut shell—processed through pyrolysis in kilns or retorts to achieve fixed carbon content above 75 percent and moisture below 8 percent, serving residential and commercial grilling applications where controlled heat release and minimal ash residue define performance. Briquettes dominate volume through standardized burn profiles that appeal to casual household grillers, while lump charcoal commands margin pools among enthusiast segments seeking unadulterated wood flavor. Binchotan, though niche, is accelerating within premium restaurant channels across France and the Netherlands as chefs adopt Japanese-style yakitori configurations.
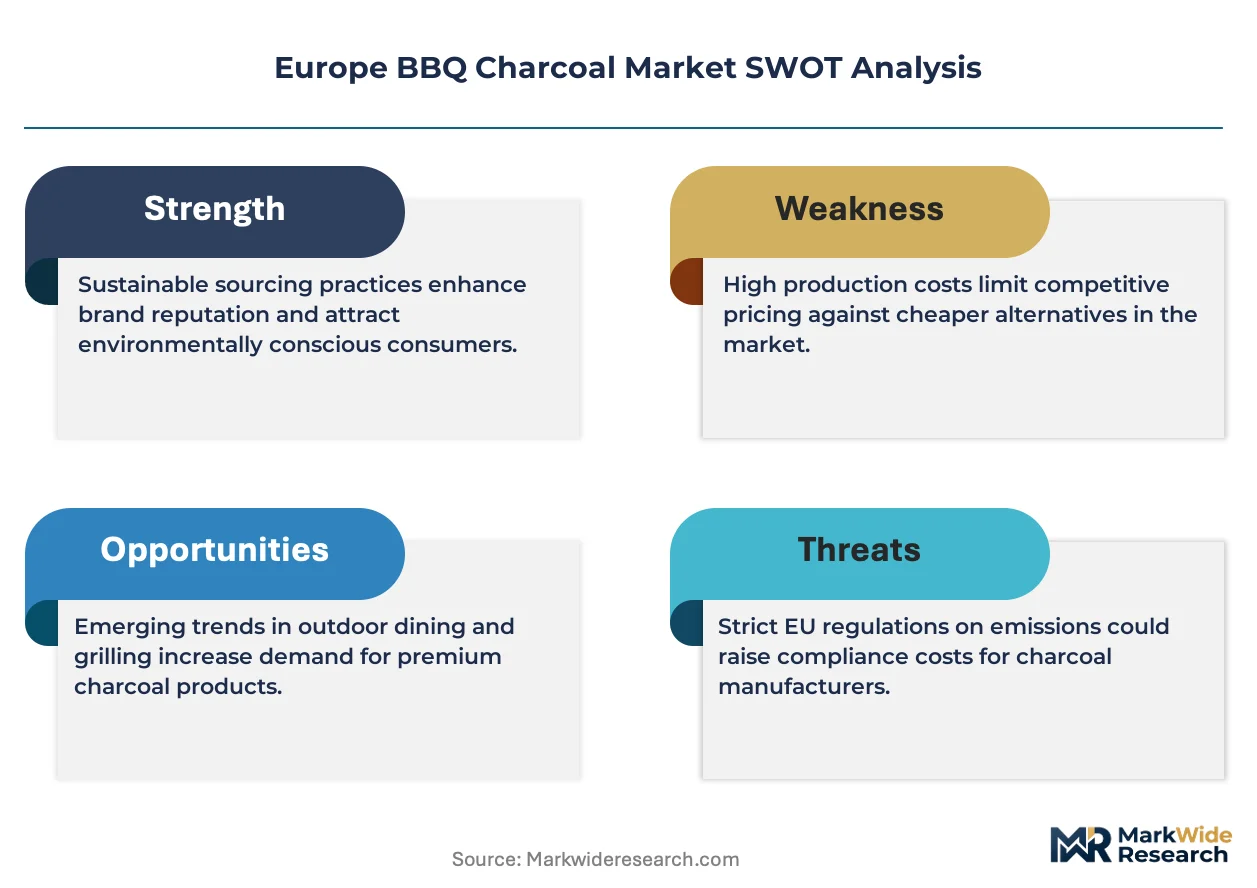
EMA, ECHA, and the EU Green Deal collectively shape product standards, with REACH restricting chemical additives in ignition aids and the EU Green Deal pressuring manufacturers toward certified sustainable sourcing and lower-carbon kiln technologies. National regulators in Germany and Poland enforce additional emissions testing for charcoal-fired appliances sold through retail channels. Stakeholders must monitor evolving sustainability certification requirements and kiln efficiency mandates that will determine which suppliers retain shelf access across European retail networks.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing permissible emissions thresholds for solid fuel combustion appliances, forcing kiln operators across Poland, Germany, and Ukraine to retrofit carbon capture systems or face retail delisting by 2030.
Growth Catalysts
- REACH-compliant ignition aids:Reformulated firelighter chemistries meeting ECHA substance restrictions now unlock shelf placement in French and Dutch hypermarkets previously closed to conventional kerosene-based products.
- Festival catering procurement:German Oktoberfest-scale events and Nordic midsummer celebrations are institutionalizing bulk charcoal contracts with fixed seasonal delivery windows.
- Coconut shell pyrolysis:Southeast Asian biomass feedstock integration into European retort operations is diversifying supply beyond hardwood dependence.
Market Restraints
- Hardwood input cost volatility:Polish and Ukrainian oak and beech log prices fluctuate with construction sector competition for timber, squeezing margin predictability for kiln operators.
- Supply concentration risk:Premium birch charcoal for Nordic markets concentrates in Belarusian and Russian-origin feedstock now subject to EU sanctions and customs complexity.
- Electric grill substitution:Urban balcony regulations in Paris, Berlin, and Amsterdam increasingly prohibit open-flame cooking, redirecting apartment dwellers toward induction and infrared alternatives.
Strategic Opportunities
- Portuguese and Spanish underpenetration:Iberian per-capita charcoal consumption trails Northern Europe by 40 percent, presenting white space for weather-resistant packaging formats suited to Mediterranean climates.
- Restaurant yakitori configuration:Binchotan adoption in French and Dutch premium dining creates demand for certified sustainable white charcoal with documented fixed carbon above 90 percent.
- CSRD-aligned sustainability certification:Corporate Sustainability Reporting Directive scope expansion pressures foodservice procurement departments to document supply chain deforestation-free status.
Industry Challenges
- Retort engineering skill scarcity:Kiln automation and emissions control system operation require technicians trained in pyrolysis thermodynamics, a competency pool concentrated in aging Polish and German workforces.
- FSC-PEFC dual certification timelines:Forest stewardship documentation for imported coconut shell feedstock extends supplier onboarding by 8-14 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe BBQ Charcoal Market |
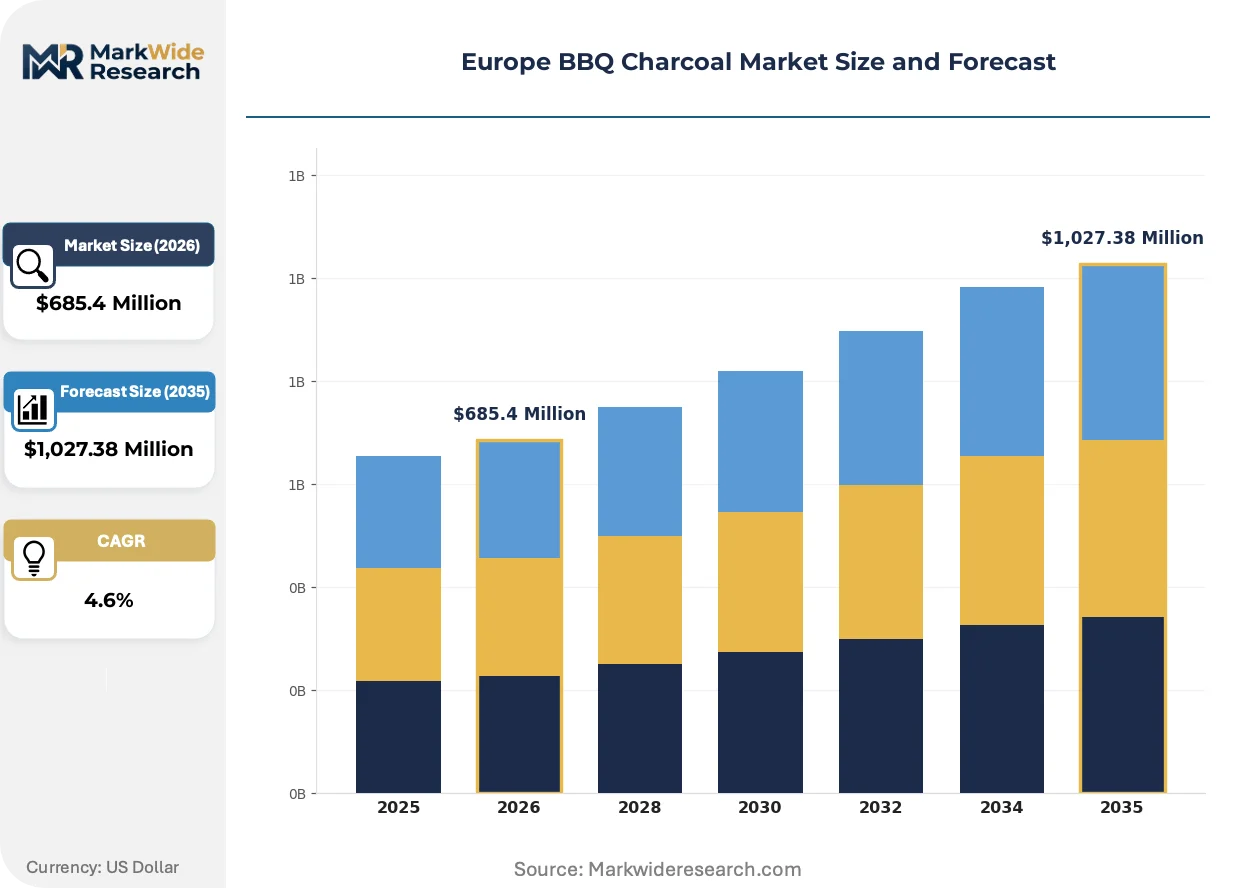
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Charcoal, Briquettes, Lump Charcoal, Binchotan End User: Households, Restaurants, Catering Services, Outdoor Events Material: Wood, Coconut Shell, Compressed Sawdust, Charcoal Dust Packaging Type: Bags, Boxes, Bulk Containers, Tubs |
| Companies Covered | Profagus, Bauer Biobrennstoffe, Grande Charcoal, Bbq & Outdoor Co., A.H. Meyer & Cie AG, CARBO Holding Sp. z o.o., CroGrill, Gryfskand, Drusedau SP. Z O.O, Marienburg Charcoal Factory, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe BBQ Charcoal Market Trends and Innovations
Kiln technology and combustion appliance design are converging to satisfy tightening EU emissions benchmarks while preserving the sensory performance characteristics that define grilling culture across the continent.
Retort kilns with staged combustion and syngas recirculation are overtaking traditional mound and brick kiln operations in Polish and Ukrainian production basins. These systems achieve fixed carbon yields above 82 percent while capturing volatile organic compounds for energy recovery. German and Austrian equipment suppliers are retrofitting existing facilities under EU Green Deal transition financing. The technology is compressing allowable operating margins for non-compliant competitors.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in ignition aids are compelling reformulation of firelighter products across European retail channels. ECHA enforcement actions in 2023-2024 delisted multiple non-compliant suppliers from major French and Belgian distributors. Briquette manufacturers integrating compliant ignition systems are securing preferred supplier status with supermarket private-label programs.
Modular starter kits bundling charcoal, firelighters, and disposable grills are displacing standalone product purchases in Central European discounters. Polish and Romanian consumers increasingly favor single-SKU solutions for impulse outdoor cooking occasions. This pattern concentrates procurement power with retailers capable of designing and sourcing integrated sets, marginally commoditizing pure charcoal suppliers.
Europe BBQ Charcoal Market Segmentation
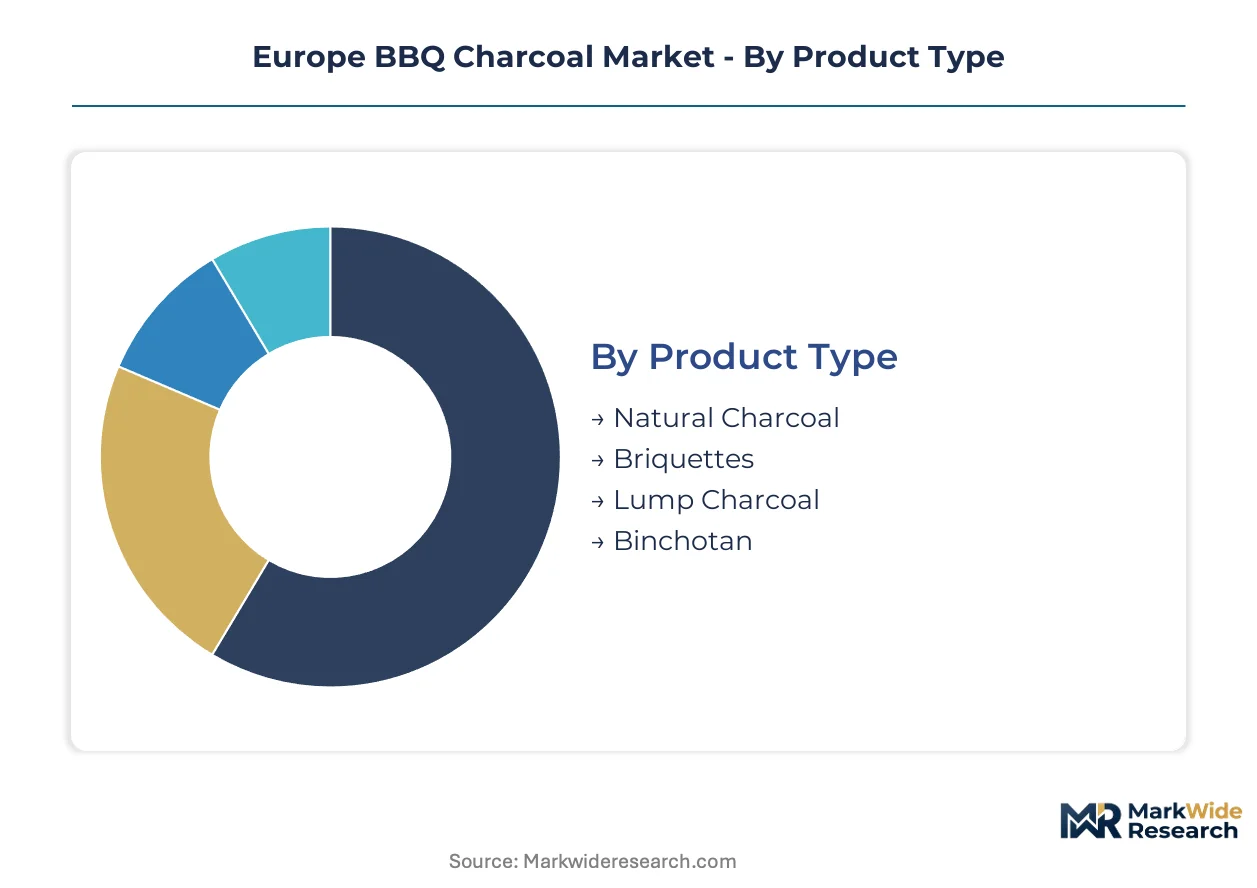
Europe BBQ Charcoal Market segmentation reveals divergent capital requirements across production technologies and distribution formats. Kiln configuration, feedstock sourcing, and packaging automation each demand distinct upfront investment profiles that shape supplier positioning.
Product Type:
Briquette production commands the heaviest capital burden through binder formulation systems, compression molding lines, and controlled drying infrastructure.
- Briquettes:Compressed charcoal fines bound with starch or mineral additives achieve uniform density and predictable burn duration. German and Polish households favor these for casual weekend grilling, though REACH-compliant binder chemistries add formulation complexity and certification cost.
- Lump Charcoal:Irregular chunks from direct wood pyrolysis retain native lignin structures that purists associate with authentic smoke flavor. French and Dutch enthusiast segments pay premium prices for hardwood-origin lump with documented forest provenance.
- Natural Charcoal:Unprocessed carbonized biomass sold without compression or additive treatment. Mediterranean markets accept higher moisture content in exchange for lower unit pricing.
- Binchotan:Japanese-style white charcoal produced from dense hardwood at extreme temperatures yielding fixed carbon above 90 percent. Paris and Amsterdam restaurant channels drive niche demand for yakitori-grade material with minimal volatile emissions.
Briquettes absorb the bulk of installed capacity; Binchotan is expanding most quickly.
End User:
Commercial procurement patterns segment by order predictability and volume scale rather than capital intensity alone.
- Households:Impulse-driven purchases through supermarket and DIY channels favor modular starter kits combining fuel, ignition, and disposable hardware. Polish and Romanian discounters now dominate this volume through private-label consolidation.
- Restaurants:Premium dining establishments in France and the Netherlands specify certified sustainable grades with batch-traceable origin documentation. CSRD-aligned procurement mandates are hardening documentation requirements.
- Catering Services:Seasonal bulk contracts for German Oktoberfest and Nordic midsummer events institutionalize forward purchasing with fixed delivery windows.
- Outdoor Events:Festival operators negotiate spot-market supply for temporary infrastructure where storage constraints preclude inventory buildup.
Households dominate absolute volume; Restaurants command the steepest expansion trajectory as sustainability certification becomes a procurement gate.
Material:
Feedstock selection determines kiln retrofit requirements and emissions compliance exposure under EU Green Deal timelines.
- Wood:Hardwood from Polish and Ukrainian oak and beech forests remains the baseline feedstock for traditional lump production. Construction sector competition for timber creates input cost volatility.
- Coconut Shell:Southeast Asian biomass integrates into European retort operations as hardwood alternatives. FSC-PEFC dual certification for imported shell extends supplier onboarding timelines significantly.
- Compressed Sawdust:Residual material from furniture and construction milling processed into uniform briquette feedstock. Sawdust moisture variability requires pre-drying investment.
- Charcoal Dust:Fines and fragments recovered from screening operations, reprocessed through briquetting to minimize waste. Dust handling systems demand explosion-proof capital expenditure.
Wood retains the deepest supply base; Coconut Shell is climbing the fastest as sanctions complicate Eastern European hardwood flows.
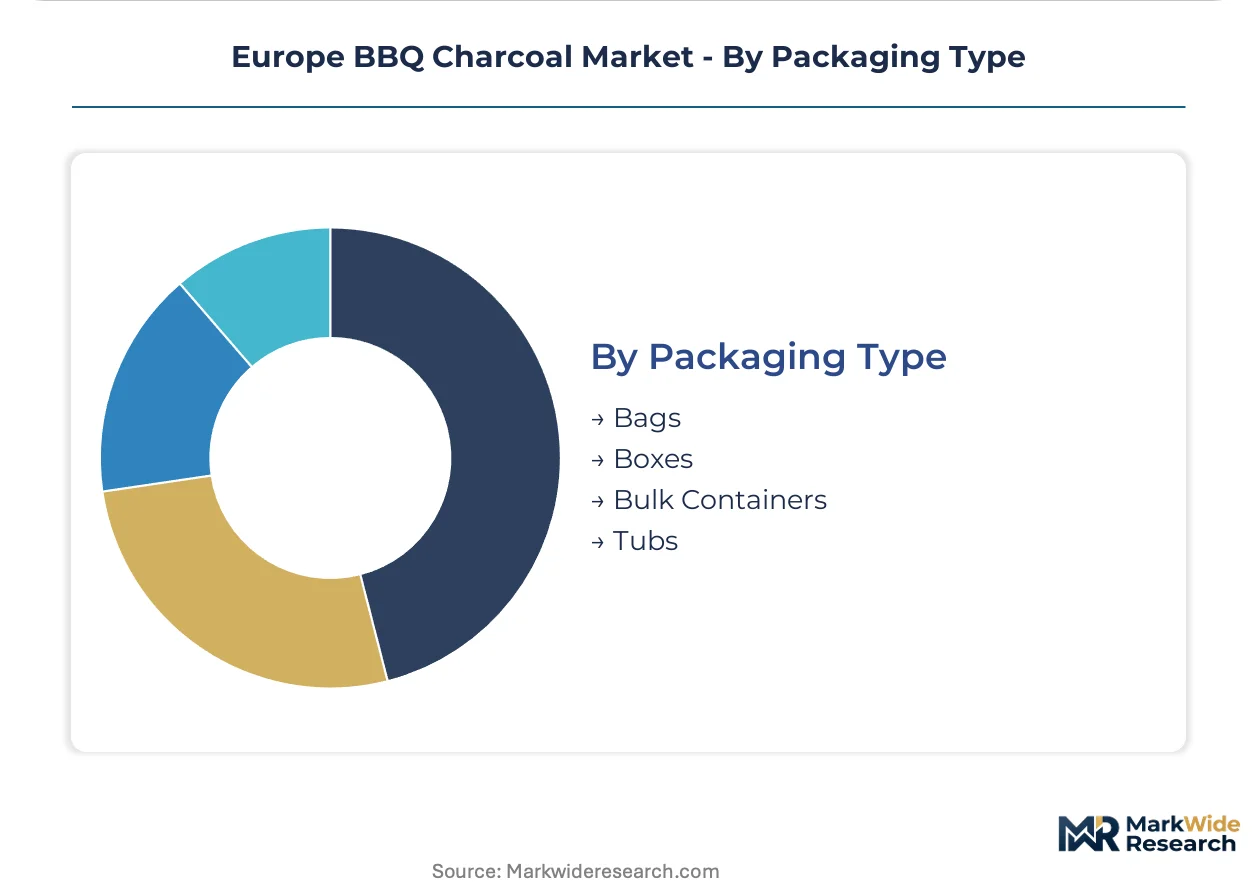
Packaging Type:
Format selection reflects climate exposure, retail channel requirements, and logistics optimization across Nordic and Mediterranean extremes.
- Bags:Paper and woven polypropylene remain standard for mass-market distribution. German retailers now specify recycled-content thresholds.
- Boxes:Rigid cardboard protects premium lump grades during handling and displays origin certification prominently. French hypermarkets favor shelf-ready box formats.
- Bulk Containers:Industrial totes and palletized loose fill serve catering and event operators with dedicated storage infrastructure. Nordic festival procurement runs primarily through bulk channels.
- Tubs:Weather-resistant plastic tubs with resealable lids enable year-round outdoor storage in maritime climates. Gryfskand anchors Nordic share through specialized birch charcoal in tub formats.
Bags carry the highest shipment volume; Tubs are gaining share fastest as all-weather cooking extends the seasonal window.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Poland and Ukraine while consumption gravitates toward Germany, France, and the Nordics. This geographic split creates freight-dependent margin structures and customs-complex supply chains.
Germany
Backyard grilling culture and Oktoberfest-scale festival procurement sustain the continent's largest absolute demand. The KBA enforces emissions testing for charcoal-fired appliances sold through retail channels. Berlin and Munich anchor distribution networks where modular starter kits now dominate supermarket shelves.
Poland
Hardwood feedstock abundance and retort kiln expertise position the country as Europe's primary production base. EU Green Deal transition financing supports carbon capture retrofits across Silesian and Mazovian facilities. Profagus leverages its Polish operations to supply private-label modular sets across Central European discounters.
France
Premium restaurant adoption of Binchotan for yakitori configurations drives niche demand growth in Paris and Lyon. REACH Annex XVII enforcement actions by ANSM delisted non-compliant ignition aid suppliers from major hypermarkets. Île-de-France and Provence-Alpes-Côte d'Azur concentrate high-end procurement with CSRD-aligned documentation requirements.
Netherlands
Urban balcony regulations in Amsterdam increasingly prohibit open-flame cooking, redirecting apartment dwellers toward electric alternatives. ECHA substance restrictions shape firelighter formulation standards across Dutch retail channels. Rotterdam serves as the primary import hub for Southeast Asian coconut shell feedstock entering European retort operations.
Sweden
Midsummer celebration traditions institutionalize seasonal bulk procurement with fixed delivery windows. Maritime climate exposure sustains demand for weather-resistant tub packaging formats enabling year-round outdoor storage. Gryfskand anchors Nordic market share through specialized birch charcoal packaged for Scandinavian conditions.
Europe BBQ Charcoal Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around production-scale kilns in Eastern Europe, premium-grade specialization for restaurant channels, and private-label consolidation for Central European retail. Three archetypes dominate: integrated hardwood processors, coconut shell importers with retort automation, and sustainability-certified niche suppliers. Capacity expansion and REACH-compliant product reformulation represent the primary competitive moves reshaping shelf access.
Among Polish production specialists, Profagus, CARBO Holding Sp. z o.o., and Gryfskand occupy distinct positioning vectors. Profagus exemplifies the private-label modular set supplier archetype serving discounter consolidation trends. CARBO Holding Sp. z o.o. represents the integrated hardwood processor model with captive feedstock access. Gryfskand anchors the weather-resistant packaging specialist tier targeting Nordic climate conditions.
| Leading Market Players |
|---|
| Profagus |
| Bauer Biobrennstoffe |
| Grande Charcoal, Bbq & Outdoor Co. |
| A.H. Meyer & Cie AG |
| CARBO Holding Sp. z o.o. |
| CroGrill |
| Gryfskand |
| Drusedau SP. Z O.O |
| Marienburg Charcoal Factory |
| Others |
Pricing and Supply Chain Analysis
Discounter procurement consolidation across Central Europe favors contract-based long-term offtake pricing with volume-scaled rebates. German and Polish retailers now bundle charcoal into modular starter kits, compressing standalone product margins and shifting pricing power toward retail private-label programs.
Pricing Analysis
Margin tightening in economy-tier briquettes reflects hardwood input cost volatility from Polish and Ukrainian timber markets competing with construction demand. Three-tier pricing structure across premium, standard, and economy levels separates FSC-PEFC certified lump from REACH-compliant briquettes and unbranded natural charcoal. Pricing pressure stems from electric grill substitution in urban balcony-restricted markets. Household segments through Central European discounters exhibit highest price sensitivity; Paris and Amsterdam restaurants purchasing yakitori-grade Binchotan show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German festival operators and French restaurant procurement departments mandate qualified suppliers across Polish, Ukrainian, and Portuguese production bases. Feedstock draws from oak and beech hardwood forests, Southeast Asian coconut shell imports, and compressed sawdust residuals. Supply chain risk centers on Belarusian and Russian-origin birch feedstock now subject to EU sanctions complexity. Distribution runs through Rotterdam import hubs for coconut shell, Silesian kiln clusters for hardwood processing, and Nordic bulk container channels for festival logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort kiln technology with staged combustion and syngas recirculation is displacing traditional mound operations, forcing capital reallocation across the supplier base.
For Market Incumbents: Cement shelf access through REACH-compliant firelighter integration and carbon capture retrofit certification before EU Green Deal retail delisting deadlines. Polish producers with captive hardwood feedstock should deepen backward integration into FSC-PEFC forest management to defend margin position against coconut shell importers. Retort engineering skill scarcity in aging German and Polish workforces threatens operational continuity. For New Entrants and Emerging Players: The price-point gap between premium Binchotan and economy briquettes offers entry space for mid-tier certified sustainable lump targeting Iberian underpenetration. Portuguese and Spanish markets trail Northern European per-capita consumption by substantial margins. Weather-resistant tub packaging formats suited to Mediterranean climates provide a differentiated go-to-market angle against bag-dominant incumbents. For Investors and Strategic Acquirers: The window for entry favors coconut shell importers with retort automation capabilities and dual FSC-PEFC certification infrastructure. Long-term viability hinges on deforestation-free supply chain documentation aligning with CSRD-aligned procurement mandates. Watch for ECHA enforcement actions delisting non-compliant ignition aid suppliers as an inflection signal for consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Kiln Retrofit with Carbon Capture | EU Green Deal transition financing supports Polish and Ukrainian facility upgrades. |
| REACH-Compliant Firelighter Reformulation | ECHA enforcement actions in France and Belgium delisted conventional kerosene-based suppliers. |
| FSC-PEFC Dual Certification Investment | CSRD-aligned procurement mandates harden documentation requirements for restaurant channels. |
| Weather-Resistant Tub Packaging Launch | Gryfskand's Nordic market share demonstrates maritime climate storage demand. |
| Coconut Shell Feedstock Integration | Rotterdam import hubs enable Southeast Asian biomass diversification beyond hardwood dependence. |
Research Methodology
Document review covered ECHA substance restriction databases, EU Green Deal policy frameworks, and FSC-PEFC certification registries, complemented by interviews with retort kiln operators, hypermarket category buyers, restaurant procurement managers, and festival logistics coordinators. Secondary validation drew from customs trade data on coconut shell imports, KBA emissions testing protocols, and SEC filings from diversified conglomerates with charcoal operations. Bottom-up production capacity modeling and top-down consumption survey triangulation anchored volume estimates.
Segment-level projections across product type, end user, material, and packaging format dimensions were generated through the analytical framework. CAGRs were derived from elasticity-adjusted demand curves incorporating urban balcony regulation diffusion rates and CSRD procurement mandate adoption curves. Feedstock cost indices for Polish oak and beech, alongside Rotterdam coconut shell landed prices, served as key forecast inputs across the projection horizon.
Inputs from ECHA enforcement action records and EU Green Deal implementation timelines were available through the study window; gaps in real-time kiln retrofit completion rates introduce uncertainty bands around compliance-driven capacity assumptions. Deviation in Belarusian birch feedstock sanction relief or accelerated electric grill substitution in German urban centers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Lupine Peptides Market
Ingredients
Marine Ingredients Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Industrial Sugar Market
Ingredients
India Protein Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Ice Cream Ingredients Market
Ingredients
US Ingredients Market
Ingredients
United States Wheat Protein Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Dry Molasses Products Market
Ingredients
Sweet Almond Oil Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Egg Free Premix Market
Ingredients
Soybean Oil Market