
 Health and Wellness Foods Market | 2026-2036
Health and Wellness Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Health and Wellness Foods Market Intelligence
Clean label formulation is collapsing the distinction between conventional and specialty food categories, pushing manufacturers toward simpler, more transparent ingredient lists. Danone S.A. leverages its deep expertise in probiotic foods and plant-based alternatives to meet this shift in consumer preference. Meanwhile, Nestlé S.A. competes across a vast portfolio of nutritional supplements and fortified food products, utilizing its global distribution network to maintain market presence. General Mills expands its offerings in the organic and natural foods space.
Health and wellness foods are commercially prepared products formulated to provide health benefits beyond basic nutrition. These items often feature fortification with specific bioactive components like plant-based proteins, vitamins, or omega-3 fatty acids. Their primary purpose is to help consumers manage health proactively, address dietary deficiencies, or achieve specific lifestyle goals. Functional beverages and protein bars represent major product categories, valued for their convenience. Concurrently, ingredient innovations centered on fiber and antioxidants are creating new avenues for product differentiation and margin expansion.
The regulatory environment is defined by stringent oversight from multiple agencies. The US FDA enforces strict rules on nutrient content claims and health claims, while the European Food Safety Authority (EFSA) requires rigorous scientific substantiation for any advertised health benefit. In China, the State Administration for Market Regulation (SAMR) governs food safety and registration protocols. Future competitive positioning will depend on a company's ability to validate product efficacy through clinical data and communicate these benefits transparently.
Market Dynamics
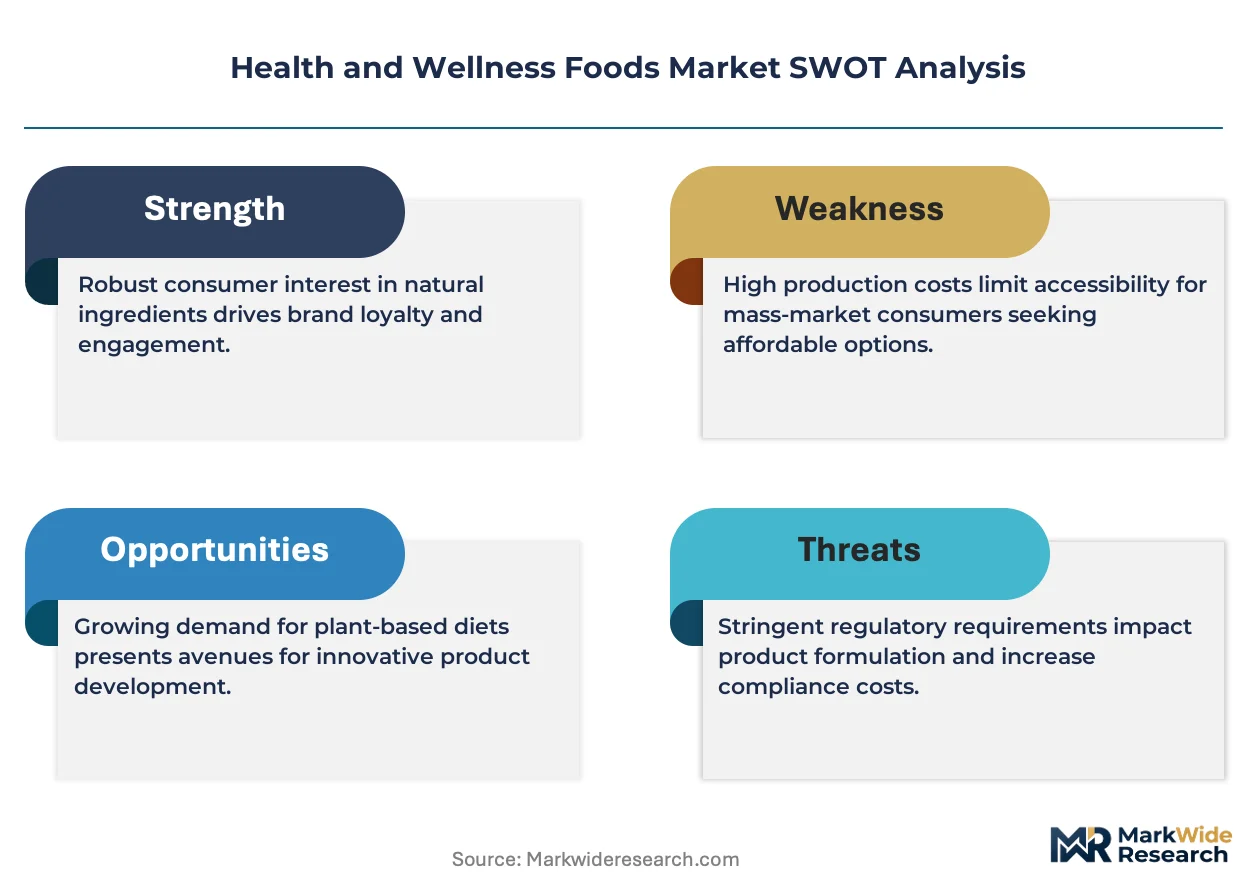
The market's central dynamic is the tension between consumer demand for simple, natural ingredients and the scientific and regulatory requirement for clinical validation of health benefits. This polarity forces manufacturers to balance clean-label marketing with rigorous, data-backed efficacy claims.
Growth Catalysts
- EU Labeling Mandates:The European Union's Green Deal and its associated nutritional labeling requirements compel manufacturers to reformulate products with greater transparency, creating a clear market for verifiably healthy options targeting the region.
- Chinese Middle-Class Demand:An expanding and health-conscious middle class in China exhibits strong preferences for fortified foods, functional beverages, and infant nutrition products, creating a concentrated geographic demand center.
- Ingredient Science:Advances in food science, particularly around plant-based proteins, fermentation for probiotics, and the isolation of bioactive compounds like antioxidants, provide new pathways for product development and differentiation.
Market Restraints
- High Input Costs:The sourcing of specialized, high-purity ingredients such as clinically studied probiotic strains, omega-3 fatty acids, or certified organic botanicals creates significant cost pressures that are difficult to pass on to consumers.
- Regulatory Scrutiny:Rigorous pre-market approval processes and the high burden of proof required by agencies like the EFSA for health claims can delay product launches and increase development costs substantially.
- Complex Supply Chains:Ensuring the traceability, purity, and authenticity of ingredients from a global supplier base presents significant logistical and quality control hurdles, especially for products with organic or non-GMO claims.
Strategic Opportunities
- Personalized Nutrition Platforms:The integration of diagnostic tools, such as biomarker or genetic testing, with food delivery creates an opportunity for highly customized subscription services that cater to individual health needs and goals.
- Underserved Geographies:Markets in Southeast Asia and Latin America, where consumer awareness of proactive health management is rising, represent significant white space for expansion beyond the more saturated markets of North America and Europe.
- Mental Wellness Foods:There is a nascent but growing opportunity in developing functional foods and beverages formulated with adaptogens, nootropics, and other ingredients specifically targeting cognitive function, stress reduction, and mood support.
Industry Challenges
- Cross-Border Regulatory Harmonization:Companies face the operational challenge of reformulating and relabeling products to comply with disparate and often conflicting regulations on health claims and ingredient safety between the US, EU, and China.
- Clinical Validation Expense:The high cost and long timelines associated with conducting human clinical trials to substantiate health benefits for food products create a significant barrier to entry for smaller innovators.
- Communicating Scientific Benefits:Effectively educating consumers on the complex mechanisms of action behind functional ingredients without making unsubstantiated or illegal health claims is a persistent marketing and compliance challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health and Wellness Foods Market |
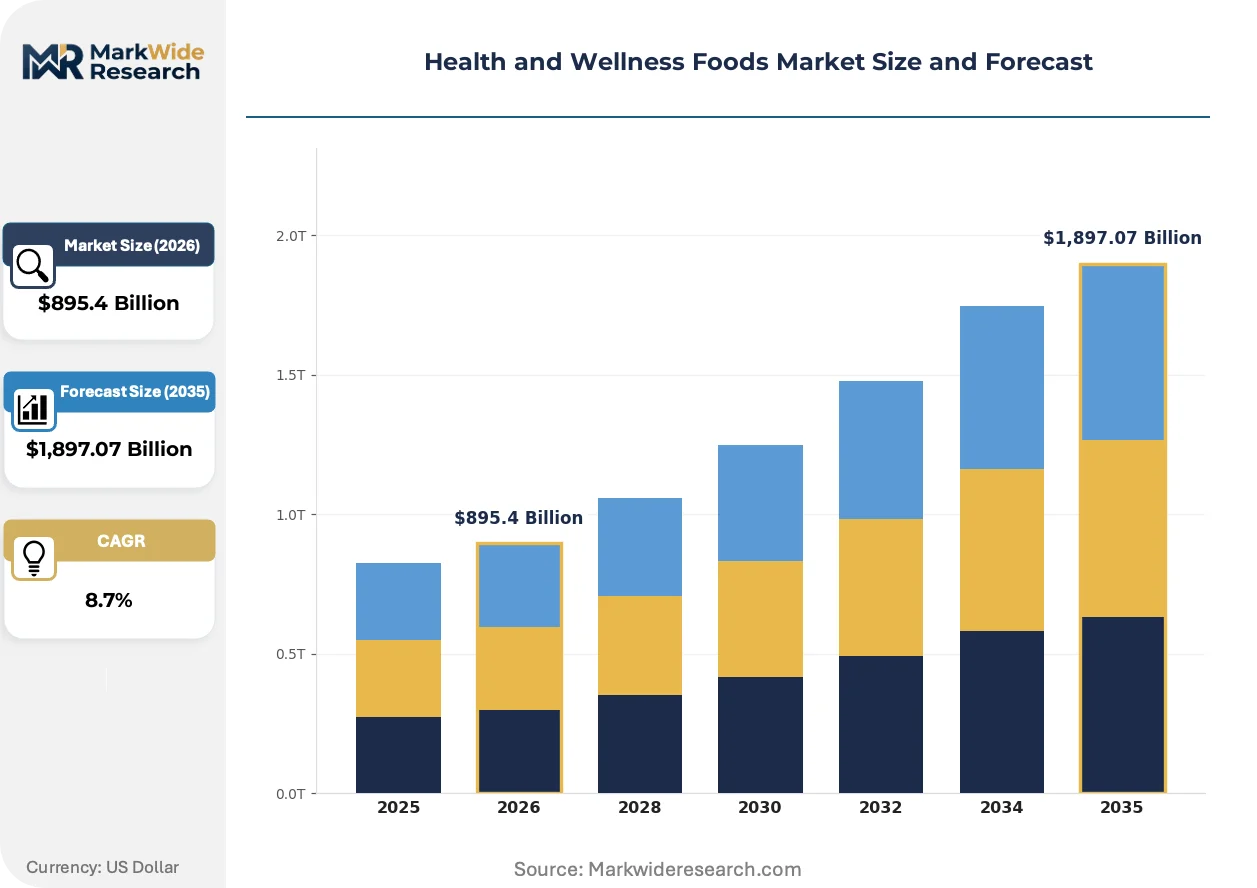
| Market Size in 2026 | $895.4 Billion |
| Market Size in 2035 | $1,897.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Beverages, Nutritional Supplements, Herbal Products, Protein Bars, Probiotic Foods Ingredient Composition: Plant-Based Proteins, Vitamins & Minerals, Omega-3 Fatty Acids, Fiber, Antioxidants Consumer Age Group: Children, Adults, Seniors, Athletes, Pregnant Women Distribution Channel: Specialty Stores, Online Retailers, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | Unilever PLC, Conagra Brands, Nestlé S.A., Herbalife Nutrition Ltd., The Hain Celestial Group, Danone S.A., General Mills, United Natural Foods, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health and Wellness Foods Market Strategic Shifts & Innovations
Product development is pivoting from generalized wellness to targeted health interventions. This shift is driven by the convergence of food science, biotechnology, and data analytics, enabling formulations that address specific physiological needs with greater precision and verifiable efficacy.
Micro-encapsulation technology protects sensitive bioactive compounds like probiotics and vitamins from degradation during processing and digestion. Functional food and beverage producers are rapidly adopting this method to improve product stability and bioavailability. This technology is miniaturizing the delivery system for active ingredients, enabling the creation of more potent and convenient formats like concentrated powders and wellness shots.
The US FDA's stringent enforcement of rules governing nutrient content claims and health claims shapes product marketing. This regulatory posture requires manufacturers to secure robust scientific evidence before advertising any specific health benefit. The functional beverage and dietary supplement categories are most impacted, often leading to more conservative labeling and a focus on "structure/function" claims over disease-prevention statements.
A notable behavioral change involves consumers moving from ad-hoc retail purchases toward curated subscription models for their wellness needs. This trend disrupts the traditional grocery and specialty health store channels by creating a direct-to-consumer relationship. This subscription-based procurement is most visible in major metropolitan areas across North America and Western Europe, where logistics infrastructure supports efficient home delivery.
Health and Wellness Foods Market Segmentation
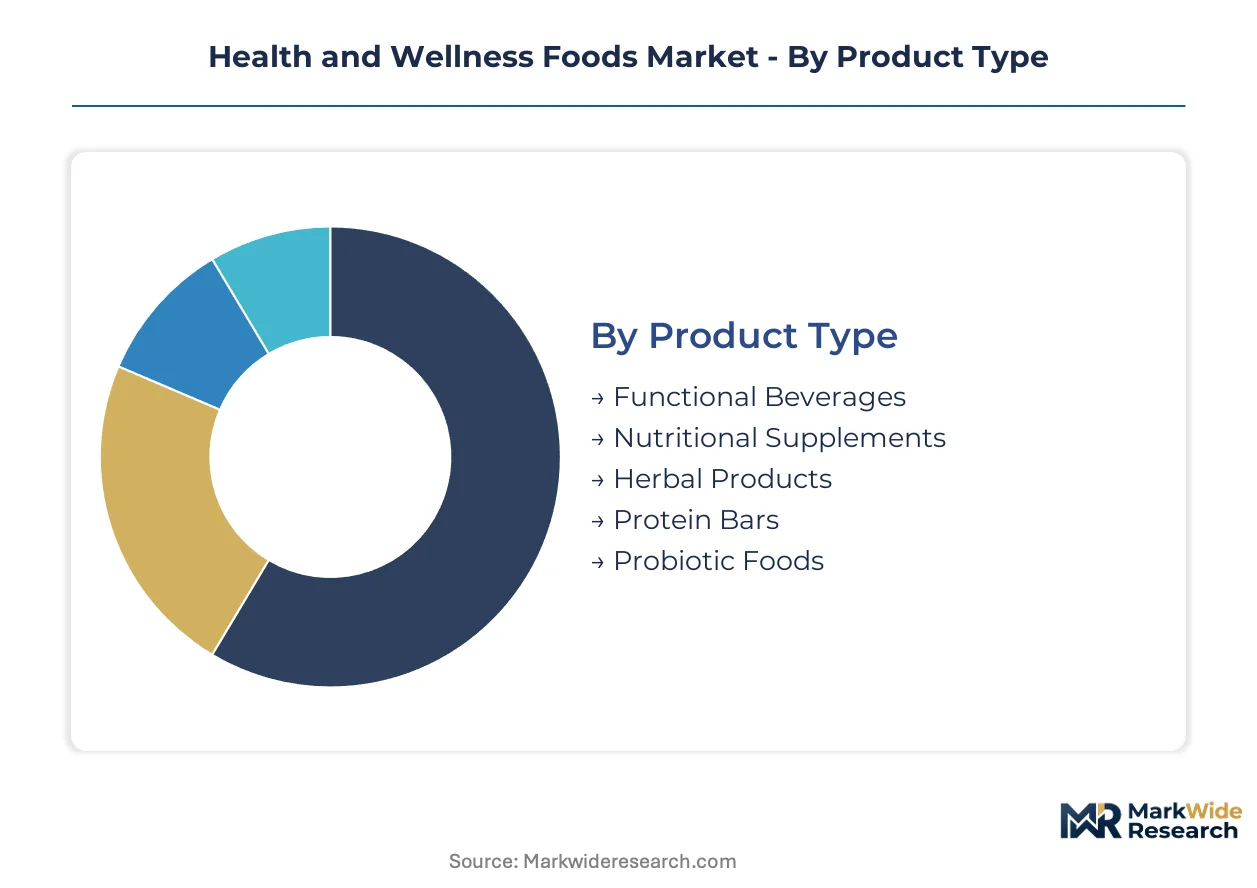
Market segmentation for health and wellness foods provides a structured view of diverse product offerings and consumer needs. This detailed analysis helps manufacturers align product development and distribution strategies with specific market demands and regulatory requirements.
Product Type:
Regulatory frameworks differentiate product types based on their intended use and composition, influencing market access and claim substantiation.
- Functional Beverages:These liquid formulations contain specific bioactive compounds, such as vitamins, minerals, or probiotics, designed to deliver targeted health benefits beyond basic hydration. Demand concentrates in Europe, driven by consumer convenience and the EU's stringent nutritional labeling requirements.
- Nutritional Supplements:Products in this category offer concentrated forms of nutrients or other substances to supplement the diet, often addressing specific deficiencies or health goals. China's expanding middle class shows strong demand for these products, influenced by proactive health management trends and SAMR registration protocols.
- Herbal Products:This segment includes formulations derived from plant extracts and botanicals, often rooted in traditional medicine practices.
- Protein Bars:Convenient, ready-to-eat bars fortified with protein, targeting muscle recovery and satiety for active individuals.
- Probiotic Foods:Products containing live microorganisms, such as certain yogurts or fermented drinks, aimed at improving gut health.
Functional Beverages handle the majority of throughput; Probiotic Foods are the fastest mover on share.
Ingredient Composition:
Ingredient composition often dictates product cost tiers, with specialized components commanding higher prices.
- Plant-Based Proteins:Derived from sources like soy, peas, or rice, these proteins serve as alternatives to animal-based options, catering to vegetarian, vegan, and flexitarian diets. Danone S.A. leverages these ingredients to meet consumer preference for clean label formulations and sustainable choices.
- Vitamins & Minerals:Essential micronutrients added to foods and beverages to fortify products, addressing common dietary deficiencies or supporting general health. Nestlé S.A. utilizes these components across its vast portfolio of fortified food products, meeting regulatory standards for nutrient content claims.
- Omega-3 Fatty Acids:These polyunsaturated fats, sourced from fish oil or algae, are incorporated for their recognized benefits in heart and brain health.
- Fiber:Dietary fiber, from sources like whole grains or chicory root, is added to support digestive health and satiety.
- Antioxidants:Compounds like vitamins C and E, or polyphenols, included for their ability to protect cells from oxidative damage.
Supply chain configurations for Plant-Based Proteins and Omega-3 Fatty Acids are complex due to sourcing and processing requirements.
Consumer Age Group:
Different consumer age groups present distinct nutritional needs and application requirements for health and wellness products.
- Adults:This broad segment seeks products for general wellness, weight management, and preventive health, forming the largest consumer base. Demand is significant across North America and Western Europe, driven by diverse lifestyle goals and a focus on proactive health.
- Athletes:Individuals focused on sports performance and recovery require specialized nutrition, including protein, electrolytes, and energy-boosting ingredients. Targeted interventions for this group are seeing increased adoption, supported by advancements in ingredient science and personalized nutrition.
- Children:Products for this group often focus on growth, development, and fortified options to ensure adequate nutrient intake.
- Seniors:This segment requires products supporting bone health, cognitive function, and managing age-related health concerns.
- Pregnant Women:Specialized formulations provide essential micronutrients crucial for maternal and fetal health during pregnancy.
The Adults segment constitutes the largest market share, while Athletes demonstrate rapid expansion in specialized product categories.
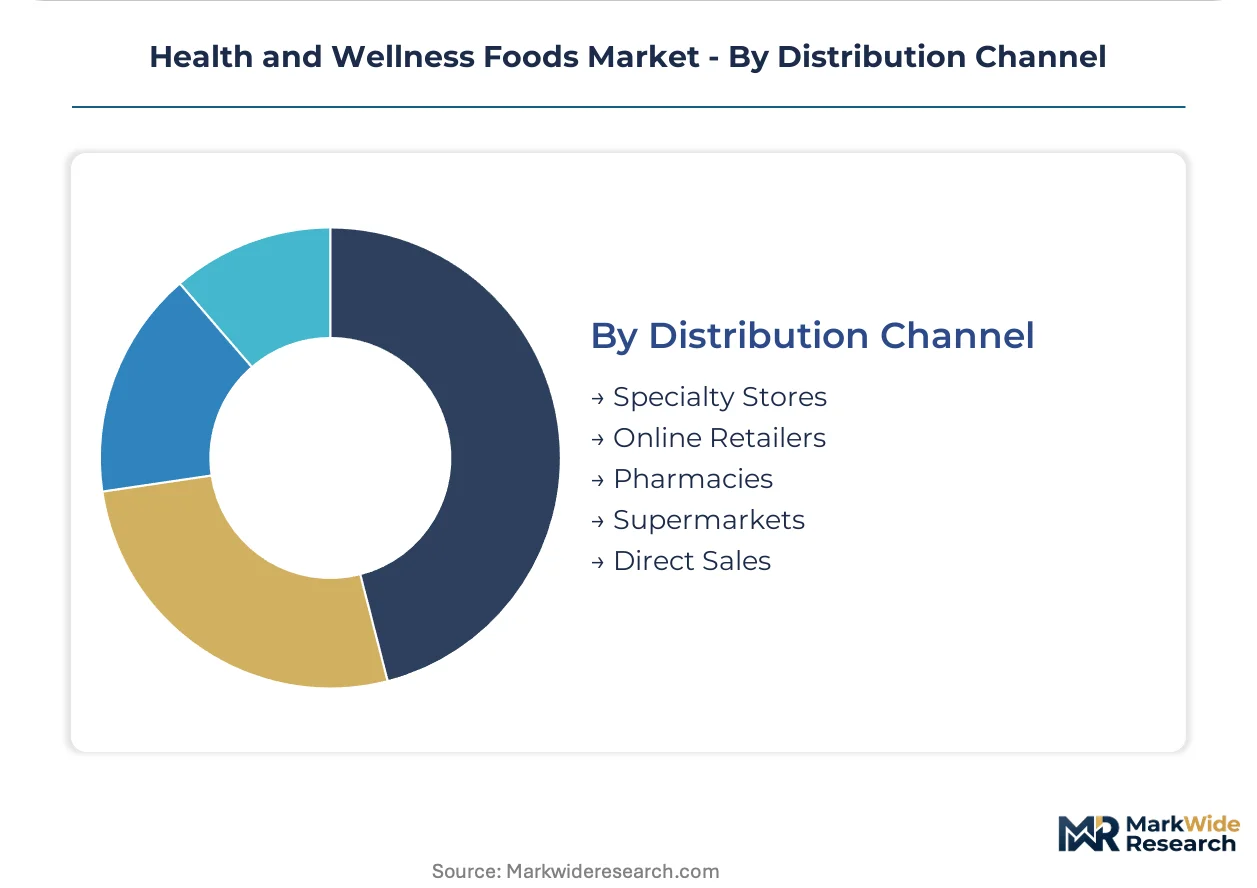
Distribution Channel:
Customer procurement patterns significantly influence the effectiveness and reach of various distribution channels.
- Online Retailers:These platforms facilitate direct-to-consumer sales, offering convenience and a wide selection, often incorporating subscription models for recurring purchases. This channel sees strong demand in major metropolitan areas across North America, supported by robust logistics infrastructure.
- Supermarkets:Traditional grocery stores provide broad consumer access, offering health and wellness foods alongside conventional products, benefiting from high foot traffic. These outlets cater to everyday shopping needs and leverage brand visibility for mainstream adoption.
- Specialty Stores:Retailers focused exclusively on health foods, organic products, or dietary supplements, serving informed consumers seeking niche items.
- Pharmacies:These channels offer health-focused products, often with professional advice, building consumer trust for dietary supplements and functional foods.
- Direct Sales:This channel involves direct interaction between sellers and consumers, often through multi-level marketing or personalized consultations.
Online Retailers offer significant margin expansion through direct engagement, whereas Supermarkets provide extensive volume opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Health and Wellness Foods Market exhibits a complex interplay of import and export dynamics, driven by localized production capabilities and consumer preferences. Nations with robust agricultural sectors often serve as ingredient suppliers, while developed economies frequently import specialized functional ingredients and finished products. This global trade network underpins the diverse availability of health-conscious food options worldwide.
China
China's expanding middle class drives substantial demand for fortified foods, functional beverages, and infant nutrition products. The State Administration for Market Regulation (SAMR) governs food safety and registration protocols, ensuring product integrity. Major cities like Shanghai and Beijing represent significant consumption hubs, with local manufacturers innovating to meet specific dietary needs.
United States
Consumers in the United States prioritize general wellness, weight management, and preventive health, forming a large adult consumer base. The US FDA enforces strict rules on nutrient content and health claims, influencing product marketing strategies. California's vibrant food tech scene fosters innovation in plant-based proteins and personalized nutrition platforms.
Germany
German consumers show strong preference for verifiably healthy options, influenced by the European Union's stringent nutritional labeling requirements. The EU Green Deal compels manufacturers to reformulate products with greater transparency. Cities like Berlin and Munich are emerging as centers for organic and natural food production, catering to discerning buyers.
Brazil
Brazil exhibits rising consumer awareness of proactive health management, particularly for functional beverages and protein-fortified foods. ANVISA, the national health surveillance agency, regulates food supplements and functional ingredients. São Paulo acts as a key distribution and innovation hub for health and wellness products across Latin America.
India
India's growing urban population increasingly seeks health and wellness foods to address lifestyle-related health concerns. The Food Safety and Standards Authority of India (FSSAI) sets standards for fortified foods and dietary supplements. Delhi-NCR and Mumbai are becoming significant markets for functional food product launches and distribution networks.
Health and Wellness Foods Market Key Industry Players
Listed leaders compete with private specialists across product innovation and market reach within the health and wellness foods sector. The market structure exhibits both consolidation among established food giants and fragmentation from numerous niche players. Strategic archetypes include diversified conglomerates, specialized ingredient providers, and direct-to-consumer wellness brands. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market presence, while smaller firms focus on niche segments. This dynamic environment fosters continuous product development and market entry strategies.
On the premium-tier vector, Nestlé S.A. exemplifies a global conglomerate with a vast portfolio of nutritional supplements and fortified food products, leveraging its extensive distribution network. Danone S.A. represents a specialist in probiotic foods and plant-based alternatives, addressing clean label consumer preferences. General Mills, Inc. occupies a position in the organic and natural foods space, expanding its offerings to meet evolving consumer demand for healthier options.
| Leading Market Players |
|---|
| Unilever PLC |
| Conagra Brands |
| Nestlé S.A. |
| Herbalife Nutrition Ltd. |
| The Hain Celestial Group |
| Danone S.A. |
| General Mills |
| United Natural Foods |
| PepsiCo |
| Others |
Cost & Logistics Intelligence
Plant-based protein substitution for animal proteins simultaneously reshapes supply geography and pricing economics. This dynamic shifts sourcing from traditional agricultural regions to new processing hubs, impacting raw material costs and final product pricing for health and wellness foods.
Pricing Analysis
Industrial OEM buyers anchor a tiered pricing structure across premium, standard, and economy levels. Price differentiation stems from certification level, such as USDA Organic or Non-GMO Project Verified, and customization level for specific formulations. Pricing softness reflects intense competition from private labels and conventional food categories. Consumers in the economy segment are most price-sensitive, while athletes and those seeking personalized nutrition show lower sensitivity.
Supply Chain Analysis
Port congestion in major global trade lanes creates inbound logistics cost pressures for specialized ingredients. Geographic supply concentration for advanced processing and bioactive compounds centers on China, the United States, and Europe. Supply chains draw from raw material dependencies on plant-based proteins, omega-3 fatty acids, and specific probiotic strains. Regulatory restrictions on ingredient sourcing and health claims create a significant compliance risk. Distribution runs through direct-to-consumer (DTC) models and traditional supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The health and wellness foods market presents an early-cycle expansion story, driven by the increasing consumer adoption of proactive health management. Consumers prioritize preventative nutrition, creating sustained demand for functional products.
For Market Incumbents: Secure proprietary ingredient supply chains to mitigate high input costs and ensure ingredient purity. Invest in clinical validation for new product formulations, particularly for functional beverages, to meet stringent regulatory requirements. This strategy counters the threat of unsubstantiated claims from smaller entrants and reinforces consumer trust. Expand distribution into underserved geographies, like Southeast Asia, leveraging existing global networks.
For New Entrants and Emerging Players: Lead with personalized nutrition platforms, integrating diagnostic tools with customized food delivery services. Target the mental wellness foods segment, which remains nascent but offers significant growth potential with adaptogens and nootropics. Focus on direct-to-consumer models to establish brand loyalty and gather direct consumer feedback. This approach allows for agile product development in niche areas.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clean-label food brands and specialized ingredient providers. Long-term viability for the health and wellness foods market spans beyond a decade, supported by fundamental shifts in consumer behavior towards proactive health. Identify innovative startups in plant-based proteins or micro-encapsulation technology for strategic acquisition. The signal to watch is sustained regulatory clarity on health claims in emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Establishes product efficacy and ensures compliance with strict regulatory bodies like EFSA. |
| Plant-Based Portfolio Expansion | Addresses consumer demand for clean-label formulations and sustainable food choices. |
| Direct-to-Consumer Channel Development | Builds brand loyalty and provides valuable consumer data for product iteration. |
| Micro-encapsulation Technology Adoption | Protects sensitive bioactive ingredients, enhancing product stability and bioavailability. |
| Personalized Nutrition Platform Launch | Caters to individual health needs, creating highly customized subscription services for consumers. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings of this study. Interviews included R&D directors, regulatory affairs specialists, and marketing managers from leading food manufacturers. Secondary data sources comprised government food safety standards, academic journals on nutrition, and corporate financial filings. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Sensitivity analysis determined the impact of various macroeconomic and industry-specific variables on market projections. The analytical framework modeled market dynamics across product type, ingredient composition, consumer age group, and distribution channel. CAGRs were derived from historical growth trends and projected future demand patterns over the analysis window. Key forecast inputs included consumer health spending and ingredient innovation pipelines.
Forecasts assume regulatory continuity in the US FDA, EFSA, and SAMR regimes; material policy shifts would require re-modeling. The projections reflect current understanding of consumer preferences and technological advancements. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Vegan Protein Bars Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market