
 Nanocapsules Market | 2026-2036
Nanocapsules Market Size, Share, and Industry Trends Forecast 2026-2036
Nanocapsules Market Analysis
European contract manufacturing capacity for lipid-based nanocarriers is hardening as specialty producers scale GMP-compliant operations. Capsugel leverages its integrated softgel and nanocapsule platform to anchor supply relationships with mid-sized pharmaceutical developers. Camurus competes through its proprietary FluidCrystal injection depot technology, which extends release kinetics for peptide APIs. ACG Worldwide sustains cost-advantaged production from its Indian manufacturing base, serving generic nanomedicine programs across emerging markets.
Nanocapsules are submicron vesicles with a liquid or semisolid core surrounded by a polymeric, lipid, or metallic shell, typically ranging from 10 to 1000 nanometers in diameter, engineered for targeted delivery of hydrophobic or hydrophilic actives across biological membranes. Their primary commercial purpose centers on improving bioavailability of poorly soluble drugs, enabling controlled release, and reducing systemic toxicity through tissue-specific accumulation. Polymeric nanocapsules dominate current revenue pools due to established formulation science and versatile surface functionalization, while lipid nanocapsules represent the fastest-growing category as mRNA vaccine platforms validate lipid nanoparticle architectures. Intravenous delivery commands the largest therapy-area share in oncology applications, though oral nanocapsule formulations for neurology indications are gaining clinical traction as blood-brain barrier penetration strategies mature.
FDA's Center for Drug Evaluation and Research maintains stringent quality-by-design expectations for nanotechnology-enabled products, requiring extensive physicochemical characterization that elevates development costs and timelines for new entrants. The EU's MDR and EMA's nanomedicine reflection papers create additional compliance layers for market access, particularly around immunogenicity assessment and batch-to-batch reproducibility. REACH obligations in Europe further govern the environmental fate of metallic and polymeric shell materials used in scale-up manufacturing. Stakeholders must monitor evolving pharmacovigilance requirements for long-circulating nanocarriers and pre-emptively invest in analytical capabilities that satisfy divergent regulatory expectations across major jurisdictions.
Market Dynamics
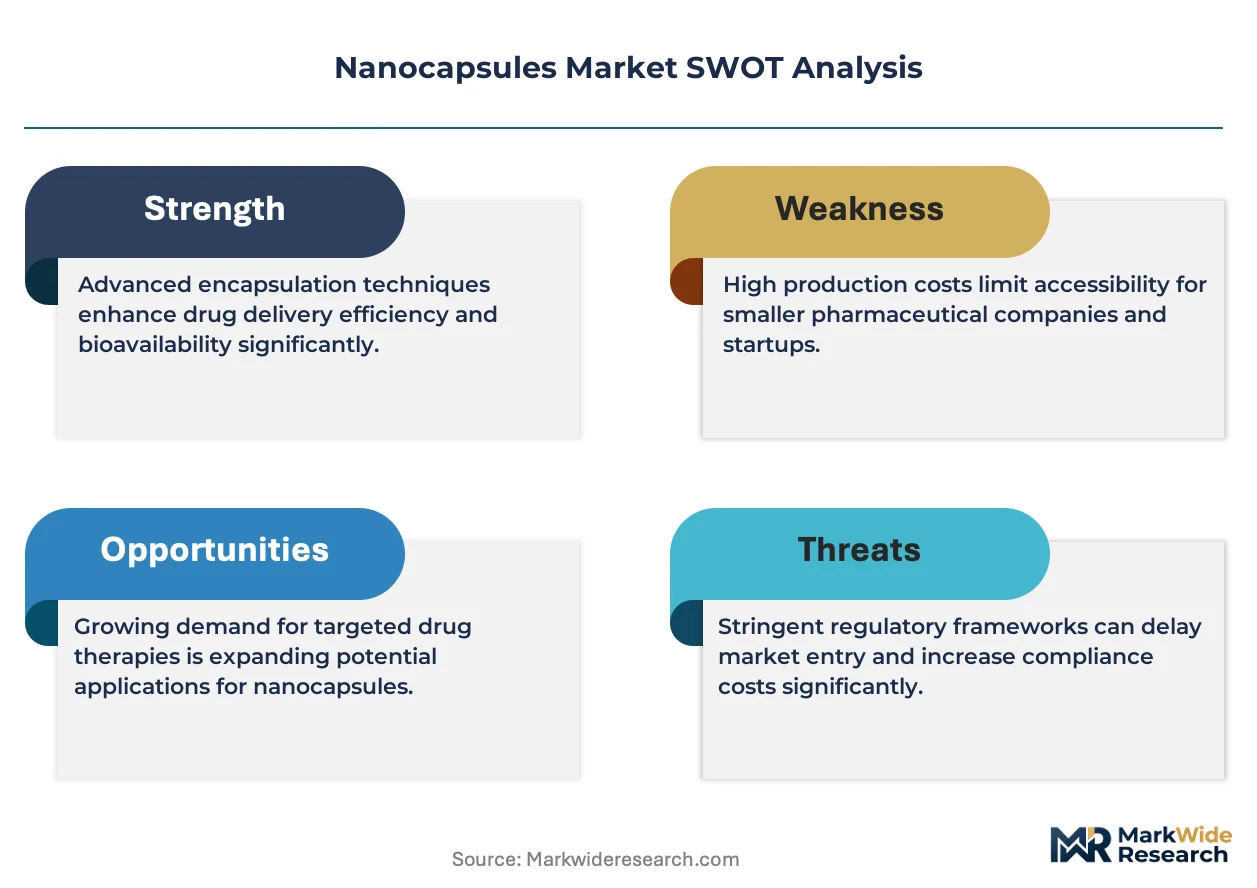
FDA's quality-by-design mandates for nanotechnology-enabled products are forcing pharmaceutical developers to front-load physicochemical characterization investments, compressing timelines for new entrants while elevating analytical capability requirements across the value chain.
Growth Catalysts
- Accelerated Approval Pathways:FDA's nanomedicine fast-track programs reduce regulatory review periods for oncology and neurology applications, pulling venture funding into early-stage lipid nanoparticle programs.
- mRNA Platform Validation:COVID-19 vaccine deployment established lipid nanoparticle manufacturing at commercial scale, de-risking process technology transfer for peptide and gene therapy developers.
- Germany's Manufacturing Infrastructure:Specialized GMP facilities in Frankfurt and Munich clusters anchor European contract production capacity for polymeric shell materials serving mid-sized developers.
Market Restraints
- High-Purity Lipid Input Volatility:Ionizable lipid supply concentrates among a handful of specialty chemical producers, exposing formulation houses to price swings and allocation constraints during demand surges.
- Batch-to-Batch Reproducibility:EMA's nanomedicine reflection papers demand stringent physicochemical equivalence across manufacturing lots, requiring analytical investments that strain emerging market producers.
- Conventional Liposome Substitution:Established PEGylated liposome platforms for doxorubicin and paclitaxel delivery compete for oncology budgets against novel nanocapsule architectures with unproven reimbursement pathways.
Strategic Opportunities
- Oral Blood-Brain Barrier Indications:Neurology programs targeting Alzheimer's and Parkinson's represent underpenetrated territory where polymeric nanocapsules demonstrate preclinical penetration advantages over intravenous biologics.
- India's Generic Nanomedicine Export Base:CDSCO's streamlined abbreviated approval pathways for complex generics create a manufacturing hub serving African and Southeast Asian markets with cost-adapted lipid formulations.
- REACH Environmental Compliance Services:Metallic shell material producers face emerging obligations governing environmental fate, opening advisory and testing revenue streams for contract research organizations.
Industry Challenges
- Cross-Functional Talent Scarcity:Formulation scientists possessing simultaneous expertise in polymer chemistry, pharmacokinetic modeling, and GMP scale-up command premium compensation, constraining team expansion at mid-cap developers.
- Analytical Equipment Capex Burden:Dynamic light scattering, transmission electron microscopy, and asymmetric flow field-flow fractionation systems require seven-figure capital commitments for in-house physicochemical characterization.
- Divergent Jurisdictional Standards:FDA's emphasis on immunogenicity risk assessment differs from EMA's batch equivalence focus, forcing parallel dossier development for multi-region product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanocapsules Market |
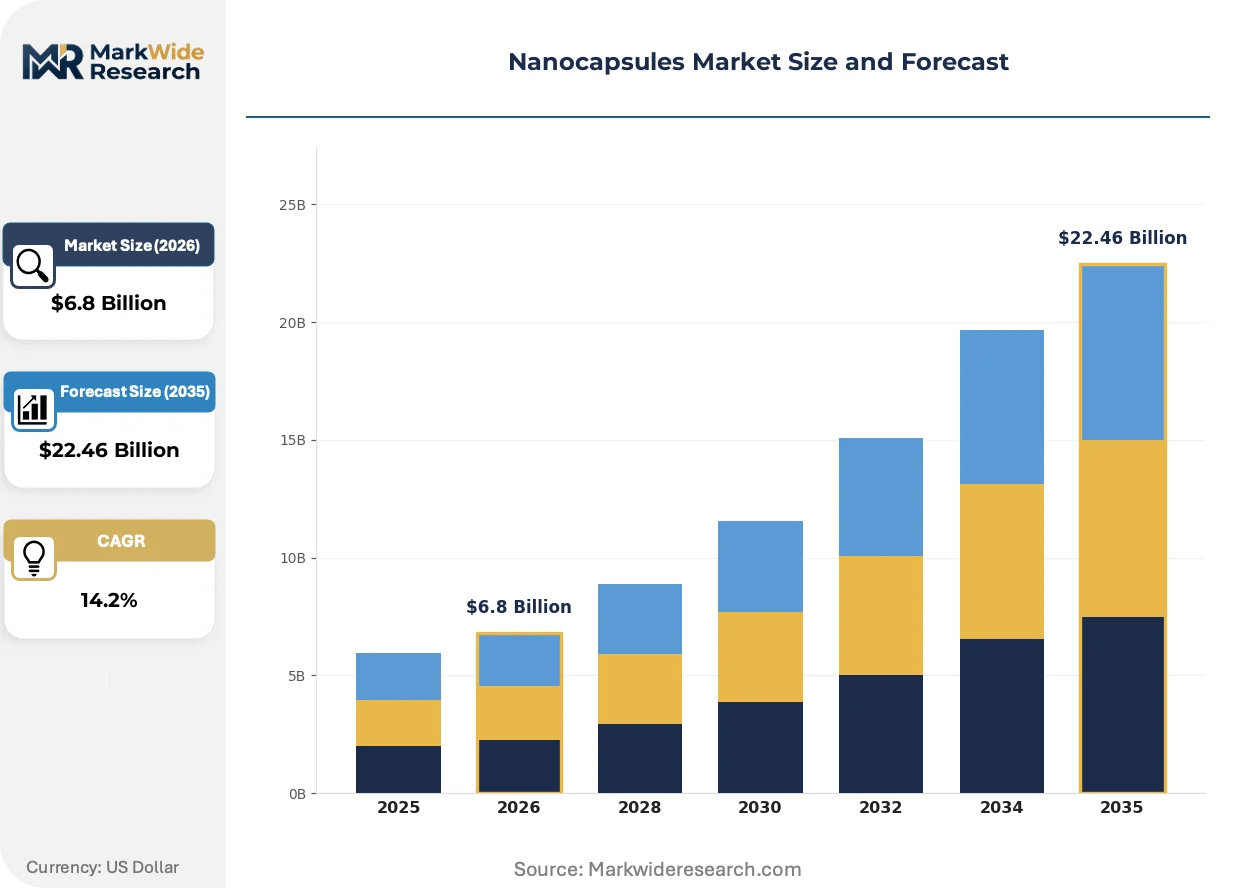
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Nanocapsules, Lipid Nanocapsules, Metallic Nanocapsules, Hybrid Nanocapsules End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Agriculture Therapy Area: Oncology, Cardiology, Neurology, Infectious Diseases Delivery Mode: Oral, Intravenous, Topical, Inhalation |
| Companies Covered | CapsCanada, NanoSphere Health Sciences, Capsugel, Camurus, BioDelivery Sciences International, ACG Worldwide, Suheung, PlasmaChem GmbH, Qualicaps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanocapsules Market Emerging Trajectories
Lipid nanoparticle architectures are fragmenting into application-specific configurations as platform technologies mature, with formulation science diverging sharply between mRNA vaccines, gene therapies, and small-molecule oncology payloads.
Active targeting ligand conjugation is modularizing nanocapsule surface engineering, enabling antibody and peptide functionalization without reformulating core shell compositions. Oncology developers at Memorial Sloan Kettering and MD Anderson are piloting folate-receptor-targeted docetaxel nanocapsules in Phase I trials. This modularization compresses development timelines by decoupling targeting optimization from encapsulation efficiency validation.
EMA's 2023 nanomedicine reflection paper update tightened immunogenicity assessment requirements for long-circulating carriers, mandating complement activation testing that adds six to nine months to preclinical packages. Contract research organizations in the Netherlands and Switzerland are scaling dedicated nanotoxicology facilities to absorb this analytical burden. European oncology developers now sequence regulatory submissions to prioritize US FDA filings where immunogenicity expectations remain less prescriptive.
Hospital procurement committees are consolidating nanomedicine purchasing through centralized pharmacy and therapeutics committees, displacing traditional physician-directed selection for infused oncology products. University of Texas MD Anderson and Dana-Farber Cancer Institute have established dedicated nanomedicine formulary review boards evaluating cost-per-quality-adjusted-life-year against conventional liposome benchmarks. This concentration is most visible in US academic medical centers where bundled payment models for oncology episodes incentivize therapeutic substitution.
Nanocapsules Market Segmentation
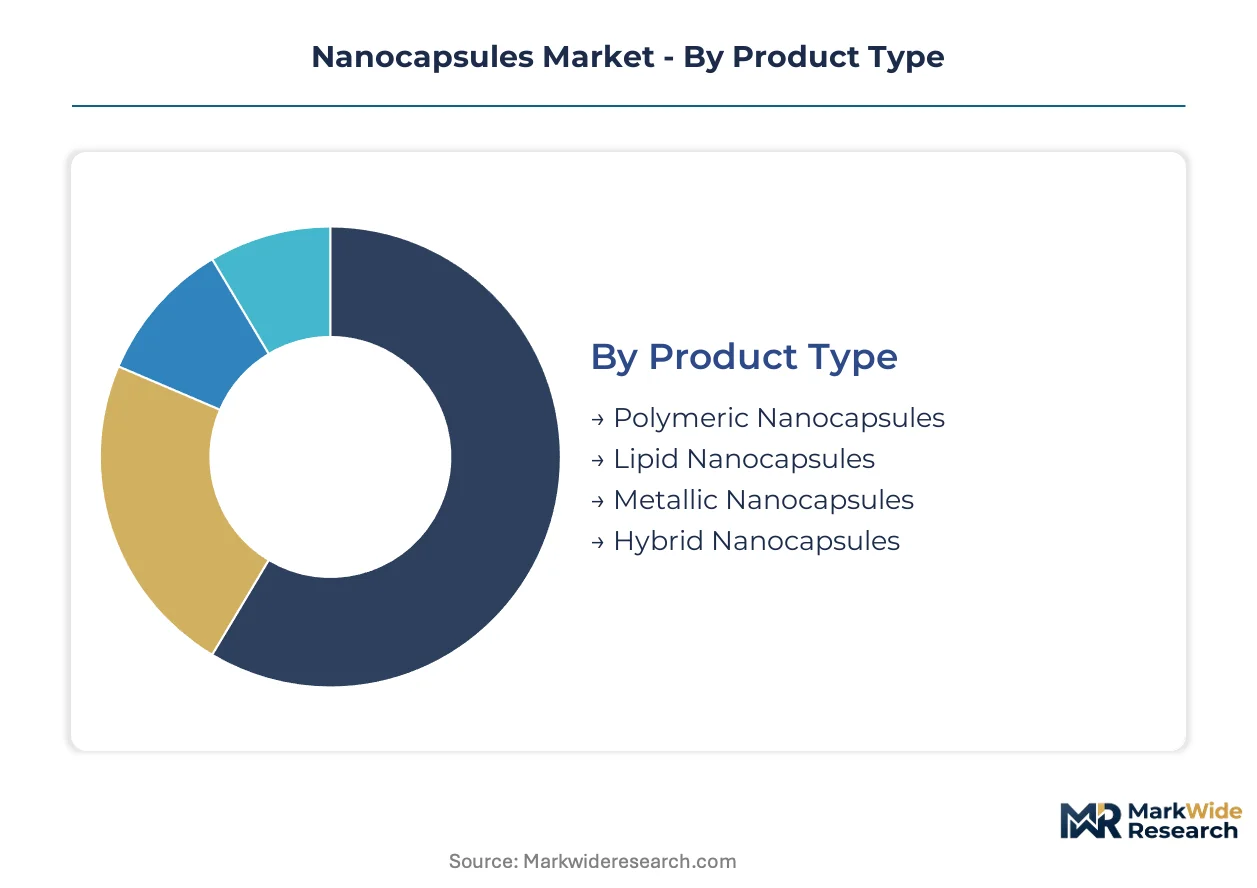
Nanocapsule architectures demand precise alignment between shell composition, biological target, and administration route. Segmentation reveals where formulation science concentrates investment and which therapy areas command premium development resources.
Product Type:
Polymeric shells serve standalone drug delivery systems requiring surface functionalization, while lipid architectures embed within platform technologies validated at manufacturing scale.
- Polymeric Nanocapsules:Synthetic or natural polymer shells—PLGA, chitosan, or polycaprolactone—enable tunable degradation kinetics and versatile ligand conjugation. Demand clusters in oncology applications across Germany and Japan where GMP-compliant polymeric manufacturing infrastructure supports mid-sized developers targeting controlled-release profiles.
- Lipid Nanocapsules:Lipid nanoparticle architectures with solid lipid cores or phospholipid bilayers optimize hydrophobic drug loading and mRNA stability. COVID-19 vaccine deployment established commercial-scale manufacturing, pulling investment into neurology and gene therapy programs in the United States.
- Metallic Nanocapsules:Gold or iron oxide shells enable photothermal therapy and magnetic targeting in specialized oncology centers.
- Hybrid Nanocapsules:Combined polymer-lipid or polymer-metallic structures address multi-modal delivery requirements in academic research settings.
Volume placements concentrate in polymeric platforms; the faster expansion belongs to lipid architectures.
End User:
Customer segments stratify by regulatory burden tolerance and manufacturing sophistication required for commercial scale.
- Pharmaceuticals:FDA and EMA-regulated developers deploy nanocapsules for bioavailability enhancement of BCS Class II and IV compounds. Oncology and neurology pipelines in the United States, Germany, and Japan drive contract manufacturing demand for GMP-compliant lipid and polymeric formulations.
- Nutraceuticals:Curcumin, resveratrol, and omega-3 fatty acid encapsulation improves stability and absorption in dietary supplement applications. Demand concentrates in India's export-oriented manufacturing base serving North American and European wellness markets.
- Cosmetics:Retinol and antioxidant nanocapsules address dermal penetration and ingredient stability in premium skincare formulations.
- Agriculture:Pesticide and micronutrient encapsulation enables controlled-release crop protection with reduced environmental runoff.
Pharmaceutical applications absorb the bulk of high-margin capacity; nutraceuticals are climbing the fastest as India's complex generic infrastructure matures.
Therapy Area:
Clinical indication determines shell material selection, targeting strategy, and acceptable toxicity thresholds.
- Oncology:Doxorubicin, paclitaxel, and docetaxel nanocapsules exploit enhanced permeability and retention effects for tumor accumulation. Memorial Sloan Kettering and MD Anderson pilot folate-receptor-targeted formulations, while EMA immunogenicity requirements add analytical burden to European filings.
- Neurology:Polymeric nanocapsules targeting Alzheimer's and Parkinson's disease demonstrate blood-brain barrier penetration advantages over intravenous biologics. Preclinical programs in Germany and Japan concentrate on oral formulations with surface-modified polysorbate 80 coatings.
- Cardiology:Statin and antihypertensive encapsulation addresses bioavailability limitations in geriatric populations.
- Infectious Diseases:Antimicrobial and antiviral payloads leverage nanocapsule stability for tropical climate distribution.
Oncology commands the deepest development pipelines; neurology shows the steepest expansion trajectory as blood-brain barrier strategies mature.
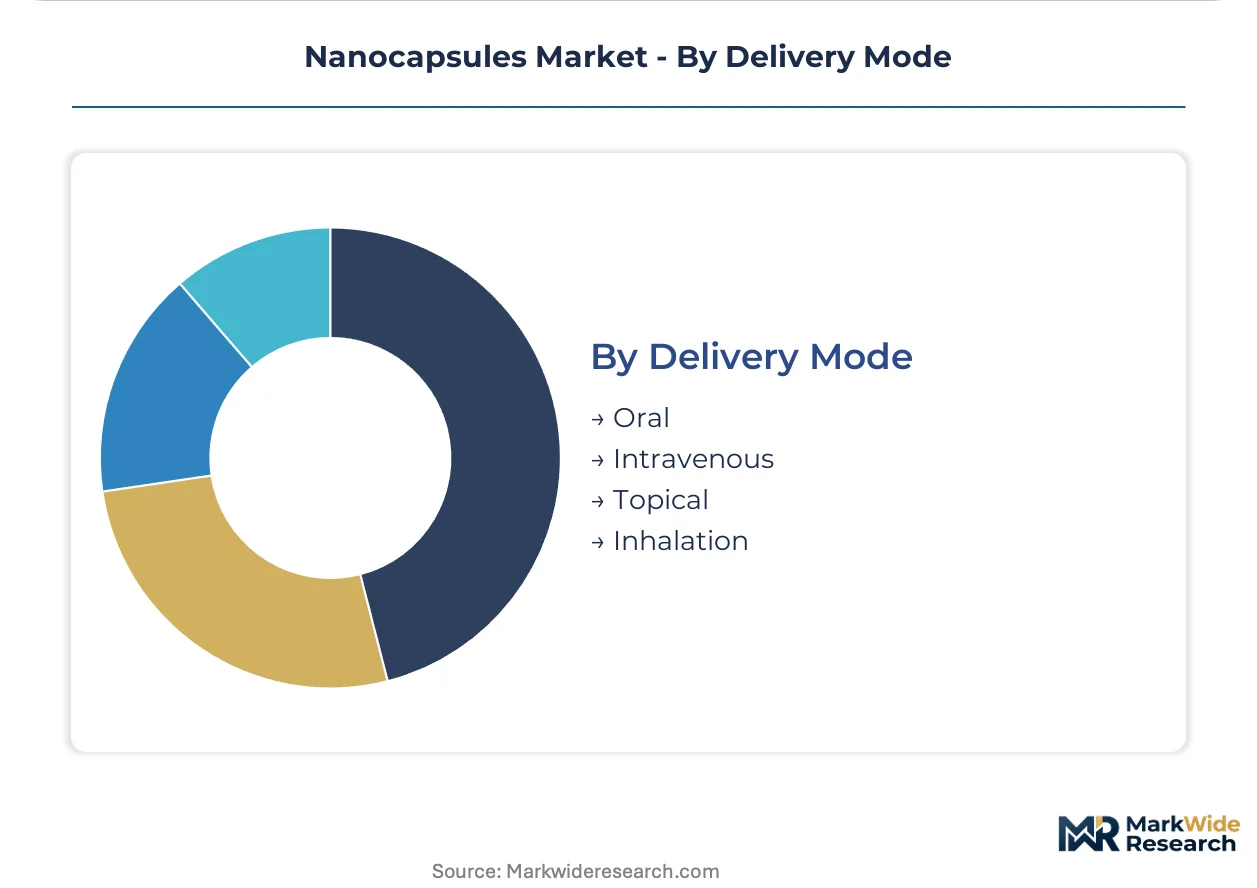
Delivery Mode:
Administration route dictates manufacturing scale, stability requirements, and reimbursement pathways.
- Intravenous:Lipid nanoparticle and polymeric nanocapsule infusions dominate oncology applications with established hospital formulary pathways. US academic medical centers consolidate purchasing through pharmacy and therapeutics committees evaluating cost-per-QALY against conventional liposome benchmarks.
- Oral:Polymeric shell formulations for neurology indications gain traction as blood-brain barrier penetration strategies advance. India's CDSCO streamlined pathways enable generic nanomedicine exports to African and Southeast Asian markets.
- Topical:Dermal and transdermal applications concentrate in cosmetic and dermatological segments with lower regulatory barriers.
- Inhalation:Pulmonary delivery of nanocapsulated antibiotics and biologics addresses cystic fibrosis and respiratory infections.
Intravenous administration anchors revenue concentration; oral formulations are gaining share fastest as neurology indications advance through clinical validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ionizable lipid feedstock from German specialty chemical producers anchors European nanocapsule manufacturing capacity. Japanese pharmaceutical clusters source polymeric shell materials from domestic polymer suppliers for neurology applications. Indian generic exporters leverage cost-adapted formulations to serve African and Southeast Asian markets.
United States
Oncology and neurology pipelines at Memorial Sloan Kettering and MD Anderson drive contract manufacturing demand for GMP-compliant lipid nanoparticles. FDA's accelerated approval pathways for nanomedicines pull venture funding into early-stage programs. Boston and San Francisco biotech clusters concentrate formulation development for blood-brain barrier indications.
Germany
Frankfurt and Munich manufacturing hubs anchor European contract production for polymeric shell materials serving mid-sized developers. EMA's nanomedicine reflection papers mandate stringent batch-to-batch reproducibility testing, elevating analytical requirements. REACH obligations govern environmental fate assessment for metallic and polymeric materials used in scale-up operations.
Japan
PMDA's quality expectations for novel drug delivery systems align with METI's advanced materials initiatives to sustain domestic nanomedicine competitiveness. Osaka and Tokyo pharmaceutical clusters concentrate oral nanocapsule development for Alzheimer's and Parkinson's disease. Surface-modified polysorbate 80 coatings from domestic suppliers enable blood-brain barrier penetration strategies.
India
CDSCO's streamlined abbreviated approval pathways for complex generics position Indian manufacturers as export hubs for cost-adapted lipid formulations. Maharashtra and Gujarat production facilities serve African and Southeast Asian markets with bioavailability-enhanced nanomedicines. ACG Worldwide's manufacturing base exemplifies the cost-advantaged production model dominating emerging market supply.
Switzerland
Swissmedic's regulatory framework for advanced therapeutics attracts nanomedicine developers seeking European market access with streamlined dossier requirements. Basel and Zurich clusters concentrate contract research organizations scaling nanotoxicology facilities for EMA immunogenicity testing. Complement activation assessment capabilities absorb analytical burdens from developers sequencing US-first regulatory submissions.
Nanocapsules Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue platform technology licensing and regional contract manufacturing partnerships. The vendor base stratifies across integrated softgel specialists, lipid nanoparticle platform owners, and cost-advantaged generic suppliers. Three archetypes dominate: technology licensors with proprietary delivery architectures, integrated manufacturers with captive shell material supply, and regional contract producers serving emerging market price points. Competitive moves concentrate on GMP capacity expansion in Frankfurt and Mumbai clusters and strategic partnerships bridging formulation science with commercial manufacturing scale.
Within the technology licensor tier, Capsugel and Camurus exemplify proprietary platform strategies, while ACG Worldwide occupies the cost-advantaged manufacturing archetype. Capsugel's integrated softgel heritage positions it within formulation science consolidation trends. Camurus represents the injection depot specialization vector extending release kinetics for peptide actives. ACG Worldwide anchors emerging market supply relationships through Indian manufacturing scale. PlasmaChem GmbH sits within the European specialty chemical supplier cluster serving ionizable lipid demand.
| Leading Market Players |
|---|
| CapsCanada |
| NanoSphere Health Sciences |
| Capsugel |
| Camurus |
| BioDelivery Sciences International |
| ACG Worldwide |
| Suheung |
| PlasmaChem GmbH |
| Qualicaps |
| Others |
Supply Flow & Price Mechanics
GMP certification tier divergence separates premium lipid nanoparticle formulations from cost-adapted polymeric alternatives, with FDA-validated batches commanding analytical service bundling while emerging market producers strip characterization to hit price points. This bifurcation concentrates contract manufacturing margins in Frankfurt and Mumbai clusters while pushing generic developers toward unbundled, commodity-grade supply relationships.
Pricing Analysis
Analytical service bundling distinguishes premium nanocapsule supply from stripped-down commodity offerings, with FDA-validated lipid nanoparticle formulations including physicochemical characterization reports and batch release documentation. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and ionizable lipid purity specifications. Cost compression in standard-tier polymeric nanocapsules intensifies as Indian generic manufacturers scale CDSCO-compliant export capacity. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity, while oncology biotech developers prioritize batch reproducibility over unit economics.
Supply Chain Analysis
Formulation scientist scarcity in German and Japanese manufacturing clusters constrains GMP-compliant polymeric shell production expansion. Ionizable lipid feedstock concentrates among German specialty chemical producers, with phospholipid and cholesterol inputs drawing from European and Indian suppliers. Single-source vulnerability in high-purity lipid allocation exposes formulation houses to supply interruption during demand surges. Distribution runs through contract manufacturing organizations serving mid-sized pharmaceutical developers with captive analytical capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FDA quality-by-design mandates will force sub-scale analytical providers into acquisition or exit, rewarding integrated platform owners with captive GMP capacity.
For Market Incumbents: Extend proprietary FluidCrystal and softgel-nanocapsule platform licensing to anchor mid-sized developer relationships before emerging lipid nanoparticle specialists achieve manufacturing scale. Deepen backward integration into ionizable lipid supply through long-term offtake agreements with German specialty chemical producers. Defend margin position by sequencing regulatory submissions to prioritize FDA pathways where immunogenicity requirements remain less prescriptive than EMA standards. For New Entrants and Emerging Players: Oral blood-brain barrier formulations for neurology indications represent the most penetrable white-space target, with Alzheimer's and Parkinson's pipelines demonstrating preclinical advantages over intravenous biologics. India's CDSCO-abbreviated approval pathways for complex generics offer regulatory arbitrage for cost-adapted lipid formulations serving African and Southeast Asian markets. Pursue platform licensing partnerships with established contract manufacturers rather than building captive GMP capacity. For Investors and Strategic Acquirers: Re-rating potential sits with integrated nanocapsule platform owners given FDA accelerated approval pathway expansion for oncology and neurology applications. Long-term viability favors technology licensors with proprietary delivery architectures and validated manufacturing scale over pure-play analytical service providers. Watch EMA nanomedicine reflection paper enforcement intensity as inflection indicator for European market access cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Capacity Expansion | Frankfurt and Mumbai facility investments anchor contract manufacturing relationships with mid-sized oncology developers. |
| Regulatory Submission Sequencing | US-first filing strategies exploit FDA immunogenicity flexibility relative to EMA batch equivalence mandates. |
| Active Targeting Ligand Modularization | Antibody and peptide surface conjugation capabilities compress development timelines for folate-receptor-targeted programs. |
| Long-term Lipid Supply Agreements | Ionizable lipid offtake contracts with German producers mitigate allocation risk during demand surges. |
| Nanotoxicology Facility Scaling | Netherlands and Switzerland CRO investments absorb EMA complement activation testing burdens from developers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at US academic medical centers. FDA nanomedicine guidance documents, EMA reflection papers, ClinicalTrials.gov entries, and REACH environmental fate assessments provided secondary validation. Bottom-up formulation pipeline analysis triangulated against top-down contract manufacturing capacity estimates across Frankfurt, Mumbai, and Osaka clusters.
Reconciliation of patient population projections, regulatory approval timelines, and manufacturing scale-up trajectories informed the analytical framework across the analysis window. Segmentation dimensions modeled included shell material composition, therapy area concentration, administration route, and regional regulatory cluster. CAGRs derived from patent filing trends, venture funding flows, and hospital formulary adoption curves, with particular weighting toward lipid nanoparticle platform validation post-mRNA vaccine deployment.
Revisions become necessary when FDA quality-by-design guidance enforcement intensifies, EMA immunogenicity requirements expand beyond complement activation testing, or ionizable lipid supply concentration triggers allocation constraints. Forecasts reflect assumptions regarding regulatory pathway stability and manufacturing scale-up feasibility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
United States Microspheres Market
Specialty Materials
Special Graphite Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Sheath Materials Market
Specialty Materials
EMI and RFI Shielding Materials Market