
 United States Neoprene Market | 2026-2036
United States Neoprene Market Size, Share, and Industry Trends Forecast 2026-2036
United States Neoprene Market Intelligence
High-performance grade neoprene is reorganizing competitive dynamics in the United States market. Lanxess leverages its Chattanooga production base to supply specialty elastomers for industrial hose applications. Covestro sustains technical leadership through advanced polymerization processes that yield superior ozone resistance. ARLANXEO anchors its position with backward integration into chloroprene monomer supply, insulating against raw material volatility.
Neoprene is a family of synthetic rubbers produced by free-radical emulsion polymerization of chloroprene, with specific gravity ranging from 1.23 to 1.25 and operating temperature tolerance from -35°C to 100°C, valued for oil resistance, chemical stability, and flexural endurance in dynamic sealing and vibration isolation applications. Solid neoprene sheet leads volume consumption in gasket fabrication, while liquid neoprene coatings represent the fastest-expanding segment as infrastructure rehabilitation projects demand spray-applied waterproofing membranes. Foam neoprene occupies the premium margin tier in wetsuit and protective equipment markets where compression set specifications differentiate suppliers.
EPA regulates chloroprene emissions under the National Emission Standards for Hazardous Air Pollutants, compelling facility upgrades at Louisiana and Texas production sites. OSHA enforces permissible exposure limits that shape workplace handling protocols and personal protective equipment requirements throughout the value chain. ASTM D2000 and SAE J200 standards govern material classification for automotive and industrial applications, creating certification barriers for non-compliant imports. Stakeholders must monitor evolving state-level air quality implementation plans and assess domestic compounding capacity against electrification-driven formulation shifts.
Market Dynamics
Electric vehicle thermal management requirements are restructuring neoprene formulation priorities across the United States, as gasket and hose specifications tighten under combined pressure from EPA emissions standards and electrification-driven performance thresholds.
Growth Catalysts
- Automotive electrification:Battery thermal management systems demand upgraded sealing performance, pulling high-grade neoprene compounds into EV manufacturing supply chains.
- Infrastructure rehabilitation:Federal bridge and tunnel maintenance programs specify spray-applied liquid neoprene membranes for waterproofing, expanding coating application volumes.
- OSHA workplace standards:Tighter permissible exposure limits for chloroprene are accelerating facility modernization investments that favor domestic compounders with compliant production assets.
Market Restraints
- Chloroprene monomer concentration:Gulf Coast petrochemical corridor dependence creates geographic supply vulnerability to hurricane disruptions and regional capacity constraints.
- EPA NESHAP compliance costs:Louisiana and Texas production sites face capital-intensive emission control upgrades that compress operating margins for non-integrated producers.
- Fluoroelastomer substitution:Aerospace and aggressive chemical applications increasingly specify FKM compounds where temperature extremes exceed neoprene's 100°C ceiling.
Strategic Opportunities
- Offshore wind infrastructure:Atlantic Coast cable sealing and nacelle gasket applications represent underdeveloped demand verticals with 25-year service life specifications.
- Recycled content mandates:California and New York procurement rules favor post-industrial neoprene reclaim in public works, rewarding compounders with closed-loop processing capabilities.
- Digital inventory platforms:Regional distributors are adopting specification-matching algorithms that reduce compounder-to-fabricator search friction and compress order cycles.
Industry Challenges
- Polymerization technician scarcity:Free-radical emulsion process expertise concentrates among aging workforces at legacy chloroprene facilities, constraining capacity expansion timelines.
- ASTM D2000 certification backlog:Third-party testing laboratory capacity limitations extend automotive qualification timelines, delaying new compound approvals by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Neoprene Market |
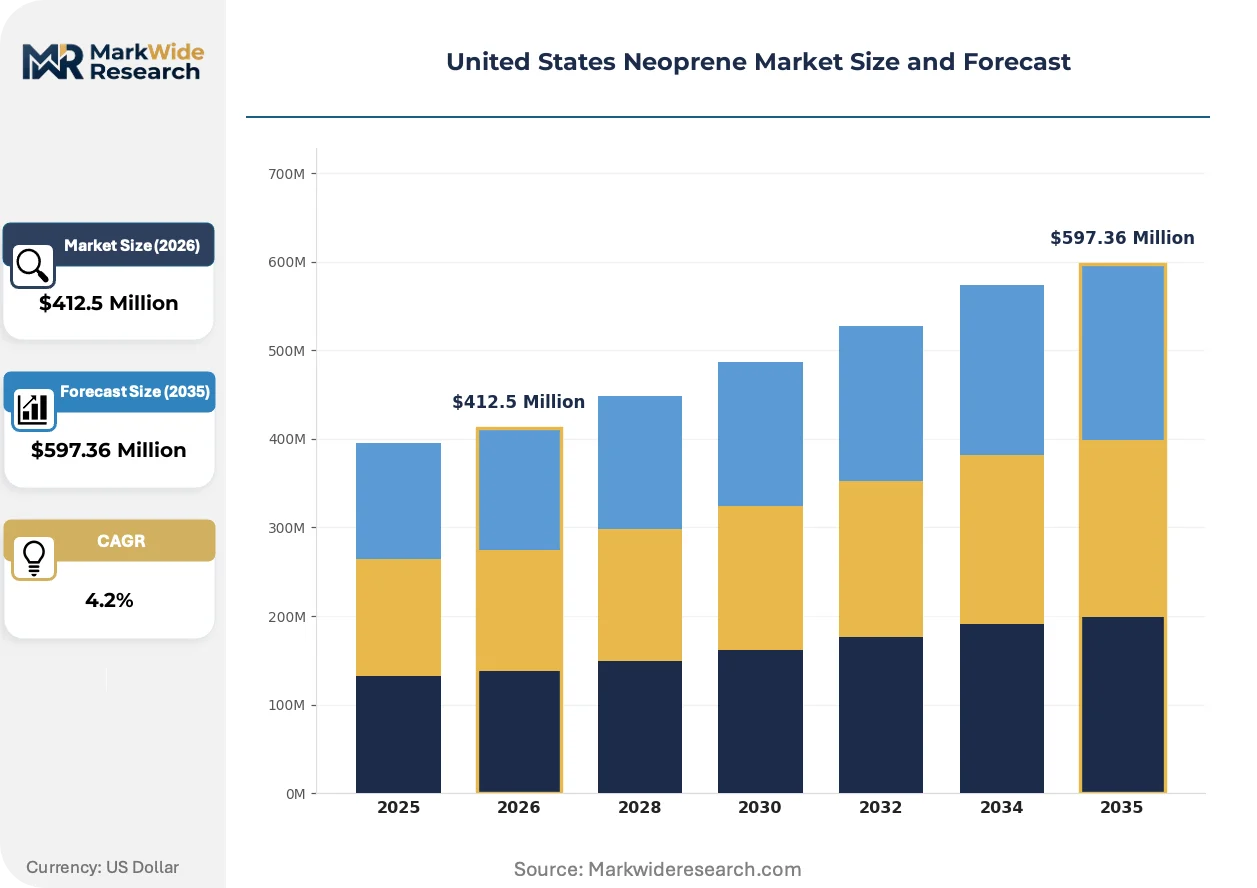
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Foam, Sheet Application: Automotive, Construction, Sports, Consumer Goods End User: Manufacturers, Retailers, Distributors, OEMs Form: Granules, Blocks, Coatings, Adhesives |
| Companies Covered | 3M, BRP Manufacturing, Covestro, Denka Company Limited, Lanxess, ARLANXEO, Pidilite Industries, Resonac Holdings Corporation, SEDO Chemicals Neoprene GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Neoprene Market Strategic Shifts & Innovations
Formulation chemistry and compliance architecture are converging to redefine competitive advantage in United States neoprene supply, with sustainability credentials and digital specification tools emerging as distinctiators beyond base polymer performance.
Advanced liquid neoprene coating systems is supplanting conventional sheet-and-adhesive waterproofing in infrastructure rehabilitation. State transportation departments specify spray-applied membranes for bridge deck protection, compressing installation timelines from weeks to days. This shift is compressing demand for solid sheet stock while expanding toll coating service revenues at regional compounders.
EPA's 2023 chloroprene emissions risk assessment is tightening National Emission Standards for Hazardous Air Pollutants enforcement at Louisiana and Texas production corridors. Integrated producers with captive monomer supply are absorbing compliance investments more efficiently than merchant market dependent compounders. Gulf Coast facility upgrades are prioritizing closed-loop vapor recovery systems ahead of 2026 implementation deadlines.
Specification-driven procurement consolidation is compressing supplier counts among automotive Tier 1 gasket fabricators. Buyers consolidate qualified compounder lists to three-to-five approved sources, replacing fragmented spot purchasing. This concentration is most visible in Michigan and Ohio automotive clusters, where thermal management system suppliers demand ISO 14001 certification alongside ASTM compliance.
United States Neoprene Market Segmentation
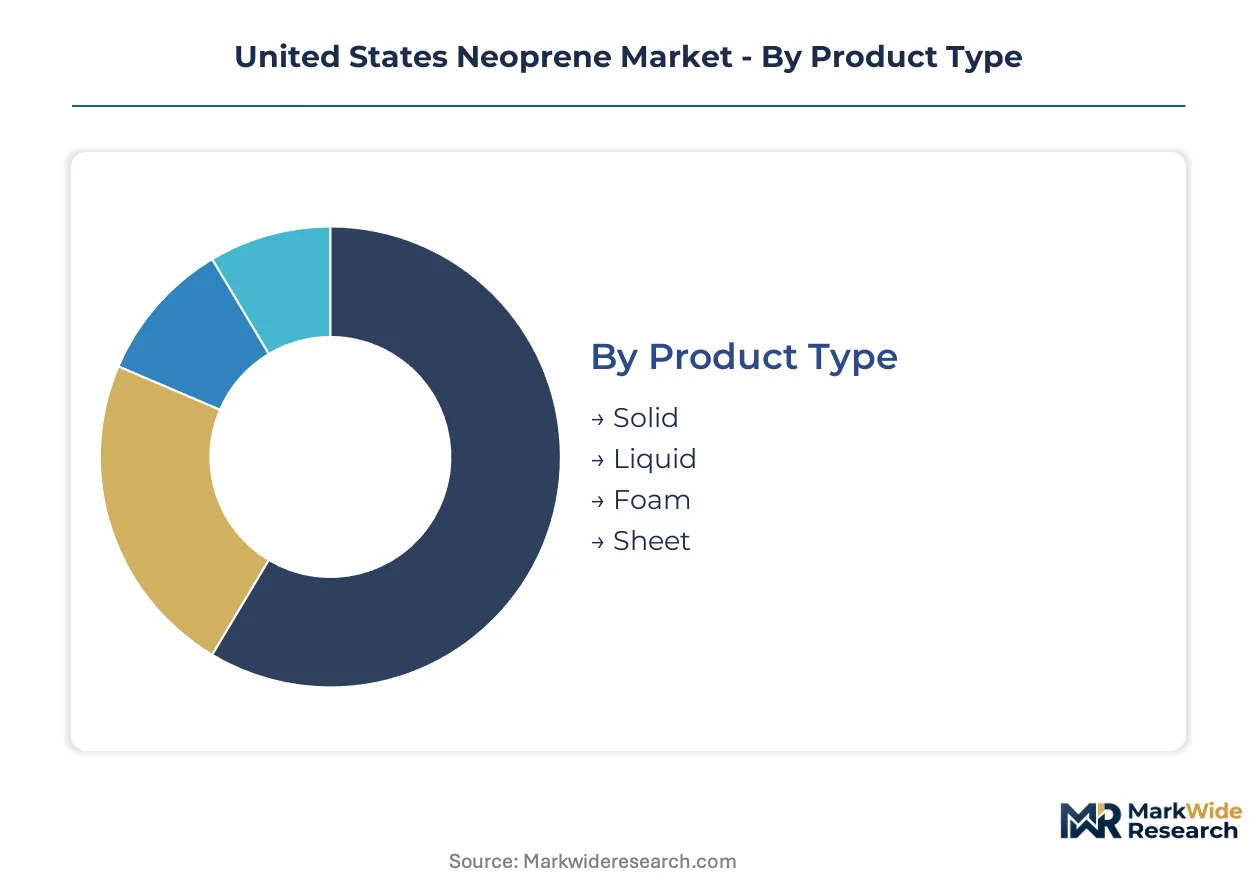
Neoprene segmentation in the United States reflects divergent supply chain logics across product forms and end-use specifications. Each category channels distinct technical requirements, regulatory pressures, and customer procurement behaviors that compounders must navigate.
Product Type:
Solid and liquid grades dominate domestic consumption, while foam neoprene serves export-oriented specialty equipment manufacturers. Gulf Coast compounders concentrate production of high-volume solid grades, whereas coastal California facilities specialize in liquid coating formulations for infrastructure rehabilitation.
- Solid:Dense rubber compounds with specific gravity of 1.23-1.25 form the backbone of gasket and hose fabrication. Michigan and Ohio automotive clusters pull solid neoprene for EV thermal management seals, constrained by ASTM D2000 certification timelines that extend qualification cycles.
- Liquid:Spray-applied coating systems with rapid cure chemistry are displacing sheet-and-adhesive waterproofing in federal bridge rehabilitation programs. State transportation departments in California and New York specify liquid membranes for deck protection, compressing installation schedules from weeks to days.
- Foam:Closed-cell expanded rubber commands premium positioning in wetsuit and protective equipment markets where compression set resistance differentiates suppliers.
- Sheet:Calendered stock for die-cut fabrication serves industrial maintenance markets with standardized dimensional tolerances.
Solid neoprene holds the largest share; momentum sits with liquid formulations.
Application:
Automotive electrification is restructuring formulation priorities across all product grades, while construction applications concentrate in federally funded infrastructure corridors. Sports equipment demand clusters in coastal manufacturing zones serving export markets.
- Automotive:Battery thermal management systems require upgraded sealing performance with operating temperature tolerance from -35°C to 100°C. Tier 1 gasket fabricators in Michigan and Ohio consolidate qualified compounder lists to three-to-five approved sources, demanding ISO 14001 certification alongside ASTM compliance.
- Construction:Spray-applied liquid neoprene membranes for bridge deck waterproofing represent the steepest expansion trajectory, driven by federal maintenance program specifications.
- Sports:Wetsuit and protective equipment manufacturers specify foam neoprene with compression set recovery metrics that exceed industrial grades.
- Consumer Goods:Laptop sleeves and lifestyle accessories pull lower-specification sheet stock through retail distribution channels.
Automotive applications anchor volume; construction specifications are gaining share fastest.
End User:
Procurement consolidation among OEMs is compressing supplier counts, while distributors adopt digital specification-matching platforms. Retail channel fragmentation persists in consumer goods segments.
- Manufacturers:Direct compounder relationships dominate automotive and industrial gasket fabrication, with specification-driven consolidation reducing qualified supplier pools.
- OEMs:Thermal management system suppliers demand backward integration assurance from compounders to mitigate chloroprene monomer supply volatility.
- Distributors:Regional players deploy algorithmic inventory platforms that reduce compounder-to-fabricator search friction and compress order cycles.
- Retailers:Consumer goods channels source standardized sheet stock through fragmented wholesale networks with limited technical specification requirements.
Manufacturers command the dominant procurement volume; distributor platform adoption is climbing fastest.
Form:
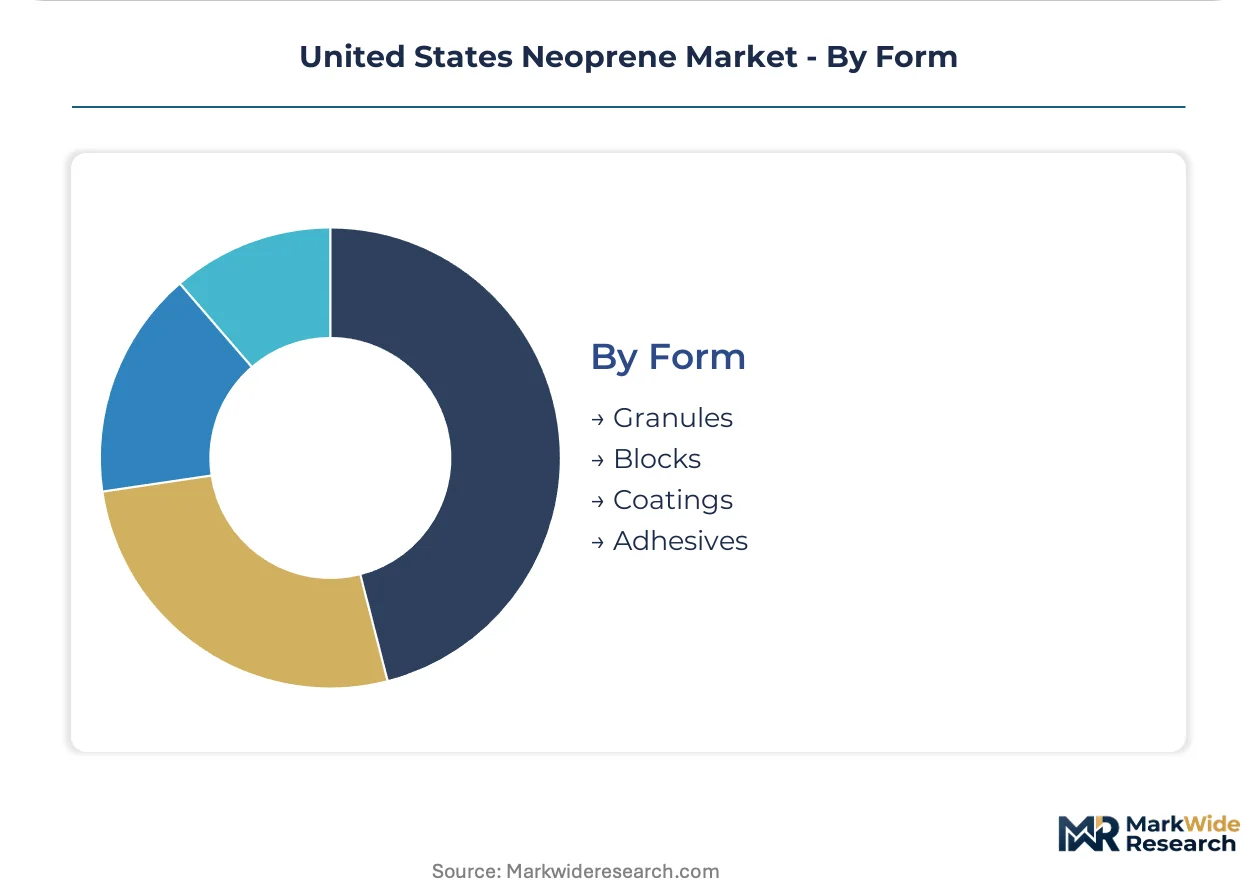
Granules and blocks serve high-volume industrial compounding, while coatings and adhesives concentrate in specialized application equipment markets. Form selection correlates with customer technical capability and installation infrastructure investment.
- Granules:Bulk polymer feedstock for custom compounding operations at regional facilities serving automotive and industrial markets.
- Blocks:Raw polymer slabs for in-house processing at integrated fabricators with calendering and extrusion capabilities.
- Coatings:Pre-formulated spray systems requiring specialized application equipment, concentrated in infrastructure rehabilitation contractors.
- Adhesives:Solvent-based and water-borne contact cements for bonding operations in marine and construction fabrication.
Blocks retain the largest consumption base; coatings are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chloroprene monomer production clusters along the Gulf Coast petrochemical corridor, with compounding operations dispersing to serve regional manufacturing demand. This geographic configuration creates hurricane exposure vulnerability while positioning domestic suppliers to meet tightening EPA emission standards. State-level procurement rules and infrastructure investment programs are redirecting material flows toward electrification and rehabilitation end-uses.
Gulf Coast Petrochemical Corridor
Louisiana and Texas host integrated chloroprene production facilities supplying domestic compounders with raw monomer feedstock. EPA NESHAP enforcement is accelerating capital deployment toward closed-loop vapor recovery systems ahead of implementation deadlines. Hurricane disruption risk concentrates supply vulnerability in this corridor, compelling buyers to secure alternative sourcing arrangements.
Midwest Automotive Belt
Michigan and Ohio thermal management system suppliers are consolidating qualified neoprene compounder lists to three-to-five approved sources for EV battery sealing applications. ASTM D2000 certification requirements extend automotive qualification timelines, delaying new compound approvals. Tier 1 gasket fabricators in this cluster demand ISO 14001 certification alongside material compliance documentation.
California Infrastructure Corridor
State transportation departments specify spray-applied liquid neoprene membranes for bridge deck waterproofing under federal rehabilitation programs. California procurement rules favor post-industrial neoprene reclaim in public works, rewarding compounders with closed-loop processing capabilities. Coastal coating facilities specialize in rapid-cure formulations that compress installation schedules from weeks to days.
New York Metro Industrial Zone
Federal tunnel maintenance programs in the Northeast corridor pull liquid neoprene coating volumes for waterproofing membrane applications. New York State procurement mandates align with California recycled content preferences, creating bicoastal demand for reclaim-capable suppliers. Regional distributors deploy algorithmic inventory platforms that reduce compounder-to-fabricator search friction.
Southeast Manufacturing Expansion
Georgia and Tennessee industrial hose fabricators source solid neoprene sheet stock for gasket and sealing applications serving regional OEMs. OSHA workplace exposure limits for chloroprene shape handling protocols and personal protective equipment requirements throughout this value chain. Chattanooga-area production bases supply specialty elastomers for industrial applications with upgraded performance specifications.
United States Neoprene Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the United States neoprene supply base. Integrated producers with captive chloroprene monomer supply anchor the cost-competitive tier, while specialty compounders command premium positioning through formulation expertise and certification depth. Three archetypes dominate: Gulf Coast integrated producers, regional custom compounders, and import-dependent distributors. Competitive intensity concentrates in M&A activity targeting compounding capacity and strategic partnerships linking monomer supply to fabrication demand.
Among German-origin integrated producers, Covestro and Lanxess exemplify technology leadership through advanced polymerization capabilities. ARLANXEO occupies a position within the backward-integrated tier, representing captive supply chain architecture that insulates against raw material volatility. These three entities anchor the premium-grade segment where ozone resistance and thermal tolerance specifications differentiate supplier positioning.
| Leading Market Players |
|---|
| 3M |
| BRP Manufacturing |
| Covestro |
| Denka Company Limited |
| Lanxess |
| ARLANXEO |
| Pidilite Industries |
| Resonac Holdings Corporation |
| SEDO Chemicals Neoprene GmbH |
| Others |
Cost & Logistics Intelligence
Liquid neoprene coating systems displacing conventional sheet-and-adhesive waterproofing simultaneously redraw supply geography toward coastal formulation facilities and compress pricing premiums for installation speed. This substitution dynamic concentrates high-margin production in California and New York corridor facilities while eroding value capture at inland sheet stock compounders serving legacy construction specifications.
Pricing Analysis
EPA NESHAP dictates the pricing tier structure across the United States neoprene market, separating integrated Gulf Coast producers with captive chloroprene supply from merchant-dependent compounders absorbing compliance capital costs. Pricing stratifies across ASTM D2000-certified automotive grades, ISO 14001-compliant industrial specifications, and uncertified commodity sheet stock. Cost compression in standard-grade solid neoprene is intensifying because Louisiana and Texas facility upgrades pass through to non-integrated buyers. Tier 1 automotive gasket fabricators exhibit lowest price sensitivity due to qualification lock-in, while construction contractors purchasing liquid coatings for bridge rehabilitation programs drive hardest bargain on volume tenders.
Supply Chain Analysis
The United States and Japan anchor chloroprene monomer production, with domestic Gulf Coast facilities feeding regional compounders and Japanese supply serving specialty foam neoprene manufacturers. Raw material flows draw from petroleum feedstock streams, chlorine supply chains, and emulsion polymerization catalyst systems. Single-source vulnerability concentrates in the Louisiana-Texas corridor where hurricane disruption risk threatens monomer availability during peak demand windows. Distribution runs through direct compounder relationships with automotive Tier 1 fabricators, supplemented by regional distributor platforms deploying specification-matching algorithms for industrial maintenance customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States neoprene market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantages. EPA emission standards and ASTM certification requirements generate switching costs that protect qualified incumbents from price-driven disruption.
For Market Incumbents: Shield market position through backward integration into chloroprene monomer supply and accelerated certification investment ahead of 2026 EPA implementation deadlines. Fluoroelastomer substitution in aerospace thermal applications threatens premium-grade margins; counter by deepening captive supply assurance for EV battery thermal management customers demanding supply continuity guarantees.
For New Entrants and Emerging Players: Lead with recycled-content neoprene reclaim capabilities targeting California and New York public procurement mandates as the most penetrable entry vector. Closed-loop processing infrastructure for post-industrial scrap recovery offers differentiated positioning against virgin-compound incumbents. Pursue toll coating service partnerships with infrastructure rehabilitation contractors lacking in-house liquid application expertise.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compounders with integrated monomer supply and coastal liquid formulation assets. Long-term viability over the next decade hinges on electrification-driven demand durability and EPA compliance cost absorption capacity. Monitor Atlantic Coast offshore wind cable sealing contract awards as inflection signal for specialty-grade demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroprene Monomer | Captive supply insulates against Gulf Coast hurricane disruption and raw material price volatility. |
| Liquid Neoprene Coating Capacity Expansion | California and New York infrastructure rehabilitation specifications accelerate spray-applied membrane demand. |
| ASTM D2000 Certification Investment | Automotive Tier 1 consolidation to three-to-five approved sources locks out non-certified competitors. |
| Closed-Loop Reclaim Processing Capability | California and New York recycled content mandates favor compounders with post-industrial scrap recovery. |
| Digital Specification-Matching Platform Deployment | Regional distributors compress compounder-to-fabricator search friction and accelerate order cycles. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with plant managers at chloroprene production facilities, procurement leads at automotive Tier 1 gasket fabricators, and technical R&D directors at regional compounders; and secondary validation against EPA emission filings, OSHA exposure limit documentation, ASTM standard revision records, and customs trade data for chloroprene monomer imports. Bottom-up volume modeling triangulated against top-down demand aggregation across automotive, construction, and industrial end-use segments.
Across the analysis window, forecasts incorporate grade tier differentiation between solid, liquid, and foam product forms; end-use industry segmentation spanning automotive electrification, infrastructure rehabilitation, and protective equipment; and regional production hub clustering along Gulf Coast, Midwest automotive belt, and coastal infrastructure corridors. CAGRs derived from historical elasticity analysis applied to electrification-driven thermal management demand curves and federal bridge maintenance program expenditure patterns.
Forecasts assume regulatory continuity in EPA NESHAP enforcement and OSHA permissible exposure limit regimes; material policy shifts in emission standards or workplace safety thresholds would require re-modeling. Recalibration cycles align with material shifts in EV battery thermal management specification releases and federal infrastructure appropriation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Alginate Films Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Barium Borate Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Polyetherimide (PEI) Market