
 Battery Separator Materials Market | 2026-2036
Battery Separator Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Separator Materials Market Outlook
Modular separator architectures that integrate coating layers with base films is restructuring procurement patterns across cell manufacturers. Asahi Kasei Corporation leverages its wet-process polyolefin expertise to anchor supply relationships with tier-one battery makers. SK IE Technology competes through captive integration with parent cell production, while Toray Industries sustains leadership in thin-film uniformity for high-energy-density applications.
Battery separator materials are thin, permeable membranes—typically 10–30 micrometers thick—composed of polyethylene, polypropylene, or ceramic composites that electrically isolate anode and cathode while permitting ion transport in electrochemical cells. Their primary purpose is to prevent internal short circuits and thermal propagation in lithium-ion systems. Polyethylene dominates volume in automotive-grade separators due to its shutdown safety mechanism above melting threshold. Ceramic coating is capturing margin pools as cell makers demand puncture resistance above 300 grams for next-generation packs. Composite structures are gaining share in energy storage applications where cycle life requirements exceed consumer electronics standards.
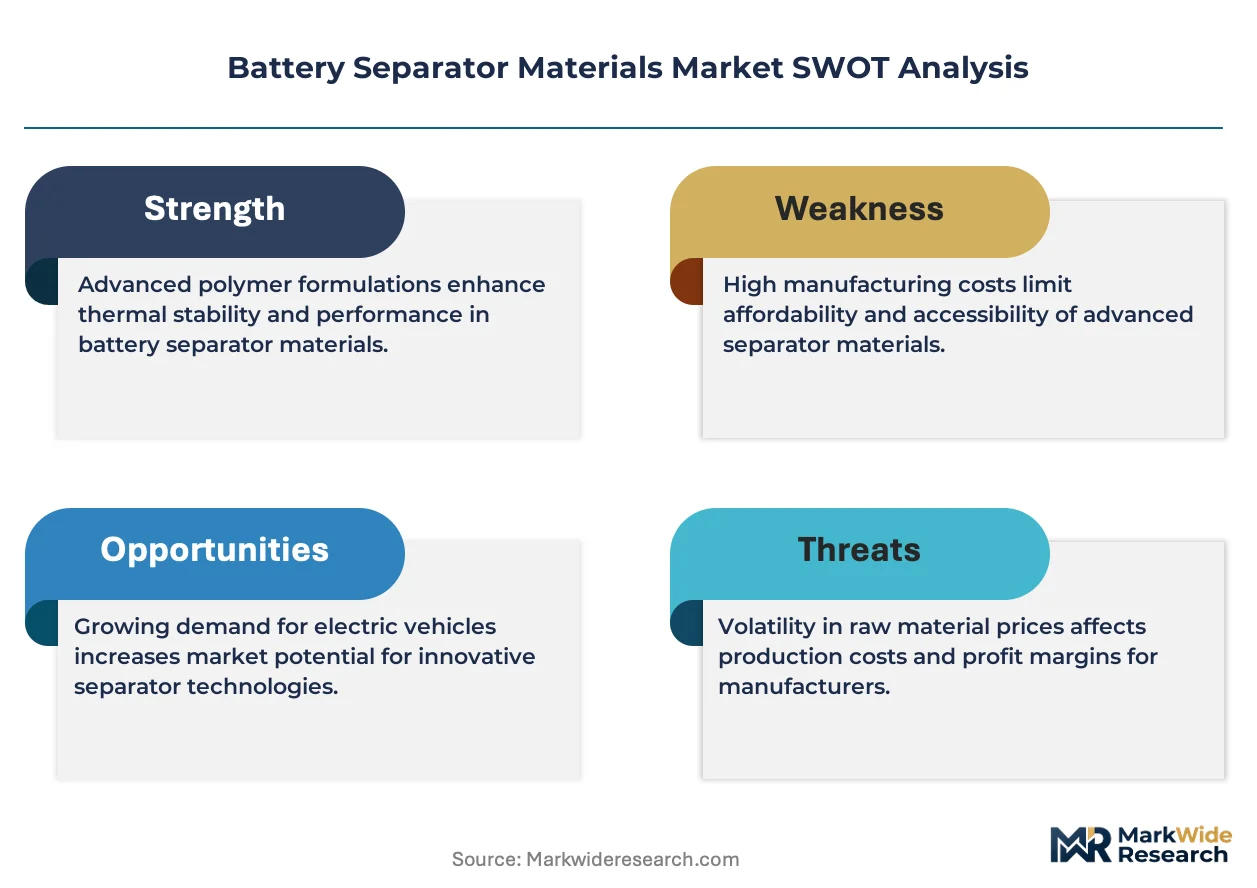
FDA guidelines for medical device batteries, EPA frameworks on fluoropolymer emissions, and China's GB standards under SAMR oversight collectively elevate barrier properties and chemical purity requirements for separator qualification. The EU's F-Gas Regulation restricts perfluorinated compound use in manufacturing processes, pushing converters toward aqueous coating chemistries. Stakeholders must monitor how solid-state battery timelines affect separator material specifications and whether dry-process technologies displace solvent-intensive production before capital commitments lock in.
Market Dynamics
Ceramic-coated separator architectures are forcing cell manufacturers to requalify entire supply chains as thermal runaway standards tighten across automotive OEM specifications. This structural shift favors converters with integrated coating capabilities and punishes standalone base-film suppliers.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on perfluorinated compounds in manufacturing processes are accelerating converter migration toward aqueous coating chemistries, opening qualification windows for new material entrants.
- Electric vehicle OEM thermal runaway mandates:Automotive-grade battery pack designs now require puncture resistance thresholds above 300 grams, pulling ceramic composite separators into standard specifications.
- South Korean manufacturing clusters:Dense concentrations of cell production around Seoul and Gwangju create localized demand pull for just-in-time separator delivery with sub-48-hour lead times.
Market Restraints
- Polyolefin resin price volatility:Feedstock costs for polyethylene and polypropylene fluctuate with crude oil indices, compressing converter margins during upstream spikes.
- East Asian supply concentration:Wet-process base film production concentrates in Japan and South Korea, creating single-source vulnerability for European and North American cell makers.
- Solid-state battery substitution timeline:Next-generation solid electrolyte designs threaten to eliminate porous separator requirements entirely, freezing long-term capital commitment decisions.
Strategic Opportunities
- Energy storage system cycle life requirements:Grid-scale battery installations demand separator durability exceeding 8,000 cycles, creating premium margin pools unavailable in consumer electronics applications.
- China NMPA battery safety enforcement:Stricter domestic certification protocols for automotive cells are disqualifying low-cost import separators, opening share for qualified local and joint-venture suppliers.
- Dry-process manufacturing convergence:Solvent-free production methods paired with electrospinning nanofiber layers are enabling thinner films with equivalent mechanical properties, reducing material intensity per cell.
Industry Challenges
- Coating uniformity talent scarcity:Process engineers with expertise in sub-micron ceramic layer deposition on polymer substrates command premium compensation and limited geographic mobility.
- Automotive qualification timeline compression:Cell makers now demand separator validation in 12-18 month windows versus historical 36-month cycles, straining R&D throughput.
- Cross-border IP licensing friction:Patent thickets around shutdown-layer formulations and ceramic binder chemistries complicate technology transfer between regional production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Separator Materials Market |
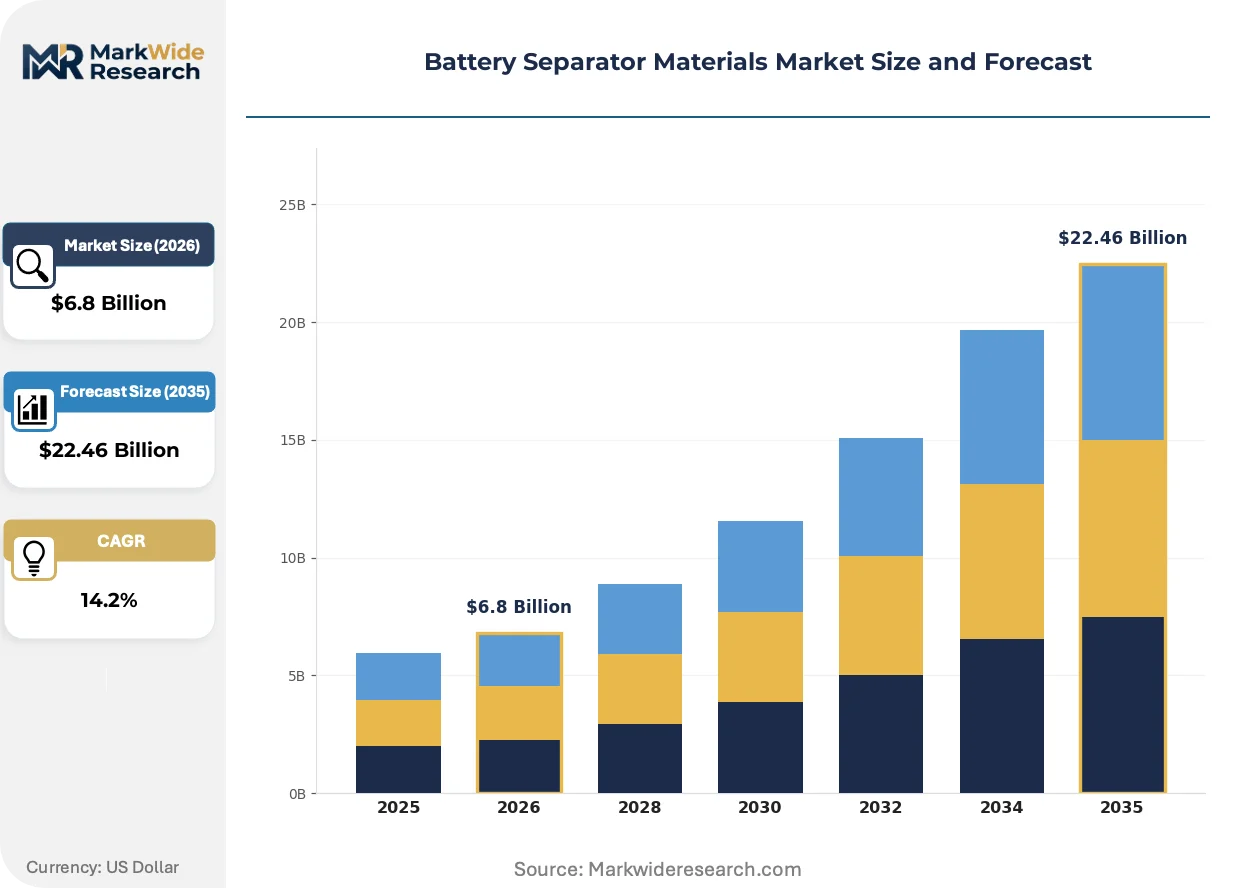
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ceramic, Composite Technology: Micro Porous, Non-Woven, Coating, Membrane End User: Consumer Electronics, Automotive, Energy Storage, Industrial Application: Li-ion Batteries, Lead-acid Batteries, NiMH Batteries, Others |
| Companies Covered | Asahi Kasei Corporation, ENTEK International, Toray Industries, SK IE Technology, UBE Corporation, W-Scope Corporation, Shanghai Energy New Materials Technology, Sumitomo Chemical, Freudenberg Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Separator Materials Market Strategic Shifts
Separator material innovation is bifurcating between incremental thickness reduction for energy density gains and radical architecture changes for safety performance. Both trajectories demand new capital equipment and retrained workforces.
Multilayer ceramic-polymer composite structures are expanding into high-nickel cathode cell designs where mechanical integrity under thermal stress determines pack safety margins. Korean and Chinese cell manufacturers are adopting these architectures fastest, compressing qualification timelines for conventional single-layer polyethylene films in premium automotive segments.
China's GB standards under SAMR oversight are mandating separator shutdown temperature windows and puncture resistance testing protocols that exceed previous industry norms. Domestic converters must retool coating lines to meet these specifications, while foreign suppliers face extended certification delays that advantage local production.
Automotive OEMs are consolidating separator procurement through direct long-term supply agreements with coating specialists, bypassing traditional distributor channels. Tier-one battery makers in Germany and the United States now negotiate base film and coating as separate contracts, fragmenting what were integrated supplier relationships and forcing converters to choose specialization strategies.
Battery Separator Materials Market Segmentation
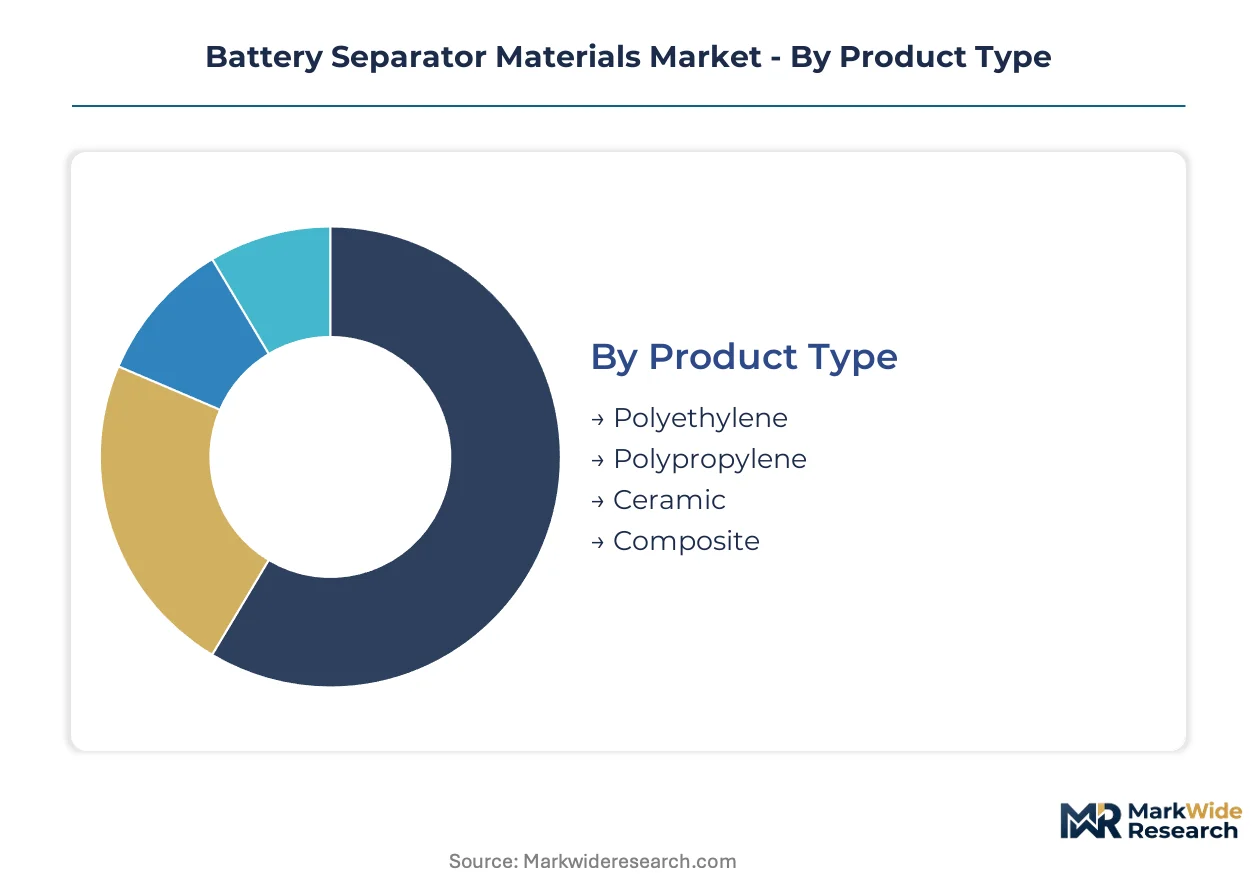
Separator material segmentation determines capital allocation across wet-process lines, coating equipment, and resin procurement. Cell manufacturers configure supply contracts around these categories, with product type and technology choices locking in decade-long equipment commitments.
Product Type:
Capital intensity varies sharply by material chemistry, with ceramic composite lines demanding 3-4x the coating infrastructure of base polyolefin films.
- Polyethylene:Semi-crystalline thermoplastic separators dominate automotive-grade volumes due to the 130°C shutdown safety mechanism that melts pores to halt ion flow during thermal events. Korean cell manufacturers around Seoul and Gwangju specify PE substrates for just-in-time delivery contracts with sub-48-hour lead times.
- Ceramic:Alumina or silica-coated architectures achieve puncture resistance above 300 grams for next-generation high-nickel cathode packs. China's NMPA battery safety regulations and EU thermal runaway mandates are pulling ceramic composites into standard automotive specifications, requalifying entire supply chains.
- Polypropylene:Higher melting threshold than PE suits industrial applications with extended temperature exposure, though lower ionic conductivity limits penetration in premium automotive cells.
- Composite:Multilayer polymer-ceramic hybrids address grid-scale energy storage cycle life requirements exceeding 8,000 cycles, opening premium margin pools unavailable in consumer electronics.
Polyethylene absorbs the bulk of installed capacity; ceramic is expanding most quickly.
Technology:
Process technology segmentation maps directly to workforce specialization and equipment supplier relationships, with coating expertise commanding premium talent compensation.
- Micro Porous:Stretching and extraction processes create controlled pore structures in 10-30 micrometer films. Japanese wet-process specialists anchor supply relationships with tier-one battery makers through uniformity guarantees for high-energy-density applications.
- Coating:Sub-micron ceramic layer deposition on polymer substrates requires process engineers with limited geographic mobility. The EU's F-Gas Regulation restricts perfluorinated compound use, accelerating converter migration toward aqueous coating chemistries.
- Non-Woven:Electrospun nanofiber layers enable thinner films with equivalent mechanical properties, reducing material intensity per cell in dry-process manufacturing convergence.
- Membrane:Standalone ceramic or polymeric membranes serve niche medical and aerospace applications where FDA guidelines for device batteries elevate chemical purity requirements.
Micro porous technology commands the largest installed base; coating is climbing the fastest as automotive qualification timelines compress.
End User:
End-user segmentation reveals diverging performance requirements, with automotive and energy storage segments demanding durability standards that consumer electronics never required.
- Automotive:OEM thermal runaway mandates now require puncture resistance thresholds above 300 grams, disqualifying conventional single-layer films in premium segments. German and US tier-one battery makers negotiate base film and coating as separate contracts, fragmenting integrated supplier relationships.
- Energy Storage:Grid-scale installations demand separator durability exceeding 8,000 cycles, creating qualification barriers for converters optimized for consumer electronics volumes.
- Consumer Electronics:Thin-film uniformity for smartphone and laptop batteries prioritizes energy density over cycle life, with shorter qualification windows than automotive applications.
- Industrial:Forklift, marine, and stationary power applications tolerate thicker separators with lower cost sensitivity than mobility applications.
Automotive end-use absorbs dominant capital deployment; energy storage is gaining share fastest as grid installations accelerate.
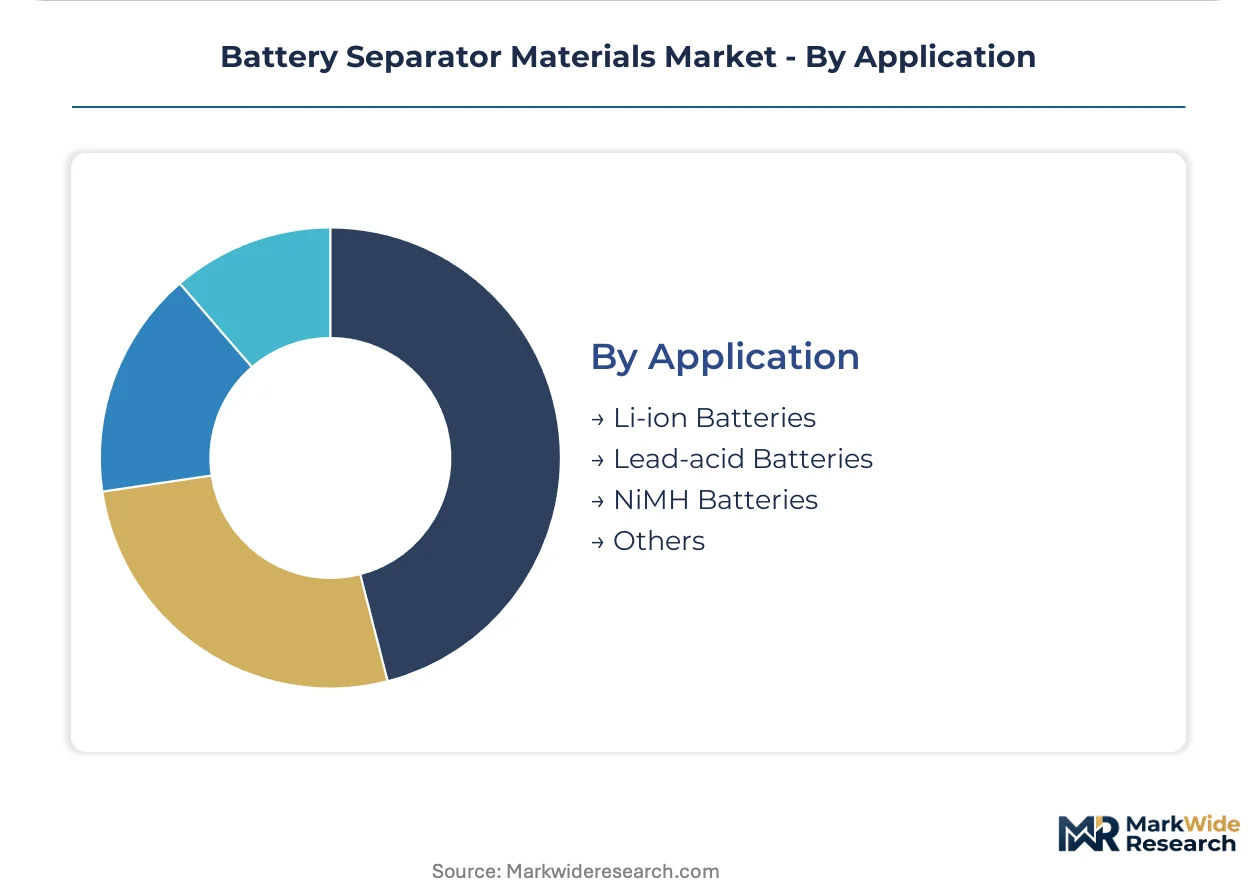
Application:
Application chemistry determines separator electrochemical stability requirements, with lithium-ion architectures imposing the most stringent purity and consistency standards.
- Li-ion Batteries:Polyolefin separators with ceramic coatings electrically isolate anode and cathode while permitting lithium-ion transport in high-voltage cells. China's GB standards under SAMR oversight mandate shutdown temperature windows and puncture resistance testing that exceed previous industry norms.
- Lead-acid Batteries:Absorptive glass mat separators dominate this mature chemistry, with minimal technology overlap to lithium-ion supply chains.
- NiMH Batteries:Hydrogen-absorbing alloy cells in hybrid vehicles use polypropylene non-woven separators with distinct wetting requirements from lithium systems.
- Others:Sodium-ion and solid-state prototype cells are testing separator architectures that may eliminate porous membrane requirements entirely.
Li-ion applications anchor the overwhelming majority of separator R&D investment; solid-state substitution timelines remain the critical uncertainty for long-term capital commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Suzhou Industrial Park and South Korea's Songdo Free Economic Zone anchor separator manufacturing concentration through tax incentives and bonded logistics facilities. These zones pull wet-process base film production and ceramic coating operations into dense clusters serving just-in-time automotive supply chains.
China
Domestic cell manufacturers under NMPA battery safety regulations are disqualifying low-cost import separators, opening share for qualified local and joint-venture suppliers. GB standards under SAMR oversight mandate shutdown temperature windows and puncture resistance testing that exceed previous industry norms. The Yangtze River Delta around Shanghai hosts Shanghai Energy New Materials Technology and dense concentrations of coating line retooling for automotive qualification.
South Korea
Seoul and Gwangju manufacturing clusters create localized demand pull for just-in-time separator delivery with sub-48-hour lead times. MFDS pharmaceutical-grade purity standards for medical device batteries elevate barrier properties requirements for export-oriented production. SK IE Technology leverages captive integration with parent cell production to anchor supply relationships in the Seoul Capital Area.
Japan
METI industrial policy supports thin-film uniformity R&D for high-energy-density applications through targeted subsidies. JIS standards for battery materials enforce consistency thresholds that favor established wet-process specialists. Kansai region around Osaka concentrates Toray Industries and Asahi Kasei Corporation polymer film expertise serving tier-one battery makers.
Germany
EU F-Gas Regulation restricts perfluorinated compound use in manufacturing processes, pushing converters toward aqueous coating chemistries. KBA automotive certification timelines compress separator validation into 12-18 month windows versus historical 36-month cycles. Bavaria and Baden-Württemberg host tier-one battery maker negotiations that fragment base film and coating into separate procurement contracts.
United States
EPA frameworks on fluoropolymer emissions elevate chemical purity requirements for separator qualification in domestic production. NHTSA thermal runaway standards for electric vehicle packs pull ceramic composite separators into OEM specifications. Michigan and California manufacturing corridors concentrate energy storage system demand exceeding 8,000 cycle life requirements.
Battery Separator Materials Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across coating and base film segments. The market structures around three tiers: integrated chemical-materials conglomerates with captive polymer expertise, independent coating converters with ceramic deposition capabilities, and regional base film suppliers serving cost-sensitive segments. Strategic moves center on backward integration into resin production and technology licensing partnerships that bypass cross-border IP friction.
Within the integrated conglomerate tier, Asahi Kasei Corporation and Toray Industries exemplify Japanese wet-process specialists anchoring supply relationships through uniformity guarantees. SK IE Technology occupies a position representing Korean captive integration models where separator production aligns with parent cell manufacturing. These three companies collectively illustrate how geographic clustering around polymer expertise, coating infrastructure, and automotive proximity defines competitive positioning in qualification-intensive segments.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| ENTEK International |
| Toray Industries |
| SK IE Technology |
| UBE Corporation |
| W-Scope Corporation |
| Shanghai Energy New Materials Technology |
| Sumitomo Chemical |
| Freudenberg Performance Materials |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM thermal runaway mandates requiring puncture resistance above 300 grams are forcing cell manufacturers to requalify entire supply chains around ceramic-coated architectures, compressing converter margins and fragmenting what were integrated supplier relationships into separate base-film and coating procurement contracts.
Pricing Analysis
Sub-48-hour lead time requirements from Seoul and Gwangju manufacturing clusters command premium pricing over standard 7-14 day delivery windows. Three-tier pricing structure across automotive-grade ceramic composites, industrial polypropylene films, and consumer electronics polyethylene substrates reflects certification grade and volume scale differentiation. Cost compression in standard polyethylene tiers is intensifying because polyolefin resin feedstock fluctuates with crude oil indices. Energy storage system buyers exhibit highest price sensitivity due to project-financed procurement models, while automotive tier-one cell makers prioritize qualification speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with wet-process base film production concentrated in Japan and South Korea, creating qualification bottlenecks for European and North American cell manufacturers. Ceramic coating operations draw from alumina and silica feedstock anchored in Chinese and Australian mineral processing. Tariff exposure on polyolefin resins and ceramic precursors threatens margin stability across converter tiers. Distribution runs through direct long-term supply agreements with coating specialists, bypassing traditional distributor channels as automotive OEMs consolidate procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's NMPA battery safety regulations and the EU's F-Gas Regulation erect barrier-to-entry moats that reward qualified incumbents while disqualifying low-cost import competitors.
For Market Incumbents: Anchor supply relationships through captive coating infrastructure and wet-process uniformity guarantees as solid-state battery substitution timelines threaten porous separator demand. Defend margin position by accelerating aqueous chemistry migration ahead of EU F-Gas enforcement deadlines. Backward integration into polyolefin resin production reduces feedstock volatility exposure. For New Entrants and Emerging Players: Grid-scale energy storage system integrators represent the most penetrable buyer archetype given their 8,000-plus cycle life requirements and limited incumbent optimization. Target Chinese domestic qualification under SAMR GB standards where foreign suppliers face extended certification delays. Lead with dry-process manufacturing convergence and electrospun nanofiber layers as a solvent-free alternative narrative. For Investors and Strategic Acquirers: The window for entry favors coating specialists with integrated ceramic deposition capabilities and existing automotive qualification relationships. Acquisition candidates should demonstrate sub-18-month validation track records with tier-one cell makers. Monitor solid-state battery prototype announcements from major OEMs as the critical inflection signal for long-term porous separator demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating Chemistry Migration | EU F-Gas Regulation compliance opens qualification windows for new material entrants. |
| Dry-Process Manufacturing Scale-Up | Electrospinning nanofiber layers reduce material intensity per cell for energy storage applications. |
| Ceramic Coating Line Retrofit | NMPA puncture resistance mandates pull alumina-silica architectures into standard automotive specifications. |
| Long-Term Supply Agreement Restructuring | German and US tier-one battery makers now negotiate base film and coating as separate contracts. |
| Joint Venture with Regional Polymer Producer | East Asian supply concentration creates vulnerability for European and North American cell makers. |
Study Parameters
SEC 10-K filings, customs and trade databases, and industry association technical reports formed the secondary backbone of this analysis. Primary fieldwork encompassed interviews with separator coating line engineers, procurement leads at tier-one battery manufacturers, ceramic raw material suppliers, and automotive OEM platform engineers. Bottom-up triangulation across resin procurement volumes, coating line capacity announcements, and cell production forecasts was validated against top-down market sizing from polymer consumption patterns and equipment installation records.
Historical trendline analysis of wet-process and dry-process capacity additions informed the projection framework across the analysis window. Segmentation dimensions modeled include product type chemistry, coating technology tier, end-use application, and regional regulatory cluster. CAGRs were derived from equipment utilization rates and qualification timeline compression patterns. Forecast inputs incorporated NMPA enforcement trajectory and solid-state battery development announcements as demand-side scenario variables.
Revisions become necessary when solid-state battery commercialization timelines accelerate, when polyolefin resin price volatility exceeds historical bands, or when automotive qualification windows compress further. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Lip Seals Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Extruders Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
High Performance Random Packing Market
Industrial Materials
Fly Ash Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Wood Protein Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Metal Molds Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
United States Graphite Electrodes Market