
 Global Beeswax Market | 2026-2036
Global Beeswax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beeswax Market Intelligence
Buyer concentration among personal care manufacturers is rebalancing as artisan candle makers and specialty food producers fragment procurement volumes across smaller batch orders. Strahl and Pitsch leverages its century-old refining infrastructure to sustain premium-grade supply lines for cosmetic houses. Koster Keunen LLC anchors North American distribution through vertically controlled rendering and filtration operations. Dabur India Ltd. competes on Ayurvedic brand strength, locking in captive beeswax demand across skin-care and wellness portfolios.
Beeswax comprises esters, hydrocarbons, and free fatty acids secreted by worker honeybees, melting between 62°C and 65°C and functioning as a pliable, moisture-resistant barrier in formulated goods. Refined beeswax dominates value capture through pharmaceutical-grade certification, while yellow beeswax retains volume leadership in candle and polish applications where color tolerance is wider. Cosmetics applications generate the fastest expansion as clean-label mandates push formulators away from petroleum-derived emollients toward hive-sourced alternatives.
FDA food-contact rules and EU REACH registrations constrain which wax grades enter cross-border trade, forcing exporters to maintain dual certification streams. India's FSSAI and BIS standards add further compliance layers for edible-coating and Ayurvedic uses. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification costs.
Market Dynamics
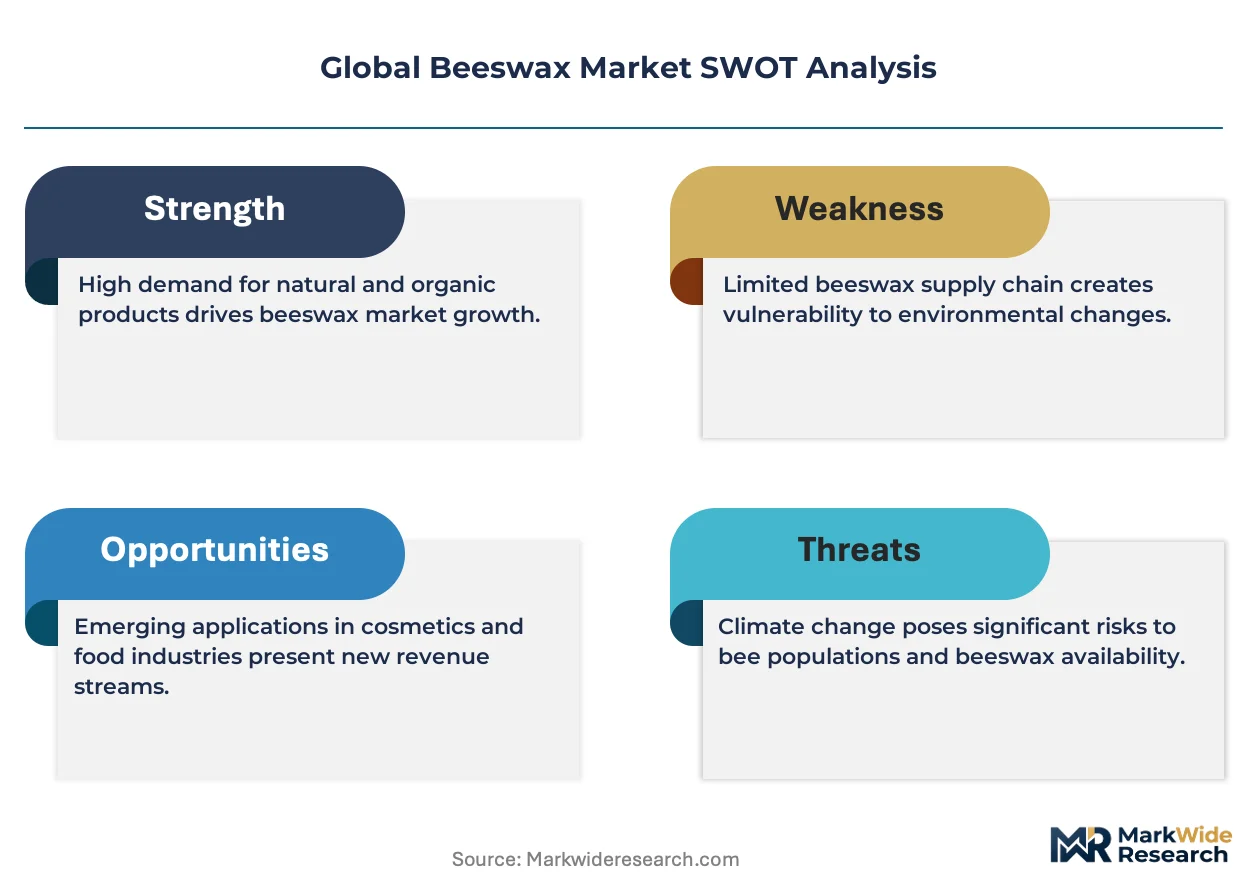
Clean-label mandates across personal care and food-contact applications are compressing demand timelines for synthetic emollients while elevating hive-sourced alternatives. This regulatory-inflected preference shift is forcing formulators to requalify supply chains around certified beeswax grades.
Growth Catalysts
- EU REACH Registration:Mandatory substance dossiers for beeswax importers create a compliance moat that filters out unqualified suppliers, concentrating volume among certified refiners serving cosmetic houses.
- Pharmaceutical Excipient Demand:Tablet coating and sustained-release formulations are absorbing larger beeswax volumes as CDSCO and FDA tighten purity benchmarks for oral dosage forms.
- India Ayurvedic Manufacturing:Domestic wellness brands are locking in captive beeswax offtake for medicated balms and massage oils, tightening spot-market availability.
Market Restraints
- Hive Supply Volatility:Colony collapse disorder and varroa mite infestations in North American apiaries constrain raw wax yields, forcing refiners to absorb input cost spikes or pass through to buyers.
- Paraffin Substitution:Petroleum-derived waxes retain price advantage in candle and polish segments where color tolerance and sensory properties permit synthetic alternatives.
- Dual Certification Burden:Exporters maintaining parallel FDA food-contact and EU REACH compliance streams face duplicated testing costs and extended qualification timelines.
Strategic Opportunities
- Brazil Pharmaceutical Growth:ANVISA's expanding GMP requirements for topical formulations create demand for pharmaceutical-grade beeswax that domestic South American supply cannot fully satisfy.
- Edible Coating Innovation:Fresh produce packers are adopting beeswax-based shelf-life extenders as retailers ban petroleum-derived coatings, opening food-grade volume channels.
- Carbon Accounting Integration:EU Green Deal disclosure rules position hive-sourced wax favorably against fossil-derived competitors in Scope 3 emissions calculations.
Industry Challenges
- Refiner Capacity Bottlenecks:Pharmaceutical-grade filtration and bleaching equipment requires 18-24 month installation cycles, constraining rapid supply response to demand spikes.
- Traceability System Integration:Batch-level hive-to-customer tracking demanded by cosmetic multinationals forces smallholder apiary networks into expensive digitization investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beeswax Market |
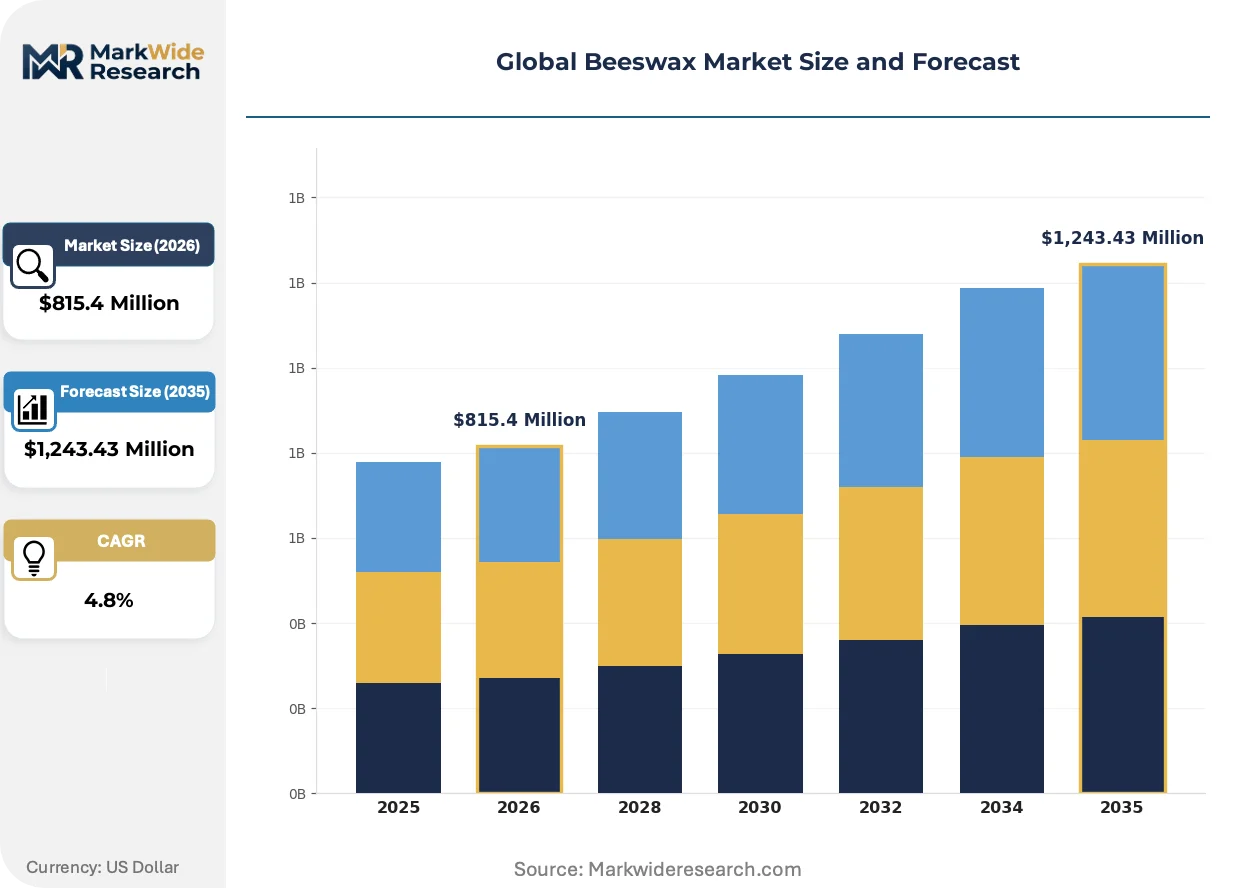
| Market Size in 2026 | $815.4 Million |
| Market Size in 2035 | $1,243.43 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Beeswax, Yellow Beeswax, White Beeswax, Bleached Beeswax Application: Candles, Cosmetics, Pharmaceuticals, Food Coating, Lubricants End User: Personal Care Manufacturers, Pharmaceutical Firms, Food Producers, Candle Makers Packaging Type: Blocks, Granules, Pastilles, Sheets |
| Companies Covered | New Zealand Beeswax Ltd., Paramold Manufacturing LLC, Strahl and Pitsch, Hilltop, Frank B Ross Co., Koster Keunen LLC, British Wax Refining Company, Dabur India Ltd., Roger A Reed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beeswax Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are converging to differentiate beeswax supply tiers. Refiners investing in advanced purification and blockchain traceability are capturing preferential offtake from premium personal care brands.
Supercritical CO2 extraction is expanding into beeswax refining operations, stripping pesticide residues and color bodies without thermal degradation. Cosmetic formulators in Germany and France are specifying CO2-refined grades for lip care and eye-area products. This technology is expanding into mid-tier refineries, compressing the premium commanded by traditional solvent-bleached alternatives.
EU CSRD sustainability reporting obligations now cover beeswax supply chains for large importers, mandating hive-level carbon footprint disclosure. French and Dutch cosmetic houses are demanding batch-specific apiary coordinates and forage-zone biodiversity metrics. Smallholder cooperatives in Tanzania and Kenya are responding by deploying satellite-linked hive monitoring to satisfy European buyer audit protocols.
Direct contracting between cosmetic brands and apiary cooperatives is displacing traditional commodity broker channels. L'Oréal and Unilever procurement teams are establishing multi-year offtake agreements with Ethiopian and Ugandan beekeeper associations, securing volume certainty while bypassing layered distributor markups. This pattern is most visible in East African supply zones where traceability infrastructure investments align with European disclosure mandates.
Global Beeswax Market Segmentation
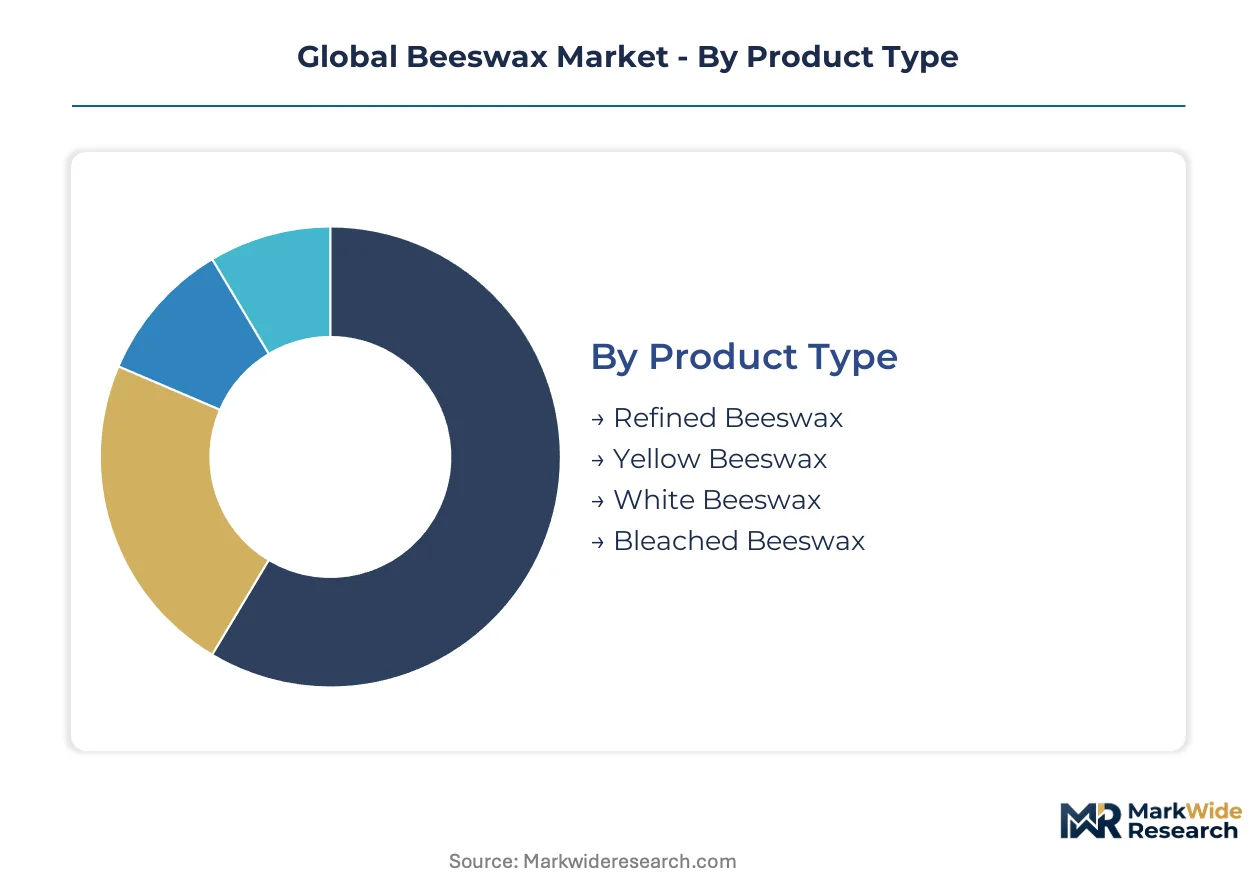
Beeswax market segmentation reflects divergent certification burdens across product grades and end-use channels. Regulatory thresholds for pharmaceutical excipients, food-contact coatings, and cosmetic formulations fragment supply tiers and reshape procurement strategies.
Product Type:
Certification requirements intensify steeply from crude yellow grades through pharmaceutical-refined tiers, with FDA food-contact and EU REACH registrations filtering supplier pools at each level.
- Refined Beeswax:Multi-stage filtration and bleaching yields pharmaceutical-grade purity meeting USP-NF and EP monographs. Tablet coating and sustained-release formulations in FDA-regulated facilities absorb this tier, with CDSCO and EMA inspections validating batch release.
- Yellow Beeswax:Retains natural color and aromatic compounds from hive debris, suitable for candle and polish applications where sensory tolerance is wider. Artisan makers in India and Turkey source this grade for Ayurvedic balms and traditional furniture finishes, bypassing costly decolorization.
- White Beeswax:Partially bleached through activated carbon or hydrogen peroxide treatment, bridging cosmetic and technical applications. Lip care formulators in France specify this grade for color consistency without full pharmaceutical processing overhead.
- Bleached Beeswax:Solvent or oxidant-treated to near-colorless state for premium cosmetic and pharmaceutical use. EU REACH dossier requirements and residual solvent testing constrain which refiners can supply German and Dutch cosmetic houses.
Yellow beeswax sits at the top of the volume ranking, with refined grades climbing the fastest as pharmaceutical excipient specifications tighten globally.
Application:
End-use channels separate by regulatory exposure, with food-contact and pharmaceutical applications demanding documented supply chain custody that candle and lubricant segments rarely require.
- Candles:Largest volume outlet absorbing yellow and partially refined grades where flame color and scent throw tolerate natural impurities. Hobbyist and liturgical segments in Italy and Mexico sustain steady offtake despite paraffin price competition.
- Cosmetics:Clean-label mandates across German and French formulators are compressing petroleum-derived emollient share. CO2-refined beeswax specified for eye-area and lip products commands premium positioning through residue-free certification.
- Pharmaceuticals:Sustained-release matrix and tablet polish applications require USP-NF or EP compliance with validated heavy metal and pesticide limits. ANVISA's expanding GMP requirements in Brazil are absorbing pharmaceutical-grade volumes that domestic South American supply cannot satisfy.
- Food Coating:Fresh produce shelf-life extension drives adoption as retailers phase out petroleum-derived coatings. FSSAI and FDA food-contact rules constrain which grades enter edible applications, favoring refiners with dual certification streams.
- Lubricants:Niche technical applications in leather conditioning and thread waxing absorb lower-grade material with minimal regulatory burden. Italian and Spanish specialty chemical blenders source this tier for industrial formulations.
Candle applications retain the widest volume base, while food coating gains share fastest as retail procurement bans on synthetic alternatives propagate.
End User:
Procurement scale and specification stringency vary sharply across buyer categories, with pharmaceutical and personal care segments driving certification investments that food and candle segments rarely justify.
- Personal Care Manufacturers:L'Oréal and Unilever procurement teams mandate batch-level hive traceability and carbon footprint disclosure under EU CSRD rules. Direct contracting with East African cooperatives is displacing traditional broker channels for premium volumes.
- Pharmaceutical Firms:Tablet coaters and topical formulators require validated excipient documentation with ICH Q3D elemental impurity compliance. CDSCO inspections in India and FDA audits in the US filter supplier pools to refiners with dedicated pharmaceutical production lines.
- Food Producers:Fresh produce packers and confectionery coaters adopt beeswax for barrier properties and clean-label positioning. FSSAI standards in India and FDA food-contact rules constrain grade selection, with edible-coating certification adding qualification layers.
- Candle Makers:Artisan and liturgical segments fragment procurement across smaller batch orders with minimal documentation requirements. Price sensitivity to paraffin alternatives shapes sourcing decisions more than certification status.
Personal care manufacturers anchor premium-grade demand, with pharmaceutical firms expanding most quickly as topical and oral dosage form specifications tighten.
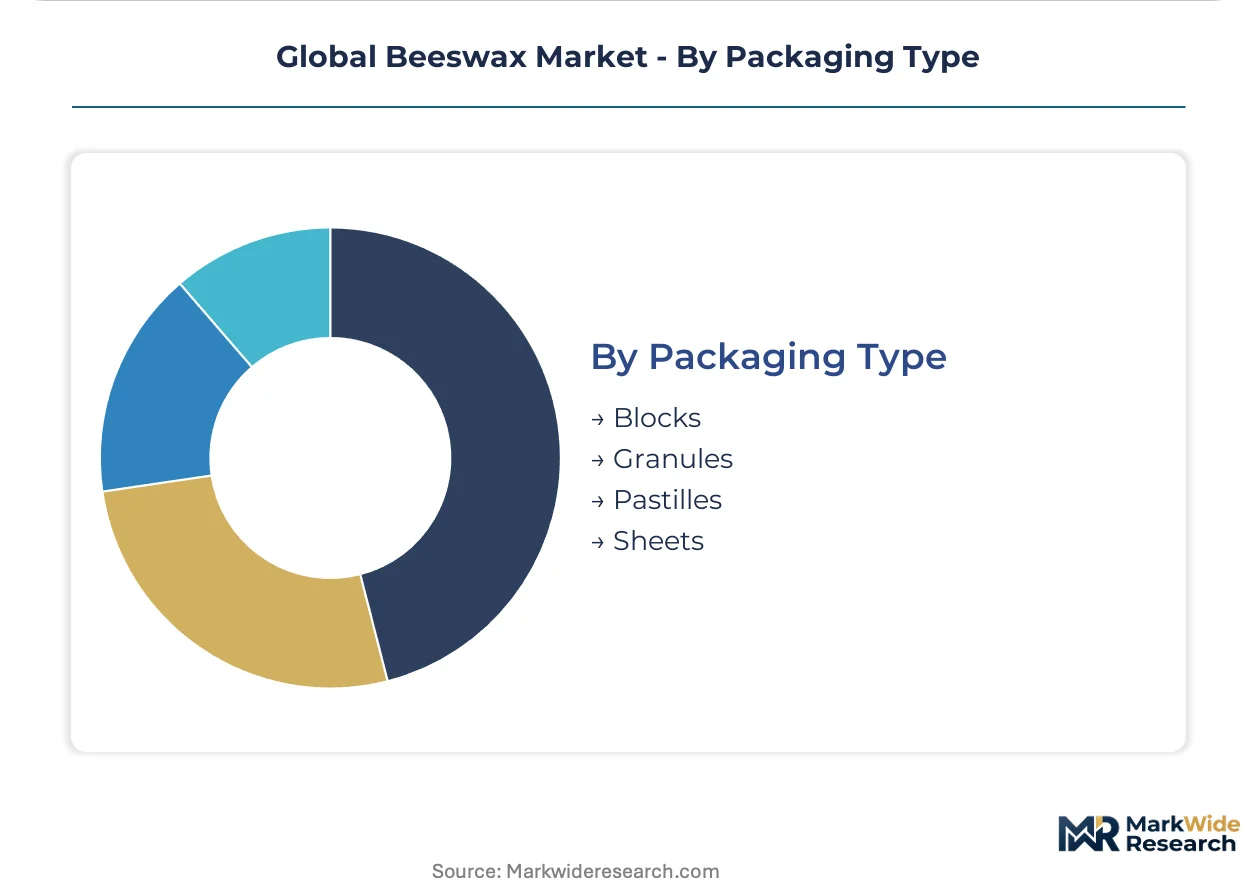
Packaging Type:
Physical form selection tracks downstream processing economics, with melting and handling characteristics dictating format preference across end-use segments.
- Blocks:Traditional bulk format for industrial melters and large-scale cosmetic compounders. Indian Ayurvedic manufacturers prefer blocks for batch-controlled heating in traditional processing equipment.
- Granules:Rapid-dissolve format reducing melt times for pharmaceutical and food coating operations. German and Swiss tablet coaters specify granules for continuous processing lines.
- Pastilles:Uniform pellet size enabling precise dosing in automated cosmetic and pharmaceutical formulation. French and Dutch personal care manufacturers favor pastilles for clean-room handling protocols.
- Sheets:Thin format for leather conditioning and specialty lubricant applications requiring surface application rather than bulk melting. Italian artisan leatherworkers source sheets for traditional finishing techniques.
Blocks dominate total volume movement, with pastilles gaining fastest as automated pharmaceutical and cosmetic processing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ayurvedic manufacturers consume beeswax volumes that rival German pharmaceutical formulators, yet certification burdens diverge sharply between CDSCO mandates and EU REACH dossier requirements.
United States
Pharmaceutical tablet coaters in New Jersey and Pennsylvania drive refined beeswax offtake for sustained-release formulations. FDA food-contact rules constrain edible-coating grades entering fresh produce supply chains. Colony collapse disorder in North Dakota and California apiaries forces refiners to source raw wax from Argentina and Brazil.
Germany
Cosmetic formulators in Hamburg and Frankfurt specify CO2-refined beeswax for lip care and eye-area products under EU Green Deal disclosure rules. ECHA REACH registrations filter supplier pools to refiners with validated heavy metal documentation. Bavarian candle makers sustain yellow beeswax demand for liturgical and artisan segments.
India
Ayurvedic brands in Maharashtra and Gujarat lock in captive beeswax offtake for medicated balms and massage oils. FSSAI standards for edible coatings add compliance layers beyond BIS technical specifications. Dabur India Ltd. anchors demand through vertically integrated sourcing across skin-care portfolios.
Brazil
ANVISA's expanding GMP requirements for topical formulations absorb pharmaceutical-grade beeswax that domestic South American supply cannot satisfy. São Paulo-based formulators import refined grades from US and European refiners. Minas Gerais apiaries supply raw yellow wax for domestic candle and polish applications.
France
Paris and Lyon cosmetic houses mandate batch-level hive traceability under EU CSRD sustainability reporting obligations. L'Oréal procurement teams establish direct contracting with Ethiopian and Ugandan beekeeper associations. Provence-based artisan candle makers fragment procurement across smaller batch orders with minimal documentation.
Global Beeswax Market Key Industry Players
North American producers anchor pharmaceutical-grade supply; European specialists hold cosmetic certification advantages. The vendor base fragments across century-old refiners, vertically integrated wellness conglomerates, and regional rendering operations. Three archetypes dominate: heritage refiners with dedicated pharmaceutical lines, Ayurvedic brands with captive apiary networks, and commodity brokers pivoting toward traceability services. Competitive moves concentrate on dual certification stream maintenance and direct cooperative contracting in East Africa.
Among heritage refiners, Strahl and Pitsch and Koster Keunen LLC exemplify the pharmaceutical-grade tier through century-old refining infrastructure and vertically controlled rendering operations. Dabur India Ltd. occupies a distinct position as a wellness conglomerate with captive beeswax demand locked across Ayurvedic portfolios. These three anchors illustrate how certification depth and downstream integration separate premium supply tiers from commodity yellow wax channels.
| Leading Market Players |
|---|
| New Zealand Beeswax Ltd. |
| Paramold Manufacturing LLC |
| Strahl and Pitsch |
| Hilltop |
| Frank B Ross Co. |
| Koster Keunen LLC |
| British Wax Refining Company |
| Dabur India Ltd. |
| Roger A Reed |
| Others |
Cost & Logistics Intelligence
Supercritical CO2 extraction adoption in German and French refineries is compressing processing cost differentials while concentrating premium-grade supply among technology-equipped facilities. This method simultaneously strips pesticide residues without thermal degradation and raises capital barriers that filter out smaller renderers, reshaping competitive economics across certification tiers.
Pricing Analysis
Capacity additions in East African apiary cooperatives are reshaping price floors for traceable yellow grades as direct contracting with cosmetic multinationals bypasses layered distributor markups. Three-tier pricing structure across pharmaceutical-refined, cosmetic-white, and technical-yellow levels separates certification-burdened tiers from commodity channels. Cost compression in candle-grade segments is intensifying because paraffin alternatives retain price advantage where sensory tolerance permits synthetic substitution. Artisan candle makers in Italy and Mexico exhibit highest price sensitivity, while pharmaceutical tablet coaters in New Jersey and Pennsylvania absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Freight cost volatility from East African hive clusters to European cosmetic houses is amplifying landed cost spreads against South American raw wax alternatives. Supply concentrates in India, Ethiopia, and Argentina, with Maharashtra Ayurvedic manufacturers and Minas Gerais apiaries feeding distinct downstream channels. Raw material flows draw from honeybee colony outputs tethered to agricultural pollination services, veterinary pharmaceutical inputs for varroa mite control, and seasonal forage availability. Single-source vulnerability runs through concentrated East African cooperative networks where satellite-linked traceability infrastructure remains underdeveloped. Distribution runs through vertically integrated wellness conglomerates for captive Ayurvedic demand, commodity brokers for candle-grade volume, and direct brand-cooperative contracts for premium cosmetic tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Indian FSSAI-compliant edible-coating grades and EU REACH-registered pharmaceutical tiers, with certification cost differentials creating margin expansion opportunities for dual-registered refiners.
For Market Incumbents: To counter hive supply volatility from colony collapse disorder in North American apiaries, Strahl and Pitsch and Koster Keunen LLC should deepen backward integration into South American raw wax sourcing while maintaining pharmaceutical-grade filtration capacity in existing facilities. Certification investment in dual FDA-EU compliance streams protects margin position against stranded inventory risk from regulatory divergence. For New Entrants and Emerging Players: Begin with CO2-refined cosmetic grades for French and German lip care formulators, where residue-free certification commands premium positioning and technology barriers filter incumbent competition. Target Brazilian ANVISA-expanding topical formulation segment as the most penetrable geography, leveraging domestic supply shortfall against import qualification timelines. Go-to-market angle should emphasize batch-level hive traceability aligned with EU CSRD disclosure mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier refiners with solvent-bleaching infrastructure facing technology obsolescence from CO2 extraction expansion. Long-term viability across the analysis window favors acquisition targets with established East African cooperative networks and existing EU REACH dossier coverage. Signal to watch is ANVISA GMP inspection backlog clearing for topical formulation facilities, which would trigger pharmaceutical-grade demand inflection in Brazil.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Wax Sourcing | Argentine and Brazilian apiary network control secures input cost stability against colony collapse volatility. |
| CO2 Extraction Technology Deployment | German cosmetic formulators specify residue-free grades for eye-area and lip product applications. |
| Dual Certification Stream Maintenance | Simultaneous FDA food-contact and EU REACH compliance prevents stranded inventory from regulatory divergence. |
| Direct Cooperative Contracting | Ethiopian and Ugandan beekeeper associations bypass layered distributor markups for L'Oréal procurement teams. |
| Blockchain Traceability Integration | French and Dutch cosmetic houses mandate batch-specific apiary coordinates under CSRD sustainability reporting. |
Research Approach
Coverage spans India, Germany, Brazil, France, and the United States, with primary inputs from each market cluster combined with secondary validation. Interviews with Ayurvedic manufacturing executives, pharmaceutical excipient procurement leads, cosmetic formulator R&D directors, and apiary cooperative managers were triangulated against customs trade data, CDSCO and FDA filing databases, ECHA REACH registration records, and BIS technical specification documents. Bottom-up volume estimates from hive-to-refiner flows were reconciled with top-down demand segmentation across application tiers.
Rate-of-change decomposition across the projection horizon isolates volume drivers by grade tier, end-use industry, packaging format, and regional regulatory cluster. CAGRs were derived from segmented demand elasticity modeling and input cost trajectory assumptions. Forecast inputs include colony health indices from agricultural extension services, cosmetic clean-label mandate propagation rates, and pharmaceutical excipient specification tightening timelines from FDA and EMA inspection data.
Several conditions sit outside the modeled scope, including extreme weather events affecting honeybee forage zones, abrupt regulatory harmonization between FDA and EU REACH frameworks, and breakthrough synthetic emollient technologies displacing hive-sourced alternatives. Forecasts reflect assumptions about certification cost stability and cooperative network digitization investment rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Halloysite Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Reflective Polarizing Films Market