
 Activated Carbon Bags Market | 2026-2036
Activated Carbon Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Carbon Bags Market Outlook
The gap between industrial bulk buyers and residential consumers is collapsing as home air purification becomes a priority purchase. Calgon Carbon Corporation leverages its captive supply of coconut shell activated carbon to sustain margin advantages across North American municipal contracts. Kuraray Co., Ltd. dominates specialty pitch-based carbon fiber precursors that anchor its position in high-performance filtration media. Jacobi Carbons AB operates a distributed manufacturing footprint that competes effectively on logistics costs in European water treatment applications.
Activated carbon bags are flexible containment systems fabricated from nonwoven or woven synthetic fabrics impregnated with granular or powdered activated carbon, typically rated for surface areas between 800 and 1,500 square meters per gram to maximize adsorption capacity for organic contaminants and volatile compounds. Filter bags lead the product type category due to established specification standards in HVAC and process air systems, while pouch bags represent the fastest-growing segment as e-commerce channels enable direct-to-consumer food preservation and odor control applications. The application dimension shows water filtration commanding the deepest margin pools because of long-term municipal contract structures, whereas air purification generates higher volume turnover through replacement cycle frequency in commercial buildings.
The EPA regulates activated carbon contactors under the Safe Drinking Water Act, while the FDA governs food-contact applications through 21 CFR compliance pathways, and OSHA sets permissible exposure limits for activated carbon dust in manufacturing facilities. These overlapping frameworks create compliance complexity that favors suppliers with certified quality management systems and documented supply chain traceability. Stakeholders must monitor evolving PFAS maximum contaminant level rules and the potential designation of additional chemicals as hazardous substances under CERCLA, as these changes will reshape specification requirements and procurement criteria across end-use segments.
Market Dynamics
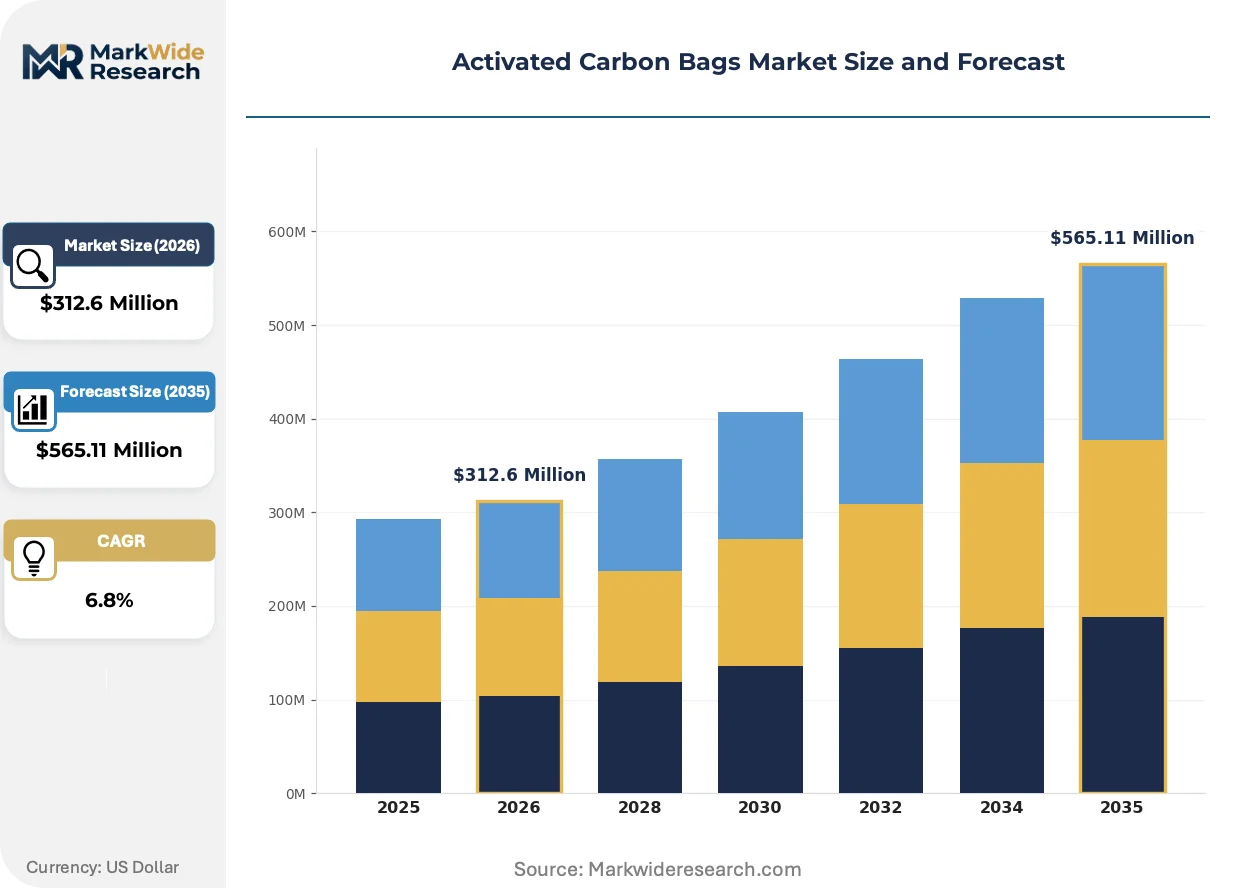
The Activated Carbon Bags Market is experiencing structural compression as municipal water utilities accelerate replacement cycles for aging filtration infrastructure while residential air purification demand converges on industrial specification standards. This dual-track demand evolution is collapsing traditional buyer segmentation and forcing manufacturers to reconfigure product portfolios for specification flexibility.
Growth Catalysts
- EPA PFAS MCL Rules:The EPA's finalized maximum contaminant levels for per- and polyfluoroalkyl substances mandate activated carbon filtration upgrades across thousands of public water systems, creating immediate procurement pull for high-adsorption bag systems.
- Coconut Shell Feedstock Abundance:Southeast Asian coconut processing clusters are expanding activated carbon precursor supply, reducing raw material cost volatility for manufacturers with backward integration into carbonization operations.
- HVAC Specification Convergence:Commercial building codes in California and New York are tightening volatile organic compound filtration requirements, driving specification upgrades from standard pleated filters to activated carbon-impregnated bag systems.
Market Restraints
- Bituminous Coal Supply Concentration:Powdered activated carbon production depends on specific Appalachian and Powder River Basin coal grades, exposing manufacturers to rail logistics bottlenecks and mining permit delays.
- Phosphoric Acid Activation Cost:Chemical activation processes for high-surface-area coconut shell carbon require food-grade phosphoric acid, subject to fertilizer industry demand spikes and export control fluctuations.
- Ion Exchange Resin Substitution:Selective anion exchange media are capturing PFAS remediation contracts in municipal pilot programs, threatening activated carbon's incumbent position in long-chain fluorochemical removal.
Strategic Opportunities
- India Municipal Water Infrastructure:The Jal Jeevan Mission's rural tap water scheme is creating first-time demand for decentralized filtration systems, opening direct procurement channels for bag-based contactors in arsenic and fluoride-affected districts.
- Electric Vehicle Battery Manufacturing:Lithium-ion cell production facilities require ultra-pure process water and solvent recovery systems, generating specification demand for pharmaceutical-grade activated carbon bags in cleanroom environments.
- EU Critical Raw Materials Act:The regulation's domestic sourcing incentives for strategic materials are accelerating European activated carbon reactivation facility investments, creating service-contract opportunities for bag-system lessors.
Industry Challenges
- Adsorption Capacity Verification:Third-party BET surface area testing backlog at ISO 17025 laboratories extends product qualification timelines by four to six months, delaying contract awards for municipal tenders.
- Legacy Contactor Retrofit Integration:Existing steel pressure vessel installations in 1970s-era water treatment plants require custom bag dimension engineering, complicating standard product rollout and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activated Carbon Bags Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Bags, Filter Bags, Pouch Bags, Pellet Bags End User: Automotive, Industrial, Residential, Commercial Application: Air Purification, Water Filtration, Odor Removal, Food Preservation Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Calgon Carbon Corporation, Cabot Corporation, Kuraray Co., Ltd., Jacobi Carbons AB, Haycarb PLC, Osaka Gas Chemicals Co., Ltd., Donau Carbon GmbH, Ingevity Corporation, CPL Activated Carbons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Carbon Bags Market Strategic Shifts
Material science advances and regulatory precision are reshaping competitive differentiation in activated carbon bag systems. Manufacturers are racing to develop application-specific surface chemistries while digital traceability requirements transform supply chain documentation.
Impregnated activated carbon formulations is fragmenting the traditional granular carbon market as specialized chemistries target narrow contaminant classes. Municipal utilities in the Great Lakes region are piloting silver-impregnated and potassium iodide-doped bag systems for combined microbial and radiological protection. This technology is fragmenting procurement specifications away from universal high-iodine-number standards toward application-optimized performance tiers.
REACH Annex XVII restrictions on persistent organic pollutants are tightening activated carbon waste classification and reactivation service requirements across European manufacturing zones. Industrial users in Germany's Rhine-Ruhr chemical corridor face mandatory spent carbon manifesting and thermal reactivation proof documentation. Food-contact bag suppliers are responding by securing EMAS-registered reactivation partnerships to maintain circular economy claims.
Direct-to-specification procurement is compressing distributor margins as large municipal utilities establish technical qualification teams and issue performance-based tenders. Engineering firms in the southeastern United States are consolidating vendor pools to three approved manufacturers per carbon type, bypassing traditional MRO distribution channels. This concentration is most visible in Florida's consolidated water utility procurement cooperatives, where multi-year framework agreements now lock in volume commitments with technical audit clauses.
Activated Carbon Bags Market Segmentation
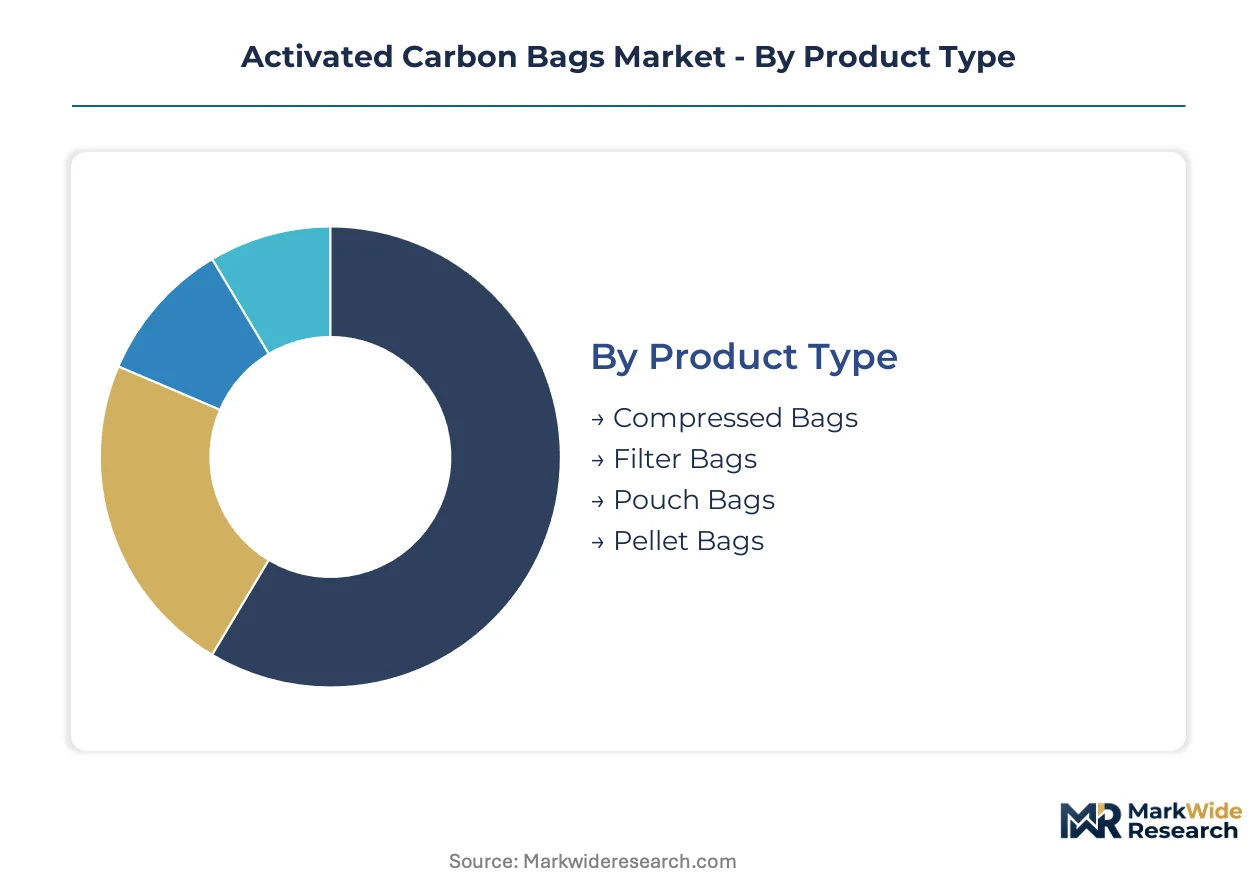
Activated carbon bags flow through sharply divergent commercial channels depending on specification complexity and buyer sophistication. Industrial procurement teams negotiate multi-year municipal contracts for high-capacity filtration systems, while residential consumers purchase odor-control pouches through e-commerce platforms with minimal technical vetting.
Product Type:
Channel mix varies dramatically by bag construction—compressed and pellet formats dominate industrial wholesale, while filter and pouch configurations split between HVAC distributors and direct-to-consumer online retail.
- Filter Bags:Nonwoven synthetic fabric enclosures rated for 800–1,500 square meters per gram surface area, engineered to HVAC specification standards. Demand concentrates in California and New York commercial building retrofits where updated codes mandate volatile organic compound filtration upgrades. Procurement flows through mechanical contractor networks with certified installer requirements.
- Pouch Bags:Small-format flexible containment systems with granular or powdered carbon for residential odor control and food preservation. E-commerce channels enable direct-to-consumer sales with minimal distributor markup, expanding fastest in suburban markets with home air purification priority purchases.
- Compressed Bags:High-density carbon block configurations for industrial pressure vessel applications. Municipal water utilities in the southeastern United States specify these for aging infrastructure replacement cycles.
- Pellet Bags:Extruded carbon cylinder containment for fixed-bed adsorption systems. Chemical processing facilities in Germany's Rhine-Ruhr corridor favor these for solvent recovery operations under REACH reactivation mandates.
Filter bags dominate installed base in commercial HVAC. Pouch bags are where expansion concentrates.
End User:
Cost tier stratification separates specification-grade industrial procurement from price-sensitive residential purchasing, with automotive and commercial segments occupying intermediate positions.
- Industrial:Municipal water treatment utilities and manufacturing facilities requiring certified adsorption capacity documentation. EPA PFAS maximum contaminant level compliance drives procurement pull for high-adsorption systems with third-party BET surface area verification.
- Residential:Homeowners purchasing air purification and odor control solutions through retail channels. Demand surged as post-pandemic indoor air quality awareness converted to priority purchase behavior.
- Automotive:Cabin air filtration and battery manufacturing process water treatment. Electric vehicle lithium-ion cell production facilities require pharmaceutical-grade carbon bags for ultra-pure water systems.
- Commercial:Office buildings, retail spaces, and hospitality venues upgrading HVAC filtration. California Title 24 and New York Local Law 97 drive specification convergence toward activated carbon-impregnated systems.
Industrial users command deepest margin pools through long-term contract structures. Residential generates highest volume turnover through replacement cycle frequency.
Application:
Volume concentration in air purification reflects commercial building stock turnover, while water filtration captures concentrated value in municipal infrastructure programs.
- Water Filtration:Public water system contactors for organic contaminant and PFAS removal. The EPA's finalized drinking water standards mandate filtration upgrades across thousands of systems, creating immediate procurement demand.
- Air Purification:HVAC-integrated volatile organic compound and particulate filtration. Commercial building codes in multiple states are tightening requirements, driving specification upgrades from standard pleated filters.
- Odor Removal:Residential and light commercial applications for pet, smoke, and chemical fume control. E-commerce subscription models capture recurring replacement revenue.
- Food Preservation:Ethylene gas adsorption for produce storage and transport. Direct-to-consumer packaging enables premium pricing through convenience positioning.
Water filtration anchors revenue concentration in municipal contracts. Air purification is gaining share fastest through commercial building code convergence.
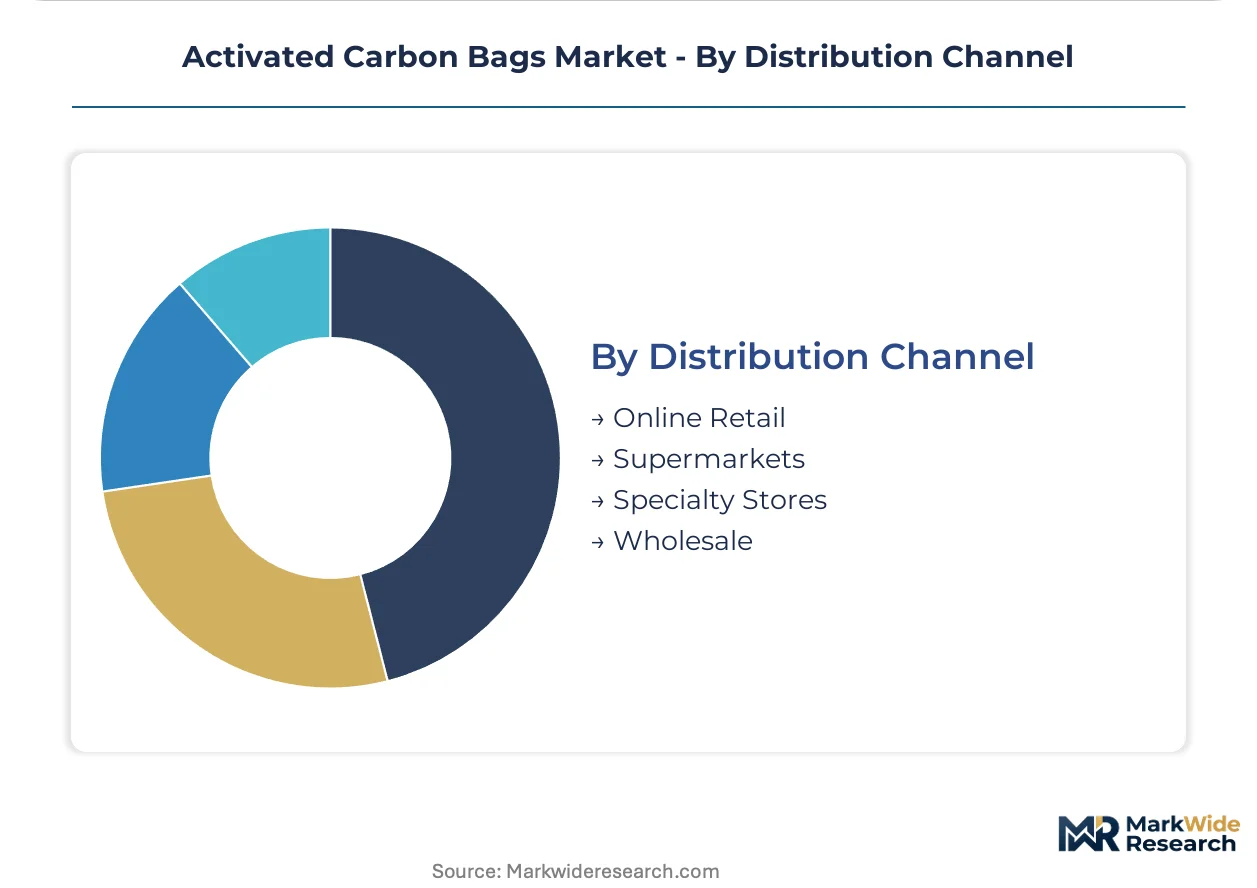
Distribution Channel:
Customer type fragmentation—institutional specification teams versus individual consumers—forces parallel channel strategies with minimal overlap.
- Wholesale:Industrial distributor networks serving municipal utilities and manufacturing facilities with technical qualification support. Florida's consolidated water utility procurement cooperatives now issue multi-year framework agreements with audit clauses.
- Online Retail:Direct-to-consumer platforms for residential air purification and food preservation products. Subscription replacement programs capture recurring revenue with minimal customer acquisition cost.
- Specialty Stores:HVAC and water treatment equipment dealers with certified installer relationships. Technical consultation requirements sustain margin premiums over mass retail.
- Supermarkets:Mass retail placement for basic odor control and food preservation products. Price competition intensifies as private label entrants expand shelf presence.
Wholesale locks in institutional volume commitments. Online retail is climbing the fastest as e-commerce penetration deepens in residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian coconut shell processors export activated carbon precursors to filtration fabricators in Germany and the United States, anchoring the industry's raw material trade corridor. This feedstock flow shapes manufacturing economics across three continents.
United States
Municipal water utilities in Florida and Georgia are replacing 1970s-era filtration infrastructure at accelerated rates. EPA PFAS maximum contaminant level rules mandate activated carbon upgrades across thousands of public water systems. Southeast procurement cooperatives now issue multi-year framework agreements with technical audit clauses.
Germany
Chemical processing facilities in the Rhine-Ruhr corridor demand pellet-based carbon bags for solvent recovery operations. REACH Annex XVII restrictions on persistent organic pollutants tighten spent carbon manifesting and thermal reactivation documentation requirements. EMAS-registered reactivation partnerships are becoming mandatory for circular economy claims.
India
The Jal Jeevan Mission's rural tap water scheme creates first-time demand for decentralized filtration in arsenic and fluoride-affected districts. BIS certification requirements for water treatment products are expanding procurement specifications. Manufacturing clusters in Tamil Nadu and Gujarat are scaling bag fabrication capacity for domestic municipal contracts.
China
Electric vehicle battery manufacturing facilities require pharmaceutical-grade activated carbon bags for ultra-pure process water systems. MIIT cleanroom standards for lithium-ion cell production are tightening contamination control specifications. Yangtze River Delta industrial zones are absorbing premium filtration imports for gigafactory construction.
Japan
Specialty pitch-based carbon fiber precursors anchor high-performance filtration media production. METI carbon neutrality roadmaps are accelerating reactivation facility investments to reduce virgin carbon dependence. Osaka-based chemical conglomerates are integrating bag-system fabrication with captive carbon supply chains.
Activated Carbon Bags Market Competitive Environment
Listed leaders compete with private specialists across specification tiers, with public companies commanding municipal contract volume while private fabricators capture niche application margins. The vendor base splits between integrated carbon producers with captive feedstock and independent bag converters sourcing activated material wholesale. Three archetypes dominate: coconut shell vertical integrators, coal-based carbon specialists, and distributed logistics operators with regional reactivation networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock access and qualification documentation.
Within the integrated producer tier, Calgon Carbon Corporation and Kuraray Co., Ltd. exemplify divergent feedstock strategies—Calgon Carbon leveraging North American municipal relationships while Kuraray anchors specialty pitch-based positioning. Jacobi Carbons AB occupies a distributed manufacturing position that competes on logistics optimization. These three names illustrate how geographic concentration, feedstock control, and service network density separate competitive positions in specification-driven procurement environments.
| Leading Market Players |
|---|
| Calgon Carbon Corporation |
| Cabot Corporation |
| Kuraray Co., Ltd. |
| Jacobi Carbons AB |
| Haycarb PLC |
| Osaka Gas Chemicals Co., Ltd. |
| Donau Carbon GmbH |
| Ingevity Corporation |
| CPL Activated Carbons |
| Others |
Value Chain & Pricing Dynamics
EPA PFAS maximum contaminant level compliance gates both supply qualification and price differentiation simultaneously, as municipal utilities demand third-party BET surface area verification that separates certified suppliers from commodity converters. This regulatory threshold fragments procurement into specification-grade tiers where documentation depth determines margin capture.
Pricing Analysis
Next-generation impregnated activated carbon formulations command substantial premiums over standard granular carbon, while legacy bituminous coal-based systems face cost compression from coconut shell feedstock abundance. Three-tier pricing structure across pharmaceutical-grade, municipal-specification, and economy residential levels reflects certification burden and volume scale. Pricing pressure stems from ion exchange resin substitution in PFAS remediation pilots, squeezing incumbent carbon suppliers. Residential pouch bag buyers exhibit highest price sensitivity through e-commerce comparison shopping, whereas municipal utilities prioritize performance guarantees over unit cost.
Supply Chain Analysis
Container availability fluctuations on Southeast Asia-to-North America trade lanes disrupt coconut shell precursor deliveries to filtration fabricators. Raw material sourcing concentrates in Indonesia, Sri Lanka, and the Philippines for coconut shell carbon, with bituminous coal drawn from Appalachian and Powder River Basin deposits. Supply chain risk centers on single-source vulnerability for food-grade phosphoric acid activation chemicals. Distribution runs through industrial wholesale networks for municipal contracts and direct-to-consumer platforms for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Activated carbon bags represent an early-cycle expansion story as EPA PFAS enforcement creates first-time specification demand across thousands of public water systems previously exempt from advanced filtration mandates.
For Market Incumbents: Shield municipal contract positions by securing captive coconut shell carbonization capacity and accelerating ISO 17025 laboratory partnerships to compress qualification timelines. Ion exchange resin substitution in Great Lakes pilot programs threatens incumbent PFAS removal market share. Backward integration into Southeast Asian precursor supply chains defends margin structure against feedstock cost volatility. For New Entrants and Emerging Players: Spent carbon reactivation service gaps in the EU Critical Raw Materials Act compliance chain offer white-space entry points where incumbents under-serve circular economy documentation requirements. India's Jal Jeevan Mission rural tap water scheme presents the most penetrable geography for first-time decentralized filtration procurement. Direct technical sales to state-level procurement cooperatives bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade cleanroom carbon bag fabrication as electric vehicle battery manufacturing scales. Five-to-ten year viability favors integrated producers with captive feedstock over pure-play converters exposed to raw material volatility. Acquisition targets should display EMAS-registered reactivation partnerships or BIS certification progress for India market access. The signal to monitor is EPA expansion of PFAS maximum contaminant levels to additional fluorochemical subclasses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Shell Carbonization | Calgon Carbon Corporation's captive Philippine supply secures margin advantage in North American municipal tenders. |
| EMAS-Registered Reactivation Partnership | German chemical processors demand thermal reactivation proof documentation under REACH Annex XVII mandates. |
| Direct-to-Specification Procurement Team Buildout | Florida consolidated water utility cooperatives bypass distributors for multi-year framework agreements with audit clauses. |
| Pharmaceutical-Grade Cleanroom Certification | MIIT cleanroom standards for Yangtze River Delta gigafactories require ultra-pure process water filtration systems. |
| Silver-Impregnated Formulation Development | Great Lakes municipal utilities pilot combined microbial and radiological protection beyond legacy iodine-number standards. |
Study Parameters
A standing panel of municipal water utility procurement directors, activated carbon plant managers, HVAC specification engineers, and filtration distributor technical sales leads provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA enforcement action databases, FDA 21 CFR food-contact filings, customs trade records for coconut shell carbon precursors, and SEC 10-K disclosures from listed chemical producers. Bottom-up unit demand modeling triangulated against top-down market size estimates from trade association publications.
Consistency checks validated volume and value outputs against external benchmarks including water infrastructure investment tracking databases and commercial building HVAC retrofit permit filings. Segmentation dimensions spanned product construction type, end-user procurement sophistication, application contaminant class, and regional regulatory framework intensity. CAGRs were derived from installed base turnover analysis and replacement cycle frequency modeling, with electric vehicle battery manufacturing absorption rates and PFAS maximum contaminant level implementation timelines as industry-specific demand drivers.
Underlying assumptions cover EPA enforcement continuity, coconut shell feedstock price stability, and REACH reactivation facility capacity expansion, with deviation risk concentrated in ion exchange resin substitution acceleration and phosphoric acid export control fluctuations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Halloysite Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Teschemacherite Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Non-Semiconductor Neon Market