
 Conductive Carbon Black Market | 2026-2036
Conductive Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Carbon Black Market Analysis
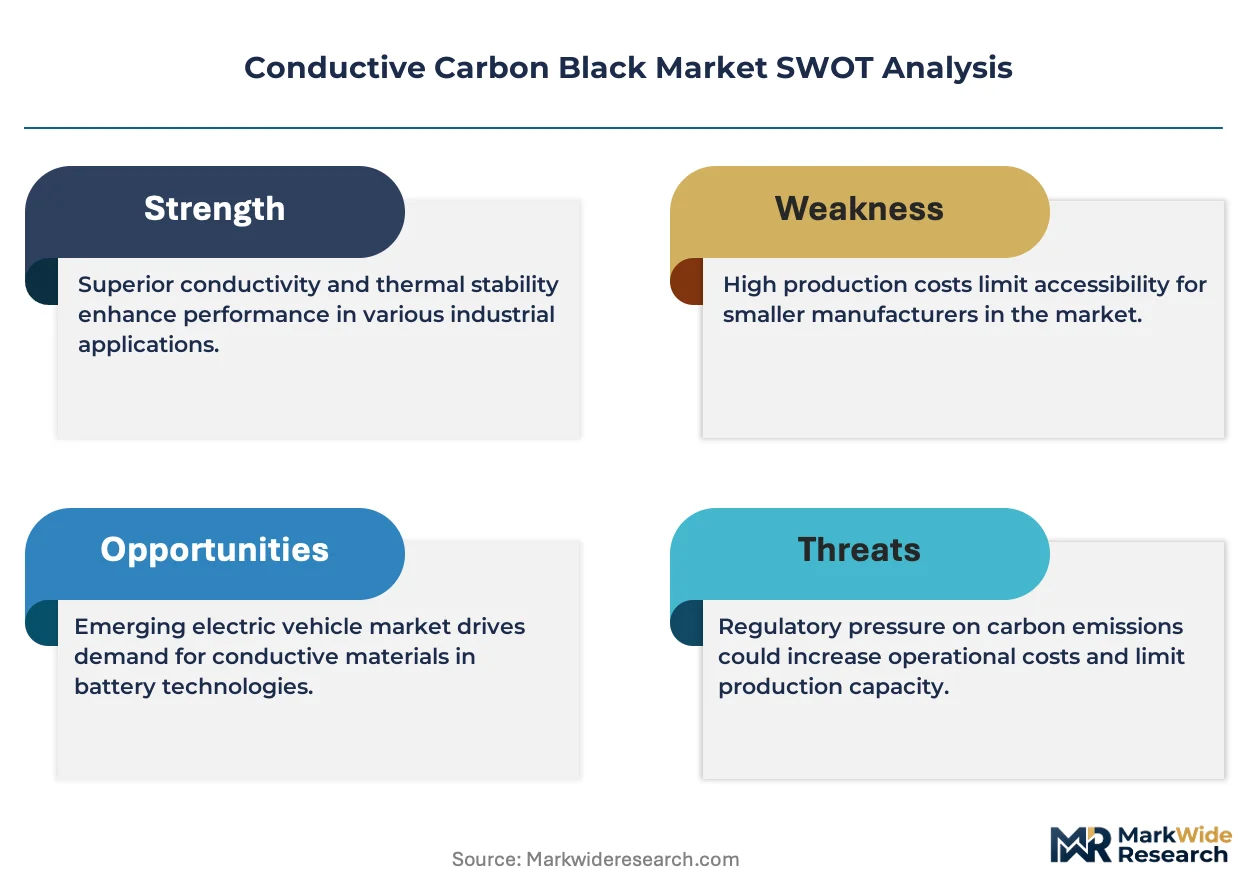
Modular additive packages is pivoting buyer choice as cell manufacturers seek pre-formulated conductive blends rather than single-grade carbon black. Cabot Corporation leverages its specialty carbon black portfolio to serve battery producers with customized dispersion solutions. Orion Engineered Carbons anchors European supply through its high-purity furnace black operations in Germany and France. Birla Carbon competes on manufacturing scale across multiple continents with integrated feedstock sourcing.
Conductive carbon black consists of furnace-processed or acetylene-derived particulate carbon with primary particle sizes ranging from 15 to 100 nanometers and surface areas of 50 to 250 m²/g, engineered to provide electrical conductivity in polymers, coatings, and energy storage materials. Its primary industrial purpose is to establish percolation networks that enable static dissipation, electromagnetic shielding, and efficient electron transport in battery electrodes. Specialty carbon black commands margin pools in lithium-ion battery applications where ultra-low metal content and controlled structure are non-negotiable. Plastic compounds represents a mature segment with steady offtake from automotive underhood components and electronics housings. High-performance carbon black is gaining fastest in electronics applications as 5G infrastructure and wearable devices require thinner conductive layers with consistent resistivity.
REACH and RoHS in Europe restrict polycyclic aromatic hydrocarbon content and hazardous substance thresholds in conductive additives destined for consumer electronics and automotive interiors. EPA oversight in the United States governs emissions from carbon black manufacturing facilities, shaping plant location decisions and capital allocation for domestic producers. China's MEE enforces dual carbon goals that pressure furnace black producers to reduce CO₂ intensity per ton or face operating constraints. Stakeholders must monitor how evolving battery-grade purity specifications interact with carbon footprint accounting to determine which production assets remain competitive.
Market Dynamics
Cell manufacturers are consolidating their additive supply base around pre-formulated conductive blends that reduce formulation complexity and electrode variability, compressing the procurement cycle from multi-grade sourcing to single-supplier qualification.
Growth Catalysts
- China's dual carbon goals:MEE enforcement of CO₂ intensity benchmarks is accelerating furnace black plant upgrades and creating premium pricing tiers for low-carbon battery-grade material.
- Lithium-ion electrode demand:Automotive OEMs in Germany are qualifying conductive additives for next-generation cell designs with higher nickel cathode loadings.
- Acetylene-derived ultra-purity grades:Controlled structure carbon black with sub-10 ppm metal content is displacing conventional furnace black in high-voltage battery applications.
Market Restraints
- Feedstock cost volatility:Carbon black producers face margin compression from naphtha and coal tar oil price swings tied to refining capacity constraints.
- Supply concentration risk:High-purity acetylene black production clusters in specific coastal Chinese provinces, exposing buyers to regional environmental shutdowns.
- REACH PAH thresholds:ECHA restrictions on polycyclic aromatic hydrocarbon content in conductive additives create formulation reformulation costs for European compounders.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Domestic battery production incentives are creating first-mover advantage for conductive additive suppliers establishing local dispersion facilities.
- 5G infrastructure shielding:Electromagnetic interference requirements for base station housings are opening volume offtake for thin-film conductive coatings.
- Modular additive packages:Pre-blended conductive-dispersant systems reduce customer R&D cycles and lock in multi-year supply agreements.
Industry Challenges
- Electrode dispersion expertise gap:Battery manufacturers struggle to source process engineers with carbon black slurry optimization experience for high-solids coating lines.
- Battery-grade certification timelines:OEM qualification protocols for conductive additives extend 18-24 months, delaying revenue recognition for new production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Carbon Black Market |
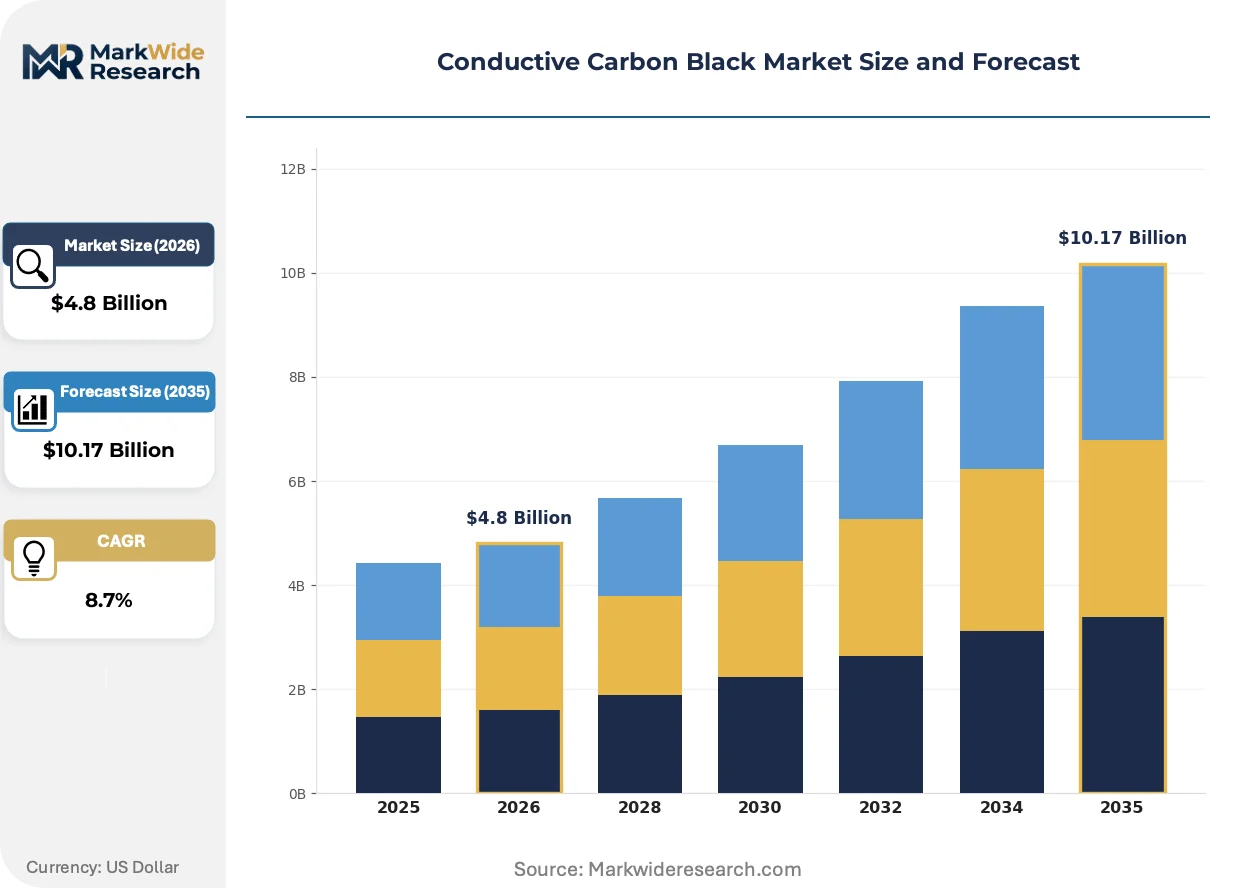
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Carbon Black, Specialty Carbon Black, High-Performance Carbon Black, Reinforcing Carbon Black Application: Electronics, Automotive, Coatings, Plastic Compounds End User: Manufacturers, OEMs, Research Institutions, Material Suppliers Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Phillips Carbon Black Limited, Omsk Carbon Group, Cabot Corporation, OCI Company Ltd., Jiangxi Black Cat Carbon Black Inc., Orion Engineered Carbons, Tokai Carbon Co., Ltd., Himadri Speciality Chemical Ltd., Birla Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Carbon Black Market Emerging Trajectories
Carbon black suppliers are repositioning around dispersion chemistry and application-specific formulations rather than commodity particle sales, blurring traditional boundaries between additive producers and materials engineering services.
Continuous liquid-phase dispersion technology is automating the deagglomeration of conductive carbon black into battery-grade slurries. Korean and Chinese cell manufacturers are adopting inline dispersion systems that reduce solvent use and electrode coating defects. This automation is compressing the traditional multi-step milling process into single-pass production, lowering capital intensity for new electrode lines.
REACH authorization requirements for PAH-containing carbon blacks are tightening purity documentation obligations across European supply chains. ECHA's evolving substance evaluation protocols now demand batch-level metal content certification for battery applications. German automotive OEMs are responding by pre-qualifying only furnace black grades with third-party validated impurity profiles, raising barriers for unverified imports.
Long-term offtake agreements are displacing spot purchasing as the dominant procurement model for battery-grade conductive additives. Tier-1 cell producers in Germany and China are locking in five-year supply contracts with fixed volume tiers and price escalation clauses tied to feedstock indices. This shift concentrates purchasing power among the largest electrode manufacturers while marginalizing smaller compounders without scale to commit forward volumes.
Conductive Carbon Black Market Segmentation
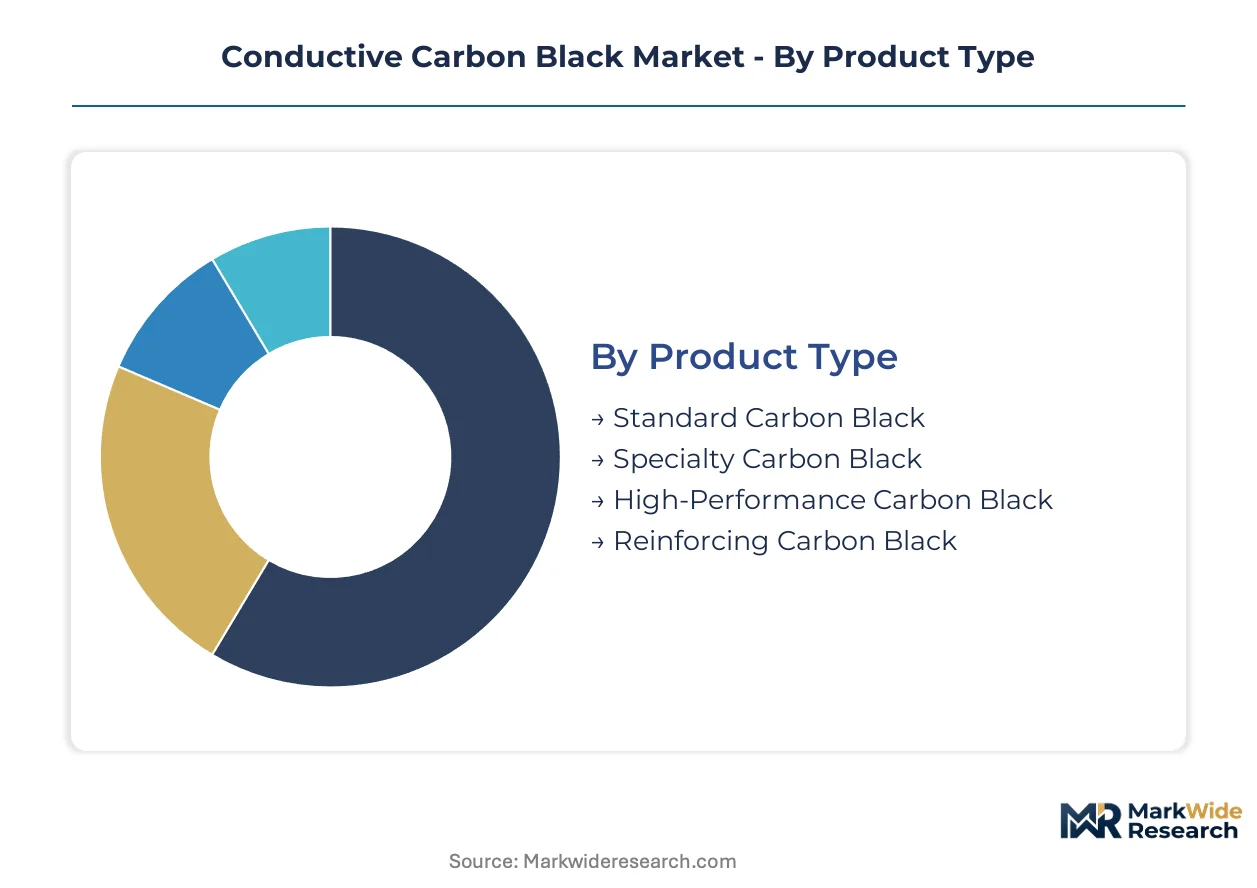
Conductive carbon black procurement decisions hinge on certification tiers that separate battery-grade purity from industrial commodity grades. Manufacturers navigate REACH PAH thresholds, EPA emissions compliance, and China's MEE dual carbon benchmarks when qualifying suppliers across product categories.
Product Type:
REACH and RoHS certification burdens fall heaviest on battery-grade material, while industrial grades face lighter documentation requirements. ECHA's evolving substance evaluation protocols now demand batch-level metal content certification for high-purity segments.
- Specialty Carbon Black:Engineered with ultra-low metal content below 10 ppm and controlled structure for lithium-ion electrode applications. German automotive OEMs are pre-qualifying only furnace black grades with third-party validated impurity profiles for next-generation nickel-rich cathode designs.
- High-Performance Carbon Black:Acetylene-derived grades with surface areas exceeding 200 m²/g serve 5G infrastructure shielding and wearable device conductive layers. Korean cell manufacturers are adopting inline dispersion systems that reduce solvent use when processing these premium grades.
- Standard Carbon Black:Furnace-processed material with broader impurity tolerances serves mature automotive underhood and electronics housing markets.
- Reinforcing Carbon Black:Larger primary particle sizes prioritize mechanical strength over conductivity in tire and rubber applications.
Specialty carbon black sits at the top of the volume ranking, with high-performance grades climbing the fastest.
Application:
Margin pools concentrate where electrode dispersion expertise commands premium pricing and multi-year supply agreements. Customer procurement power scales with cathode loading complexity and coating line automation intensity.
- Electronics:5G base station housings and wearable devices require thinner conductive layers with consistent resistivity. Electromagnetic interference specifications are opening volume offtake for thin-film conductive coatings across Asian manufacturing clusters.
- Automotive:Electric vehicle battery manufacturers are expanding purchases of high-performance conductive additives to improve electrode conductivity and cycle life. China's NMPA tightening purity standards is accelerating furnace black plant upgrades for domestic cell production.
- Plastic Compounds:Steady offtake from automotive underhood components and electronics housings characterizes this mature segment.
- Coatings:Static dissipation and electromagnetic shielding applications serve industrial and consumer electronics enclosures.
Automotive applications command the highest absolute volumes, while electronics represents the steepest expansion trajectory.
End User:
Procurement sophistication divides customers by qualification timeline tolerance and forward volume commitment capacity. Tier-1 cell producers are locking in five-year supply contracts with fixed volume tiers and price escalation clauses.
- OEMs:German automotive OEMs and Tier-1 suppliers are qualifying conductive carbon black for next-generation lithium-ion cell designs with 18-24 month certification protocols. These stakeholders concentrate purchasing power through long-term offtake agreements that marginalize smaller compounders.
- Manufacturers:Cell producers in Germany and China are consolidating their additive supply base around pre-formulated conductive blends that reduce formulation complexity and electrode variability.
- Material Suppliers:Distributors and compounders serve mid-tier customers without scale to commit forward volumes.
- Research Institutions:Pilot-scale procurement for next-generation battery chemistry development drives small-batch specialty grade demand.
OEMs dominate committed forward volumes, with manufacturers gaining share fastest through integrated electrode line investments.
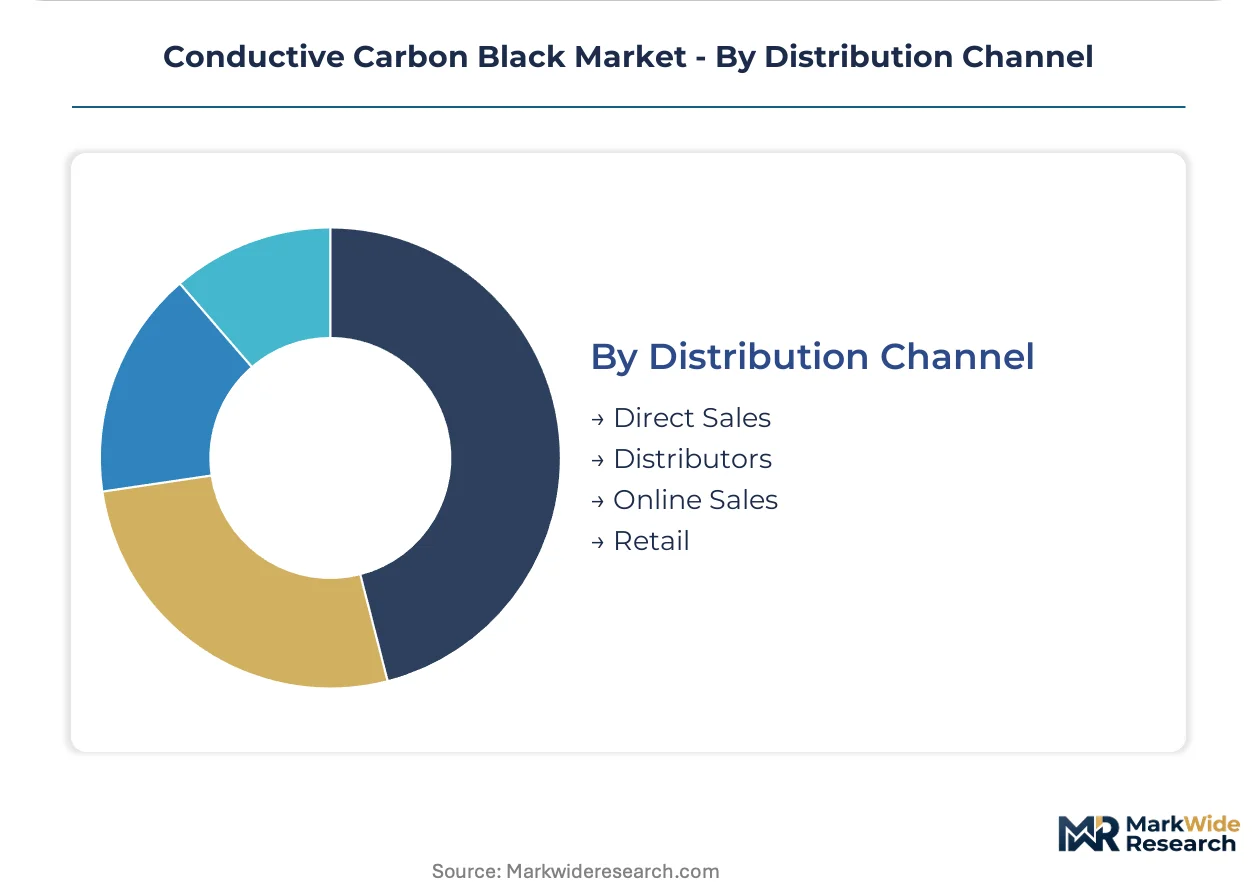
Distribution Channel:
Supply chain configuration separates technical service-intensive battery-grade sales from commodity transactional flows. Direct relationships capture value where dispersion chemistry expertise determines electrode performance.
- Direct Sales:Carbon black suppliers are repositioning around dispersion chemistry and application-specific formulations rather than commodity particle sales. Technical service teams co-develop slurry optimization protocols with Korean and Chinese cell manufacturers adopting inline dispersion systems.
- Distributors:Regional stockholding and just-in-time delivery serve plastic compounders and coatings formulators with predictable offtake patterns.
- Online Sales:Digital procurement platforms are emerging for standardized industrial grades with documented technical data sheets.
- Retail:Small-volume packaging serves research institutions and specialty coatings formulators requiring rapid sample turnaround.
Direct sales channels capture the largest revenue concentration, with distributor networks expanding most quickly in India's PLI-supported cell manufacturing corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The conductive carbon black industry traces its modern scale to German furnace black innovations in the early twentieth century, with subsequent expansion into acetylene-derived grades through Japanese and Chinese petrochemical integration. Today's geographic distribution reflects this dual heritage of European process engineering and Asian feedstock access.
Germany
Automotive OEMs in Stuttgart and Munich are qualifying ultra-low metal content grades for nickel-rich cathode designs. ECHA's REACH authorization protocols now demand batch-level PAH documentation for battery-grade imports. The Ruhr industrial corridor hosts furnace black operations serving Tier-1 cell producers with third-party validated impurity profiles.
China
Domestic cell manufacturers are expanding purchases of high-performance conductive additives to improve electrode conductivity. MEE enforcement of dual carbon goals is accelerating plant upgrades and creating premium pricing tiers for low-carbon battery-grade material. Shandong and Jiangsu provinces concentrate acetylene black production, exposing supply chains to regional environmental shutdowns.
United States
EPA emissions oversight shapes carbon black manufacturing facility location decisions and capital allocation for domestic producers. Korean cell manufacturers with US battery plant investments are sourcing pre-formulated conductive blends to reduce electrode variability. Texas and Louisiana host integrated carbon black operations with captive petrochemical feedstock access.
India
The PLI scheme for cell manufacturing is creating first-mover advantage for conductive additive suppliers establishing local dispersion facilities. BIS certification requirements for battery materials are tightening documentation obligations for imported furnace black grades. Gujarat and Maharashtra are emerging as electrode manufacturing clusters with integrated coating line investments.
South Korea
Cell manufacturers are adopting inline dispersion systems that reduce solvent use and electrode coating defects. MFDS alignment with international battery material standards is accelerating qualification timelines for imported conductive additives. The Ulsan petrochemical complex anchors domestic carbon black processing with integrated slurry production capabilities.
Conductive Carbon Black Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity certification tiers, with battery-grade specialists commanding pricing multiples over industrial furnace black producers. The vendor base stratifies into three tiers: integrated petrochemical majors with captive feedstock, specialty carbon black houses with dispersion chemistry expertise, and regional compounders serving plastic and coatings markets. Two dominant competitive moves are reshaping positioning: long-term offtake agreements with Tier-1 cell producers, and backward integration into acetylene feedstock to secure ultra-purity grade supply.
Within the integrated multinational tier, Cabot Corporation and Orion Engineered Carbons exemplify the dispersion-chemistry pivot, repositioning around application-specific formulations rather than commodity particle sales. Birla Carbon occupies a position across multiple continents with manufacturing scale advantages. Among Asian specialists, Jiangxi Black Cat Carbon Black Inc. and Himadri Speciality Chemical Ltd. represent the regional feedstock-integrated archetype, while Tokai Carbon Co., Ltd. and OCI Company Ltd. anchor the acetylene-derived purity-grade segment.
| Leading Market Players |
|---|
| Phillips Carbon Black Limited |
| Omsk Carbon Group |
| Cabot Corporation |
| OCI Company Ltd. |
| Jiangxi Black Cat Carbon Black Inc. |
| Orion Engineered Carbons |
| Tokai Carbon Co., Ltd. |
| Himadri Speciality Chemical Ltd. |
| Birla Carbon |
| Others |
Supply Flow & Price Mechanics
Naphtha and coal tar oil feedstock costs cascade through furnace black production into three distinct pricing tiers downstream, with battery-grade material commanding substantial premiums over industrial grades due to purity certification burdens and dual carbon compliance investments in China and Germany.
Pricing Analysis
Long-term offtake agreements with fixed volume tiers anchor the dominant pricing structure, separating pre-qualified battery-grade supply from spot-market industrial transactions. Price differentiation rests on metal content certification below 10 ppm and REACH PAH documentation validity, with German OEMs paying least attention to unit cost and maximum attention to batch-level impurity validation. Cost compression in standard furnace black intensifies because naphtha price volatility transmits directly through non-contracted volumes. Small compounders without forward volume commitment capacity exhibit highest price sensitivity, while Tier-1 cell producers lock in multi-year supply with price escalation clauses tied to feedstock indices.
Supply Chain Analysis
Regional distribution centers in the Ruhr corridor, Shandong province, and the Ulsan petrochemical complex anchor hub-and-spoke patterns for battery-grade material. Production concentrates in China, Germany, and South Korea, with acetylene-derived ultra-purity grades clustering in specific coastal Chinese provinces exposed to MEE environmental shutdowns. Feedstock dependencies draw from naphtha crackers, coal tar distillation, and acetylene generation units. Single-source vulnerability runs through Shandong's acetylene black concentration. Distribution runs through direct technical service relationships for battery-grade sales, with distributor networks handling standardized industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductive carbon black market functions as a stable compounder where electric vehicle battery demand provides durable volume foundations across technology cycles.
For Market Incumbents: Anticipate displacement pressure from acetylene-derived ultra-purity grades by securing backward integration into captive feedstock or pre-qualifying furnace black assets for nickel-rich cathode designs. Defensive consolidation moves should concentrate on dispersion chemistry capabilities that lock in multi-year technical service contracts with Korean and Chinese cell manufacturers. Certification investment in third-party validated impurity profiles represents the critical lever for maintaining German OEM supply relationships against emerging Asian specialists.
For New Entrants and Emerging Players: Dispersion facilities in India's PLI-supported cell manufacturing corridor offer the most penetrable entry point, with Gujarat and Maharashtra electrode clusters lacking qualified local additive suppliers. White-space targets include pre-formulated conductive-dispersant systems for high-solids coating lines and inline dispersion system integration services. Go-to-market execution should anchor on technical co-development partnerships with cell producers seeking to reduce electrode variability without internal dispersion expertise.
For Investors and Strategic Acquirers: Consolidation pressure builds where battery-grade purity certification timelines extend 18-24 months and capital intensity for qualified production assets excludes sub-scale competitors. Long-term viability frames around five-to-ten year electric vehicle penetration trajectories rather than cyclical industrial demand. Acquisition targets should screen for acetylene feedstock access or established dispersion chemistry teams. The signal to watch is MEE enforcement intensity in Shandong and Jiangsu provinces, which would accelerate premium pricing tiers for verified low-carbon material.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstock | Secures ultra-purity grade supply for high-voltage battery applications against furnace black substitution. |
| Long-term Supply Agreement | German OEMs lock in five-year contracts with Tier-1 cell producers to marginalize spot-market competitors. |
| Green Manufacturing Transition | MEE dual carbon compliance creates premium pricing tiers for low-carbon battery-grade furnace black. |
| Joint Venture | Korean cell manufacturers partner for inline dispersion systems that reduce solvent use and coating defects. |
| Capacity Expansion | India's PLI scheme rewards first-mover dispersion facilities in Gujarat and Maharashtra electrode clusters. |
Methodological Framework
Multiple input streams — primary interviews with carbon black plant managers, procurement leads at battery OEMs, and technical R&D directors; secondary validation through customs/trade data, SEC filings, and ECHA substance evaluation protocols; plus proprietary production databases — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the modeling period, with segmentation modeled by grade tier, end-use application, and regional production hub. CAGRs derived from feedstock cost trajectory assumptions and electric vehicle battery demand curves, incorporating electrode loading specifications and coating line automation intensity as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity, REACH authorization timeline shifts, and acetylene feedstock supply disruptions. Forecasts reflect documented assumptions about electric vehicle penetration and cathode chemistry evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Surface Technology Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Elastic Films Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market