
 North America Solar Control Window Films Market | 2026-2036
North America Solar Control Window Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Solar Control Window Films Market Analytics
Commercial building retrofits is expanding across North America's solar control window films landscape as facility managers prioritize envelope upgrades over full HVAC replacement. Eastman Chemical Company leverages its sputtered metalized film expertise to dominate specification-grade commercial projects. Johnson Window Films anchors the residential contractor channel through regional distribution partnerships. Madico competes in the marine and specialty transportation segments with dyed and ceramic hybrid formulations.
North America solar control window films are thin polymer laminates, typically polyethylene terephthalate-based, engineered with vapor-deposited metal oxide or carbon-based ceramic layers that reject infrared radiation while maintaining visible light transmission. Their primary purpose is reducing solar heat gain through glazing systems to lower cooling loads and extend HVAC equipment life. Ceramic films now lead product type growth due to electromagnetic signal transparency and corrosion resistance advantages over metalized alternatives. The commercial application segment captures the deepest margin pools, driven by utility rebate eligibility and green building certification requirements. Spectrally selective films represent the fastest-growing technology tier, targeting precise wavelength blocking without dark tinting.
California's Title 24 Building Energy Efficiency Standards, administered by the California Energy Commission, mandate maximum solar heat gain coefficients for fenestration retrofits above specified glazing areas. The U.S. Environmental Protection Agency's ENERGY STAR program and LEED certification frameworks from the U.S. Green Building Council shape procurement criteria for institutional buyers. Canada's National Energy Code for Buildings, enforced provincially, extends comparable performance requirements into that market. Stakeholders must monitor evolving state-level stretch codes and utility incentive program redesigns that increasingly tie rebate levels to measured whole-building energy performance rather than equipment specification alone.
Market Dynamics
California's Title 24 solar heat gain coefficient mandates are compressing specification timelines and forcing film manufacturers to accelerate certified product development cycles. This regulatory pressure is reshaping competitive positioning by rewarding firms with pre-approved product portfolios and testing relationships with the California Energy Commission.
Growth Catalysts
- Title 24 Compliance Deadlines:California's building energy codes mandate solar heat gain coefficient thresholds for commercial retrofits above specified glazing areas, creating mandatory replacement demand for non-compliant installations.
- Cooling-Degree-Day Concentration:The southwestern United States generates disproportionate demand intensity as Phoenix, Las Vegas, and Austin facility managers prioritize envelope upgrades over full HVAC replacement.
- Ceramic Film Signal Transparency:Electromagnetic interference-free ceramic formulations enable specification in data centers, hospitals, and transportation hubs where metalized films disrupt operations.
Market Restraints
- Petroleum-Based Input Volatility:Polyethylene terephthalate resin prices fluctuate with crude oil markets, compressing margin predictability for film laminators without backward integration into polymer supply.
- Installation Labor Scarcity:Skilled applicator certification programs remain concentrated in California and Texas, constraining project throughput in secondary metropolitan markets.
- Window Replacement Substitution:Declining costs for high-performance low-E glazing systems threaten film retrofit economics in premium commercial segments with 20-year building ownership horizons.
Strategic Opportunities
- Canadian Provincial Code Harmonization:Canada's National Energy Code for Buildings enforcement varies by province, creating first-mover advantage for firms establishing specification relationships with Ontario and British Columbia code officials.
- Marine and Rail Transportation:Specialty ceramic-dyed hybrid formulations address curved glass geometries and salt-corrosion environments underserved by standard architectural product lines.
- Utility Performance-Linked Rebates:Pacific Gas & Electric and Southern California Edison are redesigning incentive programs around measured whole-building energy performance rather than equipment specification alone.
Industry Challenges
- NFRC Certification Timeline Compression:National Fenestration Rating Council testing protocols require 12-16 weeks for new product validation, misaligning with project bid cycles that demand 4-6 week material availability.
- Multi-Site Rollout Coordination:National retail and hospitality chains require consistent film appearance and performance across dozens of simultaneous installations, straining quality control and installer network capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Solar Control Window Films Market |
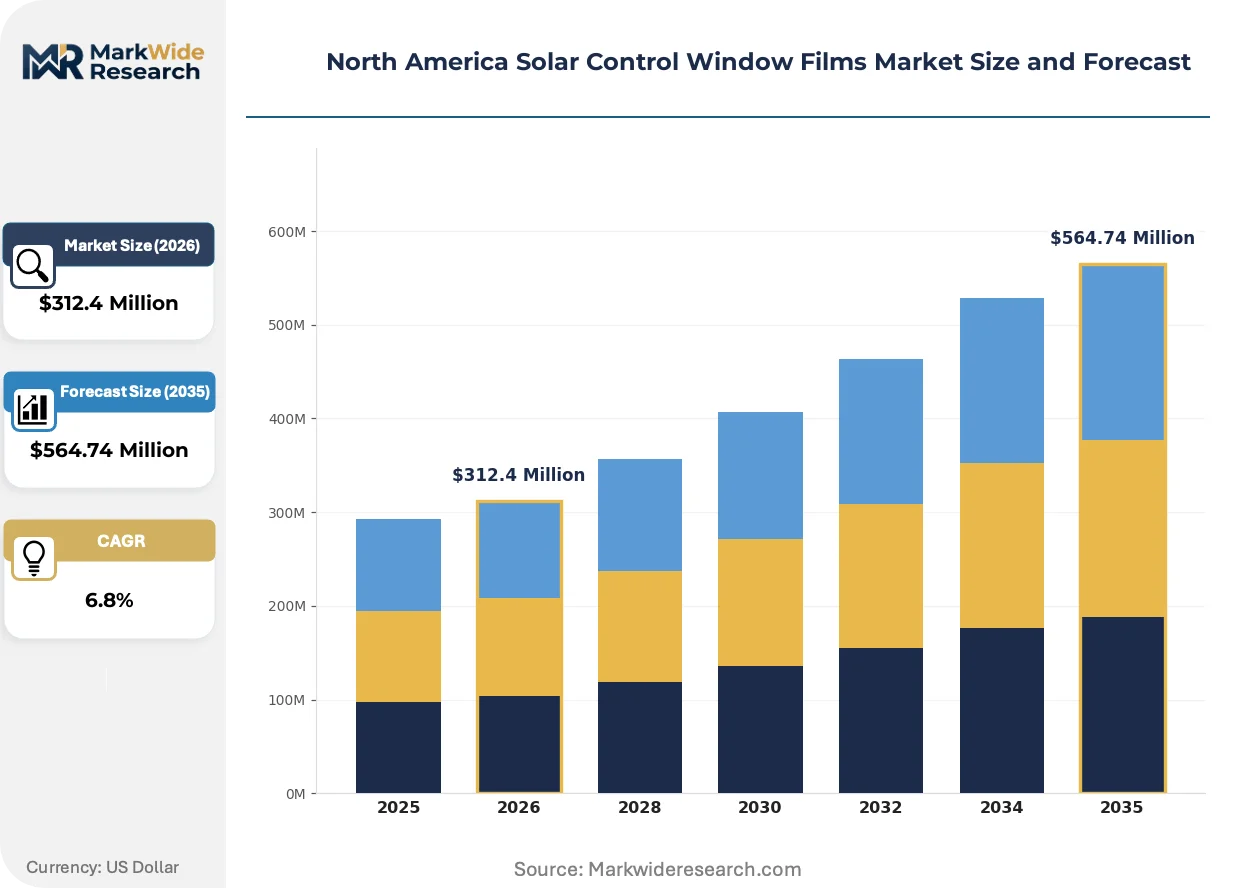
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Films, Metalized Films, Ceramic Films, Spectrally Selective Films Application: Residential, Commercial, Automotive, Marine Technology: Thermal, Optical, Adhesive, UV Protection End User: Homeowners, Contractors, Fleet Operators, Facility Managers |
| Companies Covered | 3M, Eastman Chemical Company, Saint-Gobain, Johnson Window Films, Madico, Avery Dennison Corporation, Solar Gard, XPEL, Decorative Films, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Solar Control Window Films Market Evolving Landscape
Spectrally selective coating technologies are compressing the performance gap between high-rejection films and clear glazing aesthetics. This convergence is enabling specification in heritage buildings and premium office segments previously resistant to visible tint.
Nanoparticle-doped ceramic layers are absorbing infrared wavelengths across broader spectral bands than earlier metal oxide formulations. Large healthcare systems in Texas and Arizona are specifying these films for patient-facing glazing where dark tinting is clinically undesirable. The technology is absorbing specification share from dual-reflective metalized products in commercial segments where appearance constraints previously limited film adoption.
The U.S. Environmental Protection Agency's ENERGY STAR program and LEED certification frameworks from the U.S. Green Building Council are tightening procurement criteria for institutional buyers. Property managers pursuing green building credentials now require documented solar heat gain coefficient performance and lifecycle carbon data from film suppliers. The commercial application segment is responding by demanding third-party verified environmental product declarations from specification-grade manufacturers.
Facility managers are consolidating envelope upgrade decisions under energy service company contracts rather than discrete capital procurement. This bundling displaces direct manufacturer relationships and compresses price transparency for film suppliers. The shift is most visible in California and New York markets where utility demand response programs incentivize comprehensive building performance contracting over equipment-specific rebates.
North America Solar Control Window Films Market Segmentation
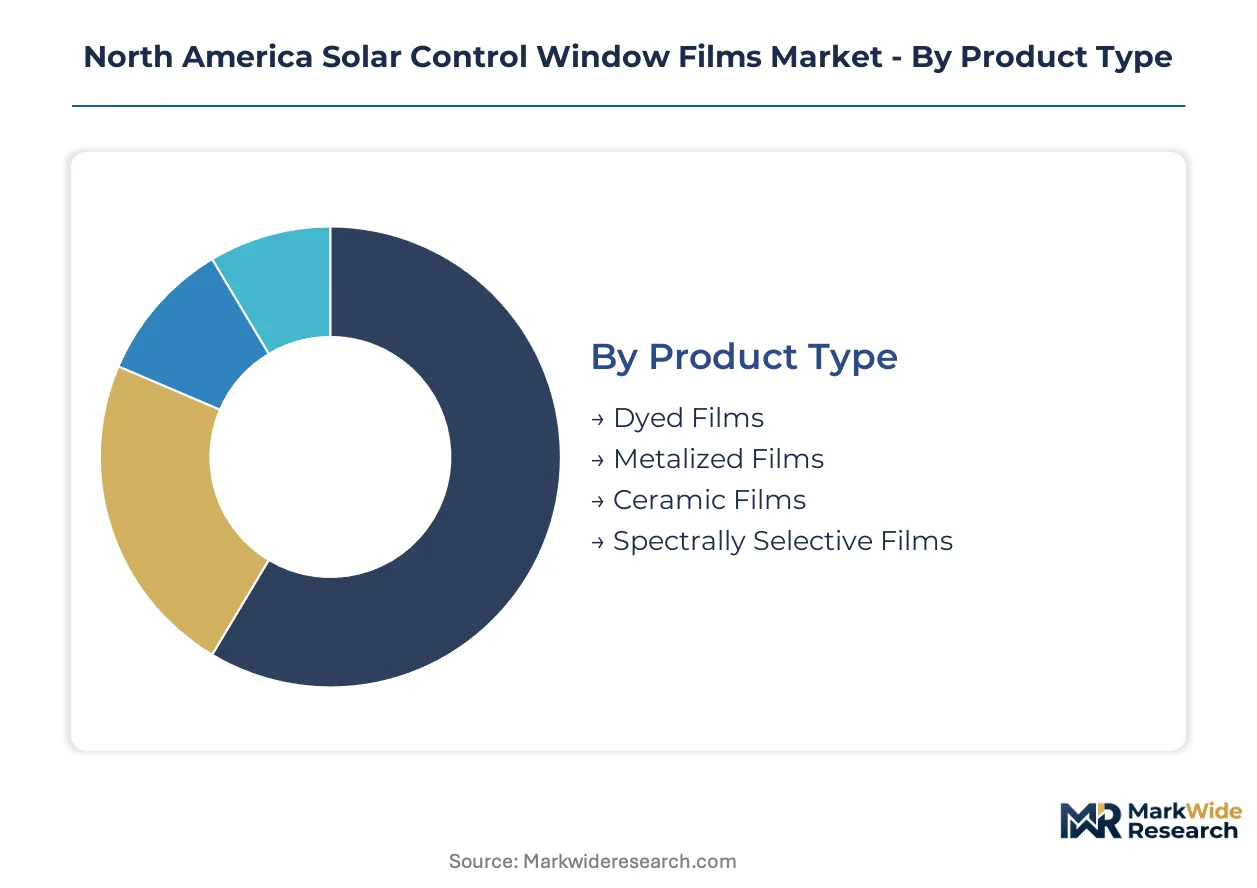
Product specification in North America's solar control window films market hinges on thermal rejection targets, electromagnetic compatibility requirements, and aesthetic constraints. Buyers navigate trade-offs between visible light transmission and infrared blocking efficiency across distinct formulation categories.
Product Type:
Cost tier dictates specification patterns, with premium ceramic and spectrally selective formulations commanding retrofit budgets in high-cooling-load climates while dyed films serve price-sensitive residential channels.
- Dyed Films:Polymer substrates infused with organic colorants absorb solar energy at the film surface, reducing glare and moderate heat gain through absorption rather than reflection. Arizona and Nevada residential contractors specify these for single-family retrofits where upfront cost constraints outweigh long-term energy savings calculations.
- Ceramic Films:Non-conductive metal oxide nanoparticles embedded in PET layers reject infrared radiation without metallic interference, enabling 5G signal transparency and corrosion resistance. Texas data centers and California healthcare facilities prioritize these formulations where electromagnetic compatibility and clear sightlines are non-negotiable.
- Metalized Films:Vacuum-deposited aluminum or nickel-chrome layers provide high solar heat gain coefficient reduction at lower price points than ceramic alternatives. Demand concentrates in commercial warehouse retrofits across the southwestern United States where signal interference is irrelevant.
- Spectrally Selective Films:Multi-layer optical stacks target precise wavelength blocking in the near-infrared spectrum while maximizing visible light transmission. Heritage building renovations in Boston and Chicago specify these to meet energy codes without altering historic glazing aesthetics.
Volume sits with metalized films in commercial retrofit channels; growth tilts toward ceramic formulations as electromagnetic transparency requirements expand beyond data centers into transportation and healthcare infrastructure.
Application:
Customer type shapes procurement pathways, with facility managers bundling envelope upgrades under energy service contracts while homeowners purchase through retail and contractor channels.
- Commercial:Office buildings, retail chains, and institutional properties drive specification-grade demand through California Title 24 compliance mandates and utility rebate eligibility. Pacific Gas & Electric's performance-linked incentive programs accelerate whole-building retrofit decisions that include high-rejection ceramic and spectrally selective installations.
- Residential:Single-family and multi-family property owners prioritize glare reduction and furniture protection over maximum thermal rejection in most climate zones. The southwestern United States generates disproportionate intensity here as Phoenix and Las Vegas homeowners face extreme cooling-degree-day exposure.
- Automotive:Aftermarket tinting and OEM specification for electric vehicle thermal management create distinct demand pools. Ceramic formulations gain share as connected vehicle architectures require electromagnetic transparency for sensor and communication systems.
- Marine:Curved glass geometries and salt-corrosion environments in yacht and commercial vessel applications demand specialized ceramic-dyed hybrid formulations. Florida and Pacific Northwest boatyards represent concentrated specification channels underserved by standard architectural product lines.
Commercial captures the deepest margin pools; marine and rail transportation segments are expanding most quickly as specialty formulation capabilities differentiate supplier positioning.
Technology:
Supply concentration among sputtering and vapor deposition equipment owners shapes which technology tiers achieve scale economics.
- Thermal:Infrared rejection performance measured by solar heat gain coefficient reduction determines specification in code-driven markets. California Energy Commission certification requirements compress development timelines for thermal-optimized formulations.
- Optical:Visible light transmission and clarity specifications enable premium positioning in heritage and healthcare segments where dark tinting is unacceptable. Spectrally selective coatings represent the leading edge of optical technology deployment.
- Adhesive:Pressure-sensitive and water-activated mounting systems determine installation speed and durability in high-humidity climates. Florida and Gulf Coast applications demand salt-resistant adhesive chemistries.
- UV Protection:Ultraviolet blocking at 99% levels protects interior furnishings and reduces skin cancer risk, driving residential specification particularly in high-elevation southwestern markets. This technology layer is now table stakes across all product tiers.
Adhesive and UV protection function as enabling layers across all product types; thermal performance is the primary specification differentiator in commercial procurement.
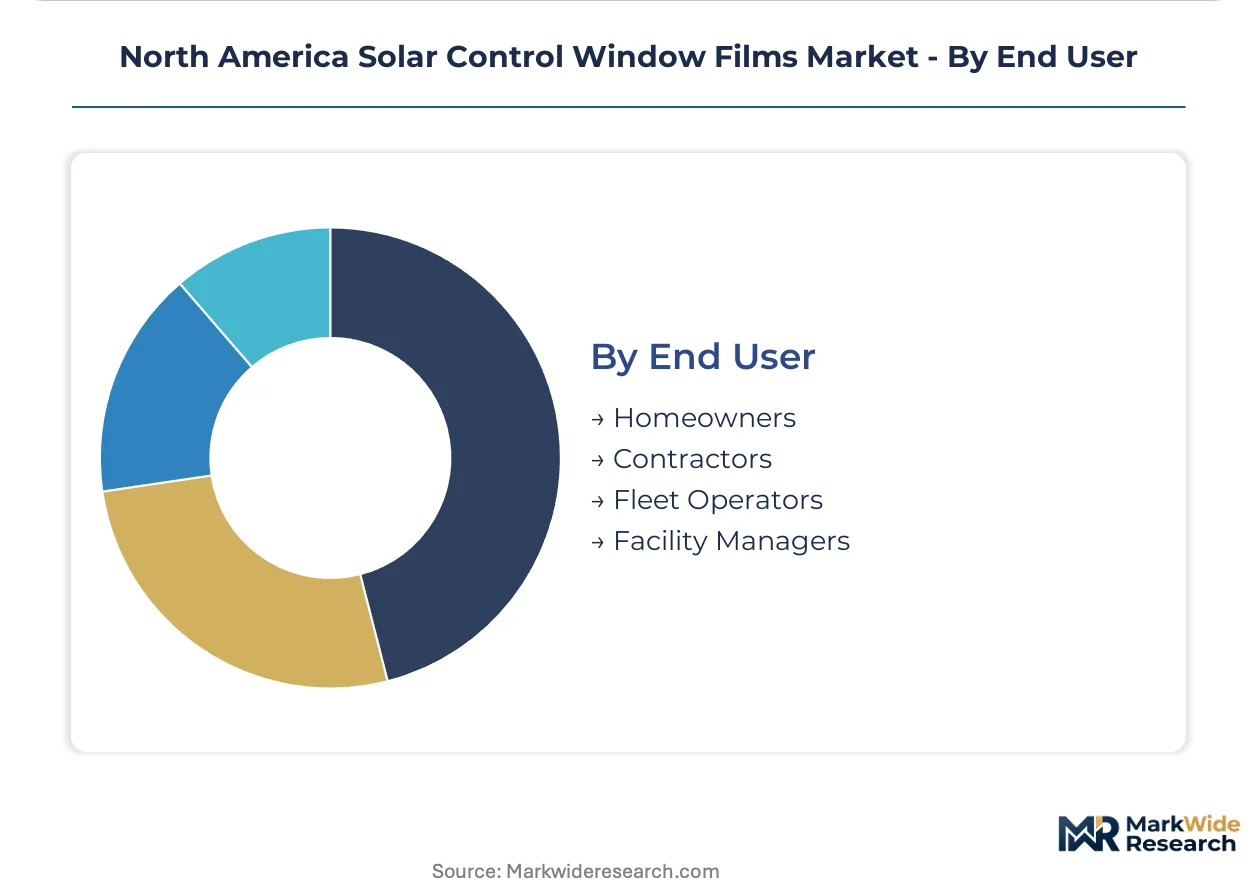
End User:
Procurement authority is fragmenting as energy service companies consolidate envelope upgrade decisions away from direct manufacturer relationships.
- Facility Managers:Corporate real estate and institutional property operators drive commercial segment volume through sustainability targets and regulatory compliance mandates. ENERGY STAR and LEED procurement criteria shape supplier selection in this channel.
- Contractors:Residential and commercial installation firms influence product selection through distributor relationships and certified applicator networks. California and Texas labor scarcity constrains project throughput in secondary metropolitan markets.
- Homeowners:Retail and direct-to-consumer channels serve DIY installations and small-project professional sourcing. Price sensitivity dominates decision-making outside extreme climate exposure zones.
- Fleet Operators:Commercial vehicle and marine fleet managers specify standardized film packages across multi-unit deployments. National retail and hospitality chains require consistent appearance and performance across simultaneous installations.
Facility managers control the largest contract values; fleet operators are gaining procurement influence as transportation electrification intensifies thermal management requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southwestern United States concentration zone drives disproportionate specification intensity, with California's Title 24 compliance corridors and Texas utility incentive clusters forming the dominant demand poles across North America.
United States
California's Title 24 Building Energy Efficiency Standards mandate solar heat gain coefficient thresholds for commercial retrofits above specified glazing areas, compressing specification timelines for certified film portfolios. The EPA's ENERGY STAR program and USGBC LEED frameworks shape institutional procurement criteria nationwide. Phoenix, Las Vegas, and Austin facility managers prioritize envelope upgrades over full HVAC replacement in high cooling-degree-day markets.
Canada
Ontario and British Columbia code officials are harmonizing enforcement of the National Energy Code for Buildings, creating first-mover advantage for firms establishing specification relationships in these provinces. Health Canada's building performance guidelines extend comparable thermal requirements into institutional procurement. Toronto and Vancouver commercial real estate operators are consolidating envelope upgrade decisions under energy service company contracts.
Southwestern United States
Texas data centers and Arizona healthcare facilities specify ceramic formulations where electromagnetic compatibility and clear sightlines are non-negotiable. Pacific Gas & Electric and Southern California Edison are redesigning incentive programs around measured whole-building energy performance rather than equipment specification alone. Dallas-Fort Worth and Houston metropolitan markets face skilled applicator certification constraints that limit project throughput.
California
The California Energy Commission administers solar heat gain coefficient compliance mandates that accelerate certified film installations across commercial building retrofits. Utility rebate eligibility and green building certification requirements drive the deepest margin pools in specification-grade procurement. San Francisco Bay Area and Los Angeles Basin property managers pursue energy cost reductions through high-performance ceramic and spectrally selective film installations.
North America Solar Control Window Films Market Competitive Landscape
Top-tier vendors anchor specification-grade commercial projects, while regional distributors and specialty formulators occupy mid-tier and niche positions. The market structure rewards firms with pre-approved product portfolios and testing relationships with the California Energy Commission. Three archetypes dominate: sputtered metalized film specialists, ceramic formulation innovators, and marine/transportation segment specialists. Competitive moves concentrate on strategic partnerships with energy service companies and portfolio diversification into spectrally selective coating technologies.
Within the diversified chemical conglomerate tier, 3M and Eastman Chemical Company exemplify scale-driven positioning across multiple technology tiers. Among specialty film fabricators, Johnson Window Films occupies a position in regional distribution networks, while Madico represents the marine and specialty transportation segment archetype with ceramic-dyed hybrid formulations.
| Leading Market Players |
|---|
| 3M |
| Eastman Chemical Company |
| Saint-Gobain |
| Johnson Window Films |
| Madico |
| Avery Dennison Corporation |
| Solar Gard |
| XPEL |
| Decorative Films |
| Others |
Value Network & Pricing Analysis
Ceramic-to-metalized formulation bifurcation separates premium specification-grade pricing from commodity retrofit economics, with California Energy Commission certification timelines compressing lead-time premiums for compliant portfolios while spot-market metalized inventory trades at thinner margins. This tier divergence manifests in supply chain configuration: certified ceramic laminates flow through specification-engineer relationships with energy service companies, while metalized films move through distributor networks serving contractor-driven commercial warehouse retrofits.
Pricing Analysis
Short-lead-time premiums for California Energy Commission pre-certified ceramic formulations command 15-25% markups over standard delivery windows, while spot inventory of metalized films clears at discounted rates in Texas and Arizona markets. Three-tier pricing structure across premium ceramic, standard metalized, and economy dyed levels reflects certification grade and electromagnetic transparency performance. Cost compression in metalized tiers intensifies as low-E glazing substitution threatens retrofit economics in 20-year ownership horizons. Residential contractors in Phoenix and Las Vegas exhibit highest price sensitivity; data center facility managers in Dallas-Fort Worth demonstrate lowest sensitivity due to 5G signal transparency requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale commercial retrofit demand through energy service company contracts, while regional distributor networks serve residential contractor and fleet operator procurement. Manufacturing concentration rests in the United States, South Korea, and Germany for sputtering equipment and vapor deposition systems. Raw material dependencies include polyethylene terephthalate resin, metal oxide nanoparticles, and pressure-sensitive adhesive chemistries. Single-source vulnerability sits with specialized sputtering equipment owners who control scale economics for spectrally selective coating production. Distribution runs through California and Texas certification hubs that constrain installer network capacity in secondary metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America solar control window films market is executing a technology transition from metalized to ceramic formulations, with nanoparticle-doped infrared absorption replacing legacy dual-reflective products in specification-grade segments.
For Market Incumbents: Lock in California Energy Commission testing relationships to compress certification timelines below NFRC standard protocols, defending specification-grade positioning against emerging ceramic specialists. Deepen backward integration into PET resin supply to buffer petroleum-based input volatility threatening metalized film margins. Prioritize spectrally selective R&D investment as heritage building and healthcare segments reject visible tint aesthetics.
For New Entrants and Emerging Players: E-commerce direct-to-fleet-operator channels bypass incumbent distributor relationships in marine and rail transportation segments underserved by standard architectural product lines. Target Florida and Pacific Northwest boatyards with ceramic-dyed hybrid formulations addressing curved glass geometries and salt-corrosion environments. Pursue utility performance-linked rebate program partnerships in Ontario and British Columbia as Canadian provincial code harmonization creates first-mover specification advantages.
For Investors and Strategic Acquirers: Re-rating potential sits with ceramic formulation innovators given electromagnetic transparency requirements expanding from data centers into connected vehicle architectures and 5G infrastructure. Long-term viability favors firms with spectrally selective coating capabilities and pre-approved California Energy Commission portfolios over metalized commodity producers facing low-E glazing substitution. Monitor Pacific Gas & Electric and Southern California Edison incentive program redesigns toward whole-building performance metrics as inflection indicator for energy service company contract consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| California Energy Commission Certification Acceleration | Pre-approved portfolios capture Title 24 retrofit mandates before NFRC timeline compression disadvantages competitors. |
| Ceramic Formulation Capacity Expansion | Electromagnetic transparency capabilities enable specification in Texas data centers and California healthcare facilities. |
| Energy Service Company Partnership | Direct relationships with Pacific Gas & Electric performance-linked programs bypass distributor price transparency erosion. |
| Spectrally Selective Coating Development | Heritage building renovations in Boston and Chicago demand precise wavelength blocking without dark tint aesthetics. |
| Marine Segment Distribution Partnership | Florida and Pacific Northwest boatyards require specialized ceramic-dyed hybrids for curved glass and salt corrosion. |
Research Methodology
Multi-period observation of cooling-degree-day intensity, Title 24 compliance retrofit volumes, and ceramic formulation specification share anchored the trend analysis, supplemented by interviews with film laminator plant managers, California Energy Commission certification officials, energy service company procurement leads, and commercial facility managers in Phoenix, Las Vegas, and Austin. Secondary validation drew from U.S. Environmental Protection Agency ENERGY STAR program databases, California Energy Commission building standards documentation, utility incentive program filings from Pacific Gas & Electric and Southern California Edison, and National Fenestration Rating Council certification records. Bottom-up project pipeline triangulation against top-down regional cooling-load macro indicators ensured cross-verification of demand estimates.
Segment-weighting across product type, application, technology layer, and end-user procurement authority shaped volume and value outputs throughout the forecast period. Modeled dimensions included ceramic versus metalized versus dyed formulation tiers, commercial versus residential versus automotive versus marine application segments, and facility manager versus contractor versus homeowner versus fleet operator procurement pathways. CAGRs derived from regression analysis of historical retrofit penetration rates against cooling-degree-day exposure and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated polyethylene terephthalate resin price elasticity and skilled applicator certification program expansion constraints.
The model holds under stable California Title 24 enforcement intensity and continued petroleum-based input cost volatility; deviation in low-E glazing cost trajectories or federal energy code preemption would shift retrofit economics and specification patterns. Forecasts reflect documented assumptions regarding ceramic formulation electromagnetic transparency adoption curves and utility incentive program redesign velocity. Periodic stress-testing of base assumptions against National Energy Code for Buildings harmonization progress in Ontario and British Columbia is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Silicone Gel Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Lab Grown Diamonds Market