
 Global Consumer Foam Market | 2026-2036
Global Consumer Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Foam Market Analysis
Buyer concentration across the furniture and bedding supply chain is rebalancing as large-format retailers and direct-to-consumer mattress brands consolidate procurement volumes while specialized hospitality and healthcare buyers fragment specifications. BASF SE leverages its integrated polyol supply chain to sustain cost competitiveness in flexible polyurethane systems. Dow Inc. anchors North American production with dedicated TDI and MDI derivative capacity for bedding applications. Covestro AG differentiates through low-VOC and bio-based foam grades targeting European sustainability mandates.
Consumer foam encompasses cellular polymer structures engineered with controlled porosity, density ranges from 10 to 80 kg per cubic meter, and compression set resistance tailored to cushioning and insulation functions; manufacturers employ slabstock, molded, or continuous lamination processes to produce sheets, blocks, or contoured components for comfort and protective packaging. Polyurethane Foam dominates value generation due to its versatility across furniture and automotive seating applications where durability and cost efficiency determine specification. Memory Foam commands premium positioning in bedding as pressure-mapping technology and sleep-science marketing elevate consumer willingness to pay for viscoelastic performance. Latex Foam sustains niche growth in natural and organic product lines where botanical sourcing and hypoallergenic claims attract health-conscious residential buyers.
The EPA regulates volatile organic compound emissions from foam manufacturing under Clean Air Act standards, while the EU REACH framework restricts hazardous substance content and mandates substitution pathways for conventional blowing agents. China's MEE enforces national emission standards for polyurethane production facilities in the Yangtze and Pearl River manufacturing clusters. Japan's METI promotes next-generation insulation foam through energy-efficiency building codes. Stakeholders must monitor regulatory divergence between jurisdictions to determine where formulation standardization or regional product customization preserves margin and market access.
Market Dynamics
Water-blown polyurethane formulations are displacing conventional HCFC-based systems as REACH isocyanate exposure limits and EPA Clean Air Act enforcement tighten manufacturing protocols across major production clusters.
Growth Catalysts
- Residential renovation intensity:Furniture manufacturers in China and Germany are expanding slabstock procurement as housing retrofit rates accelerate comfort upgrade cycles.
- REACH substitution mandates:The EU framework restricts hazardous blowing agents and mandates low-VOC pathways, accelerating compliant formulation adoption across European bedding supply chains.
- Pressure-mapping integration:Sleep-science marketing elevates viscoelastic specification in premium mattress segments, pulling memory foam into direct-to-consumer brand portfolios.
Market Restraints
- TDI/MDI feedstock volatility:Aromatic isocyanate pricing swings compress margin predictability for flexible polyurethane producers serving furniture OEMs.
- China production concentration:Yangtze and Pearl River manufacturing clusters concentrate global polyurethane capacity, exposing supply continuity to regional emission enforcement actions by MEE.
- Natural latex substitution pressure:Botanical foam alternatives capture health-conscious residential buyers in organic product lines, constraining synthetic share in premium bedding.
Strategic Opportunities
- India consumption expansion:Underpenetrated mattress replacement rates and urban household formation create white space for molded foam component suppliers.
- Healthcare specification divergence:Antimicrobial and pressure-relief grades for hospital and long-term care facilities open specialized contracting channels beyond residential retail.
- Japan METI efficiency codes:Next-generation insulation foam promotion through building energy standards pulls high-performance grades into commercial construction specification.
Industry Challenges
- Formulation chemist scarcity:Water-blown system expertise gaps constrain R&D velocity as manufacturers transition from legacy HCFC protocols.
- Multi-jurisdiction certification timelines:Divergent EPA, REACH, and China GB standard compliance requirements fragment product platforms and extend qualification cycles.
- Continuous lamination capex intensity:Automated sheet production lines require substantial capital deployment, disadvantaging mid-scale producers against integrated resin-to-foam operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Foam Market |
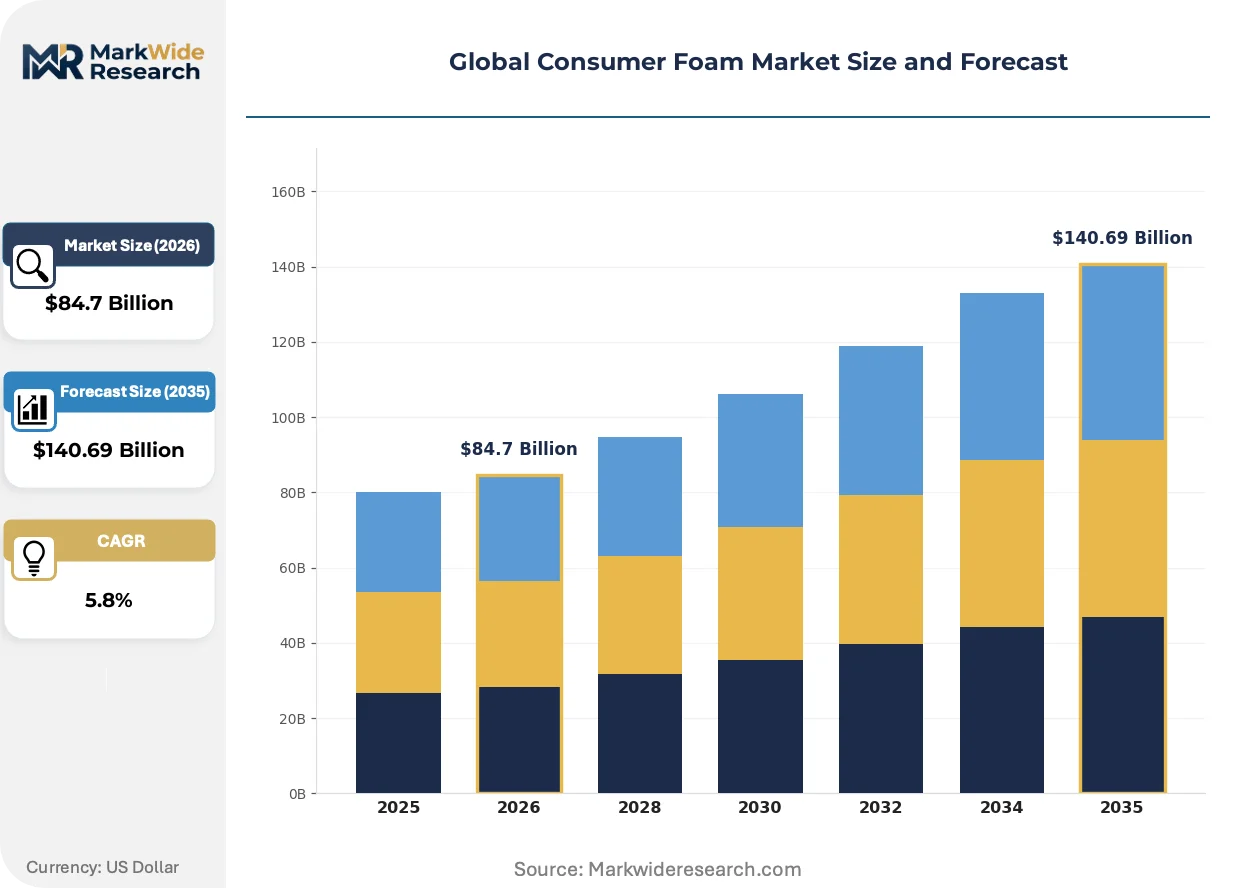
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $140.69 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Polyurethane Foam, Latex Foam, Polystyrene Foam Application: Furniture, Bedding, Automotive Interiors, Packaging End User: Residential, Commercial, Educational, Healthcare Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | BASF SE, Dow Inc., Covestro AG, Huntsman Corporation, JSP Corporation, DuPont, Rogers Corporation, Sekisui Chemical Co., Ltd., Recticel NV/SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Foam Market Emerging Trajectories
Bio-based polyol feedstocks, digital sleep diagnostics, and compressed mattress logistics are restructuring how foam specifications are developed, validated, and delivered to end-users.
Plant-derived polyol systems incorporating castor oil and soybean oil fractions are decentralizing petroleum dependency in flexible polyurethane production. North American bedding brands are accelerating specification of 20-30% bio-content grades as sustainability claims differentiate direct-to-consumer portfolios. This feedstock diversification is compressing exposure to aromatic crude derivatives while introducing new supply partnerships with agricultural processors.
EPA enforcement of Clean Air Act volatile organic compound standards is tightening emission thresholds for foam curing and finishing operations. Manufacturers serving US residential furniture channels are retrofitting thermal oxidizers and carbon capture systems to maintain operating permits. California and Texas production facilities face the steepest compliance timelines due to state-level air quality management district overlays.
Compressed roll-pack mattress logistics are reshaping fulfillment economics for foam-intensive bedding products. E-commerce brands are eliminating traditional wholesale markup layers by shipping vacuum-compressed viscoelastic units direct to residential doorsteps. Germany and the United Kingdom represent the most advanced adoption corridors, where last-mile density supports compressed product handling infrastructure.
Global Consumer Foam Market Segmentation
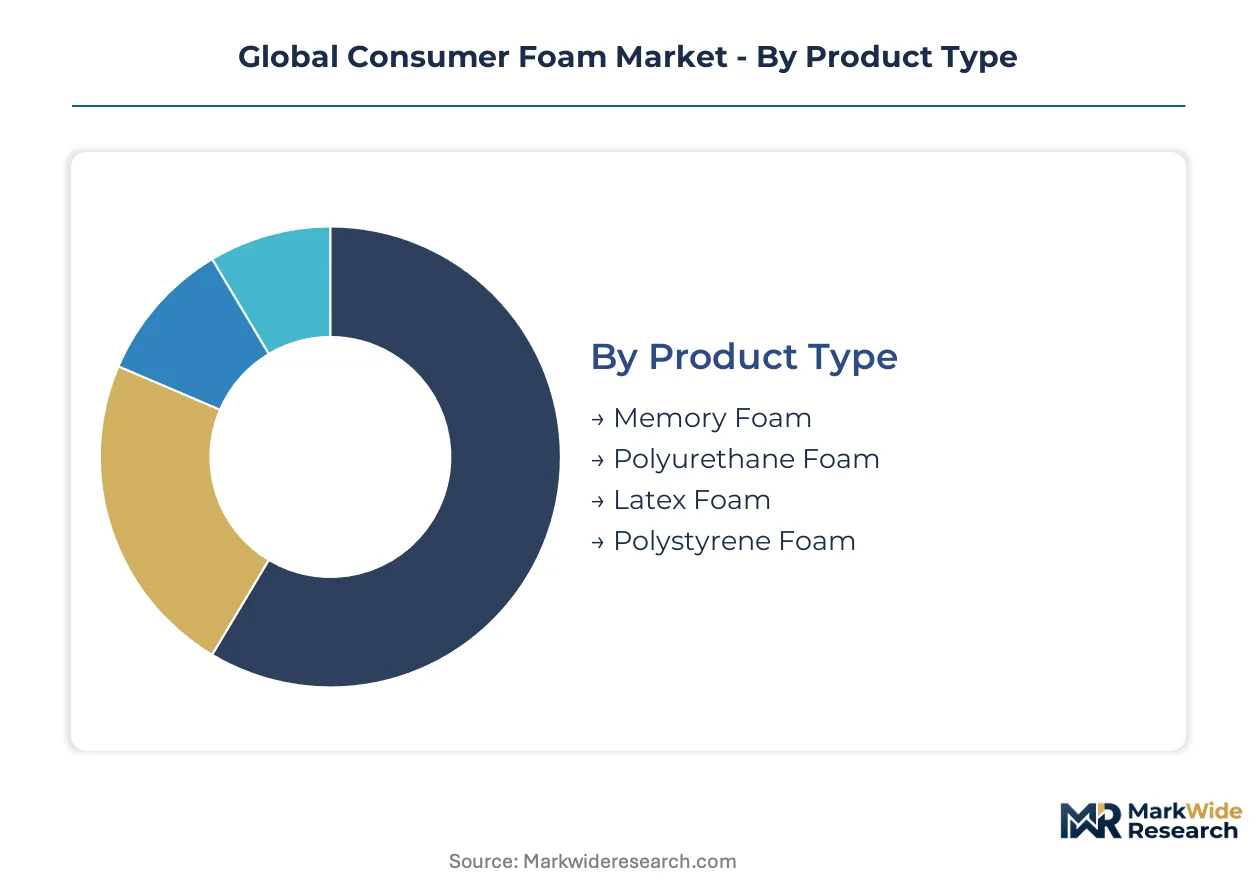
Consumer foam specifications diverge sharply across end-use contexts, with density, compression set, and VOC compliance profiles determining supplier qualification. Procurement patterns concentrate in furniture and bedding channels where slabstock and molded grades compete on cost-to-performance ratios.
Product Type:
Supply concentration in aromatic isocyanate derivatives shapes competitive positioning across material categories, with integrated polyol producers commanding formulation flexibility.
- Polyurethane Foam:Flexible slabstock and molded grades employ TDI or MDI crosslinking systems with density ranges from 18 to 45 kg per cubic meter. Furniture OEMs in China and Germany specify this material for cushioning cores due to durability-to-cost ratios and established supply chain density. REACH-compliant water-blown formulations are displacing legacy HCFC systems in European bedding procurement.
- Memory Foam:Viscoelastic polyurethane systems incorporate open-cell structures with slow recovery rates calibrated through glass-transition temperature manipulation. Direct-to-consumer mattress brands in the United States and Germany leverage pressure-mapping validation to justify premium positioning in compressed roll-pack logistics channels.
- Latex Foam:Dunlop and Talalay processes yield either natural rubber-derived or synthetic styrene-butadiene grades with inherent antimicrobial properties. Botanical sourcing claims attract health-conscious residential buyers in organic product lines.
- Polystyrene Foam:Expanded and extruded variants provide rigid insulation and protective packaging with closed-cell moisture resistance. Cold-chain logistics and appliance protection applications dominate consumption.
Polyurethane Foam absorbs the bulk of installed capacity; Memory Foam is expanding most quickly.
Application:
Cost tier differentiation separates specification pathways, with automotive and healthcare channels demanding certified grades that residential furniture buyers rarely require.
- Furniture:Upholstery cushioning and seating components utilize flexible polyurethane slabstock cut to dimension or molded for contour integration. Chinese manufacturers in the Yangtze River Delta cluster supply global OEMs through just-in-time logistics contracts.
- Bedding:Mattress cores, toppers, and pillows specify viscoelastic, latex, or high-resilience polyurethane grades based on pressure-relief marketing positioning. Compressed roll-pack fulfillment infrastructure in Germany and the United Kingdom enables direct-to-consumer brand economics.
- Automotive Interiors:Seating, headliners, and trim panels require low-VOC emission profiles meeting OEM material qualification protocols. MDI-based molded systems dominate due to structural rigidity requirements.
- Packaging:Protective inserts and insulation blocks employ expanded polystyrene or polyethylene foam with die-cut customization for electronics and pharmaceutical cold chain.
Furniture channels anchor volume procurement; Bedding applications are climbing the fastest on e-commerce penetration.
End User:
Customer type determines specification complexity, with healthcare and commercial buyers imposing certification burdens that residential channels largely bypass.
- Residential:Homeowners and renters purchase mattresses, upholstered furniture, and comfort accessories through retail or direct-to-consumer channels. Renovation intensity in China and India drives replacement cycle acceleration.
- Commercial:Hotels, offices, and retail spaces procure contract-grade seating and mattresses with fire-resistance and durability certifications. Hospitality procurement consolidation favors suppliers with multi-property logistics capability.
- Educational:Dormitory furniture and institutional seating require cost-optimized polyurethane grades with abrasion resistance for high-turnover environments.
- Healthcare:Hospitals and long-term care facilities specify antimicrobial, pressure-relief, and fluid-resistant foam grades for patient mattresses and seating. Regulatory compliance with medical device or facility sanitation standards restricts supplier pools.
Residential buyers absorb the bulk of installed capacity; Healthcare specifications are gaining share fastest on infection-control prioritization.
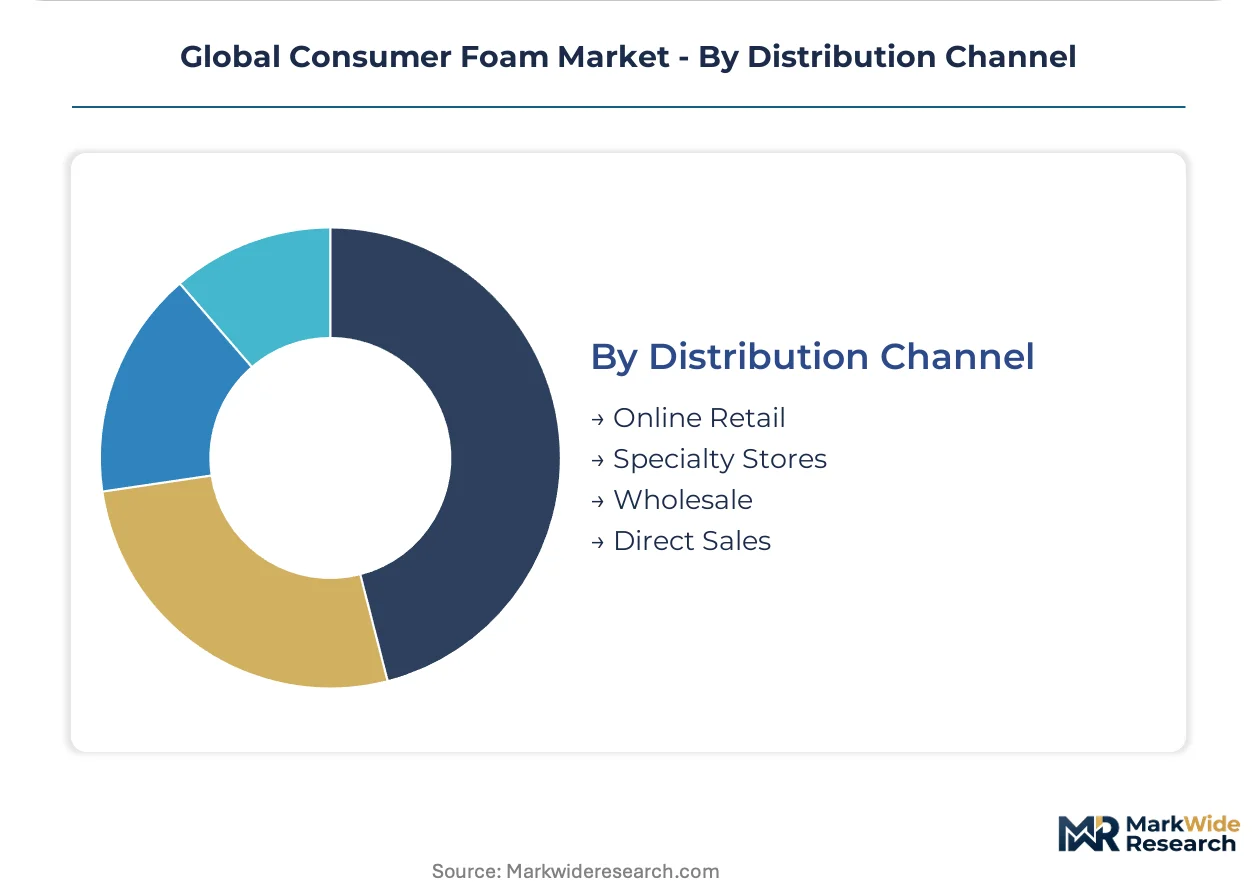
Distribution Channel:
Geography of fulfillment infrastructure determines channel economics, with last-mile density in Germany and the United Kingdom enabling compressed product handling that other markets cannot replicate.
- Online Retail:E-commerce platforms and direct-to-consumer brands ship vacuum-compressed mattresses and foam accessories to residential doorsteps. Return logistics and trial-period policies compress margin structures compared to traditional wholesale.
- Specialty Stores:Mattress showrooms and furniture galleries provide tactile evaluation and white-glove delivery services. Premium viscoelastic and latex grades dominate assortment due to higher per-unit economics.
- Wholesale:Furniture manufacturers and bedding assemblers procure slabstock and molded components through distributor networks with volume pricing and technical support.
- Direct Sales:Large-format retailers and hospitality procurement departments negotiate direct contracts with foam converters for private-label or specification-grade supply.
Specialty Stores absorb the bulk of installed capacity; Online Retail is expanding most quickly on compressed logistics maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential renovation cycles concentrate procurement volumes across four major economies where furniture and bedding supply chains have achieved critical mass. Regulatory divergence on emission standards and blowing agent protocols is fragmenting formulation requirements by jurisdiction.
China
Yangtze River Delta manufacturers are expanding slabstock output for furniture OEMs as housing retrofit rates accelerate comfort upgrade demand. The Ministry of Ecology and Environment enforces national emission standards on polyurethane production facilities in the Pearl River manufacturing cluster. Zhejiang and Jiangsu province converters supply global just-in-time logistics contracts for upholstered seating components.
Germany
Bedding retailers are consolidating procurement of REACH-compliant water-blown formulations as residential renovation intensity peaks. The ECHA framework restricts isocyanate exposure limits and mandates substitution pathways for conventional blowing agents. North Rhine-Westphalia production facilities anchor European flexible polyurethane capacity for automotive and furniture channels.
United States
Direct-to-consumer mattress brands are scaling compressed roll-pack fulfillment infrastructure as e-commerce penetration reshapes bedding distribution. The EPA enforces Clean Air Act volatile organic compound standards on foam curing and finishing operations. California and Texas production facilities face the steepest compliance timelines due to state-level air quality management district overlays.
India
Underpenetrated mattress replacement rates and urban household formation are creating white space for molded foam component suppliers. The Bureau of Indian Standards maintains certification requirements for polyurethane product safety in residential applications. Maharashtra and Gujarat manufacturing hubs are attracting capacity expansion from multinational resin-to-foam operators seeking export positioning.
Japan
Commercial construction specification is shifting toward high-performance insulation grades as building energy codes tighten. The Ministry of Economy, Trade and Industry promotes next-generation insulation foam through efficiency mandates and subsidy programs. Kanto region chemical producers are developing low-thermal-conductivity formulations for retrofit applications.
Global Consumer Foam Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based specialization and compressed logistics integration. The vendor base stratifies across integrated petrochemical conglomerates, regional foam converters, and niche sustainability-focused formulators. Three archetypes dominate: resin-integrated systems suppliers, independent slabstock specialists, and direct-to-consumer brand owners with captive formulation partnerships. Capacity expansion in India and Southeast Asia is accelerating, while European players are consolidating around REACH-compliant water-blown technology licensing.
Among integrated chemical conglomerates, BASF SE, Dow Inc., and Covestro AG exemplify the resin-to-foam archetype that commands formulation flexibility through captive polyol supply. These Germany-based and US-based entities occupy positions where backward integration into aromatic isocyanate derivatives sustains cost competitiveness against independent converters. Their market presence anchors the standard tier against which regional specialists and sustainability-focused entrants must differentiate.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Covestro AG |
| Huntsman Corporation |
| JSP Corporation |
| DuPont |
| Rogers Corporation |
| Sekisui Chemical Co., Ltd. |
| Recticel NV/SA |
| Others |
Supply Flow & Price Mechanics
EU REACH isocyanate exposure limits and water-blown formulation mandates gate qualified supply access while compressing margin structures for non-compliant producers. Premium-tier pricing power concentrates with integrated resin-to-foam operators commanding captive polyol supply chains.
Pricing Analysis
Volume procurement of standard-grade flexible polyurethane slabstock generates thin margins for independent converters, while specialty viscoelastic and bio-based grades sustain premium-mid-economy pricing differentiation through certification tiering. Price differentiation rests on REACH compliance status and bio-content percentage, with German and US buyers paying premiums for low-VOC validation. Cost compression in standard furniture cushioning is intensifying as Chinese slabstock exports flood wholesale channels. Residential furniture OEMs exhibit highest price sensitivity; healthcare procurement committees show lowest sensitivity due to mandated antimicrobial specifications.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta aromatic isocyanate production, where BASF SE and Covestro AG concentrate MDI derivative capacity. Raw material flows draw from petroleum-based polyol streams, castor oil agricultural partnerships, and TDI/MDI aromatic derivatives. Regulatory restriction risk intensifies as China MEE emission enforcement actions threaten Pearl River cluster operating permits. Distribution runs through just-in-time logistics contracts to furniture OEMs, compressed roll-pack fulfillment to direct-to-consumer brands, and distributor networks serving regional bedding assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around formulation expertise and captive raw material access, with REACH compliance timelines and water-blown R&D capex requirements forcing weaker independents toward exit or acquisition.
For Market Incumbents: To counter feedstock volatility and margin compression, BASF SE and Dow Inc. should deepen backward integration into bio-based polyol feedstocks through agricultural processor partnerships. Covestro AG must accelerate water-blown technology licensing to European converters, converting compliance cost into recurring royalty revenue while locking in formulation standardization.
For New Entrants and Emerging Players: Direct-to-consumer mattress brands represent the most penetrable channel partner type for compressed logistics specialists lacking resin integration. White space exists in India's underpenetrated molded foam component supply, where urban household formation outpaces incumbent capacity expansion. A go-to-market angle targeting antimicrobial grades for healthcare facilities bypasses retail price wars entirely.
For Investors and Strategic Acquirers: ECHA enforcement actions accelerating plant retrofits in Germany are the leading indicator that water-blown formulation expertise will command scarcity premiums. Long-term viability favors integrated operators with captive polyol supply or specialized healthcare certification positions. Acquisition targets should display either REACH-compliant production assets or established compressed logistics infrastructure. The signal to monitor is MEE emission suspension orders affecting Yangtze River Delta capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Blown Formulation Transition | REACH compliance mandates are displacing HCFC systems across European bedding supply chains. |
| Bio-Based Polyol Backward Integration | Castor oil and soybean partnerships reduce petroleum dependency for North American direct-to-consumer brands. |
| Compressed Roll-Pack Logistics Expansion | Vacuum-compressed mattress fulfillment enables e-commerce margin structures in Germany and the United Kingdom. |
| Healthcare Certification Investment | Antimicrobial and pressure-relief grades open specialized contracting channels beyond residential retail. |
| India Capacity Buildout | Maharashtra and Gujarat hubs attract multinational resin-to-foam operators seeking export positioning. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with polyurethane plant managers, furniture OEM procurement leads, bedding distributor channel partners, and technical R&D directors. Bottom-up triangulation across product-grade volume estimates and top-down validation against chemical industry production disclosures ensured cross-verification. EPA Clean Air Act enforcement records, ECHA REACH registration databases, and China MEE emission compliance filings provided regulatory constraint inputs.
Granularity-level modeling addressed density-tier specifications, end-use industry absorption rates, regional production hub capacity, and compliance-grade certification status across the analysis window. CAGRs were derived from segmented demand projection and supply-side capacity expansion schedules, incorporating residential renovation cycle intensity and e-commerce penetration trajectories as foam-intensive bedding demand drivers.
Caveats apply where feedstock volatility, regulatory enforcement acceleration, or compressed logistics infrastructure delays could materially shift the outlook. Forecasts reflect assumptions about water-blown formulation adoption curves and bio-based polyol supply scalability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Barium Borate Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Electroactive Polymers (EAP) Market