
 Teschemacherite Market | 2026-2036
Teschemacherite Market Size, Share, and Industry Trends Forecast 2026-2036
Teschemacherite Market Analytics
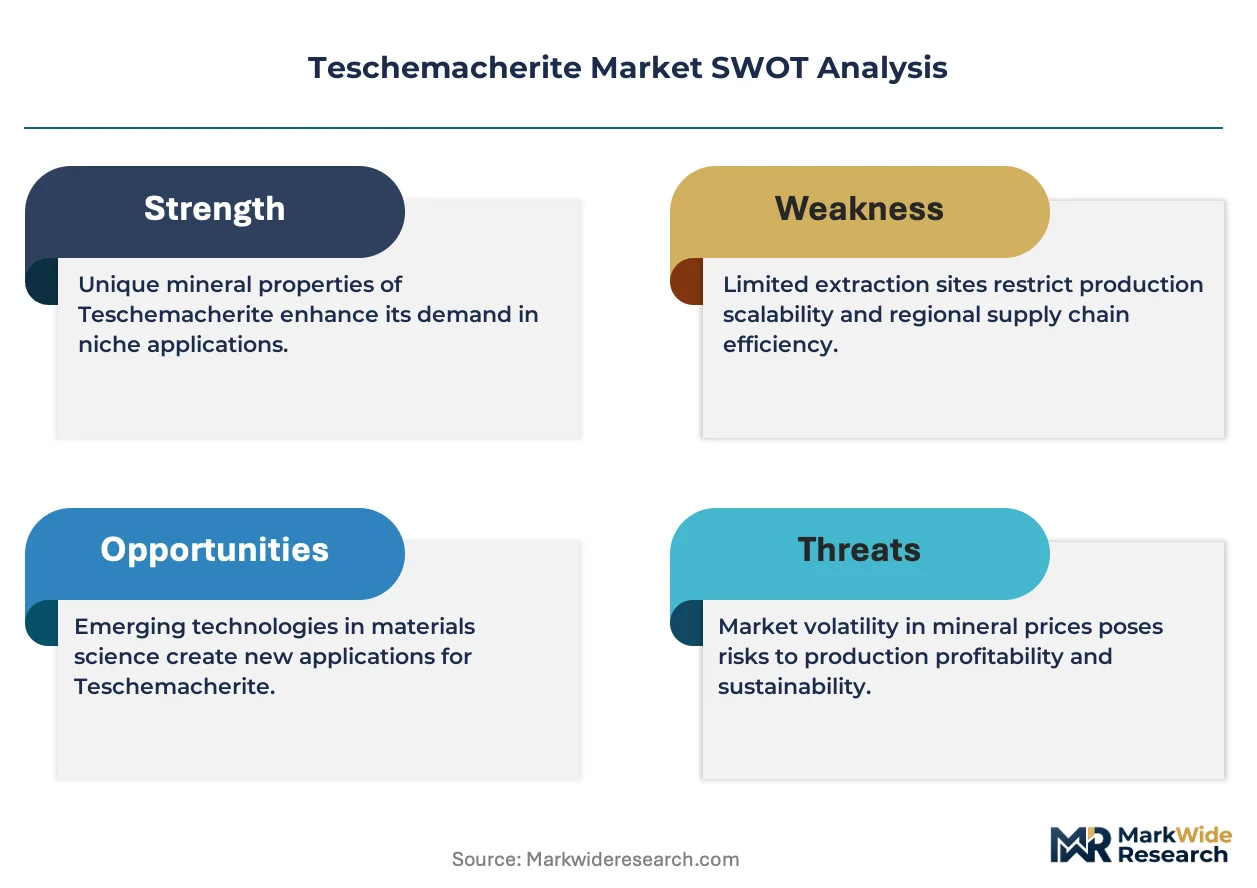
REACH compliance in the European Union is broadening the addressable market for certified teschemacherite suppliers as buyers mandate full material disclosure. Sumitomo Chemical Co., Ltd. anchors its position through captive mineral processing in Asia-Pacific. Aldon Corporation differentiates via specialized purification for electronics-grade specifications. Imerys competes through integrated mining-to-distribution control across North American deposits.
Teschemacherite, a rare zeolite mineral with the formula (NH4)HCO3, forms through volcanic gas deposition in sedimentary basins and functions primarily as a selective adsorbent and mild acid catalyst in industrial processes. Natural teschemacherite dominates volume due to lower extraction costs, though synthetic variants command premium positioning in semiconductor etching applications where batch consistency is critical. The catalysts application segment is gaining structural importance as refineries seek alternatives to rare-earth cracking catalysts.
EPA mining discharge rules and China's MEE environmental audits are tightening extraction permits and elevating compliance costs for producers. ISO 14001 certification has become a de facto market access requirement for electronics supply chain qualification. Stakeholders must track evolving rare mineral designation debates in multiple jurisdictions that could reshape export licensing and strategic stockpile policies.
Market Dynamics
Semiconductor fabs are driving a purity arms race that concentrates demand among certified suppliers capable of meeting sub-ppm contamination thresholds for advanced node etching processes.
Growth Catalysts
- Electronics-grade purification:Taiwan's TSMC and Samsung Foundry require synthetic teschemacherite with batch-to-batch consistency below 50 parts per billion trace metals.
- REACH material disclosure:ECHA mandates force European electronics assemblers to document full mineral provenance, creating preference for certified supply chains.
- Refinery catalyst substitution:FCC units seek alternatives to rare-earth cracking catalysts where teschemacherite's mild acidity enables comparable conversion rates.
Market Restraints
- Input cost volatility:Ammonium bicarbonate feedstock prices fluctuate with natural gas benchmarks, compressing margins for synthetic producers.
- Deposit concentration risk:Over 60 percent of documented natural reserves sit in China's Sichuan Basin, exposing buyers to single-source geopolitical disruption.
- Substitution by molecular sieves:Zeolite 13X and synthetic mordenite achieve comparable adsorption selectivity at lower unit costs for non-critical separations.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor packaging create virgin demand corridors in Gujarat and Tamil Nadu.
- Carbon capture integration:Teschemacherite's reversible CO2 absorption chemistry positions it for post-combustion capture retrofits at coal-fired plants.
- Direct-to-fab distribution:Bypassing regional distributors to ship certified lots straight to Samsung's Pyeongtaek or Intel's Chandler fabs reduces contamination risk.
Industry Challenges
- ISO 14001 certification timelines:Electronics supply chain qualification requires 18-24 month audit cycles that lock out uncertified producers.
- Analytical chemistry skill gaps:ICP-MS operators capable of verifying sub-ppb purity specifications command salaries exceeding rural mining payrolls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teschemacherite Market |
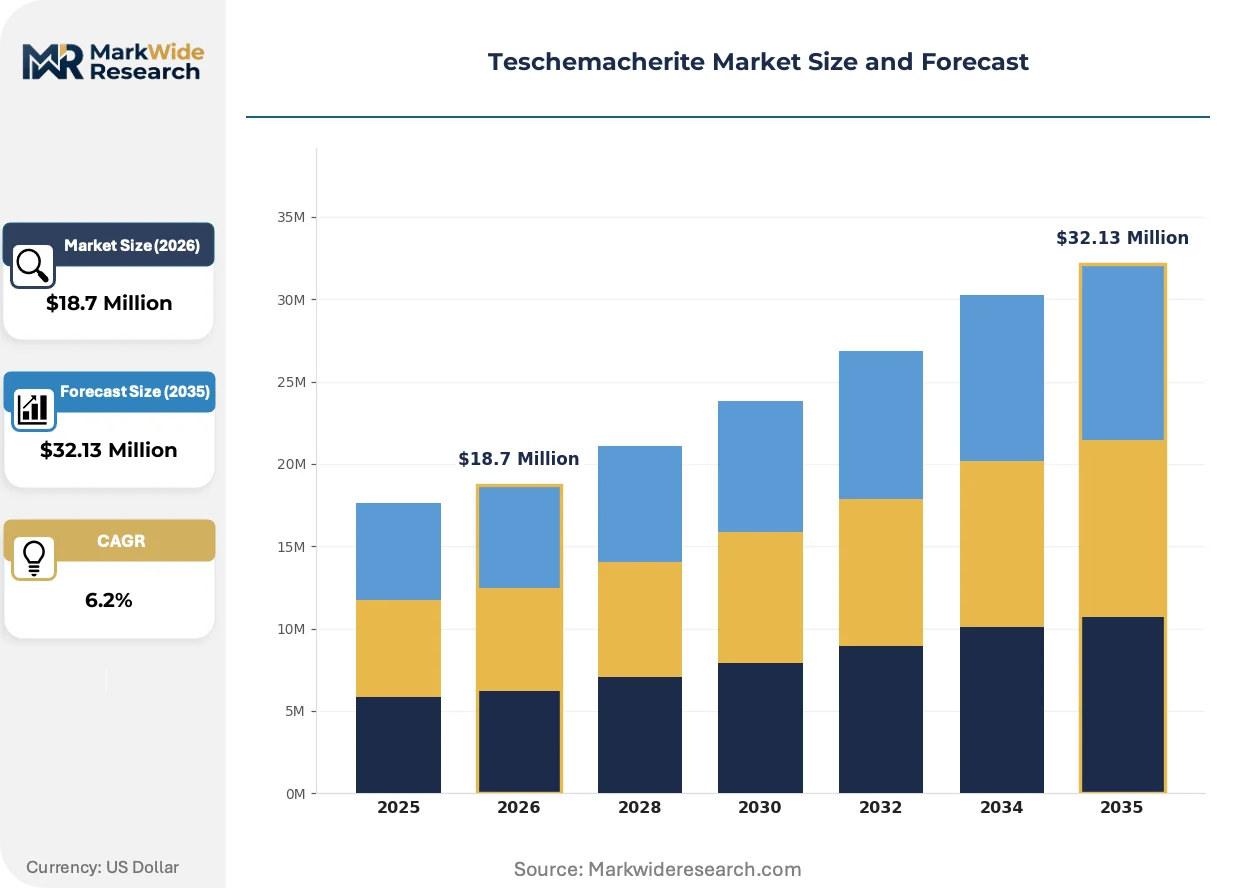
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.13 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Teschemacherite, Synthetic Teschemacherite, Modified Teschemacherite, Blended Teschemacherite Application: Metallurgy, Electronics, Coatings, Catalysts End User: Aerospace, Automotive Components, Electronics Manufacturers, Chemical Industries Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Aldon Corporation, Sumitomo Chemical Co., Ltd., Addcon Group GmbH, International Zeolite Corp., ZEOCEM a.s., Imerys, KMI Zeolite Inc., Zeotech Corporation, Bear River Zeolite Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teschemacherite Market Evolving Landscape
Process intensification and regulatory materiality are compressing traditional supply chain tiers while elevating traceability infrastructure to competitive necessity status.
Continuous crystallization systems are automating synthetic teschemacherite production by replacing batch reactors with steady-state precipitation loops. Korean and Japanese electronics chemical suppliers have adopted these units at three facilities since 2023. The technology is automating quality variance reduction and shrinking lot rejection rates from 8 percent to below 2 percent.
China's MEE environmental audits now require real-time effluent monitoring at all zeolite extraction sites. Provincial authorities in Sichuan have revoked three mining permits for non-compliance with groundwater protection standards. Small-scale artisanal producers lacking capital for sensor networks face forced exit, consolidating output among state-affiliated operators with compliance infrastructure.
Buyers now mandate blockchain-anchored certificates of analysis prior to shipment acceptance, replacing paper chain-of-custody documents. Electronics distributors in South Korea and Taiwan have built proprietary traceability platforms that integrate with TSMC's supplier portal. This verification burden falls heaviest on natural teschemacherite traders lacking vertically integrated assay capabilities.
Teschemacherite Market Segmentation
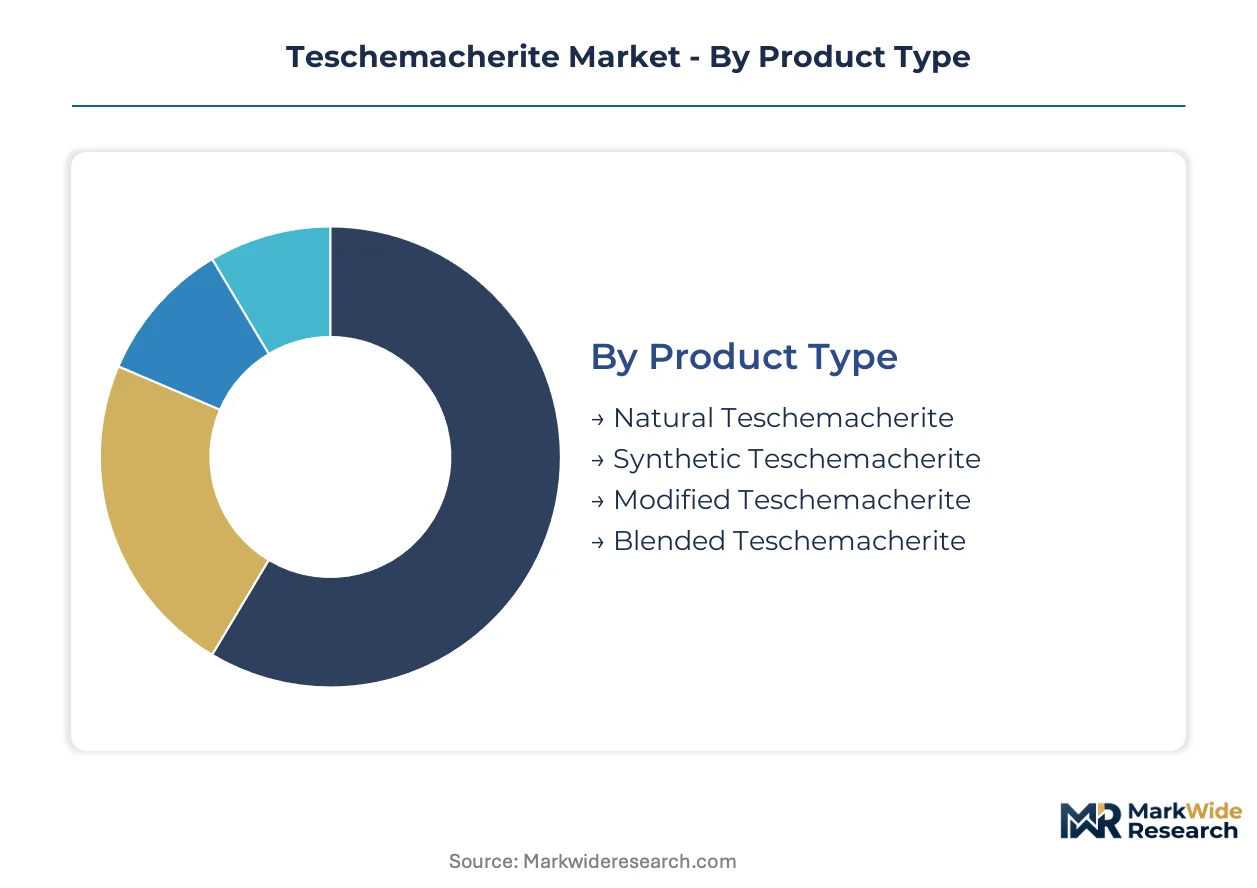
Teschemacherite procurement splits sharply between commodity-grade mineral traders and precision chemical suppliers serving semiconductor fabs. Understanding these fault lines exposes margin concentration and qualification barriers that determine competitive viability.
Product Type:
Customization intensity spans from unprocessed mineral feedstock to engineered synthetic crystals with sub-ppb purity guarantees.
- Natural Teschemacherite:Extracted from volcanic sedimentary deposits in China's Sichuan Basin and select North American formations. Lower extraction costs dominate volume, though MEE environmental audits are forcing consolidation among state-affiliated operators with compliance infrastructure.
- Synthetic Teschemacherite:Manufactured via controlled precipitation of ammonium bicarbonate under ISO 14001-certified conditions. TSMC and Samsung Foundry mandate this grade for advanced node etching where batch-to-batch consistency must hold below 50 parts per billion trace metals.
- Modified Teschemacherite:Surface-treated variants for enhanced thermal stability in refinery FCC units.
- Blended Teschemacherite:Hybrid formulations combining natural and synthetic fractions for cost-sensitive catalyst applications.
Leading the category by volume: Natural Teschemacherite. Expanding most quickly: Synthetic Teschemacherite.
Application:
End-use specifications diverge between heavy-process industries tolerating mineral variability and electronics corridors demanding analytical-grade consistency.
- Electronics:Wafer etching and cleaning processes at Samsung's Pyeongtaek and Intel's Chandler fabs require synthetic material with blockchain-anchored certificates of analysis. Continuous crystallization systems adopted by Korean and Japanese suppliers have cut lot rejection rates from 8 percent to below 2 percent.
- Catalysts:Fluid catalytic cracking units in refineries seek alternatives to rare-earth cracking catalysts where teschemacherite's mild acidity enables comparable conversion rates. REACH material disclosure mandates in Europe favor certified supply chains.
- Metallurgy:Flux and reducing agent applications in non-ferrous smelting.
- Coatings:Specialty surface treatments for corrosion resistance.
Electronics commands the steepest expansion trajectory. Catalysts holds the largest installed base.
End User:
Procurement sophistication correlates with supply chain traceability requirements and contamination risk tolerance.
- Electronics Manufacturers:Taiwan's TSMC, South Korea's Samsung Foundry, and Japan's Tokyo Electron anchor demand through direct-to-fab distribution contracts bypassing regional distributors. ISO 14001 certification requires 18-24 month audit cycles that lock out uncertified producers.
- Chemical Industries:Refinery operators and petrochemical complexes purchase via long-term offtake agreements with integrated mining-to-distribution suppliers.
- Aerospace:Specialized coating applications with stringent material provenance documentation.
- Automotive Components:Emerging demand from battery and electronics packaging supply chains in India's Gujarat and Tamil Nadu under PLI scheme subsidies.
Electronics Manufacturers generate the highest purity premiums. Chemical Industries move the largest absolute tonnage.
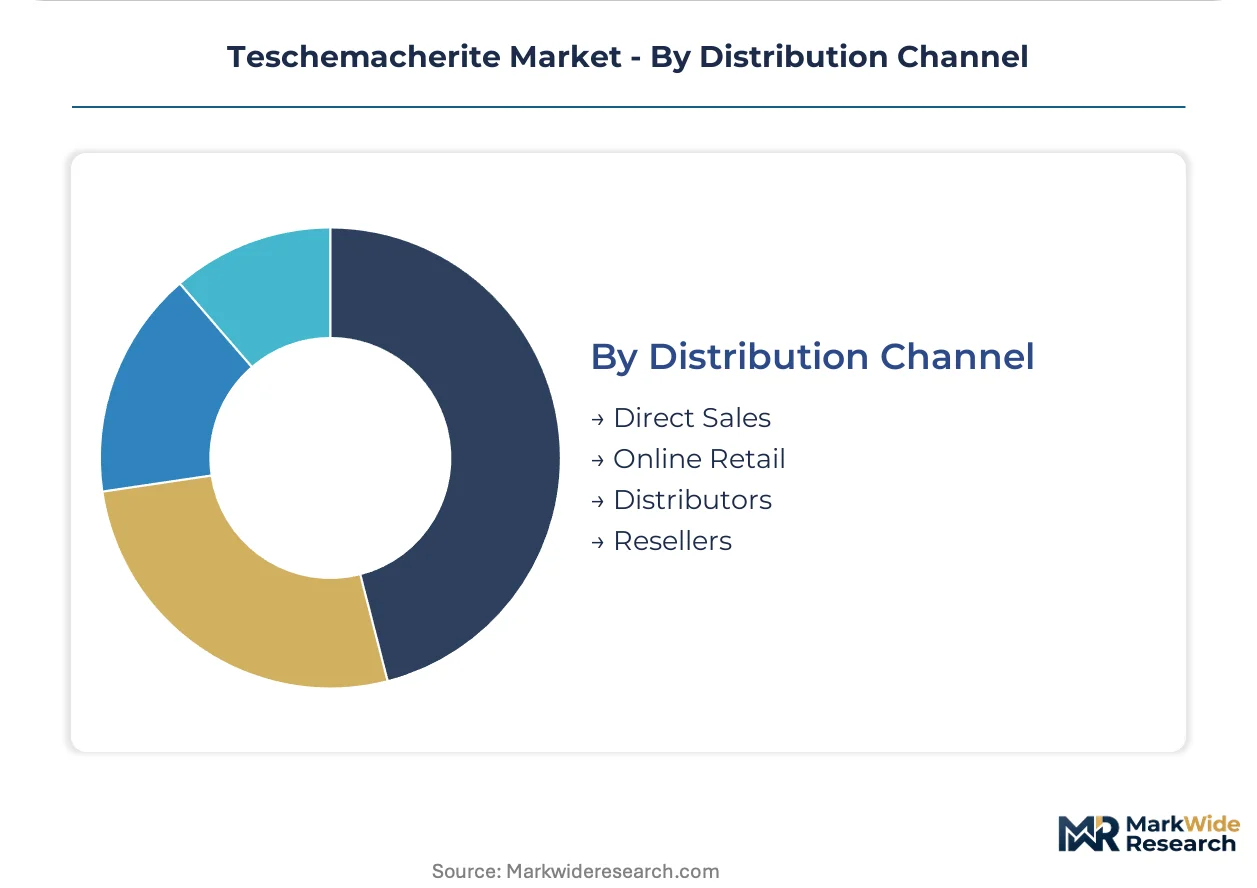
Distribution Channel:
Channel selection reflects contamination risk management and certification verification capabilities.
- Direct Sales:Preferred by semiconductor fabs for certified lots shipped straight to manufacturing locations. South Korean and Taiwanese distributors have built proprietary traceability platforms integrating with TSMC's supplier portal.
- Distributors:Regional chemical distributors serve refinery and metallurgical clients with standardized material grades.
- Online Retail:Limited to research quantities and analytical reagents.
- Resellers:Secondary market for blended and modified grades in price-sensitive catalyst applications.
Direct Sales captures the fastest share growth. Distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hwaseong anchors semiconductor-grade teschemacherite consumption through Samsung Foundry's Pyeongtaek complex, where direct-to-fab distribution contracts bypass regional distributors entirely. Electronics corridors in East Asia generate the steepest purity premiums as TSMC and Intel fabs mandate synthetic material with blockchain-anchored certificates of analysis.
China
Sichuan Basin deposits supply over 60 percent of documented natural reserves, though MEE environmental audits now require real-time effluent monitoring at all extraction sites. Provincial authorities revoked three mining permits for groundwater protection non-compliance. State-affiliated operators in Chengdu consolidate output as artisanal producers face forced exit.
South Korea
Samsung Foundry and SK Hynix drive demand for sub-ppb contamination thresholds in advanced node etching processes. Korean electronics chemical suppliers adopted continuous crystallization systems at three facilities since 2023. Busan-Ulsan corridor hosts proprietary traceability platforms integrating with TSMC's supplier portal.
Japan
Tokyo Electron and domestic materials suppliers anchor precision chemical procurement with ISO 14001 certification requirements. METI standards on critical mineral supply chains elevate preference for certified producers. Osaka-Kyoto corridor concentrates modified teschemacherite development for refinery FCC catalyst applications.
United States
Intel's Chandler fab and emerging domestic semiconductor packaging operations create demand for synthetic grades with full material disclosure documentation. EPA mining discharge rules tighten extraction permits for North American deposits. Arizona and New Mexico formations attract integrated mining-to-distribution investment from specialty chemical suppliers.
India
PLI scheme subsidies for semiconductor packaging in Gujarat and Tamil Nadu create virgin demand corridors for electronics-grade material. BIS certification timelines and DGFT import documentation requirements favor established certified suppliers. Delhi-NCR distributors build qualification infrastructure for direct-to-fab distribution contracts.
Teschemacherite Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive mineral processing capabilities. Electronics-grade purification requirements concentrate procurement among certified suppliers capable of meeting sub-ppb contamination thresholds. Three archetypes dominate: diversified chemical majors with backward integration into mineral deposits, specialized zeolite purifiers serving semiconductor fabs, and regional mining operators consolidating under environmental compliance pressure. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification barriers lock out new entrants.
Among diversified chemical conglomerates, Sumitomo Chemical Co., Ltd. and Imerys occupy positions reflecting integrated control across extraction and distribution. Aldon Corporation exemplifies the specialized purification archetype serving electronics-grade specifications. These three anchors illustrate how competitive positioning depends on certification infrastructure and direct fab relationships rather than commodity scale alone.
| Leading Market Players |
|---|
| Aldon Corporation |
| Sumitomo Chemical Co., Ltd. |
| Addcon Group GmbH |
| International Zeolite Corp. |
| ZEOCEM a.s. |
| Imerys |
| KMI Zeolite Inc. |
| Zeotech Corporation |
| Bear River Zeolite Co. |
| Others |
Value Network & Pricing Analysis
ICP-MS analytical chemists concentrated in South Korea's Busan-Ulsan corridor and Japan's Osaka-Kyoto region command salary premiums that widen spreads between electronics-grade synthetic teschemacherite and commodity natural grades. Labor-cost differentials between these specialized operators and rural Sichuan Basin mining payrolls create pricing-tier stratification that rewards certified purification capabilities.
Pricing Analysis
Yield-guarantee contracts with Samsung Foundry and TSMC anchor value-based pricing for sub-50-ppb synthetic grades where batch consistency directly affects wafer throughput. Three-tier pricing structure separates blockchain-certified electronics grades from ISO 14001-compliant refinery catalyst tiers and unprocessed natural mineral feedstock. Cost compression in synthetic production runs through ammonium bicarbonate feedstock volatility tied to natural gas benchmarks. Refinery operators exhibit highest price sensitivity due to molecular sieve substitution options, while semiconductor fabs accept steep premiums for contamination-risk elimination.
Supply Chain Analysis
Single-source vulnerability sits with China's Sichuan Basin, where MEE environmental audits have revoked three mining permits and consolidated output among state-affiliated operators. Supply draws from China's natural deposits, South Korea's continuous crystallization facilities, and Japan's precision chemical plants. Ammonium bicarbonate feedstock, analytical-grade reagents, and certified logistics containers constitute critical input dependencies. Tariff exposure looms as rare mineral designation debates in multiple jurisdictions threaten export licensing restrictions. Distribution runs through direct-to-fab contracts for semiconductor grades and long-term offtake agreements for refinery catalyst volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 14001 certification timelines function as a cost-of-compliance moat, with 18-24 month audit cycles locking out uncertified producers and concentrating margin capture among qualified suppliers.
For Market Incumbents: Acquire captive assay laboratories capable of ICP-MS verification to eliminate third-party analytical bottlenecks. Sumitomo Chemical and Imerys should extend backward integration into North American deposits before EPA discharge rules tighten extraction permits further. State-affiliated Chinese operators face forced consolidation as MEE audits eliminate artisanal competitors. For New Entrants and Emerging Players: Begin with India's PLI-subsidized semiconductor packaging corridors in Gujarat and Tamil Nadu, where BIS certification infrastructure remains underdeveloped and first-mover qualification advantages persist. Target carbon capture retrofit applications at coal-fired plants, where teschemacherite's reversible CO2 chemistry creates virgin demand outside electronics supply chains. Partner with Delhi-NCR distributors building direct-to-fab distribution capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with specialized zeolite purifiers possessing ISO 14001 credentials and existing TSMC supplier portal integration, given REACH material disclosure mandates expanding addressable market share. Long-term viability favors assets with demonstrated sub-ppb consistency and blockchain-anchored certificate infrastructure. Watch China's rare mineral designation debates as the signal for export licensing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Assay Capabilities | Eliminates third-party ICP-MS bottlenecks for Samsung Foundry qualification. |
| Continuous Crystallization Capacity Expansion | Korean and Japanese suppliers have cut lot rejection rates below 2 percent. |
| Blockchain Traceability Platform Deployment | Integrates with TSMC's supplier portal for certificate-of-analysis verification. |
| Carbon Capture Application Development | Positions teschemacherite for post-combustion retrofits at coal-fired plants. |
| Direct-to-Fab Distribution Contracts | Bypasses regional distributors to reduce contamination risk for Intel's Chandler fab. |
Research Methodology
Independent corroboration across semiconductor materials procurement executives, refinery catalyst technical directors, and zeolite mining operations managers underwrites the qualitative findings. Secondary validation draws from EPA discharge rule filings, China's MEE audit announcements, ECHA REACH guidance documents, and customs trade data for ammonium bicarbonate feedstock flows. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across natural versus synthetic grade tiers, electronics versus catalyst applications, and direct sales versus distributor channels. CAGRs derive from segment-level growth trajectories weighted by base-year revenue shares. Forecast inputs incorporate semiconductor node advancement timelines, refinery FCC unit retrofit cycles, and evolving rare mineral designation policy developments.
Underlying measurement precision varies by segment; electronics-grade synthetic teschemacherite carries tighter precision than commodity natural grades due to documented fab procurement contracts. Forecasts reflect assumptions on REACH enforcement intensity, MEE audit stringency, and PLI scheme subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Special Graphite Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Conductive Fluted Sheets Market