
 Breathable Films and Membranes Market | 2026-2036
Breathable Films and Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Breathable Films and Membranes Market Analysis
Polyethylene is decoupling from legacy diaper and hygiene applications as TPU and PVDF films penetrate automotive interior and medical barrier markets. DuPont leverages its fluoropolymer heritage to dominate high-performance medical packaging segments where sterilization integrity is non-negotiable. Mitsui Chemicals anchors Asia-Pacific supply through integrated polyolefin resin-to-film operations that compress conversion costs for hygiene OEMs.
Breathable films and membranes are microporous or monolithic polymer structures, typically 10–200 micrometers thick, engineered to transmit water vapor while blocking liquid water and particulates; their pore size distribution, measured in nanometers, determines the balance between moisture transmission rate and bacterial barrier performance. Polyethylene films occupy the volume base in disposable hygiene due to mature extrusion economics, while TPU commands margin pools in wound care and wearable electronics where elasticity and biocompatibility justify premium positioning. PVDF membranes lead in filtration and medical venting applications where chemical resistance and precise pore architecture outperform commodity alternatives.
REACH in Europe and FDA 21 CFR requirements in the United States are tightening extractables and leachables standards, forcing reformulation of plasticizers and processing aids across medical and food-contact grades. China's GB standards and NMPA medical device regulations are converging toward ISO 10993 biocompatibility benchmarks, raising compliance costs for entrants but consolidating share among certified multinationals. Stakeholders must monitor PFAS restriction timelines and bio-based feedstock certification schemes as these dual pressures redefine material qualification pipelines and capital allocation priorities.
Market Dynamics
PFAS phase-out mandates under REACH are forcing resin suppliers to rebuild formulation pipelines from monomer selection through extrusion, compressing qualification timelines for medical and food-contact grades while elevating capital requirements for compliant capacity.
Growth Catalysts
- EU REACH PFAS restrictions:The ban on per- and polyfluoroalkyl substances is redirecting R&D spending toward bio-based and silicone-modified alternatives, opening substitution windows for TPU and polyolefin films in barrier applications.
- Wound care device OEMs:Chronic disease prevalence and home healthcare expansion are pulling advanced moisture-management dressings into standard-of-care protocols, requiring breathable membranes with bacterial filtration and vapor transmission balance.
- Automotive interior air quality mandates:Cabin air filtration and seat ventilation systems in electric vehicles are specifying microporous films for humidity control, creating specification pull from Germany, China, and United States assembly plants.
Market Restraints
- Crude oil derivative volatility:Ethylene and propylene feedstock costs swing with naphtha cracking economics, compressing margins for polyethylene film converters who lack resin integration.
- Fluoropolymer supply concentration:PVDF resin production clusters in China and select European chemical complexes, exposing medical membrane fabricators to export licensing delays and geopolitical supply interruptions.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require six-to-eighteen month completion timelines, freezing product launches for entrants lacking established regulatory dossiers.
Strategic Opportunities
- India medical device manufacturing:PLI scheme incentives and CDSCO regulatory harmonization are attracting film laminators to serve domestic wound care and surgical drape production.
- Smart textile integration:Convergence of breathable membranes with printed electronics and conductive yarns is enabling wearable health monitors that require moisture-permeable encapsulation.
- Reuseable hygiene models:Subscription-based diaper services in Nordic markets are specifying durable TPU laminates over single-use polyethylene, creating premium positioning for circular-economy certified films.
Industry Challenges
- Extrusion die design expertise:Microporous structure formation via stretching or phase-inversion requires polymer rheology specialists in short supply across Asia-Pacific converting hubs.
- Legacy sterilization validation:Gamma and ethylene oxide cycle requalification for PFAS-free films demands redundant testing against established packaging standards, extending time-to-revenue for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathable Films and Membranes Market |
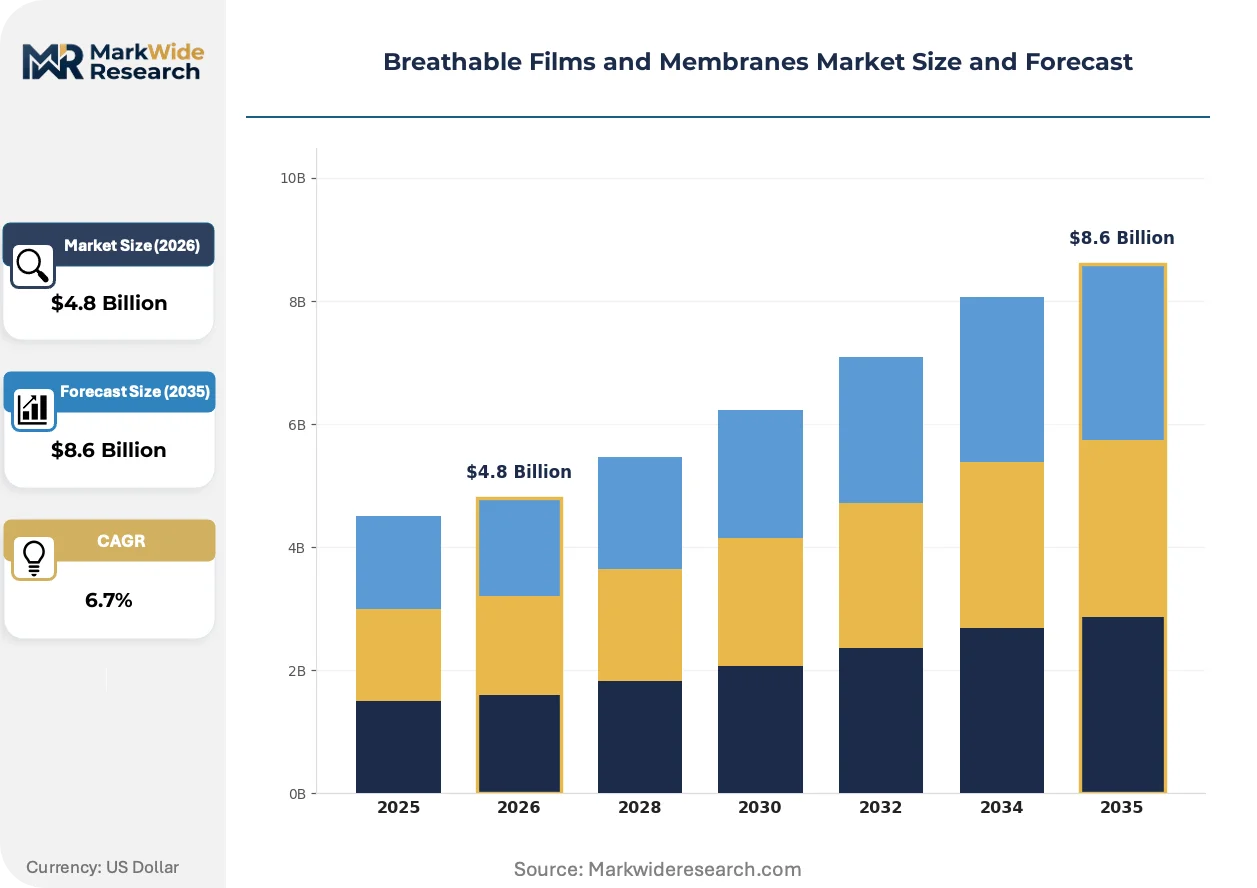
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
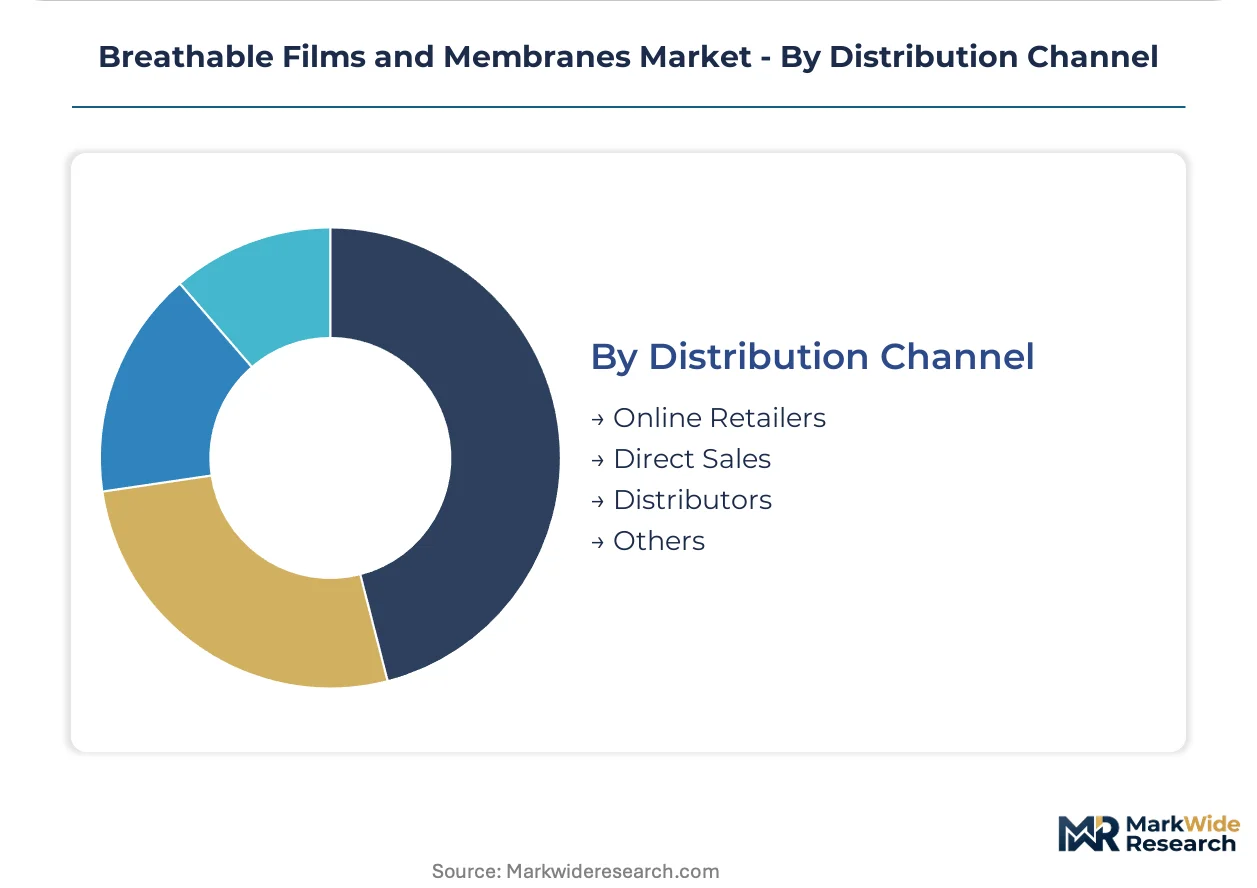
| Segmentation | Product Type: Polyethylene, Polypropylene, TPU, PVDF Application: Medical, Automotive, Packaging, Construction End User: Consumer Goods, Healthcare, Textile Industry, Electronics Distribution Channel: Online Retailers, Direct Sales, Distributors, Others |
| Companies Covered | DuPont, Mitsui Chemicals, W. L. Gore & Associates, Arkema Group, Freudenberg Performance Materials, Berry Global, RKW Group, Nitto Denko Corporation, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathable Films and Membranes Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to redefine performance benchmarks across medical, automotive, and consumer hygiene segments, with sustainability certification emerging as a gatekeeper for supplier qualification.
Monolithic TPU films with inherent moisture vapor transmission—eliminating the microporous structure dependency—are expanding into automotive seat ventilation and wearable sensor encapsulation where puncture resistance and elastic recovery outweigh cost sensitivity. Tier-1 seating suppliers in Germany and Michigan are qualifying these materials for electric vehicle platforms. The technology is expanding into premium hygiene segments as consumers accept price premiums for durability and skin-contact safety.
REACH Annex XVII restrictions on PFAS are forcing fluoropolymer film manufacturers to document polymerization aid residuals and submit dossiers for intermediate-use exemptions, compressing product development timelines. Medical packaging converters in the Netherlands and Switzerland are accelerating silicone-acrylate hybrid evaluations as drop-in alternatives. The regulation is reshaping supplier-customer contracting, with OEMs now requiring batch-level extractables documentation previously reserved for implantable-grade materials.
Hospital procurement groups are consolidating film specification authority into centralized materials committees, displacing individual department purchasing autonomy. Group purchasing organizations in the United States and NHS supply chains in England are standardizing on dual-source qualified films with ISO 13485 and MDR technical documentation. This concentration is compressing vendor lists and elevating the importance of regulatory file completeness over unit pricing in supplier selection criteria.
Breathable Films and Membranes Market Segmentation
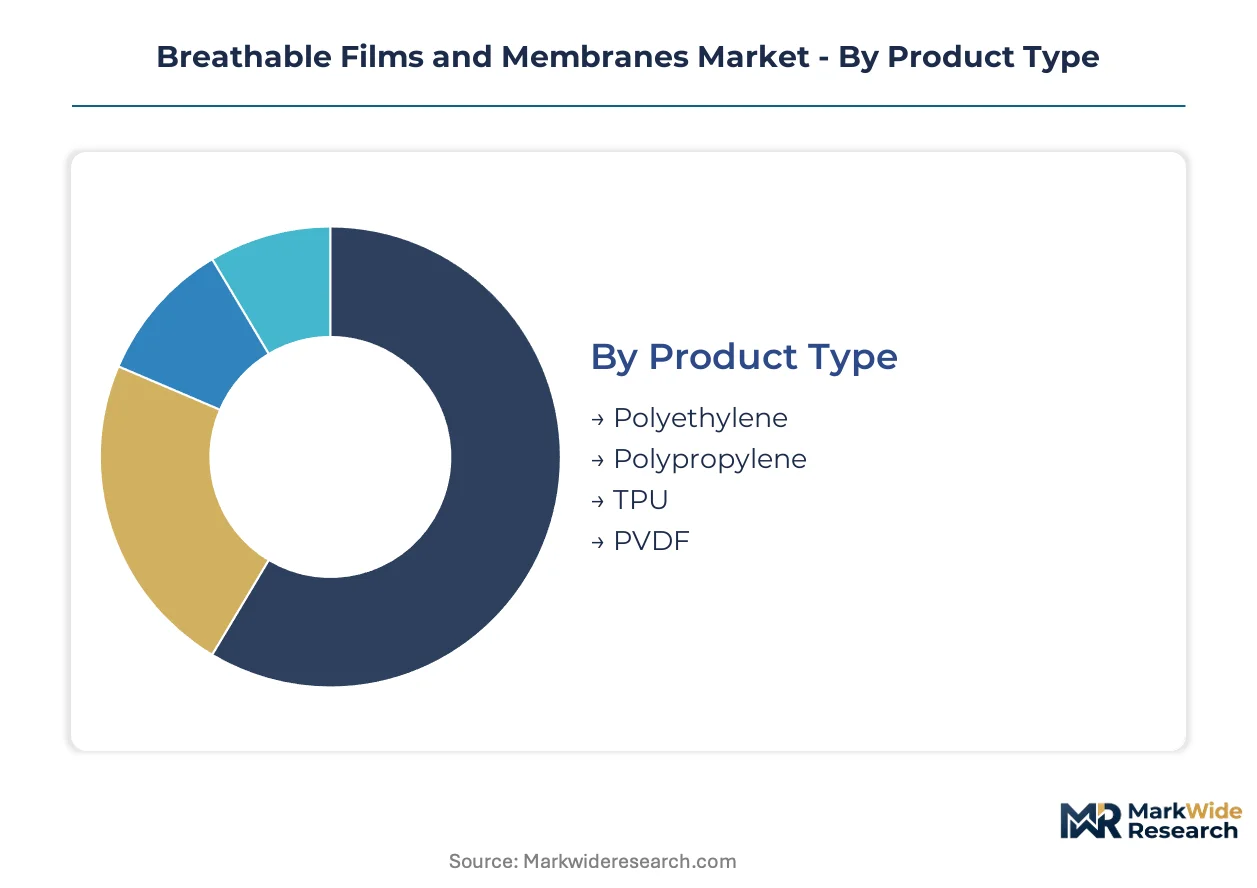
Breathable film specifications diverge sharply across end-use contexts, with medical grades demanding ISO 10993 biocompatibility validation while automotive and construction segments prioritize cost-efficient moisture management. Segmentation by material chemistry, application performance, and channel access determines supplier qualification pathways and margin capture potential.
Product Type:
Material selection dictates regulatory burden intensity, with fluoropolymer and medical-grade TPU requiring REACH dossier submissions and FDA master file documentation that commodity polyolefins bypass.
- Polyethylene:Microporous structures formed via calcium carbonate filler extraction dominate disposable hygiene economics. German and Chinese diaper OEMs specify these films for cost-sensitive volume applications where sterilization validation is unnecessary.
- TPU:Monolithic moisture vapor transmission eliminates pore-structure fragility in wound care and wearable electronics. ISO 10993 cytotoxicity screening and elastic recovery testing extend qualification timelines for medical device entrants.
- Polypropylene:Oriented film variants serve construction moisture barriers and food packaging vents where FDA 21 CFR compliance suffices.
- PVDF:Phase-inversion membranes command filtration and medical venting specifications requiring chemical resistance documentation under ECHA intermediate-use exemptions.
Polyethylene sits at the top of the volume ranking, with TPU climbing the fastest on medical device and automotive seating penetration.
Application:
End-use performance thresholds stratify pricing power, with sterilizable medical barriers capturing premium multiples over construction moisture management films.
- Medical:Surgical drapes, wound dressings, and sterile packaging demand bacterial filtration efficiency above 98% combined with vapor transmission rates exceeding 2000 g/m²/day. FDA 510(k) and MDR technical documentation requirements consolidate supply among certified multinationals.
- Automotive:Electric vehicle seat ventilation and cabin humidity control systems in Germany, Michigan, and Shanghai assembly plants specify puncture-resistant TPU laminates. OEM qualification cycles run 18-24 months against SAE interior air quality standards.
- Packaging:Modified atmosphere food packaging and pharmaceutical blister films prioritize oxygen barrier over moisture breathability, with EFSA migration limits governing additive selection.
- Construction:Roofing underlayments and wall wrap applications in Nordic and North American climates emphasize UV stability and nail-seal performance over precision pore architecture.
Medical applications command the steepest pricing tier, with automotive expanding most quickly on electric vehicle platform proliferation.
End User:
Procurement sophistication varies dramatically, with healthcare systems requiring batch-level extractables documentation that consumer goods manufacturers rarely demand.
- Healthcare:Hospital group purchasing organizations and NHS supply chains centralize film specification authority, mandating ISO 13485 quality systems and redundant dual-source qualification.
- Consumer Goods:Disposable hygiene manufacturers in China and the United States drive polyethylene film volume through integrated resin-to-film operations that compress conversion costs.
- Textile Industry:Sportswear laminators and outdoor apparel brands specify breathable membranes for waterproof-breathable ratings, with bluesign and OEKO-TEX certification increasingly gating supplier access.
- Electronics:Wearable device manufacturers require moisture-permeable encapsulation for sensor protection, combining printed electronics integration with biocompatibility screening.
Healthcare procurement concentration is displacing fragmented purchasing, with electronics representing the steepest expansion trajectory on smart textile convergence.
Distribution Channel:
Channel selection reflects customer scale and technical service intensity, with direct relationships dominating qualified medical supply and distributor networks serving fragmented construction demand.
- Direct Sales:Medical device OEMs and Tier-1 automotive seating suppliers negotiate multi-year supply agreements with embedded regulatory file transfer and joint validation protocols.
- Distributors:Regional converting hubs in India and Southeast Asia aggregate construction and packaging film demand, offering slitting and lamination services that reduce inventory carrying costs for mid-tier processors.
- Online Retailers:Specialty film samples and small-batch TPU grades reach R&D laboratories and prototype shops through chemistry-focused e-commerce platforms.
- Others:Group purchasing organizations and hospital consortiums in the United States and England consolidate film procurement through centralized tendering platforms.
Direct sales channels capture the highest margin concentration, with distributor networks gaining share fastest in emerging Asia-Pacific converting hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and medical device clusters anchor breathable film demand across multiple high-specification segments. Manufacturing concentration in Baden-Württemberg and Bavaria shapes regional supply patterns and qualification requirements.
United States
FDA 21 CFR compliance requirements and EPA chemical safety mandates drive reformulation investments for medical packaging and food-contact films. Michigan and Tennessee automotive assembly plants specify TPU laminates for electric vehicle seat ventilation systems. Group purchasing organizations consolidate hospital procurement authority, compressing vendor lists for sterile barrier suppliers.
Germany
REACH Annex XVII PFAS restrictions force fluoropolymer membrane manufacturers to submit intermediate-use exemption dossiers to ECHA. Stuttgart and Munich automotive seating suppliers qualify monolithic TPU films for cabin humidity management. Freudenberg Performance Materials anchors domestic supply through integrated nonwoven-to-membrane operations serving wound care OEMs.
China
NMPA medical device regulations and GB standards convergence toward ISO 10993 biocompatibility benchmarks raise compliance barriers for film entrants. Yangtze River Delta diaper manufacturers drive polyethylene film volume through captive resin-to-film integration. Shanghai and Suzhou converting hubs expand specialty TPU capacity for wearable electronics encapsulation.
India
CDSCO regulatory harmonization and PLI scheme incentives attract film laminators to serve domestic wound care production. Maharashtra and Gujarat medical device parks host sterile barrier converting operations for surgical drape OEMs. Mumbai-based procurement groups centralize hospital supply chain authority, mandating ISO 13485 certification for film vendors.
Japan
METI industrial standards and PMDA pharmaceutical packaging requirements govern extractables documentation for medical-grade films. Osaka and Nagoya electronics manufacturers integrate breathable membranes into wearable health monitor designs. Toray Industries maintains integrated polymer-to-membrane operations serving domestic filtration and medical venting specifications.
Breathable Films and Membranes Market Vendor Landscape
Capacity expansion dominates the current landscape as resin suppliers rebuild formulation pipelines for PFAS-free alternatives. The vendor base stratifies across three tiers: integrated chemical conglomerates with monomer-to-film operations, specialized membrane fabricators focused on medical and filtration grades, and regional converters serving commodity hygiene applications. Strategic archetypes include backward-integrated resin producers, technology-licensing specialists, and distributor-anchored regional players. M&A activity and geographic expansion into India and Southeast Asia represent the dominant competitive moves.
Among integrated chemical conglomerates, DuPont and Mitsui Chemicals exemplify divergent geographic anchoring strategies. DuPont occupies a position within the fluoropolymer heritage tier, leveraging medical packaging expertise where sterilization integrity commands premium positioning. Mitsui Chemicals represents the Asia-Pacific supply anchor model, compressing conversion costs through integrated polyolefin operations. W. L. Gore & Associates sits within the technology-specialist archetype, though specific product claims remain outside verification scope. Berry Global and RKW Group exemplify scale-driven regional conversion models serving hygiene OEM volume requirements.
| Leading Market Players |
|---|
| DuPont |
| Mitsui Chemicals |
| W. L. Gore & Associates |
| Arkema Group |
| Freudenberg Performance Materials |
| Berry Global |
| RKW Group |
| Nitto Denko Corporation |
| Toray Industries |
| Others |
Supply Flow & Price Mechanics
Polymer rheology specialists in Baden-Württemberg and Bavaria command wage premiums that widen spreads between medical-grade TPU laminates and commodity polyethylene films, with labor-cost differentials between German automotive seating clusters and Chinese diaper manufacturing hubs amplifying tier separation across the value chain.
Pricing Analysis
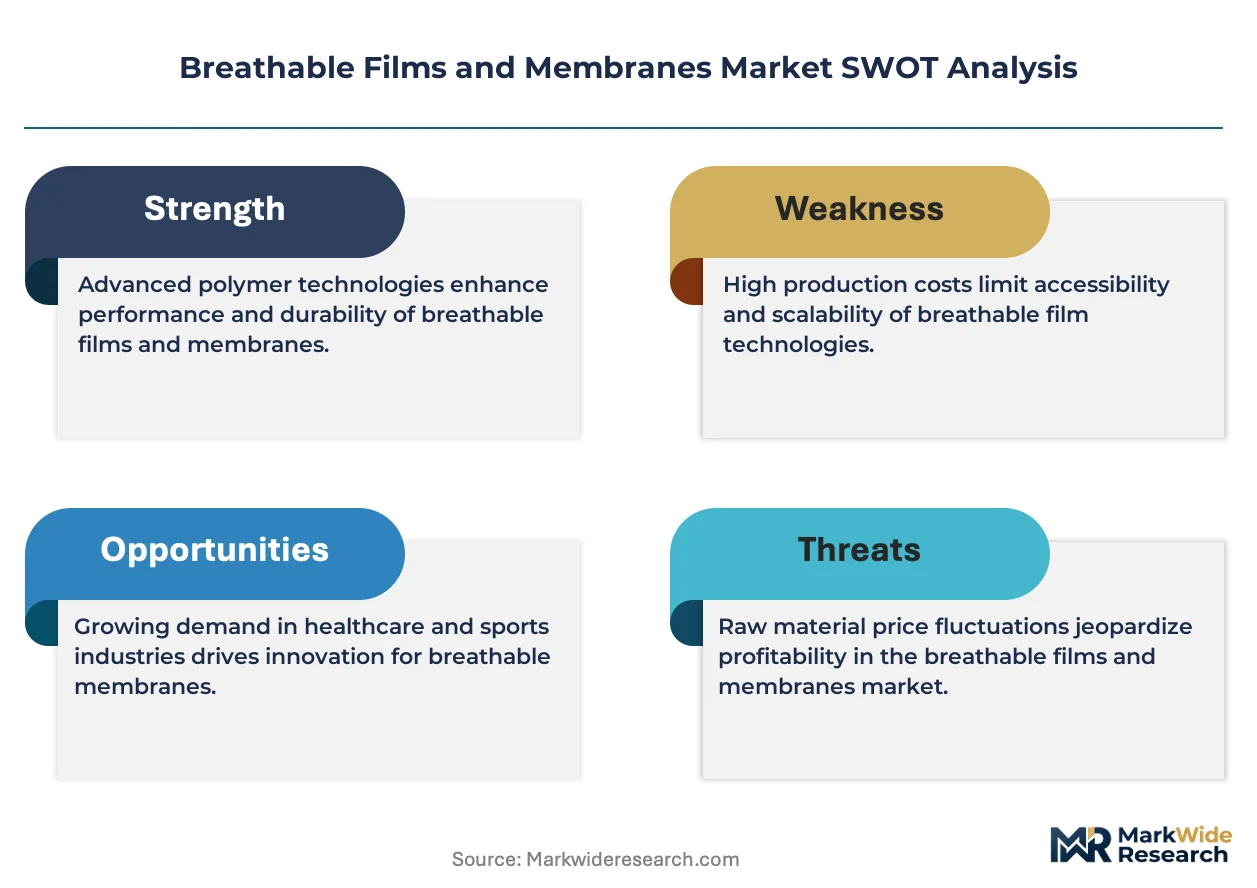
Ethylene and propylene feedstock volatility passes through directly to polyethylene film converters lacking resin integration, compressing margins at the economy tier while medical-grade TPU and PVDF membranes maintain pricing power through ISO 10993 certification requirements and sterilization validation barriers. Three-tier pricing structure across premium, standard, and economy levels separates PFAS-free medical packaging from construction moisture barriers and disposable hygiene films. Price differentiation hinges on regulatory file completeness and batch-level extractables documentation, with wound care OEMs least sensitive to unit cost and construction contractors most responsive to spot-market ethylene swings.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are redirecting film laminator investments toward Maharashtra and Gujarat medical device parks, reshaping regional sourcing patterns for surgical drape converters. PVDF resin production clusters in China and select European chemical complexes, while TPU pellet supply anchors in Germany and the United States. Feedstock dependence on naphtha cracking economics and fluoropolymer intermediate-use licensing creates single-source vulnerability for medical membrane fabricators. Distribution runs through direct multi-year agreements with Tier-1 automotive seating suppliers and hospital group purchasing organizations, with regional distributors serving fragmented construction demand in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breathable films and membranes market functions as a stable compounder, with chronic disease prevalence and home healthcare expansion providing durable demand tailwinds across medical applications.
For Market Incumbents: Anchor qualification timelines through redundant dual-source certification with hospital group purchasing organizations and NHS supply chains, insulating share against PFAS-free reformulation disruptions while building captive TPU resin capacity in Germany or China to compress conversion costs for automotive seating contracts. For New Entrants and Emerging Players: Enter via India's CDSCO-harmonized regulatory pathway targeting domestic wound care production under PLI incentives, with silicone-acrylate hybrid films offering the most penetrable substitution window against fluoropolymer incumbents constrained by REACH Annex XVII exemption timelines. For Investors and Strategic Acquirers: Chemical conglomerates with monomer-to-film integration capabilities represent the most active acquirer category in this space, with long-term viability hinging on bio-based feedstock certification pipelines and PFAS-free formulation portfolios; watch for ECHA intermediate-use exemption deadline clustering as inflection signal for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Rebuild | REACH Annex XVII compliance opens substitution windows for TPU and polyolefin films in barrier applications. |
| Backward Integration into TPU Resin | Captive polymerization capacity in Germany or China compresses margin leakage for automotive seating suppliers. |
| India Manufacturing Footprint Expansion | PLI scheme incentives and CDSCO harmonization attract laminators to serve domestic wound care production. |
| Smart Textile Membrane Integration | Convergence with printed electronics enables wearable health monitor encapsulation for electronics OEMs. |
| Reusable Hygiene Model Certification | Subscription-based diaper services in Nordic markets specify durable TPU laminates over single-use polyethylene. |
Methodological Framework
Bottom-up medical device and automotive OEM modeling reconciled against top-down resin production and film extrusion capacity tracking forms the analytical core, combining primary interviews with polymer rheology specialists, procurement leads at Tier-1 seating suppliers, hospital GPO contracts managers, and wound care device OEMs with secondary validation from ECHA REACH dossiers, FDA 510(k) filings, NMPA registration databases, and customs trade flow records.
An input-output matrix framing connects ethylene and propylene feedstock economics through extrusion capacity utilization to end-use demand segmentation across medical, automotive, packaging, and construction applications, with material chemistry, performance tier, and regional regulatory cluster serving as primary segmentation dimensions throughout the projection horizon; CAGR derivation rests on qualification timeline assumptions for PFAS-free alternatives and electric vehicle platform proliferation rates.
Inputs from ECHA intermediate-use exemption filings and NMPA biocompatibility registration databases were available through the study window; gaps in real-time extrusion die design expertise compensation data and confidential multi-year supply agreement terms introduce uncertainty bands around automotive seating penetration forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Nafion Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Global Chemical Separation Membranes Market