
 Silver Sulphate Market | 2026-2036
Silver Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Sulphate Market Outlook
High-purity grade specification is bifurcating the competitive landscape as buyers in electronics and pharmaceuticals enforce tighter impurity thresholds. Merck KGaA leverages its analytical standards heritage to dominate laboratory-grade distribution in Western Europe. American Elements anchors North American supply through its in-house refining capabilities and rare metal portfolio breadth. Thermo Fisher Scientific Inc competes by integrating silver sulphate into its broader research chemicals catalog, capturing institutional procurement workflows.
Silver sulphate (Ag₂SO₄) is an inorganic salt with a molecular weight of 311.8 g/mol, produced through the reaction of silver nitrate with sulfuric acid or by electrolytic oxidation of silver in sulfuric acid medium; it serves primarily as a selective oxidant in organic synthesis, a precursor for silver-based catalysts, and a reagent in analytical chemistry. Powder form commands the largest volume share due to its handling efficiency in catalyst manufacturing and water treatment dosing systems, while crystal form carries premium positioning for electronics plating applications where dissolution kinetics must be precisely controlled. High-purity product type captures the fastest expansion as semiconductor fabricators and advanced pharmaceutical developers mandate sub-ppm metallic impurity profiles.
EPA drinking water regulations and REACH substance restrictions are elevating compliance costs for technical-grade producers while creating certification barriers for new entrants. ISO 17025 laboratory accreditation and USP monograph compliance increasingly determine supplier eligibility in pharmaceutical and research end-user segments. Stakeholders must monitor how evolving battery recycling directives in the European Union reshape silver recovery economics and secondary supply availability.
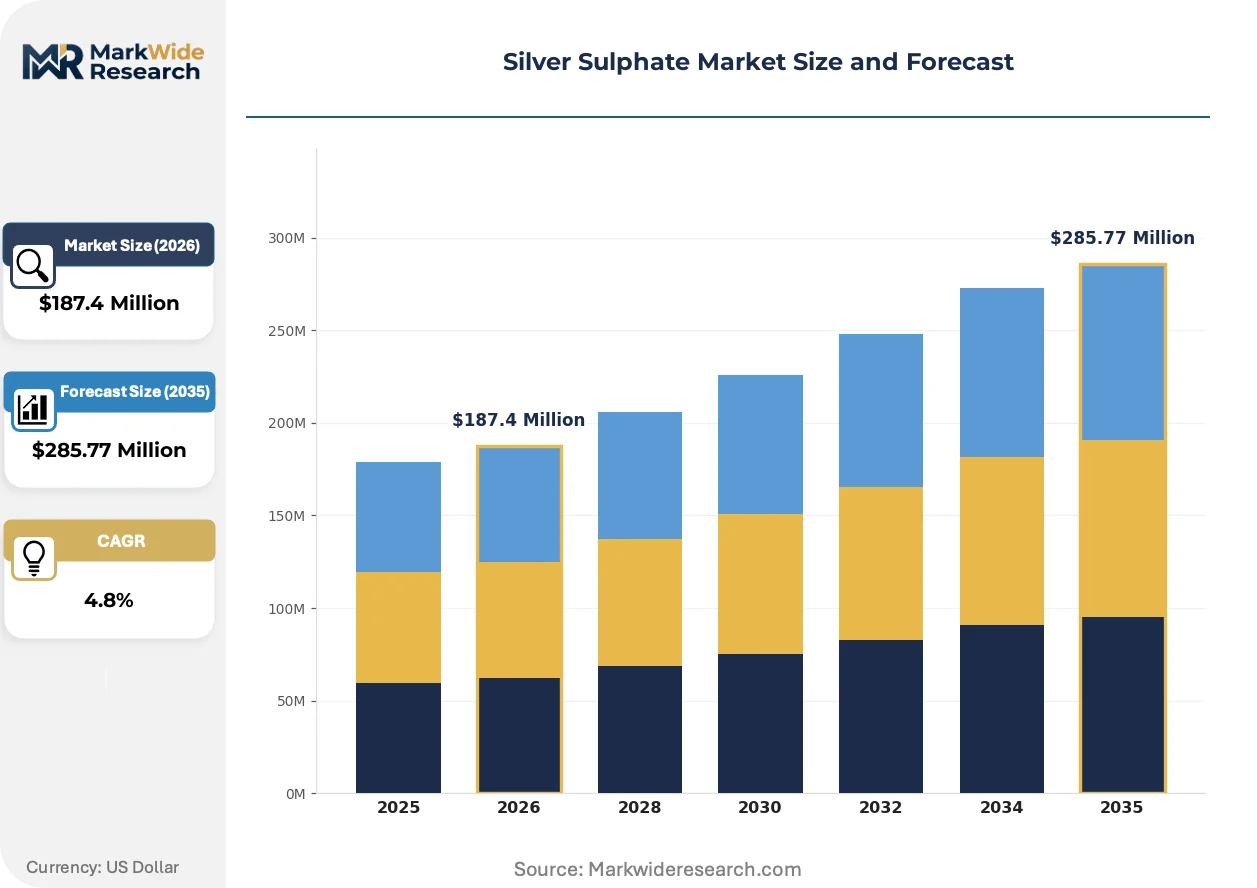
Market Dynamics
Purity specification divergence between pharmaceutical and electronics buyers is fragmenting supplier tiers, as sub-ppm metallic impurity requirements for semiconductor plating collide with USP-grade monograph demands from drug formulators.
Growth Catalysts
- REACH substance restrictions:Tightening purity benchmarks in Europe are disqualifying technical-grade producers and consolidating procurement around certified high-purity suppliers for analytical and pharmaceutical applications.
- Antimicrobial formulation expansion:Pharmaceutical developers are incorporating silver sulphate into topical and wound-care products, creating dedicated demand streams separate from traditional industrial offtake.
- German specialty chemical concentration:Bavarian and Rhineland producers with in-house refining capabilities are capturing premium positioning for laboratory-grade material through ISO 17025-accredited production.
Market Restraints
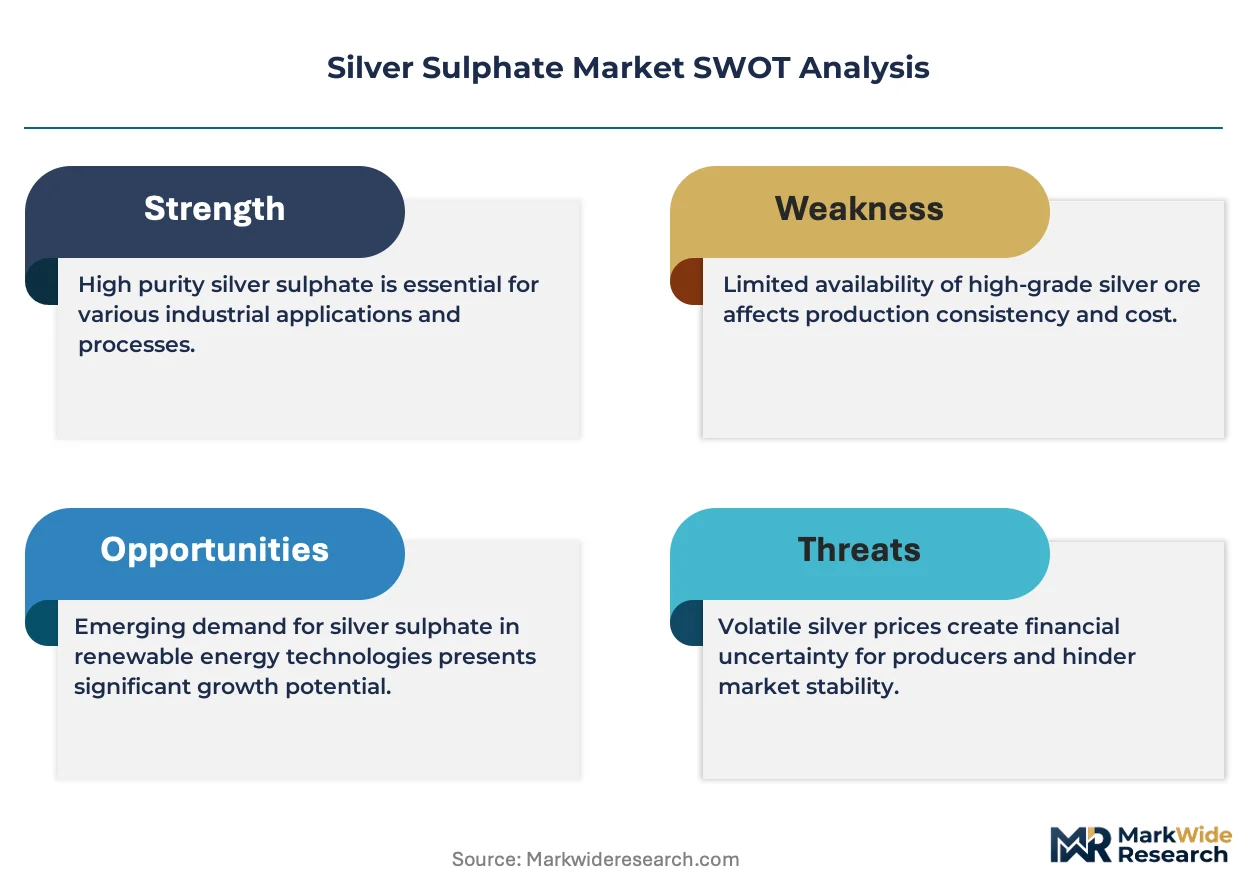
- Silver price volatility:Feedstock cost swings tied to precious metals trading compress margin predictability for toll refiners and contract manufacturers without captive bullion supply.
- Chinese rare earth dominance:Concentration of upstream silver recovery and refining capacity in specific provinces creates geographic supply risk for European and North American formulators.
- Aqueous solubility limitation:Silver sulphate's moderate water solubility restricts its deployment in high-throughput continuous-flow water treatment systems where sodium hypochlorite maintains operational preference.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO-registered production facilities in Gujarat and Maharashtra are expanding analytical reagent consumption as domestic drug development accelerates under PLI scheme incentives.
- Battery recycling directives:EU mandates for lithium-ion recovery are reshaping secondary silver supply economics, creating feedstock arbitrage for refiners with hydrometallurgical extraction capabilities.
- Direct-to-laboratory e-commerce:Research chemical distributors are bypassing traditional wholesale channels to capture institutional procurement workflows through digital catalog integration.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous pursuit of USP, EP, and ISO 17025 accreditations extends qualification periods to 18-24 months for new production facilities.
- Specialized analytical talent scarcity:ICP-MS operators and trace-metals chemists command premium compensation, constraining expansion plans for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Sulphate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Photographic Grade, Laboratory Grade Application: Water Treatment, Catalysts, Pharmaceuticals, Electronics End User: Chemical Manufacturers, Research Laboratories, Pharmaceutical Companies, Water Utilities Form: Crystals, Powder, Granules, Solution |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc, American Elements, Honeywell Research Chemicals, Avantor Inc, Schwitz Biotech, Silvershine Chemicals, Modison Metals Ltd, Jiodine Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Sulphate Market Strategic Shifts
Electrochemical synthesis methods and closed-loop refining systems are compressing production economics while regulatory data requirements are reshaping how purity is documented and transmitted through supply chains.
Electrolytic oxidation in sulfuric acid medium is supplanting traditional silver nitrate precipitation routes for high-purity material, as semiconductor fabricators in Taiwan and South Korea adopt electrochemically produced grades to meet sub-100 ppb sodium and potassium specifications. The shift is compressing batch-to-batch variability and enabling just-in-time delivery contracts that precipitation chemistry cannot support.
REACH Article 33 disclosure obligations are forcing downstream formulators to document silver sulphate concentration in finished goods, creating audit trail requirements that technical-grade suppliers cannot satisfy. Electronics plating houses in Germany and the Netherlands are responding by consolidating procurement around ECHA-registered producers with full substance volume tracking.
Specification-driven supplier consolidation is visible in institutional research procurement, where university central purchasing departments are narrowing approved vendor lists to dual-source arrangements with ISO 17025-accredited distributors. The pattern is most pronounced in Scandinavian markets, where national research councils mandate documented chain-of-custody for all analytical reagents.
Silver Sulphate Market Segmentation
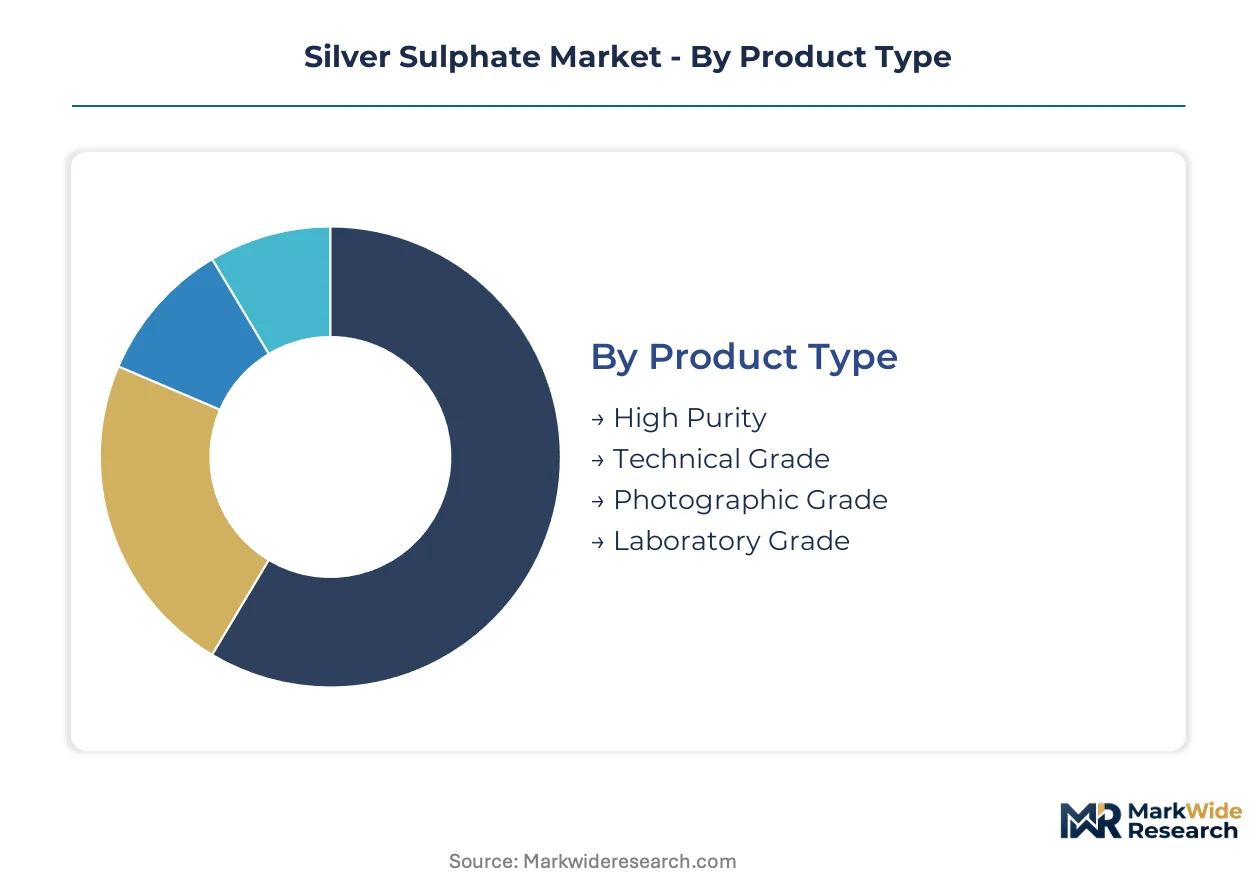
Purity thresholds and regulatory compliance requirements fragment the silver sulphate landscape into distinct procurement tiers. Semiconductor fabricators, pharmaceutical formulators, and water utilities each enforce incompatible specification regimes that reshape supplier positioning.
Product Type:
REACH substance restrictions and USP monograph compliance create divergent certification burdens across purity grades.
- High Purity:Sub-ppm metallic impurity profiles satisfy semiconductor plating specifications in Taiwan and South Korea. Electrochemical synthesis methods displace precipitation chemistry for this grade as fabricators mandate sub-100 ppb sodium and potassium thresholds.
- Technical Grade:Moderate purity levels serve industrial catalyst manufacturing and bulk water treatment applications where cost efficiency outweighs trace-metals control. EPA discharge monitoring and REACH Article 33 disclosure obligations are disqualifying uncertified producers from electronics supply chains.
- Photographic Grade:Legacy emulsion chemistry applications persist in specialized imaging markets.
- Laboratory Grade:ISO 17025-accredited production dominates institutional procurement in Germany and Scandinavia.
Established volume favors Technical Grade; emerging adoption favors High Purity.
Application:
End-use performance requirements dictate incompatible specification regimes that reshape supplier eligibility.
- Electronics:Semiconductor fabricators in Taiwan and South Korea enforce sub-100 ppb alkali metal limits for plating bath formulations. Electrochemical production methods secure qualification for just-in-time delivery contracts that precipitation routes cannot support.
- Pharmaceuticals:Antimicrobial formulation developers incorporate silver sulphate into topical and wound-care products under USP and EP monograph compliance. CDSCO-registered facilities in Gujarat and Maharashtra expand consumption as domestic drug development accelerates.
- Water Treatment:Moderate aqueous solubility restricts deployment in high-throughput continuous-flow systems where sodium hypochlorite maintains operational preference.
- Catalysts:Powder form dominates handling efficiency in petrochemical and specialty chemical manufacturing.
Pharmaceutical applications climb the fastest; water treatment retains the largest installed base.
End User:
Procurement sophistication and certification requirements stratify the customer base into distinct negotiation positions.
- Research Laboratories:University central purchasing departments narrow approved vendor lists to dual-source arrangements with ISO 17025-accredited distributors. Scandinavian national research councils mandate documented chain-of-custody for all analytical reagents.
- Pharmaceutical Companies:CDSCO-registered production facilities in India expand analytical reagent consumption as domestic drug development accelerates under PLI scheme incentives. Multi-jurisdiction USP, EP, and ISO 17025 qualification timelines extend to 18-24 months.
- Chemical Manufacturers:Bavarian and Rhineland producers with in-house refining capabilities capture premium positioning for laboratory-grade material.
- Water Utilities:EPA drinking water regulations elevate compliance costs while creating certification barriers for technical-grade suppliers.
Research laboratories command the steepest premium; water utilities drive the largest procurement volumes.
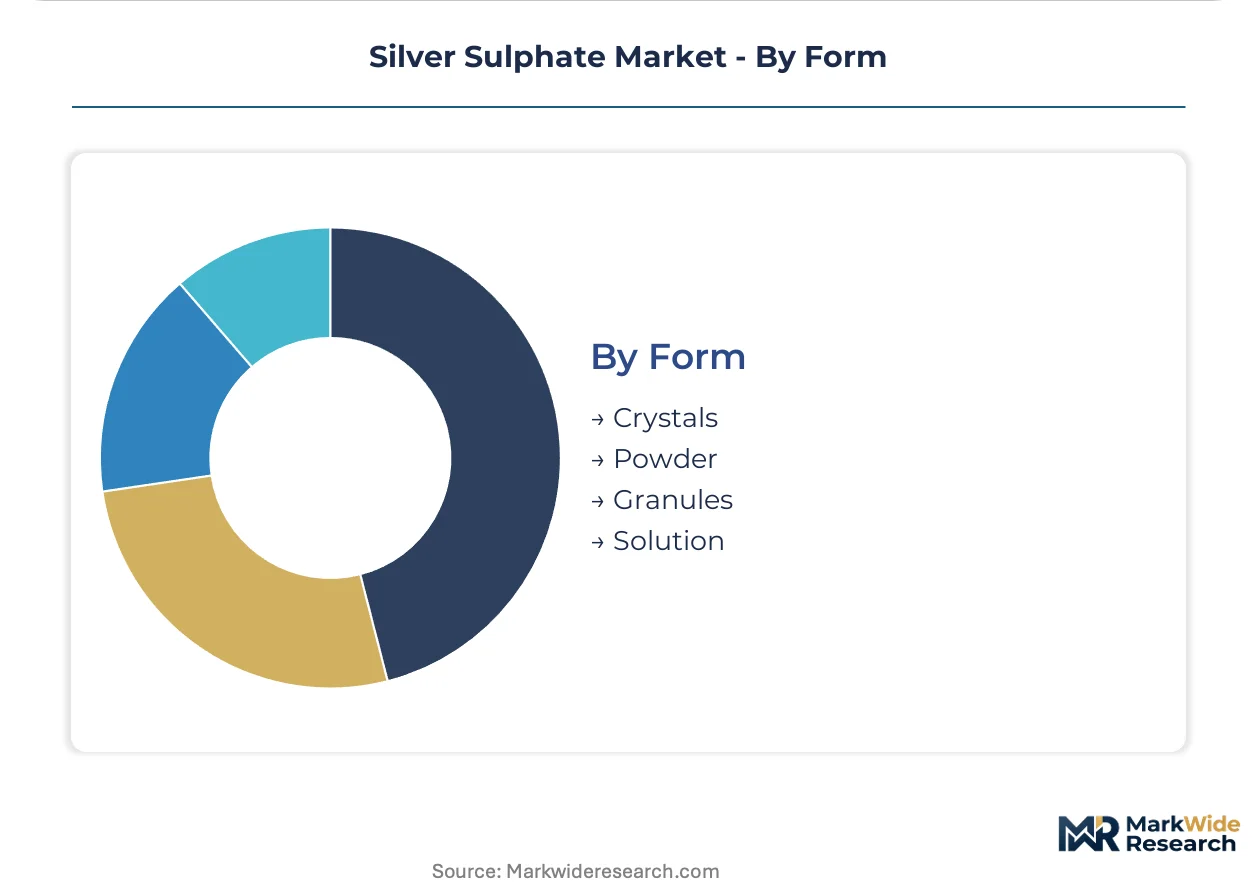
Form:
Handling economics and dissolution kinetics determine form selection across end-use applications.
- Powder:Dominates volume share through handling efficiency in catalyst manufacturing and water treatment dosing systems. Bulk pneumatic conveying and automated dispensing favor this form for continuous-process industrial applications.
- Crystals:Premium positioning for electronics plating applications where dissolution kinetics must be precisely controlled. Semiconductor fabricators specify crystal size distribution to manage bath chemistry stability.
- Granules:Intermediate form for specialized dosing equipment in smaller-scale water treatment installations.
- Solution:Ready-to-use format eliminates dissolution steps for laboratory and small-batch pharmaceutical applications.
Powder form anchors industrial procurement; crystal form extracts the highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Water utilities in India and Brazil prioritize cost efficiency, while semiconductor fabricators in Taiwan and South Korea absorb premium pricing for sub-100 ppb impurity grades. European pharmaceutical formulators occupy a middle position, balancing REACH compliance costs against supply security.
Germany
Bavarian and Rhineland specialty chemical manufacturers command premium positions for laboratory-grade silver sulphate. ECHA-registered producers with full substance volume tracking capture electronics plating contracts from Dutch and German semiconductor houses. ISO 17025-accredited facilities in Leverkusen and Ludwigshafen dominate institutional procurement for analytical reagents.
United States
EPA drinking water regulations and evolving water quality standards tighten purity benchmarks for technical-grade suppliers. American Elements anchors North American supply through in-house refining capabilities in California. Research institutions in Massachusetts and California narrow approved vendor lists to dual-source arrangements with accredited distributors.
India
CDSCO-registered production facilities in Gujarat and Maharashtra expand analytical reagent consumption as domestic drug development accelerates under PLI scheme incentives. Pharmaceutical formulators in Hyderabad and Mumbai incorporate silver sulphate into topical antimicrobial products. Toll refiners face margin compression from silver price volatility without captive bullion supply.
South Korea
Semiconductor fabricators in Suwon and Pyeongtaek enforce sub-100 ppb sodium and potassium specifications for plating bath formulations. Electrochemical production methods secure qualification for just-in-time delivery contracts that precipitation chemistry cannot support. Domestic suppliers compete with Taiwanese and Japanese imports for high-purity grades.
China
Concentration of upstream silver recovery and refining capacity in Hunan and Jiangxi provinces creates geographic supply risk for European and North American formulators. NMPA-registered facilities serve domestic pharmaceutical demand while technical-grade output dominates industrial catalyst manufacturing. Environmental compliance costs under MEE directives reshape production economics for smaller refiners.
Silver Sulphate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with analytical-grade specialists commanding premium pricing while commodity refiners compete on silver feedstock access. The market structure stratifies into three tiers: integrated multinationals with rare metal portfolios, mid-scale regional producers with in-house refining, and toll refiners dependent on spot silver markets. Dominant competitive moves include backward integration into captive bullion supply and geographic expansion through ECHA registration for European market access.
Among Germany-based analytical specialists, Merck KGaA leverages its analytical standards heritage to dominate laboratory-grade distribution in Western Europe. American Elements exemplifies the integrated multinational archetype through its rare metal portfolio breadth. Thermo Fisher Scientific Inc occupies a position within the research chemical catalog segment, capturing institutional procurement workflows through digital channel integration.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc |
| American Elements |
| Honeywell Research Chemicals |
| Avantor Inc |
| Schwitz Biotech |
| Silvershine Chemicals |
| Modison Metals Ltd |
| Jiodine Chemical |
| Others |
Value Chain & Pricing Dynamics
REACH Article 33 disclosure obligations and ISO 17025 laboratory accreditation simultaneously gate supplier qualification and stratify price tiers, as uncertified producers face exclusion from electronics and pharmaceutical procurement while accredited facilities command 15-40% premiums for documented chain-of-custody.
Pricing Analysis
After-sales revenue from analytical certification renewals and regulatory compliance documentation drives lifetime value for high-purity grade suppliers. Three-tier pricing structure across premium, standard, and economy levels separates electrochemically produced semiconductor grades from precipitation-chemistry laboratory grades and technical-grade bulk material. Cost compression in technical-grade tiers is intensifying because toll refiners lack captive bullion supply to hedge silver feedstock volatility. Water utilities in India and Brazil exhibit the highest price sensitivity, while semiconductor fabricators in Taiwan absorb premium pricing for sub-100 ppb impurity specifications.
Supply Chain Analysis
China and Germany anchor upstream silver refining and high-purity chemical synthesis respectively. Hunan and Jiangxi provinces concentrate electrolytic silver recovery capacity, while Bavarian producers dominate ISO 17025-accredited laboratory-grade output. The supply chain draws from silver bullion markets, sulfuric acid industrial supply, and specialized electrochemical equipment fabrication. Single-source vulnerability concentrates in Chinese upstream refining, where environmental compliance directives under MEE reshape production economics for smaller operators. Distribution runs through ECHA-registered specialty chemical distributors with full substance volume tracking for European electronics plating houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silver sulphate market sits in early-cycle expansion as antimicrobial formulation developers in pharmaceuticals create dedicated demand streams separate from traditional industrial offtake, with penetration rates in topical and wound-care products climbing from negligible bases.
For Market Incumbents: Fortify qualification moats by accelerating multi-jurisdiction USP, EP, and ISO 17025 certification timelines to 12-15 months through pre-submission regulatory consulting, while backward integration into captive bullion supply hedges margin compression from silver price volatility that threatens toll refiners without metal trading desks. For New Entrants and Emerging Players: Lead with CDSCO-registered production partnerships in Gujarat and Maharashtra to capture analytical reagent consumption growth under India's PLI scheme incentives, targeting pharmaceutical formulators with direct-to-laboratory e-commerce catalog integration that bypasses traditional wholesale channel markups. For Investors and Strategic Acquirers: EU battery recycling directives reshape the acquisition landscape by creating feedstock arbitrage opportunities for refiners with hydrometallurgical extraction capabilities. Long-term viability centers on secondary silver supply economics over a 5-10 year window. Target acquisition archetype: mid-scale regional producers with in-house refining and ECHA registration for European market access. The signal to watch is lithium-ion recovery mandate implementation timelines that redirect silver-bearing waste streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Bullion Supply | Hedges margin compression from silver price volatility for toll refiners without metal trading capabilities. |
| ECHA Registration for Full Substance Volume Tracking | Qualifies suppliers for electronics plating contracts from Dutch and German semiconductor houses under REACH Article 33. |
| Electrochemical Synthesis Method Adoption | Secures just-in-time delivery contracts from Taiwan fabricators demanding sub-100 ppb sodium and potassium thresholds. |
| CDSCO-Registered Production Facility Expansion | Captures analytical reagent consumption growth as domestic drug development accelerates under PLI scheme incentives. |
| Direct-to-Laboratory E-Commerce Channel Development | Bypasses traditional wholesale markups to capture institutional procurement workflows through digital catalog integration. |
Study Parameters
A spread of perspectives from specialty chemical plant managers, pharmaceutical procurement leads, semiconductor fabrication engineers, and analytical reagent distribution channel partners converged on the working assumptions that purity specification divergence and regulatory compliance timelines are the primary demand segmentation drivers. Primary interview insights were cross-validated against customs and trade data, Cefic specialty chemical reports, SEC 10-K filings from diversified chemical conglomerates, and ECHA substance volume tracking disclosures. Bottom-up demand modeling from end-use application consumption rates was triangulated against top-down supply-side capacity assessments.
Segmentation dimensions modeled include purity grade tier, end-use industry application, physical form factor, and regional production hub certification status across the analysis window. CAGRs were derived from regression analysis of historical consumption patterns and forward projection of adoption curves in semiconductor plating and antimicrobial formulation applications. Industry-specific forecast inputs incorporated silver bullion price trajectory assumptions and evolving EPA drinking water regulation stringency.
Forecasts assume regulatory continuity in REACH substance restrictions and EPA water quality standards; material policy shifts would require re-modeling. Specific risk factors that could revise projections include lithium-ion battery recycling directive implementation timelines that reshape secondary silver supply availability, and MEE environmental compliance cost escalations in Chinese upstream refining. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Long Products Market
Metals
Platinum Compounds Market
Metals
Global Vanadium Market
Metals
Nickel Oxide Target Market
Metals
Reconditioned Steel Drums Market
Metals
Global Duplex Stainless Steel Market
Metals
Zirconium Market
Metals
Global High Purity Titanium Powder Market
Metals
Powder Metallurgy Market
Metals
Nickel Powder Plating Market
Metals
Osmium Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Ruthenium Market
Metals
Cobalt Market
Metals
Silver Powder and Flakes Market