
 High Magnetic Induction Grain-Oriented Silicon Steel Market | 2026-2036
High Magnetic Induction Grain-Oriented Silicon Steel Market Size, Share, and Industry Trends Forecast 2026-2036
High Magnetic Induction Grain-Oriented Silicon Steel Market Intelligence
Revenue from custom-order, high-performance formulations is reshaping the margin pool away from standardized sheet steel products. Nippon Steel Corporation leverages its advanced manufacturing processes to lead in ultra-thin gauge products for high-frequency applications. JFE Steel Corporation competes on material purity and domain-specific R&D, while Baosteel Group Corporation sustains its position through massive production scale.
High magnetic induction grain-oriented silicon steel is an electrical steel alloy with a grain structure optimized for superior magnetic properties in one direction. This material, with its low core loss and high permeability, is essential for minimizing energy dissipation in electrical equipment. Power transformers constitute the largest end-user segment, consuming vast quantities of laminated steel for efficient energy conversion. Demand for thin steel products is accelerating for use in high-frequency applications like advanced electric motors and inductors.
Performance standards are set by bodies like the US Department of Energy and through Europe's Ecodesign Directive, mandating minimum efficiency levels for transformers. In Asia, China's dual carbon goals and Japan's METI-led energy conservation policies directly influence material specifications and procurement. Navigating these varied regional efficiency requirements while managing raw material price volatility is the central strategic challenge for manufacturers.
Market Dynamics
The central structural force shaping the market is the global mandate for enhanced energy efficiency in power infrastructure. This pressure, codified in regulations from the US Department of Energy to the EU Green Deal, compels a definitive shift toward higher-grade materials.
Growth Catalysts
- Grid Modernization:Expansive grid upgrades in developed nations and infrastructure build-outs in emerging economies like India create sustained demand for high-efficiency transformers, the primary end-use for this steel.
- EV Infrastructure Expansion:The rapid construction of new energy vehicle charging networks, particularly in China, requires a massive volume of high-performance distribution transformers that rely on low-loss grain-oriented silicon steel.
- High-Frequency Applications:The development of advanced electric motors and compact power electronics is driving consumption of ultra-thin gauge products, which minimize energy loss at higher operational frequencies.
Market Restraints
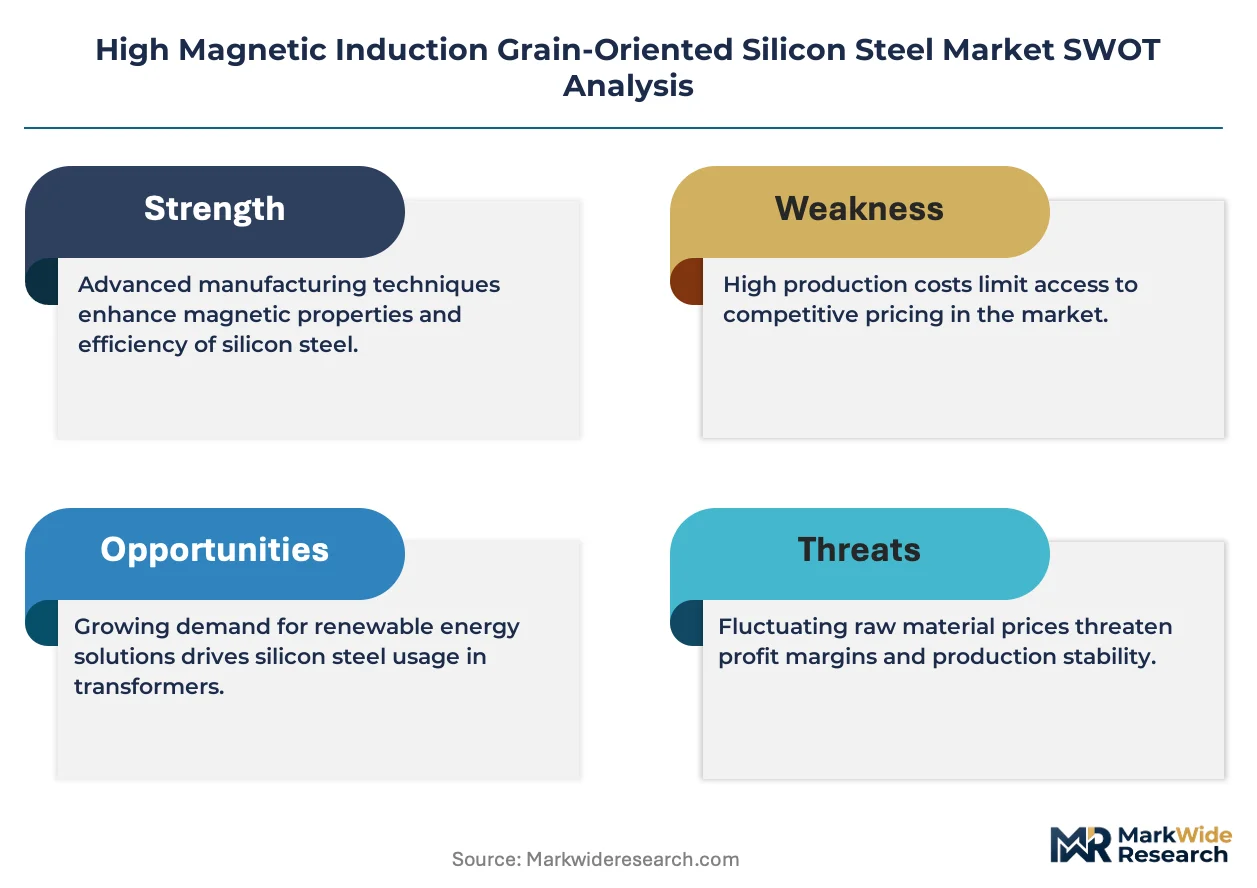
- Raw Material Volatility:Fluctuations in the price of high-purity iron ore and silicon, the primary raw materials, create significant cost pressure and margin uncertainty for steel manufacturers.
- Production Complexity:The multi-stage, capital-intensive process of cold rolling and annealing required to achieve precise grain orientation acts as a high barrier to entry for new competitors.
- Supply Chain Concentration:A significant portion of the world's most advanced, low-loss grade production capacity is concentrated in Japan and China, posing a potential geopolitical and logistical risk for global buyers.
Strategic Opportunities
- Next-Generation Power Electronics:The market for high-frequency inductors and power supplies for data centers and telecommunications represents a key growth vector for specialized, ultra-thin gauge formulations.
- Renewable Energy Integration:Wind and solar farm collector transformers, which must operate with high efficiency under variable loads, offer a dedicated segment for custom-engineered high-permeability steel.
- Emerging Market Electrification:National electrification programs in regions like Southeast Asia and Latin America present long-term volume opportunities as their grids are built and modernized to higher efficiency standards.
Industry Challenges
- Capital Investment Cycles:The immense capital expenditure required for building new or upgrading existing production lines to meet demand for thinner gauges and lower core loss grades presents a significant financial hurdle.
- Navigating Disparate Standards:Manufacturers face complexity in developing products that comply with a patchwork of regional efficiency regulations, such as Europe's Ecodesign Directive and North American DOE rules.
- Specialized Talent Scarcity:A shortage of metallurgists and process engineers with deep expertise in grain-oriented steel production and magnetic property optimization constrains R&D and operational excellence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Magnetic Induction Grain-Oriented Silicon Steel Market |
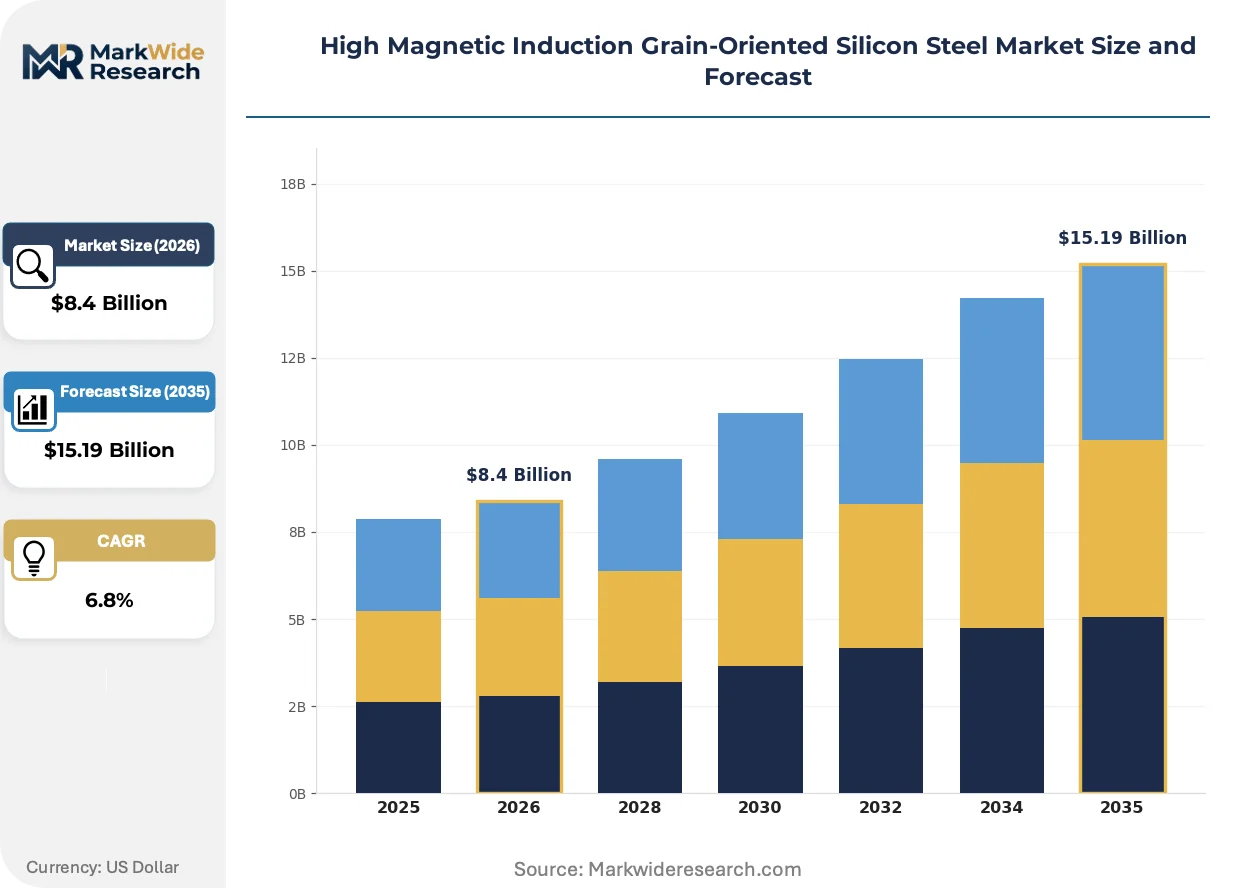
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Steel, Thin Steel, Laminated Steel, Coated Steel End User: Power Transformers, Electric Motors, Generators, Inductors Application: Energy Sector, Industrial Machinery, Renewable Energy, Automotive Industry Manufacturing Stage: Prime, Secondary, Tertiary, Custom Order |
| Companies Covered | Nippon Steel Corporation, Baosteel Group Corporation, JFE Steel Corporation, POSCO, Cleveland-Cliffs Inc., ArcelorMittal, Thyssenkrupp, Shougang Group, China Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Magnetic Induction Grain-Oriented Silicon Steel Market Strategic Shifts & Innovations
Material science advancements are enabling application-specific formulations that command higher margins than standardized grades. This evolution is moving producers away from commodity supply models and toward collaborative, performance-driven partnerships with original equipment manufacturers.
Advanced laser scribing technology refines the magnetic domains within the steel after the final annealing process to significantly reduce core loss. Transformer manufacturers are adopting this process for their highest-tier products to meet stringent efficiency targets. This technology is collapsing the performance-cost gap between top-grade grain-oriented steel and more expensive amorphous metal cores for certain power applications.
China's "dual carbon" policy framework is a major regulatory driver, establishing aggressive targets for carbon neutrality that necessitate higher energy efficiency across the power grid. This directly influences material procurement, compelling transformer and electric motor manufacturers to favor higher-grade silicon steels with lower hysteresis and eddy current losses. The policy effectively makes low-loss performance a non-negotiable specification for domestic equipment suppliers.
A notable behavioral shift involves end-users in high-tech sectors moving from transactional purchasing to co-development partnerships with steel producers. Instead of selecting from a catalog, automotive and renewable energy firms now collaborate directly with mills to create bespoke materials optimized for a specific EV motor or wind turbine generator. This trend is most visible in Germany and Japan, where deep engineering integration is common.
High Magnetic Induction Grain-Oriented Silicon Steel Market Segmentation
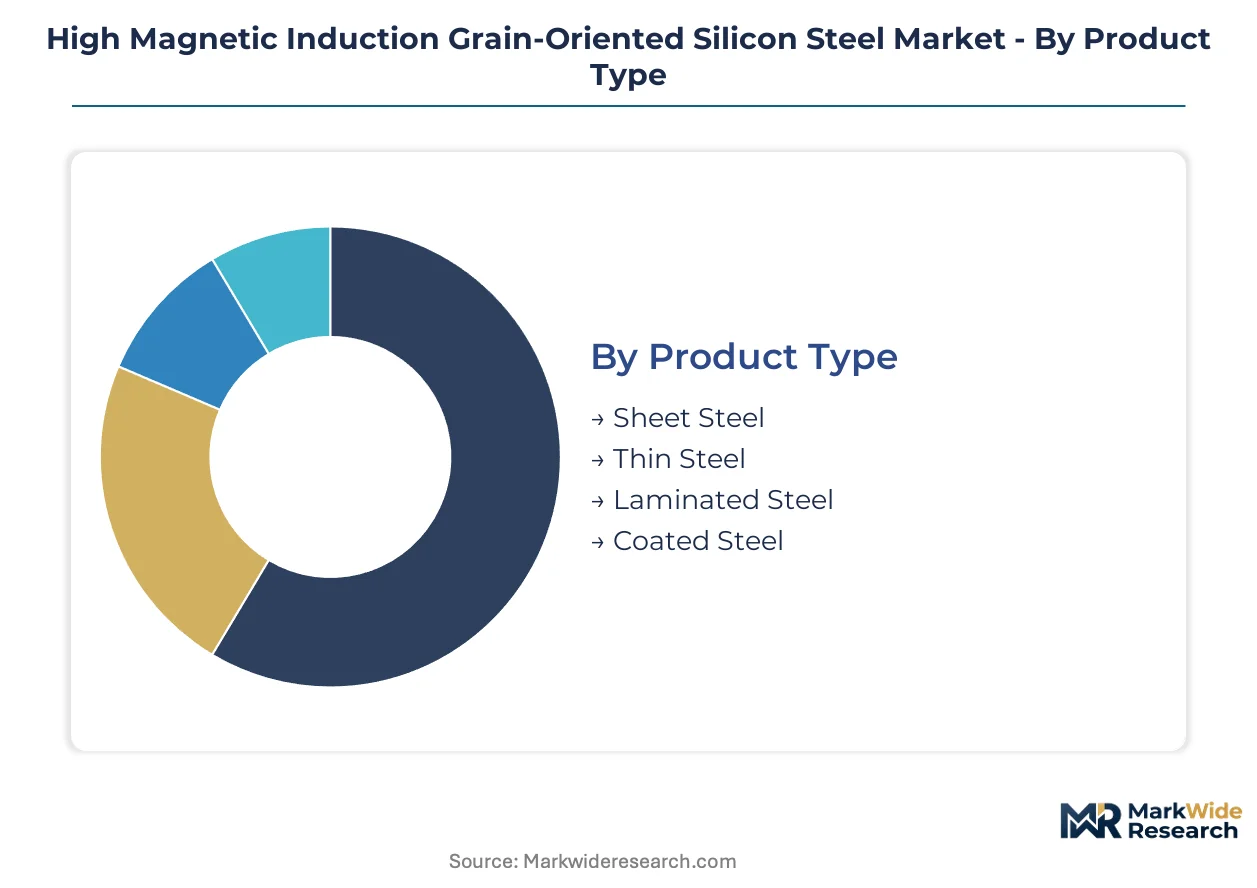
Understanding the segmentation of the high magnetic induction grain-oriented silicon steel market is crucial for identifying precise demand pockets and technological trajectories. This detailed breakdown reveals where innovation is concentrated and how different product forms and end-use applications shape material specifications. Each segment reflects distinct performance requirements and supply chain dynamics, influencing strategic investment decisions.
Product Type:
The product type spectrum ranges from established commodity grades to advanced, application-specific formulations that drive market evolution.
- Sheet Steel:This traditional form of grain-oriented silicon steel features standard thicknesses and magnetic properties. Demand remains robust in large-scale power transformer manufacturing for extensive grid modernization projects across India and China.
- Thin Steel:Characterized by ultra-thin gauges, this product type is engineered for superior magnetic performance at high operational frequencies. The rapid expansion of new energy vehicle charging infrastructure in China drives significant consumption for compact power electronics.
- Laminated Steel:Composed of multiple thin sheets insulated from each other, this product minimizes eddy current losses in static electrical equipment. Power transformer manufacturers widely utilize laminated steel for their core assemblies, meeting efficiency mandates from the US Department of Energy.
- Coated Steel:Featuring an insulating coating applied to the steel surface, this product type enhances core loss reduction and corrosion resistance. Manufacturers employ coated steel in specialized transformers and reactors to improve long-term operational reliability.
Sheet Steel handles the majority of throughput; Thin Steel is the fastest mover on share.
End User:
Customer applications for high magnetic induction grain-oriented silicon steel are diverse, with efficiency mandates driving material selection across industrial and energy sectors.
- Power Transformers:This segment represents the largest consumer, utilizing vast quantities of grain-oriented silicon steel for efficient energy conversion and transmission. Extensive grid upgrades in developed nations and infrastructure build-outs in emerging economies create sustained demand.
- Electric Motors:High-performance electric motors, particularly in electric vehicles and industrial automation, rely on this specialized steel for reduced energy loss and improved power density. The automotive industry's shift towards electrification, notably in Germany and Japan, accelerates demand for compact designs.
- Generators:Electrical generators in power plants and renewable energy installations incorporate grain-oriented silicon steel to optimize magnetic flux and minimize core losses. Manufacturers seek higher permeability grades to enhance overall system efficiency under varying load conditions.
- Inductors:Used in power electronics and high-frequency applications, inductors benefit from the low core loss properties of this material to manage energy storage and current regulation. Data centers and telecommunications infrastructure represent a key growth vector for specialized, ultra-thin gauge formulations.
Demand for Power Transformers drives significant volume; specialized applications like Electric Motors show accelerated growth.
Application:
The material's application spans critical infrastructure and advanced technological systems, each with unique performance requirements and regulatory pressures.
- Energy Sector:This broad application encompasses power generation, transmission, and distribution infrastructure, where high-efficiency transformers are indispensable. Global mandates for enhanced energy efficiency, codified in regulations like the EU Green Deal, compel a shift toward higher-grade materials.
- Automotive Industry:The rapid expansion of electric vehicles and associated charging networks demands high-performance magnetic materials for motors, inverters, and onboard chargers. China's new energy vehicle strategy significantly influences material specifications and procurement patterns.
- Industrial Machinery:Electric motors and control systems within industrial equipment rely on grain-oriented silicon steel for optimal performance and energy savings. Manufacturers of robotics and automation systems seek materials that ensure precision and durability in demanding operational environments.
- Renewable Energy:Wind and solar farm collector transformers, along with inverters, require highly efficient magnetic cores to operate effectively under variable loads. These applications offer a dedicated segment for custom-engineered high-permeability steel, particularly in Europe's decarbonization efforts.
The Energy Sector remains foundational; however, the Automotive Industry is rapidly expanding its material requirements.
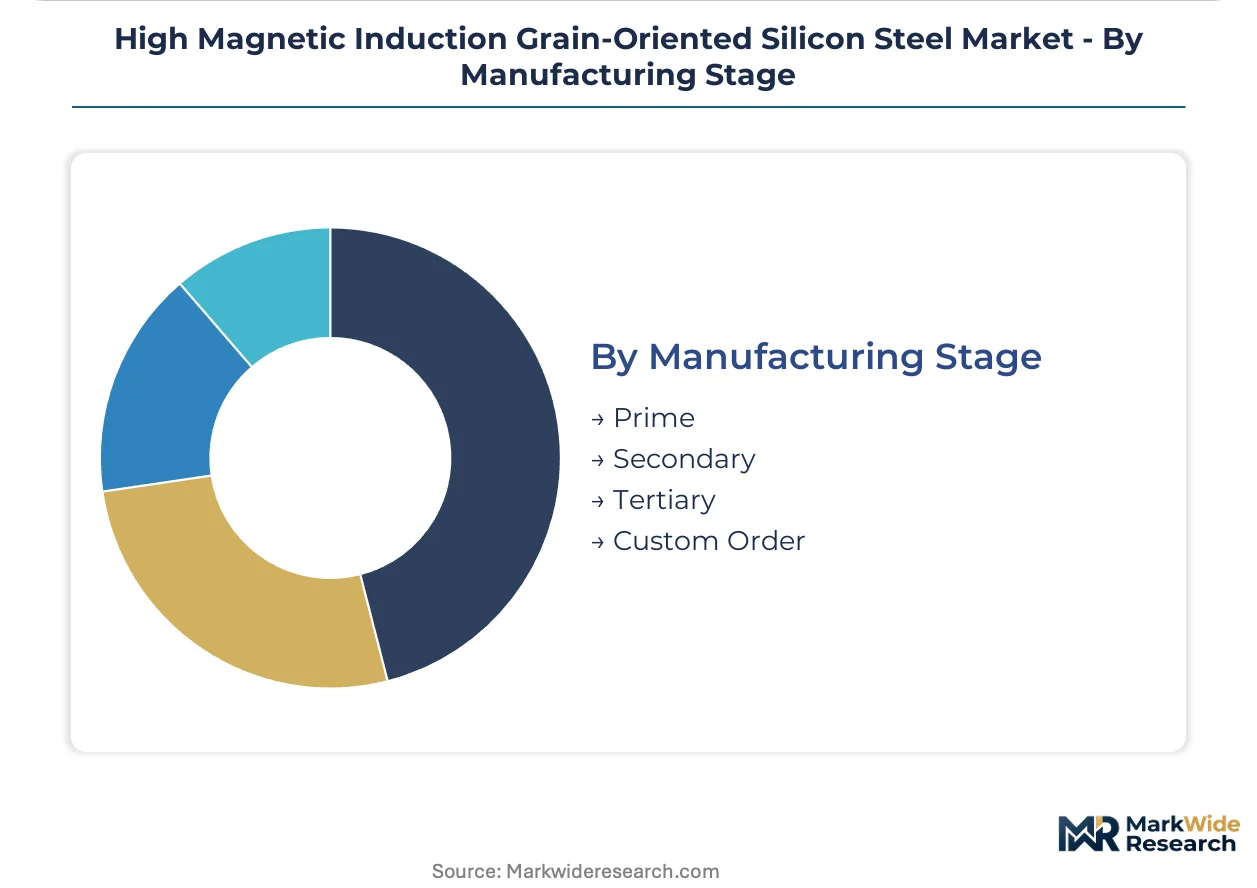
Manufacturing Stage:
The manufacturing stage segmentation highlights the varying quality levels and customization opportunities available within the market.
- Prime:This category denotes the highest quality grain-oriented silicon steel, produced to stringent specifications with minimal defects and superior magnetic properties. High-efficiency power transformers and critical infrastructure projects prioritize prime-grade materials to meet demanding performance standards.
- Custom Order:Representing bespoke material formulations developed in collaboration with original equipment manufacturers, this segment caters to highly specialized applications. Automotive and renewable energy firms frequently partner with steel producers to create optimized materials for specific EV motors or wind turbine generators.
- Secondary:This category includes materials that may have minor surface imperfections or slightly lower magnetic performance compared to prime grades. Secondary products find use in less demanding applications or smaller distribution transformers where cost optimization is a primary concern.
- Tertiary:Often consisting of off-specification or re-rolled materials, tertiary grades offer a cost-effective option for applications with less stringent magnetic property requirements. This material is typically utilized in non-critical components or smaller electrical devices.
While Secondary represents the baseline production, Custom Order is where value creation is most pronounced.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for high magnetic induction grain-oriented silicon steel vary significantly across regions, reflecting diverse infrastructure priorities and regulatory landscapes. China's market is heavily influenced by new energy vehicle infrastructure, while developed nations like the United States prioritize grid modernization. European countries emphasize renewable energy integration and stringent efficiency mandates.
China
Demand for thin steel is accelerating due to new energy vehicle charging networks and associated power electronics. China's dual carbon goals directly influence material specifications for domestic equipment, compelling manufacturers to favor higher-grade silicon steels. Massive infrastructure build-outs in the Yangtze River Delta region require high-performance distribution transformers for urban and industrial expansion.
India
Expansive grid upgrades create sustained demand for high-efficiency transformers, the primary end-use for this specialized steel. The country's national energy policies, guided by the Central Electricity Authority (CEA), promote efficient power transmission and distribution. Infrastructure development in states like Maharashtra fuels consumption of standard sheet steel for large-scale power projects.
United States
Grid modernization projects drive the need for high-efficiency power transformers, particularly in aging infrastructure. US Department of Energy (DOE) standards mandate minimum efficiency levels for all new transformers, influencing material procurement. Advanced manufacturing hubs in the Midwest utilize specialized steel for industrial machinery and smart grid components.
Japan
Advanced electric motors and high-frequency applications for compact power electronics require ultra-thin gauge products. METI-led energy conservation policies influence material specifications and procurement, promoting high-efficiency solutions. Deep engineering integration in regions like Kanto drives co-development of bespoke materials for specialized EV motors and industrial robotics.
Germany
Renewable energy integration and advanced power electronics for data centers are key demand drivers for high-performance steel. Europe's Ecodesign Directive compels the use of higher-grade materials in transformers and electrical equipment to meet efficiency targets. Automotive firms in Bavaria collaborate with steel producers for optimized EV motor materials and compact power solutions.
High Magnetic Induction Grain-Oriented Silicon Steel Market Key Industry Players
Capability concentration sits with one tier of producers, specializing in high-performance formulations, while scale advantage sits with another, focusing on massive production volumes. The market exhibits a tiered structure, with a few global giants dominating commodity sheet steel production. Strategic archetypes include integrated steelmakers, specialized material science firms, and regional niche players. Capacity expansion, coupled with technology licensing, are dominant competitive moves among key participants seeking to meet evolving demand.
Within the premium and specialized material segment, Japan-based Nippon Steel Corporation exemplifies leadership in ultra-thin gauge products for high-frequency applications, representing advanced material science. JFE Steel Corporation, also from Japan, competes on material purity and domain-specific R&D, anchoring the high-performance end of the market. Baosteel Group Corporation, a Chinese conglomerate, sustains its position through massive production scale for standardized sheet steel, particularly for grid modernization projects, representing the volume-driven segment.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Baosteel Group Corporation |
| JFE Steel Corporation |
| POSCO |
| Cleveland-Cliffs Inc. |
| ArcelorMittal |
| Thyssenkrupp |
| Shougang Group |
| China Steel Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lane costs directly influence material pricing, reflecting both the geographic concentration of advanced production and the widespread global demand for high magnetic induction grain-oriented silicon steel. This dynamic shapes how manufacturers manage costs and how end-users procure specialized materials.
Pricing Analysis
Contract-based long-term offtake agreements and project-based purchasing define the dominant pricing structure for high magnetic induction grain-oriented silicon steel. Price differentiation stems from quality grade, particularly for ultra-thin gauge products, and the level of customization required by OEMs. Pricing softness impacts standardized sheet steel due to massive production scale from Baosteel Group Corporation. Power transformer manufacturers seeking commodity sheet steel exhibit higher price sensitivity, while automotive and renewable energy firms prioritizing custom-order, high-performance formulations are less sensitive.
Supply Chain Analysis
Upstream, the supply chain for high magnetic induction grain-oriented silicon steel relies heavily on high-purity iron ore and silicon. Production capability concentrates significantly in Japan and China. Raw material price volatility represents a primary structural risk, creating margin uncertainty for steel manufacturers. Downstream, distribution primarily occurs through direct sales channels to major OEMs, including power transformer manufacturers and advanced electric motor producers, fostering close technical collaboration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for a cyclical recovery, primarily driven by ongoing global grid modernization and expansive infrastructure build-outs. Strategic positioning now will capture long-term value from the energy transition.
For Market Incumbents:
Harden core intellectual property around advanced manufacturing processes for ultra-thin gauge products, such as laser scribing technology. This defends against potential substitution by amorphous metal cores in certain power applications. Invest in capacity additions for specialized product lines in strategic geographies to meet regional efficiency mandates like Europe's Ecodesign Directive. Deepen R&D into novel coating formulations for enhanced magnetic performance and corrosion resistance.
For New Entrants and Emerging Players:
Niche applications in high-frequency power electronics for data centers and telecommunications represent a penetrable entry point. Specialized components for renewable energy collector transformers in emerging markets, particularly Southeast Asia, offer significant white-space opportunities. A viable go-to-market angle involves forming collaborative co-development partnerships with OEMs to create bespoke materials optimized for specific next-generation applications.
For Investors and Strategic Acquirers:
Carve-out targets emerge from integrated steelmakers seeking to divest non-core specialty materials divisions. The market demonstrates long-term viability as an essential material for global energy transition and grid resilience over the next decade. Acquisition targets should focus on specialized material science firms possessing proprietary ultra-thin gauge production capabilities or advanced coating technologies. Increased patent filings for magnetic domain refinement or new high-permeability alloy compositions serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Ultra-Thin Gauge | Addresses growing demand from EV infrastructure and high-frequency applications. |
| Advanced Laser Scribing Technology | Reduces core loss in high-tier products to meet stringent efficiency targets. |
| Joint Development with Automotive OEMs | Creates bespoke materials optimized for next-generation electric motors. |
| Raw Material Hedging Strategies | Mitigates cost pressure from volatile high-purity iron ore and silicon prices. |
| Regional Certification Compliance | Ensures market access and competitiveness in Europe and North America. |
Research Approach
A standing panel of metallurgists, transformer design engineers, procurement specialists, and energy grid operators provided ongoing calibration for market assumptions. This primary research was rigorously combined with secondary validation from regulatory filings, industry association reports, and company annual reports. Bottom-up and top-down triangulation ensured data consistency across all segments.
Scenario-based modeling formed the core of the analytical framework, projecting market dynamics across the analysis window. Segmentation dimensions included product type, end-user, application, manufacturing stage, and regional energy policy. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included global electrification rates, electric vehicle adoption curves, and grid modernization investment.
Practitioners should monitor geopolitical shifts impacting raw material supply and significant regulatory changes in energy efficiency standards for early signals of market revision. Forecasts reflect assumptions, but unforeseen technological disruptions or economic downturns could affect infrastructure spending. Cross-checking against national energy agency forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Global High Purity Titanium Powder Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Aluminum Ingots Market
Metals
Vietnam Aluminum Market
Metals
Shipbuilding Steel Plate Market
Metals
Arc Ferrite Magnet Market
Metals
Osmium Market
Metals
Armour Steel Plate Market
Metals
Ore Metals Market
Metals
North America Electrical Steel Market
Metals
Expanded Metal Foils Market
Metals
Weathering Steel Market
Metals
Battery Metals Market
Metals
Amorphous Metal Cores Market
Metals
Russia Metal Fabrication Market