
 Barium Derivatives Market | 2026-2036
Barium Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Derivatives Market Outlook
Technical-grade specification services and certified purity subscriptions is decoupling barium derivatives from commodity chemical sales. Solvay leverages its European REACH compliance infrastructure to command premium positioning in pharmaceutical-grade barium sulfate. Hebei Xinji Chemical Group anchors regional supply through integrated barite ore-to-derivative processing in Hebei Province. Nippon Chemical Industrial differentiates via ultra-high-purity barium nitrate for pyrotechnic and electronics applications.
Barium derivatives encompass inorganic salts and compounds synthesized from barite ore or barium carbonate feedstock, typically processed through acid digestion, precipitation, or thermal reduction to achieve specific purity grades ranging from technical to pharmaceutical or reagent standards. These compounds serve primarily as functional additives, process intermediates, and performance materials across industrial manufacturing systems. Barium sulfate dominates value capture in oilfield drilling fluids and medical imaging contrast media, where density and radiopacity requirements create defensible margin pools. Barium carbonate maintains mature demand in ceramics and glass manufacturing, while barium chloride and barium nitrate occupy specialized niches in pyrotechnics and electronics surface treatment.
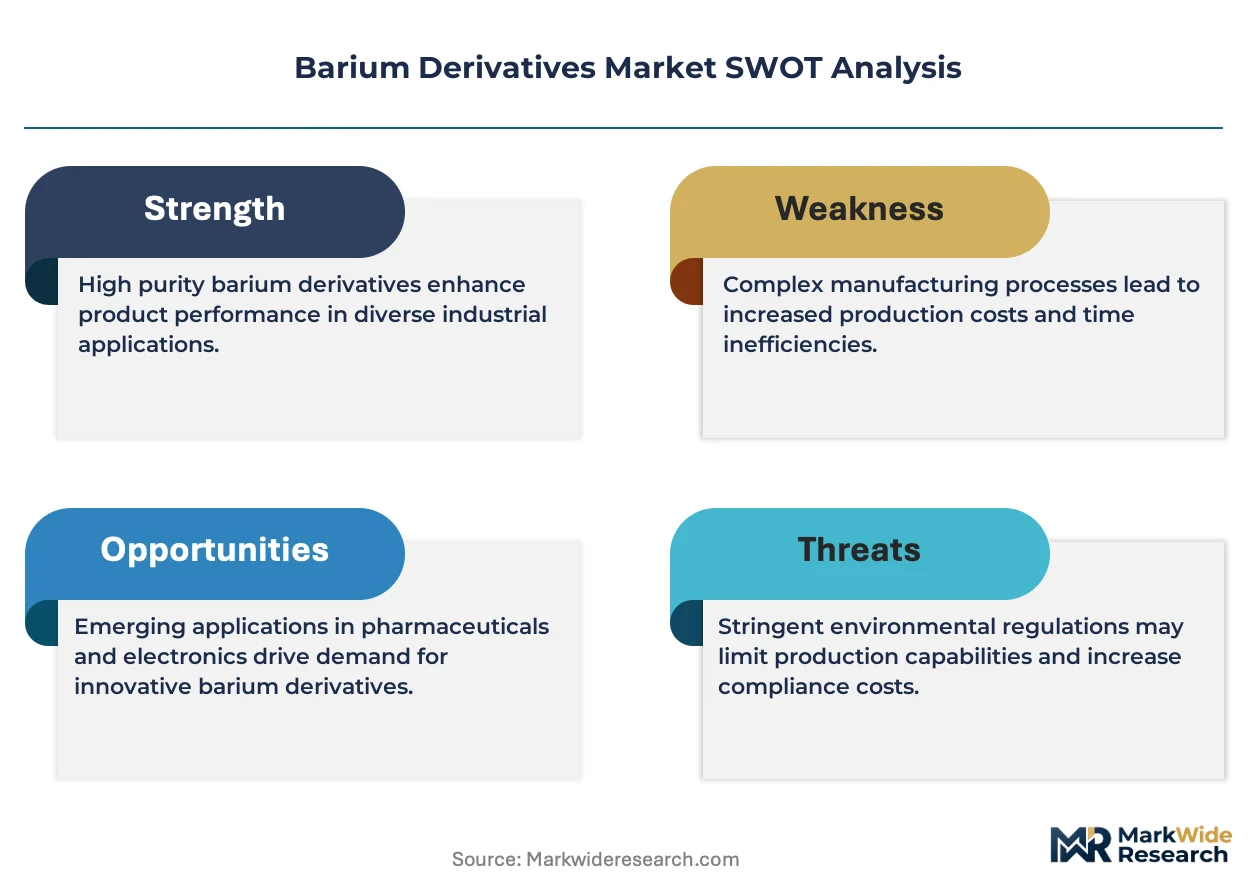
China's MEE enforces wastewater discharge limits on barium salt producers, compelling capital upgrades that smaller operators cannot absorb. REACH registration requirements in Europe restrict market access for non-compliant Asian exporters, consolidating import channels through certified traders. The US EPA and OSHA jointly govern permissible exposure limits and waste classification for barium compounds in industrial settings. Stakeholders must monitor how fragmented environmental enforcement across producing regions reshapes cost structures and sourcing geography.
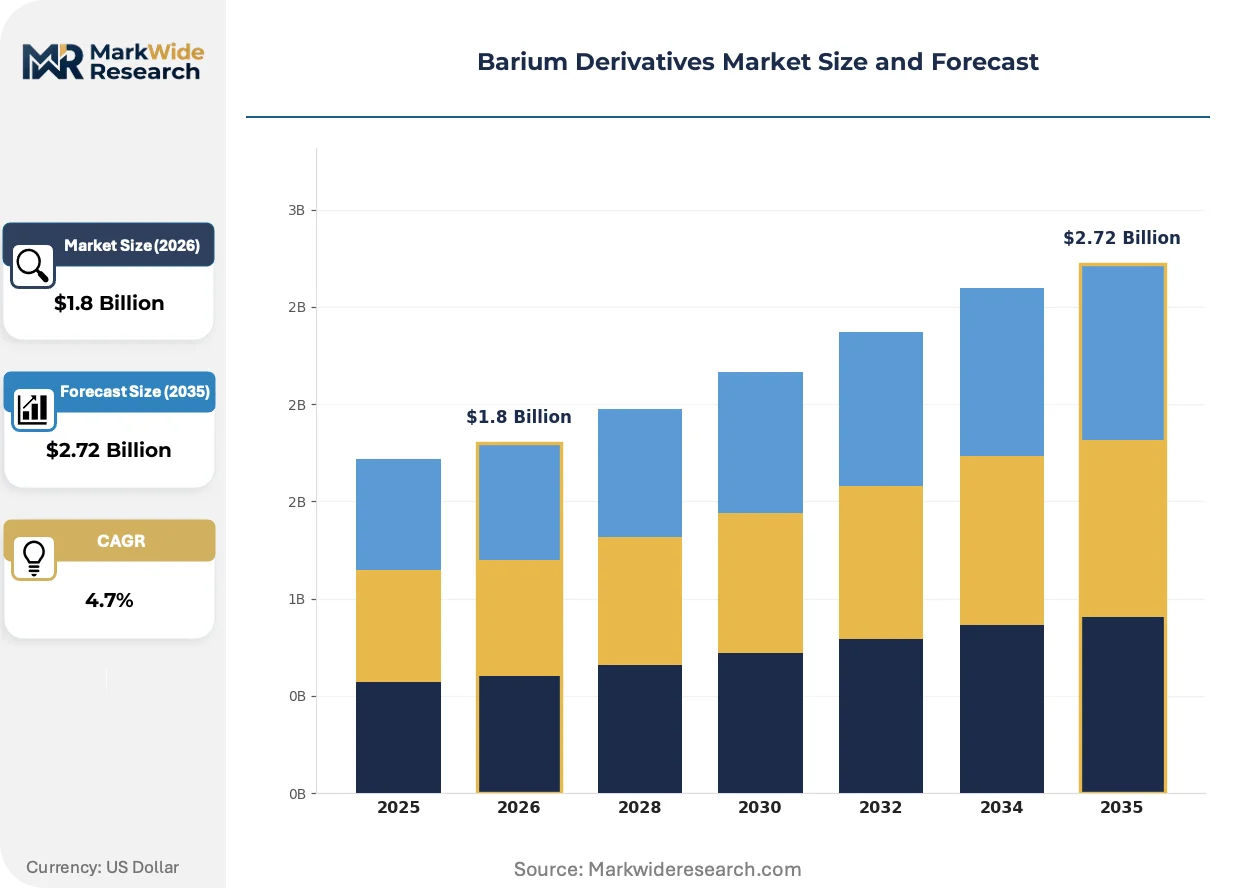
Market Dynamics
China's MEE environmental enforcement is compressing barium salt production capacity, forcing consolidation among smaller acid-digestion operators while redirecting investment toward closed-loop wastewater systems and thermal reduction alternatives.
Growth Catalysts
- Oilfield weighting agent specifications:API drilling fluid standards mandate high-density barium sulfate for deepwater and extended-reach wells, sustaining pull from offshore exploration in the US Gulf Coast and Brazil's pre-salt basins.
- REACH registration barriers:European chemical compliance requirements filter non-certified Asian exporters, creating protected margin pools for registered suppliers serving pharmaceutical and electronics-grade segments.
- Dual carbon policy alignment:China's national emissions targets accelerate cleaner thermal reduction technologies, opening capital deployment pathways for producers retrofitting Zibo and Weifang facilities.
Market Restraints
- Barite ore supply concentration:Guizhou and Hunan provinces control over half of domestic Chinese feedstock, exposing processors to provincial export quota fluctuations and rail logistics bottlenecks.
- Acid digestion cost volatility:Sulfuric acid pricing tied to sulfur burner operations and phosphate fertilizer co-production creates unpredictable input cost swings for technical-grade carbonate and chloride derivatives.
- Calcium carbonate substitution:Lower-density weighting agents penetrate shallow drilling applications where density specifications permit, eroding volume in marginal oilfield service contracts.
Strategic Opportunities
- Pharmaceutical-grade barium sulfate:FDA and EMA radiocontrast media specifications create certified purity premiums for producers achieving USP and EP monograph compliance, with demand anchored in US and German imaging networks.
- Electronics surface treatment expansion:Barium nitrate and barium chloride formulations for printed circuit board metallization are gaining traction in South Korean and Taiwanese semiconductor packaging operations.
- Pyrotechnic specialty channels:Ultra-high-purity nitrate specifications for military and aerospace igniter systems bypass commodity pricing through defense procurement frameworks in NATO-aligned supply chains.
Industry Challenges
- Process engineering talent scarcity:Wet chemistry expertise for acid digestion optimization and precipitation control is concentrating among retiring technical workforces in China's older industrial zones.
- MEE compliance capital intensity:Wastewater treatment retrofits, barium sludge solidification systems, and scrubber installations require 18-24 month payback periods that strain privately held processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Derivatives Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Carbonate, Barium Sulfate, Barium Chloride, Barium Nitrate Application: Paints, Plastics, Pharmaceuticals, Ceramics End User: Automotive, Construction, Healthcare, Electronics Packaging Type: Bags, Drums, Bulk Containers, Pails |
| Companies Covered | Albemarle Corporation, Solvay, BASF, Hebei Xinji Chemical Group, Nippon Chemical Industrial, Barium & Chemicals Inc., Honeywell International, Venator Materials PLC, Vishnu Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Derivatives Market Strategic Shifts
Barium derivative production is bifurcating between commodity-scale acid digestion and precision-controlled precipitation systems, with certification-grade purity becoming the primary axis of supplier differentiation rather than volume throughput.
Continuous-flow precipitation reactors with inline particle size monitoring are overtaking batch crystallization in pharmaceutical-grade barium sulfate manufacturing. European and Japanese contrast media compounders now specify D50 particle distributions below one micron, forcing Chinese exporters to install laser diffraction feedback loops or forfeit high-margin contracts. This equipment shift is compressing the supplier base to operators with capital reserves for automated process control.
REACH authorization requirements for barium compounds are tightening substance volume thresholds and downstream user notification obligations. ECHA's 2023-2024 substance evaluation wave targeted barium salts for reproductive toxicity dossier updates, compelling registrants to generate new mammalian study data. German and French chemical distributors are consolidating import channels through pre-certified traders, excluding smaller Asian producers lacking EU-based only representatives.
Long-term offtake agreements with fixed purity premiums are displacing spot-market procurement in oilfield services. North American drilling contractors now contract directly with registered barite processors for multi-year weighting agent supply, embedding API specification compliance into contract terms. This shift is most visible in Permian Basin operations, where integrated service companies prioritize supply security over quarterly price arbitrage.
Barium Derivatives Market Segmentation
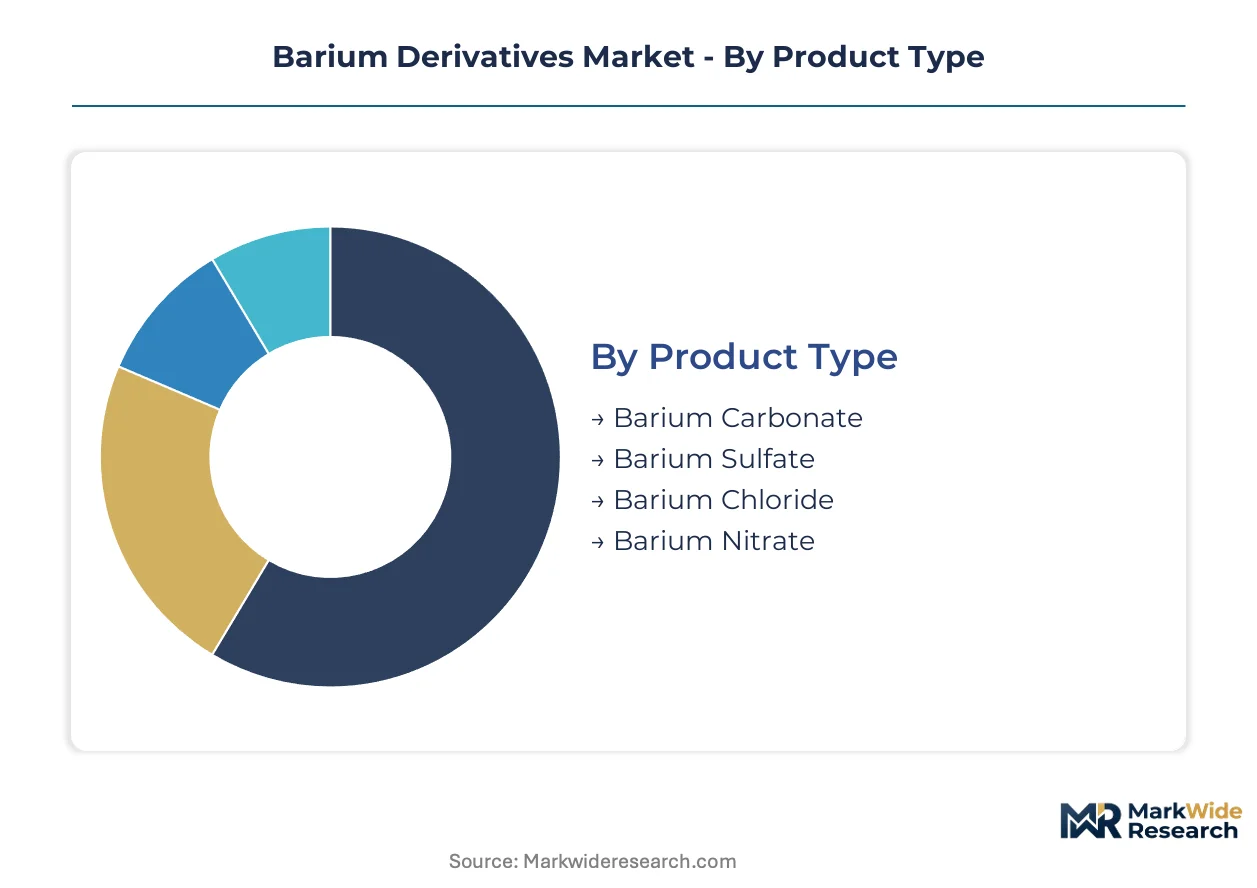
Barium derivatives serve radically different value chains depending on purity grade and delivery format. Segmentation reveals how pharmaceutical-grade sulfate commands margins tenfold above technical-grade carbonate, while packaging specifications determine logistics economics across oilfield, ceramics, and electronics channels.
Product Type:
Integration depth varies sharply: barium sulfate functions as a standalone performance additive in drilling fluids and contrast media, while barium carbonate embeds chemically into ceramic glazes and glass matrices during thermal processing.
- Barium Sulfate:Precipitated or ground mineral forms achieve density specifications from 4.2 to 4.5 g/cm³. API-grade material for Gulf Coast and Brazilian pre-salt drilling anchors volume demand; USP-grade precipitation for German and US imaging networks captures premium pricing.
- Barium Carbonate:Synthesized via acid digestion of barite ore or reduction of sulfate feedstock, with soda ash conversion yielding 99.2% minimum purity. Zibo and Weifang clusters in East China supply Italian and Spanish tile manufacturers facing REACH-registered import requirements.
- Barium Chloride:Dihydrate crystals serve metallurgical flux applications and heat treatment salt baths.
- Barium Nitrate:Ultra-high-purity specifications above 99.5% meet South Korean semiconductor packaging and NATO defense igniter requirements.
Volume placements concentrate in Barium Sulfate; the faster expansion belongs to Barium Nitrate.
Application:
Cost tier stratification separates commodity pigment loads from certified pharmaceutical and medical device pathways.
- Pharmaceuticals:FDA and EMA radiocontrast media specifications mandate USP and EP monograph compliance with D50 particle distributions below one micron. Continuous-flow precipitation reactors with laser diffraction feedback loops now filter out batch-crystallization suppliers lacking capital reserves.
- Ceramics:Barium carbonate functions as a flux and crystallization agent in tile glazes, with Italian manufacturers sourcing through pre-certified traders to satisfy REACH authorization obligations.
- Paints:Blanc fixe precipitated sulfate provides opacity and chemical inertness in industrial coatings.
- Plastics:Filler applications in polypropylene and PVC compounding leverage density and X-ray opacity for medical device tracing.
Margin concentration sits with Pharmaceuticals; volume scale favors Ceramics.
End User:
Customer type determines specification stringency, with healthcare and electronics demanding certified purity subscriptions while construction tolerates technical-grade variability.
- Healthcare:German and US imaging networks contract directly for multi-year radiocontrast supply, embedding FDA and EMA compliance into fixed-premium offtake terms rather than spot procurement.
- Electronics:South Korean and Taiwanese semiconductor packaging operations specify barium nitrate and chloride formulations for printed circuit board metallization, with purity thresholds rising alongside line-width miniaturization.
- Automotive:Brake pad and clutch facing formulations consume technical-grade sulfate as a friction modifier.
- Construction:Tile, glass, and cement applications absorb carbonate and sulfate derivatives with minimal certification overhead.
Specification intensity peaks in Healthcare; procurement scale runs through Construction.
Packaging Type:
Supply chain configuration dictates format selection, with offshore oilfield logistics favoring bulk and pharmaceutical distribution requiring contamination-controlled pails.
- Bulk Containers:Intermodal tank containers and pneumatic trailers serve Permian Basin drilling contractors under multi-year API-grade supply contracts, minimizing handling costs for high-volume weighting agent offtake.
- Drums:Steel and fiber drums with liner systems protect hygroscopic barium chloride and nitrate from moisture degradation during ocean freight from Chinese ports to European compounders.
- Bags:Multi-wall paper and woven polypropylene sacks handle technical-grade carbonate for ceramic tile manufacturers.
- Pails:Sealed plastic pails with tamper-evident closures satisfy pharmaceutical-grade sulfate requirements for contrast media compounders in US and German imaging networks.
Logistics efficiency concentrates in Bulk Containers; contamination control drives Pails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zibo and Weifang in East China host the densest clusters of barium salt processing capacity, with provincial regulators enforcing stricter discharge limits that redirect investment toward closed-loop wastewater systems.
China
Guizhou and Hunan provinces control over half of domestic barite ore feedstock, exposing processors to provincial export quota fluctuations. MEE wastewater discharge limits compel capital upgrades that smaller acid-digestion operators cannot absorb, forcing consolidation. Zibo and Weifang facilities are retrofitting thermal reduction alternatives to align with national dual carbon goals.
United States
API drilling fluid standards mandate high-density barium sulfate for deepwater and extended-reach wells in the Gulf Coast. EPA and OSHA jointly govern permissible exposure limits and waste classification for barium compounds in industrial settings. Permian Basin drilling contractors now contract directly with registered processors for multi-year weighting agent supply.
Germany
German imaging networks anchor European radiocontrast media demand, contracting for multi-year supply with fixed purity premiums. ECHA substance evaluation waves target barium salts for reproductive toxicity dossier updates, compelling registrants to generate new mammalian study data. German chemical distributors consolidate import channels through pre-certified traders.
Japan
Ultra-high-purity barium nitrate specifications for pyrotechnic and electronics applications differentiate Japanese suppliers in regional markets. METI standards govern chemical purity thresholds for semiconductor packaging materials. Domestic producers serve South Korean and Taiwanese electronics surface treatment operations with certified reagent-grade formulations.
India
Ceramic tile manufacturers in Gujarat and Rajasthan source barium carbonate through pre-certified traders to satisfy export compliance requirements. BIS standards for chemical purity create certification barriers for technical-grade imports. Domestic processors in Maharashtra are expanding acid-digestion capacity to serve construction sector demand.
Barium Derivatives Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across certification-grade and technical-grade segments. The supplier base compresses toward operators with capital reserves for automated process control and REACH registration infrastructure. Three archetypes dominate: integrated ore-to-derivative processors with captive feedstock, specialty chemical houses with pharmaceutical-grade certification, and regional distributors with pre-certified import channels. Competitive moves center on multi-year offtake agreements with fixed purity premiums and M&A targeting wastewater-compliant processing assets.
Among European specialty chemical houses, Solay anchors premium positioning through REACH compliance infrastructure. Hebei Xinji Chemical Group exemplifies the integrated processor archetype with ore-to-derivative operations in Hebei Province. Nippon Chemical Industrial occupies the ultra-high-purity specialist tier, serving pyrotechnic and electronics applications with certified reagent-grade formulations.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Solvay |
| BASF |
| Hebei Xinji Chemical Group |
| Nippon Chemical Industrial |
| Barium & Chemicals Inc. |
| Honeywell International |
| Venator Materials PLC |
| Vishnu Chemicals |
| Others |
Value Chain & Pricing Dynamics
Continuous-flow precipitation reactors with inline particle size monitoring simultaneously compress production costs for pharmaceutical-grade barium sulfate and consolidate supply among capital-rich operators capable of automated process control. This equipment transition redirects margin capture toward Zibo and Weifang facilities with closed-loop wastewater systems, while batch-crystallization processors face exclusion from high-purity contracts.
Pricing Analysis
USP and EP monograph compliance anchors value-based pricing premiums for radiocontrast media applications, with fixed-premium multi-year offtake terms displacing spot procurement in German and US imaging networks. Price differentiation separates pharmaceutical-grade sulfate from technical-grade carbonate through certification overhead and particle distribution specifications, with D50 below one micron commanding substantial premiums. Cost compression in API-grade drilling fluid segments intensifies as calcium carbonate substitutes penetrate shallow-well applications. Construction sector buyers exhibit highest price sensitivity, while healthcare networks prioritize supply security over quarterly arbitrage.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg consolidate REACH-registered imports for European compounders, creating hub-and-spoke patterns that filter non-compliant Asian exporters. Supply concentrates in China, with Guizhou and Hunan provinces controlling barite ore feedstock and Zibo-Weifang clusters dominating derivative processing. Sulfuric acid pricing volatility, tied to phosphate fertilizer co-production, feeds unpredictable input cost swings. Single-source vulnerability runs through provincial export quota fluctuations. Distribution runs through pre-certified traders for pharmaceutical-grade segments, while bulk intermodal containers serve Permian Basin drilling contractors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barium derivative production is transitioning from acid-digestion batch processing to continuous-flow precipitation systems, with legacy operators facing stranded asset risk absent capital reserves for automated control infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into Guizhou barite ore sources and accelerated MEE-compliant wastewater retrofit programs. Solvay's REACH infrastructure demonstrates how certification investment creates protected margin pools against non-compliant Asian export pressure. Prioritize multi-year offtake embedding API specification compliance to lock Permian Basin drilling contractors before direct-procurement patterns solidify. For New Entrants and Emerging Players: Capture white-space opportunity in South Korean and Taiwanese electronics surface treatment channels, where barium nitrate purity specifications for semiconductor packaging remain underpenetrated by established suppliers. India's ceramic tile export compliance requirements create accessible entry through pre-certified trader partnerships. Lead with reagent-grade formulation capabilities rather than commodity volume scale. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical houses with pharmaceutical-grade certification infrastructure and integrated ore-to-derivative processors with captive feedstock security. Long-term viability favors operators with demonstrated MEE compliance capital deployment and thermal reduction technology transition execution. Watch ECHA substance evaluation waves targeting reproductive toxicity dossier updates as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Ore Sources | Captive Guizhou and Hunan feedstock secures supply against provincial export quota volatility. |
| Continuous-Flow Reactor Installation | Laser diffraction feedback loops unlock USP-grade contracts with German imaging networks. |
| REACH Registration Infrastructure Investment | EU-based only representative status filters competition from non-compliant Asian exporters. |
| Long-Term Supply Agreement with Fixed Purity Premiums | Multi-year offtake terms with Permian Basin contractors displace spot-market procurement patterns. |
| Closed-Loop Wastewater System Retrofit | MEE compliance capital deployment forces consolidation among smaller acid-digestion operators. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving barium salt plant managers, procurement leads at oilfield service companies, pharmaceutical compounder technical directors, and ceramic tile manufacturer supply planners. ACC and Cefic chemical industry reports, Chinese MEE discharge compliance databases, SEC 10-K filings from listed processors, and ECHA REACH registration dossiers supplied quantitative benchmarks. Bottom-up capacity assessments across Zibo and Weifang facilities triangulated against top-down end-use demand modeling for drilling fluids and radiocontrast applications.
Data-stream reconciliation across production volume surveys, import-export trade statistics, and end-user procurement patterns shaped the analytical framework. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions across the projection horizon. CAGRs derived from weighted average of historical trajectory analysis and demand elasticity coefficients for oilfield exploration activity and medical imaging procedure volumes. Forecast inputs included API drilling rig count projections and EMA radiocontrast media approval timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity, ECHA authorization threshold revisions, and calcium carbonate substitution rates in shallow drilling applications. Outputs reflect documented assumptions regarding dual carbon policy alignment pace and REACH registration barrier maintenance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Epoxidized Soybean Oil Market