
 Global Bronze Market | 2026-2036
Global Bronze Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bronze Market Foresight
Capital-intensity divergence between integrated smelters and downstream fabricators is unwinding traditional competitive boundaries in bronze supply. Aurubis AG leverages captive copper refining to control input costs across European distribution. Wieland Group anchors its position through continuous casting investments in Germany and Asia. Ningbo Boway Alloy Material Co., Ltd. competes on scale in phosphor bronze strip for electronics connectors.
Bronze is a copper-tin alloy typically containing 3–12% tin by weight, with phosphorus, aluminum, or silicon additions engineered for specific mechanical and corrosion properties; manufacturers produce it through sand casting, continuous casting, or hot and cold working to achieve tensile strengths ranging from 200 to 800 MPa depending on composition and temper. Phosphor bronze dominates electrical connector applications due to its fatigue resistance and spring characteristics, while aluminum bronze commands premium positioning in marine propellers and offshore valves where cavitation resistance matters. Rod and wire forms sustain higher per-kilogram margins than commodity sheet, reflecting tighter dimensional tolerances and specialized heat treatment requirements.
REACH restrictions on lead content in copper alloys and the EU F-Gas Regulation indirectly shape bronze demand by limiting substitute materials in HVAC and refrigeration components. China's SAMR enforces GB standards for non-ferrous metal emissions that affect foundry investment decisions. The US EPA and OSHA jointly regulate foundry particulate exposure, raising compliance costs for smaller North American casters. Stakeholders must monitor alloy substitution threats from engineered polymers in bearing applications and regulatory divergence between Asian and European chemical composition standards.
Market Dynamics
Lead-free alloy mandates across marine and potable water applications are forcing foundries to reformulate tin-bronze compositions, compressing margins for smaller casters while rewarding integrated producers with captive metallurgical R&D.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic refrigerants in HVAC systems preserve bronze valve and compressor component demand by limiting polymer substitution in high-pressure fittings.
- Marine electrification:South Korean shipbuilders are expanding procurement of nickel-aluminum bronze for corrosion-resistant electric propulsion housings in battery-hybrid vessels.
- Continuous casting technology:Investment in horizontal continuous casting lines is improving yield rates for phosphor bronze strip used in precision electronics connectors.
Market Restraints
- Tin price volatility:Concentrated Indonesian and Chinese smelter supply creates input cost instability that sand-casting foundries cannot pass through to long-term industrial contracts.
- REACH lead restrictions:ECHA enforcement of lead content limits in copper alloys forces costly reformulation of traditional bearing bronzes for European automotive and plumbing markets.
- Engineered polymer substitution:High-performance polyetheretherketone and polyphenylene sulfide materials are capturing low-load bearing applications previously served by sintered bronze.
Strategic Opportunities
- India infrastructure buildout:BIS certification requirements for potable water fittings create premium positioning for lead-free silicon bronze in municipal plumbing systems.
- Offshore wind mooring systems:Cavitation-resistant aluminum bronze is penetrating jacket foundation and dynamic cable applications as floating wind capacity expands.
- Digital alloy design:Machine learning integration with CALPHAD thermodynamic modeling is accelerating development of custom bronze compositions for niche friction and wear applications.
Industry Challenges
- Metallurgical talent scarcity:Foundry engineering programs in Germany and the United States are producing insufficient graduates to replace retiring non-ferrous casting specialists.
- Dual certification timelines:Concurrent GB standard compliance for Chinese export markets and EN standards for European customers extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bronze Market |
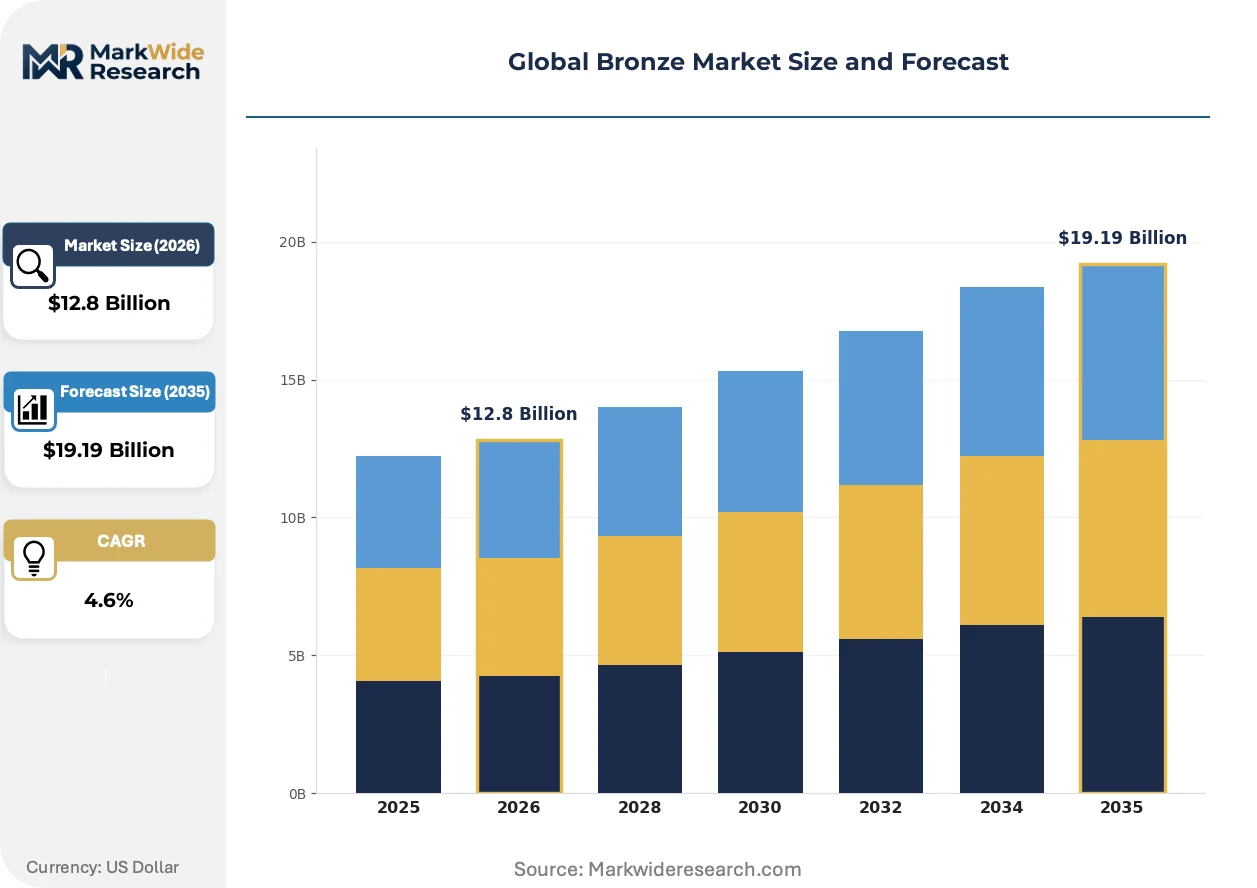
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphor Bronze, Aluminum Bronze, Silicon Bronze, Manganese Bronze, Nickel Bronze Form: Sheet, Rod, Wire, Tube, Casting Application: Marine Components, Electrical Connectors, Musical Instruments, Bearings, Decorative Items End User Industry: Construction, Electronics, Transportation, Art & Craft, Aerospace |
| Companies Covered | Aurubis AG, Wieland Group, KME Germany GmbH & Co. KG, Lebronze Alloys, Diehl Metall Stiftung & Co. KG, Mitsubishi Materials Corporation, Aviva Metals, Concast Metal Products Co., Ningbo Boway Alloy Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bronze Market Shifts & Advancements
Additive manufacturing of copper alloys is moving from prototyping to functional component production, with directed energy deposition now achieving density levels suitable for conformal cooling channels in plastic injection molds.
Near-net-shape powder metallurgy is displacing conventional investment casting for complex bronze impellers and pump components. Aerospace and chemical processing equipment manufacturers are adopting metal injection molding for aluminum bronze parts below 200 grams. The technology is compressing lead times from twelve weeks to three while reducing material waste rates by half.
China's GB standards for non-ferrous metal emissions are tightening particulate and sulfur dioxide limits across foundry operations. SAMR enforcement is accelerating consolidation among smaller casters in Zhejiang and Jiangsu provinces. European exporters serving Chinese marine and power generation markets must now document compliance with MEE environmental audits to maintain supplier qualification.
Specification-driven procurement is consolidating buyer power among tier-one automotive and industrial OEMs. Long-term alloy supply agreements with indexed tin pricing are replacing spot market purchases for high-volume phosphor bronze consumers. Germany's precision engineering corridor around Stuttgart exhibits the most advanced contract structuring, with foundries accepting penalty clauses for dimensional tolerance deviations below 25 micrometers.
Global Bronze Market Segmentation
Bronze alloys fragment across metallurgical specifications that trigger divergent regulatory compliance burdens. Each segment carries distinct REACH, GB, and BIS certification requirements that reshape procurement patterns among marine, electronics, and infrastructure end users.
Product Type:
ECHA lead restrictions and SAMR emissions standards force foundries to document alloy composition at the elemental level, raising qualification costs disproportionately for specialty grades.
- Phosphor Bronze:Copper-tin alloys with 0.01–0.35% phosphorus addition deliver fatigue resistance and spring characteristics critical for precision electrical contacts. South Korean electronics manufacturers in the Gyeonggi-do corridor specify this grade for high-density connector arrays in 5G infrastructure.
- Aluminum Bronze:Copper-aluminum systems containing 8–12% aluminum provide cavitation resistance for marine propulsion. German shipyards in Hamburg and Bremerhaven specify nickel-aluminum bronze variants for electric propulsion housings in battery-hybrid vessels.
- Silicon Bronze:Silicon additions improve weldability and corrosion resistance for potable water applications. Indian municipal infrastructure projects under BIS certification mandate this grade for lead-free plumbing fittings.
- Manganese Bronze:Manganese and iron additions enhance tensile strength for heavy-duty bearings and gears. Foundries serving Brazilian mining equipment OEMs favor this composition for load-bearing bushings.
- Nickel Bronze:Nickel content above 2% improves saltwater corrosion resistance for offshore hardware. Norwegian floating wind developers specify this grade for dynamic cable protection systems.
Phosphor bronze handles the majority of throughput; aluminum bronze is expanding most quickly on share.
Form:
Continuous casting investments in Germany and China have compressed dimensional tolerances for strip and wire products, widening margin spreads against sand-cast alternatives.
- Sheet:Cold-rolled phosphor bronze strip serves precision stamping operations for electronics connectors. Stuttgart-area fabricators supply automotive sensor housings with thickness tolerances below 25 micrometers.
- Rod:Extruded and drawn rod forms sustain premium positioning through tighter straightness specifications. Wieland Group's continuous casting lines in Ulm achieve yield rates above 90% for free-cutting rod grades.
- Wire:Fine wire diameters below 0.5 millimeter serve spring and electrical winding applications. Japanese manufacturers in Osaka prefecture dominate ultra-fine phosphor bronze wire for consumer electronics.
- Tube:Seamless bronze tubing serves heat exchanger and condenser applications. US Gulf Coast petrochemical facilities specify aluminum bronze tubes for seawater cooling systems.
- Casting:Sand and investment casting retains dominance for complex marine propellers and valve bodies. Indonesian foundries face MEE audit requirements for exports to Chinese shipbuilders.
Sheet and rod command the steepest margin premiums; wire is climbing fastest on specification intensity.
Application:
End-use certification requirements fragment demand across marine classification societies, automotive IATF standards, and electronics IPC specifications.
- Marine Components:Propellers, valves, and pump housings require DNV or ABS classification approval. South Korean shipbuilders in Geoje source nickel-aluminum bronze for corrosion-resistant electric propulsion systems.
- Electrical Connectors:Phosphor bronze strip dominates socket and terminal applications through fatigue resistance. German automotive tier-ones specify tin-plated variants for high-voltage EV interconnects.
- Musical Instruments:Acoustic properties of phosphor and silicon bronze sustain artisanal demand for cymbals and saxophone bodies. Turkish cymbal manufacturers in Istanbul source specific temper grades for tonal consistency.
- Bearings:Sintered bronze bushings face substitution pressure from engineered polymers in low-load applications. Indian textile machinery OEMs in Coimbatore specify oil-impregnated grades for spindle bearings.
- Decorative Items:Architectural bronze serves facades, statuary, and hardware with patina specifications. French heritage restoration projects in Paris mandate traditional tin-bronze compositions for monument compatibility.
Marine components and electrical connectors absorb the bulk of volume; offshore wind hardware is gaining share fastest.
End User Industry:
Procurement consolidation among tier-one OEMs concentrates contract power in construction and electronics verticals.
- Construction:Municipal plumbing and architectural metalwork drive silicon bronze demand. India's AMRUT urban infrastructure scheme specifies lead-free grades for potable water distribution.
- Electronics:Connector, relay, and semiconductor packaging applications sustain phosphor bronze consumption. Taiwanese contract manufacturers in Taoyuan source ultra-thin strip for smartphone component miniaturization.
- Transportation:Marine, rail, and aerospace systems require certified bearing and bushing alloys. Deutsche Bahn specifies manganese bronze for high-speed rail pantograph components.
- Art & Craft:Sculptural casting and musical instrument fabrication sustain artisanal foundry demand. Italian bronze foundries in Pietrasanta serve global gallery and monument commissions.
- Aerospace:Landing gear bushings and engine components specify aluminum bronze for wear resistance. Safran Landing Systems sources French-produced grades for A320 family undercarriages.
Construction and electronics dominate procurement volume; aerospace specifications are tightening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foundries absorb tin price swings through state-backed inventory programs, while German precision engineers reject cost pass-through for dimensional tolerances below 25 micrometers. Indian municipal buyers exhibit intermediate elasticity, accepting lead-free premiums for BIS-certified potable water fittings.
China
Marine electrification drives nickel-aluminum bronze procurement from South Korean shipbuilders sourcing through Chinese distributors. SAMR enforces GB standards for non-ferrous metal emissions that accelerate foundry consolidation in Zhejiang and Jiangsu provinces. Ningbo anchors phosphor bronze strip production for electronics connector exports to Taiwanese contract manufacturers.
Germany
Stuttgart-area fabricators supply automotive sensor housings with thickness tolerances below 25 micrometers, commanding premium positioning. ECHA REACH restrictions on lead content force reformulation of traditional bearing bronzes for European automotive markets. The Ruhr industrial basin sustains captive copper refining through Aurubis AG to control input costs across European distribution.
South Korea
Geoje shipyards expand procurement of corrosion-resistant electric propulsion housings in battery-hybrid vessels. The country's national environmental regulator tightens foundry particulate exposure limits in alignment with MEE audit requirements for Chinese export markets. The Gyeonggi-do electronics corridor specifies phosphor bronze for high-density connector arrays in 5G infrastructure.
India
AMRUT urban infrastructure schemes specify lead-free silicon bronze for municipal potable water distribution systems. BIS certification requirements create premium positioning for compliant foundries against unorganized sector competitors. Coimbatore textile machinery OEMs specify oil-impregnated bronze grades for spindle bearings facing engineered polymer substitution pressure.
United States
Gulf Coast petrochemical facilities specify aluminum bronze tubes for seawater cooling systems in downstream processing. EPA and OSHA joint regulation of foundry particulate exposure raises compliance costs for smaller North American casters. Aviva Metals anchors distribution networks serving aerospace landing gear specifications for wear-resistant bearing alloys.
Global Bronze Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive copper refining separating cost-stable producers from margin-compressed sand casters. The structure rewards backward integration into primary metal production and continuous casting technology deployment. Three archetypes dominate: integrated smelter-fabricators controlling input costs, continuous casting specialists compressing dimensional tolerances, and scale-driven strip producers serving electronics miniaturization. Competitive moves concentrate on metallurgical R&D for lead-free reformulations and dual-certification investments spanning GB and EN standards.
Among German-based integrated producers, Aurubis AG and Wieland Group exemplify the captive-refining archetype, with the latter anchoring continuous casting investments across European and Asian production nodes. Ningbo Boway Alloy Material Co., Ltd. occupies a position within the scale-driven phosphor bronze tier, representing Chinese fabrication capacity serving global electronics connector demand. These three entities illustrate the geographic and structural diversity of competitive positioning without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Aurubis AG |
| Wieland Group |
| KME Germany GmbH & Co. KG |
| Lebronze Alloys |
| Diehl Metall Stiftung & Co. KG |
| Mitsubishi Materials Corporation |
| Aviva Metals |
| Concast Metal Products Co. |
| Ningbo Boway Alloy Material Co., Ltd. |
| Others |
Supply & Pricing Matrix
Long-term alloy supply agreements with indexed tin pricing lock in procurement visibility for high-volume phosphor bronze consumers while exposing sand-casting foundries to margin compression when Indonesian smelter supply tightens. Stuttgart-area fabricators enforce penalty clauses for dimensional tolerance deviations below 25 micrometers, transferring metallurgical risk onto suppliers.
Pricing Analysis
After-sales technical service and alloy qualification support drive lifetime value for continuous casting specialists serving precision electronics. Contract-based long-term offtake dominates procurement, with price differentiation resting on certification grade and volume scale. Cost compression in sand-cast bearing grades is intensifying because REACH lead restrictions force costly reformulation. Tier-one automotive OEMs exhibit lowest price sensitivity; unorganized Indian foundries face highest buyer pressure on lead-free silicon bronze.
Supply Chain Analysis
Strategic tin stockpiling through state-backed inventory programs in China contrasts with just-in-time raw material flows among German continuous casting specialists. Concentrated supply draws from Indonesia, China, and Peru for tin concentrate; copper cathode feeds from Chile and Zambia. Single-source vulnerability runs through Indonesian smelter consolidation. Distribution feeds from integrated smelter-fabricators through regional service centers to tier-one OEM procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-driven procurement is creating platform-economics dynamics where alloy qualification databases and dual-certification documentation become the interoperability layer locking in buyer-supplier relationships.
For Market Incumbents: Secure captive copper refining capacity to buffer tin price volatility and defend margin position against integrated Asian competitors. Accelerate metallurgical R&D investment for lead-free bearing formulations ahead of ECHA enforcement expansion. Extend dual-certification capabilities spanning GB and EN standards to compress qualification cycles for Chinese export markets. For New Entrants and Emerging Players: Differentiate on digital alloy design capabilities using machine learning-CALPHAD integration for niche friction applications underserved by scale producers. Target Indian municipal infrastructure under AMRUT schemes with BIS-certified lead-free silicon bronze. Pursue direct qualification with South Korean shipbuilders in Geoje for nickel-aluminum bronze electric propulsion components. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with captive metallurgical R&D and continuous casting technology deployment. Long-term viability hinges on exposure to marine electrification and offshore wind hardware rather than commodity bearing substitution. Watch engineered polymer penetration rates in low-load applications as the inflection signal for bronze demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Copper Refining | Aurubis AG leverages in-house cathode production to control input costs across European distribution networks. |
| Continuous Casting Technology Deployment | Wieland Group's horizontal casting lines in Ulm achieve yield rates above 90% for precision rod grades. |
| Dual Certification Investment (GB/EN Standards) | Accelerates supplier qualification for Chinese marine markets under MEE environmental audit requirements. |
| Lead-Free Alloy Reformulation R&D | Addresses ECHA REACH restrictions forcing composition changes in traditional automotive bearing bronzes. |
| Machine Learning Alloy Design Integration | Compresses development timelines for custom bronze compositions in niche friction and wear applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, foundry association reports, SEC filings from listed copper producers, and national emissions disclosures. Primary interviews engaged metallurgical R&D directors, procurement leads at tier-one marine and automotive OEMs, foundry operations managers, and distribution channel partners. Secondary validation drew from ECHA regulatory filings, SAMR GB standard documentation, BIS certification records, and DNV classification society approvals. Bottom-up alloy demand modeling triangulates against top-down copper consumption benchmarks.
Segmentation dimensions modeled include alloy composition grade, product form, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from volume trajectory analysis indexed to tin price scenarios and foundry capacity utilization trends. Industry-specific inputs incorporate marine electrification procurement schedules, electronics connector miniaturization roadmaps, and municipal infrastructure buildout pipelines.
Material uncertainties — tin supply disruption from Indonesian export policy shifts, engineered polymer substitution acceleration, and divergence between Asian and European chemical composition standards — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement timelines and shipbuilder procurement patterns. Revision becomes warranted when polymer bearing penetration in sub-50 MPa load applications crosses thresholds that trigger accelerated OEM specification changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Crude Steel Market
Metals
Nickel Foam Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Aluminum Welding Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Qatar Metalworking Market
Metals
North America Metal Casting Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Armour Steel Plate Market
Metals
Barium Market
Metals
GCC Aluminium Cans Market
Metals
Aluminium Rolled Products Market
Metals
High Carbon Bearing Steel Market
Metals
GCC Metal Forging Market
Metals
Silver Cyanide Market
Metals
Copper Wire Market