
 Egypt Ceramic Tiles Market | 2026-2036
Egypt Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Ceramic Tiles Market Foresight
After-sales maintenance and installation support services is broadening revenue streams beyond pure tile sales. Ceramica Cleopatra leverages vertical integration from raw material extraction to retail distribution across Upper Egypt. Pharaohs Ceramics Group anchors its position through specialized export channels targeting Sub-Saharan African markets. Lecico Egypt differentiates via deep product specialization in sanitary ware adjacent categories.
Ceramic tiles are fired clay-based surfacing materials, typically composed of kaolin, feldspar, and quartz sintered at temperatures exceeding 1,000 degrees Celsius, engineered for durability, moisture resistance, and aesthetic finish in built environments. Porcelain tiles command premium positioning due to lower water absorption rates below 0.5 percent, while glazed variants dominate residential application volume through cost accessibility and design versatility. Large format tiles capture accelerating specification from commercial developers seeking reduced grout lines and seamless visual continuity in hospitality and retail fit-outs.
Egyptian Organization for Standardization and Quality (EOS) mandates compliance with ES standards for mechanical strength and chemical resistance, directly filtering market access for imported and domestic production alike. The Industrial Development Authority coordinates factory licensing and environmental permitting, shaping capital deployment timelines and plant location decisions across Suez Canal Economic Zone and 10th of Ramadan industrial corridors. Stakeholders must monitor how anticipated building energy efficiency codes and green construction certification adoption will redirect specification criteria toward thermally optimized tile systems.
Market Dynamics
Megaproject concentration in the New Administrative City and Alexandria corridor is reshaping demand patterns, pulling specification toward large-format porcelain and compressing procurement timelines for domestic manufacturers competing against Turkish and Italian imports.
Growth Catalysts
- Residential construction:Greater Cairo's urban expansion drives volume absorption across middle-income housing developments, with developers specifying glazed ceramic for cost-sensitive unit interiors.
- ES standards compliance:EOS mechanical strength and chemical resistance mandates filter import competition, creating protected runway for certified domestic production.
- Sub-Saharan export channels:Specialized logistics corridors through Port Sudan and Mombasa unlock adjacent market access for Egyptian-manufactured tiles.
Market Restraints
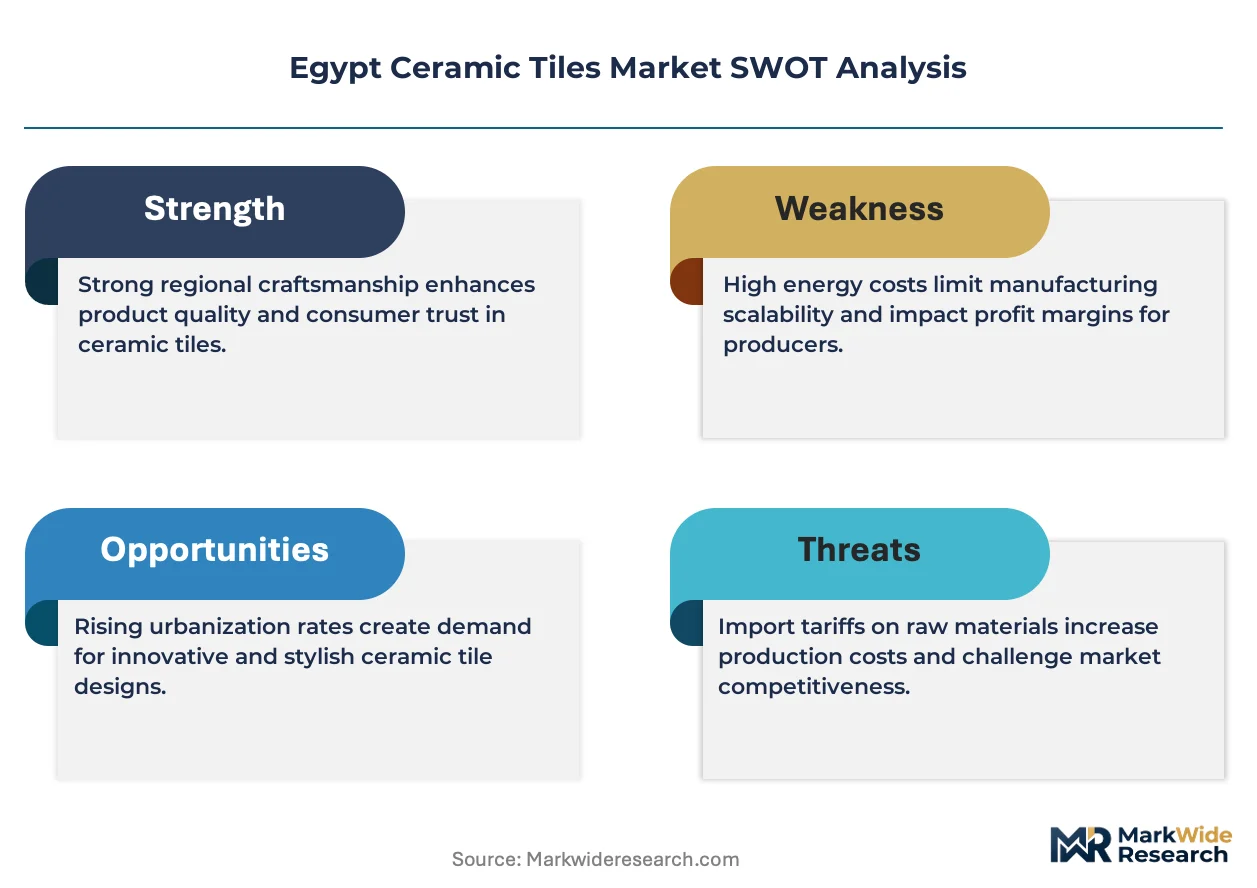
- Natural gas price volatility:Kiln operations depend on subsidized Egyptian Natural Gas Holding Company supply, with tariff adjustments compressing margin predictability for energy-intensive firing processes.
- Kaolin deposit concentration:Upper Egypt's Aswan and Qena governates control premium raw material access, concentrating upstream supply leverage among vertically integrated incumbents.
- Import substitution pressure:Turkish ceramic exports exploit preferential trade terms under the Egypt-Turkey Free Trade Agreement, pressuring domestic price positioning in mid-tier segments.
Strategic Opportunities
- Suez Canal Economic Zone:Industrial Development Authority incentives for capital-intensive manufacturing create favorable depreciation schedules and customs exemptions for export-oriented plant investment.
- Thermally optimized tile systems:Anticipated building energy efficiency codes will redirect specification criteria toward cool-roof and insulated facade applications.
- Installation service bundling:After-sales maintenance contracts represent unbundled revenue streams beyond commodity tile sales, particularly in commercial hospitality fit-outs.
Industry Challenges
- Skilled kiln technician scarcity:Temperature control expertise for large-format porcelain firing remains concentrated among legacy operator workforces, constraining production scale-up.
- Environmental permitting timelines:Industrial Development Authority factory licensing and air quality compliance reviews extend capital deployment cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Ceramic Tiles Market |
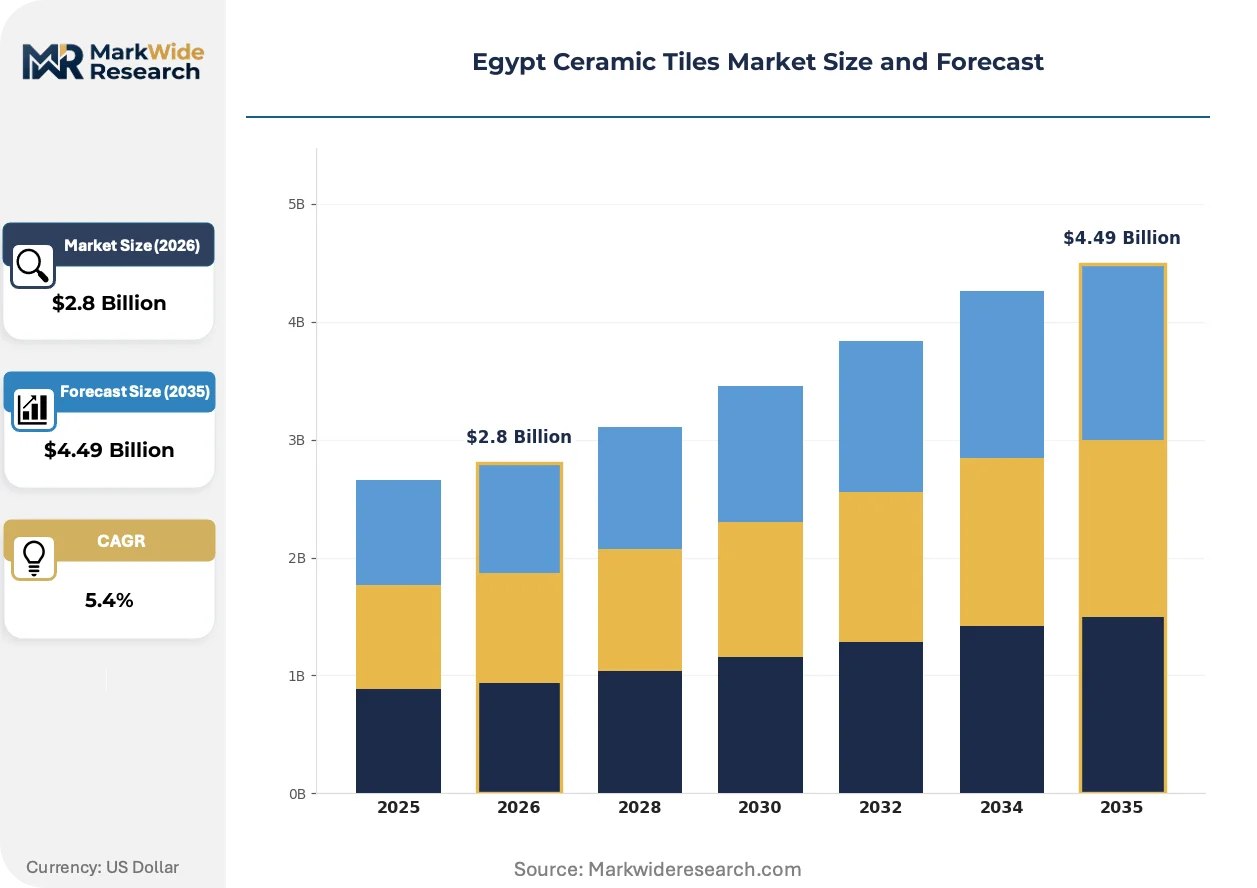
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glazed, Unglazed, Mosaic Application: Residential, Commercial, Industrial, Institutional Size: Small Format, Large Format, Custom Size, Rectified Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Ceramica Cleopatra, Lecico Egypt, Pharaohs Ceramics Group, Al-Ezz Ceramics and Porcelain, Misr International Ceramic Company, Al Amir Ceramics, Ceramica Venzia, Gloria Ceramics, Ceramica Prima, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Ceramic Tiles Market Shifts & Advancements
Digital inkjet decoration and thin-body porcelain technologies are compressing traditional manufacturing cost structures while enabling design differentiation previously restricted to premium imports.
Thin-body porcelain slabs are absorbing specification share from conventional full-body tiles in commercial retail and hospitality fit-outs. Property developers in New Cairo and Sheikh Zayed City are specifying 3-6mm thickness variants for facade cladding and interior wall applications. The technology is absorbing margin pressure from Turkish imports by reducing raw material inputs and shipping weights.
EOS certification requirements for mechanical strength and chemical resistance are tightening market access filters. Domestic manufacturers must demonstrate compliance through accredited testing laboratories in Cairo and Alexandria. The New Administrative City's government building specifications now mandate EOS-certified sourcing, redirecting procurement away from uncertified import channels.
Developer procurement teams are consolidating supplier relationships around full-service providers offering design consultation, technical specification support, and installation supervision. Large-format tile specification in Alexandria's coastal resort projects increasingly bundles material supply with certified installer networks. This pattern concentrates contract value among vertically integrated Egyptian manufacturers with captive distribution capabilities.
Egypt Ceramic Tiles Market Segmentation
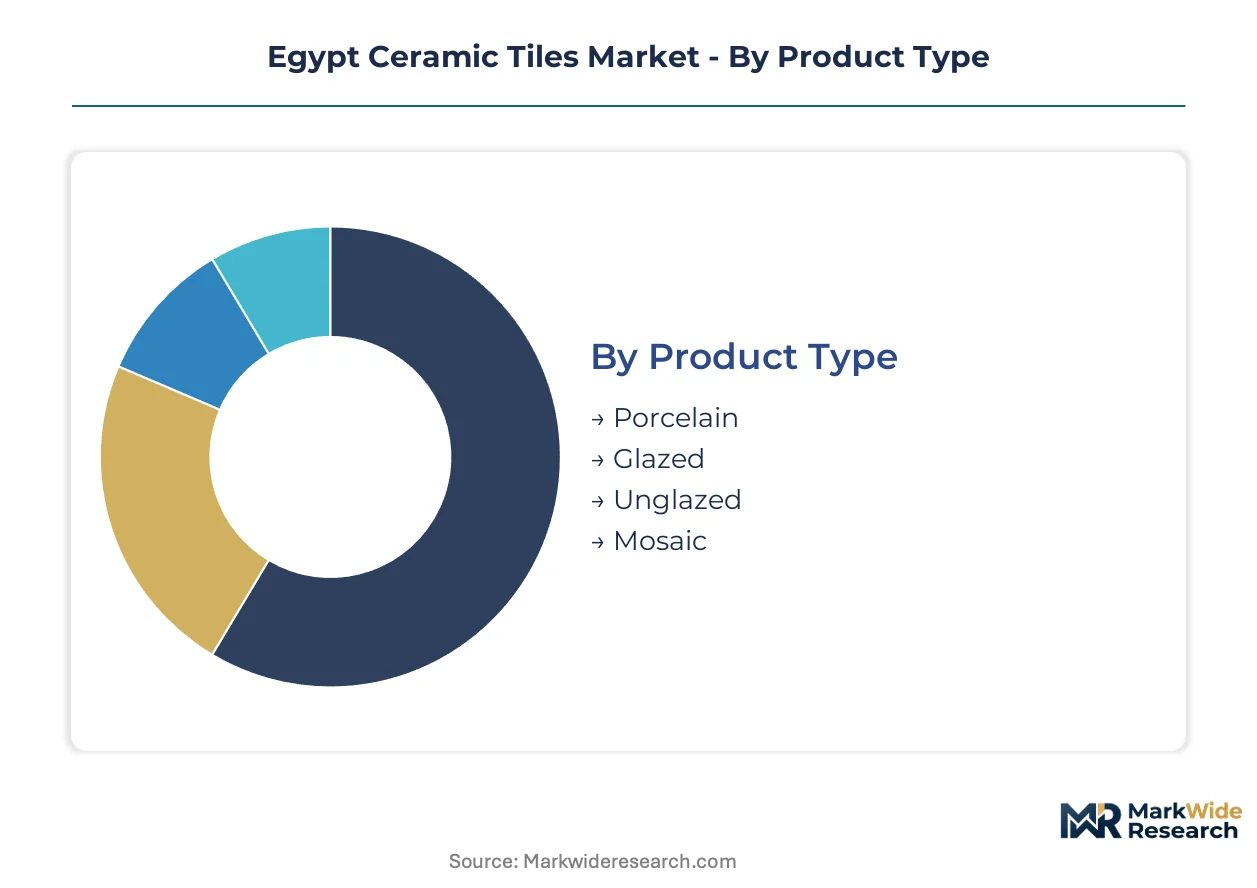
Egypt's ceramic tiles market fragments across technical specifications, end-use applications, and procurement channels. Specification choices in New Administrative City megaprojects cascade through distribution networks, compressing manufacturer response timelines. Segmentation discipline separates commodity volume plays from premium positioning opportunities.
Product Type:
Technical specifications differentiate firing temperatures, water absorption thresholds, and surface durability profiles. Egyptian manufacturers optimize kiln configurations around EOS mechanical strength mandates.
- Porcelain:Full-body vitrified tiles fired above 1,200 degrees Celsius achieve water absorption below 0.5 percent. New Administrative City government buildings specify porcelain for high-traffic corridors, with procurement teams prioritizing EOS-certified domestic sources over Turkish imports.
- Glazed:Clay-based substrates carry applied glass coatings enabling design versatility at accessible price points. Greater Cairo middle-income housing developments absorb glazed ceramic volume, though natural gas tariff volatility compresses firing cost predictability for manufacturers.
- Unglazed:Dense, through-body color tiles resist surface wear in heavy commercial applications. Industrial flooring in 10th of Ramadan industrial corridors specifies unglazed variants for chemical resistance.
- Mosaic:Small-format tesserae assembled for decorative accent applications. Alexandria coastal resort bathrooms and hospitality spas drive mosaic specification through design consultant channels.
Mature deployment sits with glazed ceramic across residential mass housing. Newer deployment is concentrated in porcelain specification for government and commercial prestige projects.
Application:
End-use segmentation maps to construction cycle timing, budget allocation authority, and technical specification complexity. Each vertical channels through distinct procurement decision-makers.
- Residential:Volume absorption concentrates in Greater Cairo's urban expansion corridors, with developers specifying cost-optimized glazed ceramic for unit interiors. Sixth of October City and New Cairo satellite developments pull tile procurement through contractor networks.
- Commercial:Retail fit-outs and office developments in Sheikh Zayed City specify large-format porcelain with reduced grout lines. Hospitality projects bundle material supply with certified installer supervision.
- Industrial:Manufacturing facilities in Suez Canal Economic Zone demand chemical-resistant unglazed flooring. Heavy machinery load-bearing requirements filter specification toward high-mechanical-strength grades.
- Institutional:Schools, hospitals, and government buildings in the New Administrative City mandate EOS-certified sourcing. Procurement compliance redirects volume from uncertified import channels toward accredited domestic manufacturers.
Volume concentration tracks residential construction cycles. Margin expansion is climbing the fastest in commercial bundling of supply-plus-installation services.
Size:
Format dimensions determine raw material throughput, kiln occupancy efficiency, and shipping economics. Egyptian manufacturers retool production lines around developer preferences for seamless visual surfaces.
- Small Format:Traditional 300x300mm and 400x400mm tiles dominate renovation and repair demand. Existing housing stock in Alexandria and Delta governorates sustains replacement volume through wholesale distribution.
- Large Format:Slabs exceeding 600x1200mm reduce grout lines for hospitality and retail fit-outs. New Cairo commercial developers specify large-format porcelain for seamless lobby and corridor finishes.
- Custom Size:Project-specific dimensions require dedicated cutting and rectification. Bespoke facade cladding for Alexandria coastal resorts drives custom specification through design-build contracts.
- Rectified:Precision-cut edges enable minimal grout joints. High-end residential developments in Sheikh Zayed City specify rectified large-format for premium interior finishes.
Small format sustains replacement and renovation volume. Large format is gaining share fastest in new commercial construction specification.
Distribution Channel:
Channel structure separates project-direct procurement from retail specification. Vertical integration advantages concentrate among manufacturers with captive distribution assets.
- Online Retail:Digital catalogues and sample ordering accelerate specification research for design consultants. Cairo-based architects leverage online platforms for technical documentation access ahead of project bidding.
- Direct Sales:Manufacturer-to-developer relationships dominate megaproject procurement. Ceramica Cleopatra's Upper Egypt retail network captures direct sales volume through embedded specification support.
- Wholesalers:Bulk distribution through 10th of Ramadan and Obour City trading hubs serves contractor and retail tile shop demand. Inventory concentration enables rapid fulfillment for construction timeline pressure.
- Specialty Stores:Design-focused showrooms in New Cairo and Alexandria guide consumer selection through physical sample comparison. Premium porcelain and imported Italian collections concentrate in specialty retail.
Wholesale channels anchor volume throughput for standard grades. Direct sales is expanding most quickly in megaproject bundling of technical support and installation supervision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo dominates Egypt's ceramic tile demand through megaproject concentration in New Administrative City and Sixth of October City corridors. The Egyptian Organization for Standardization and Quality enforces ES compliance mandates that filter procurement toward certified domestic production. Alexandria's coastal resort developments and the Suez Canal Economic Zone industrial clusters anchor secondary demand poles.
Greater Cairo Metropolitan Region
New Administrative City government buildings mandate EOS-certified sourcing, redirecting procurement from uncertified imports toward accredited domestic manufacturers. Sixth of October City and New Cairo satellite developments pull glazed ceramic volume through contractor networks for middle-income housing. Sheikh Zayed City's high-end residential projects specify rectified large-format porcelain for premium interior finishes.
Alexandria and the Northern Coast
Coastal resort hospitality projects bundle material supply with certified installer supervision, concentrating contract value among vertically integrated players. Alexandria's wholesale distribution hubs serve Delta governorate renovation demand through 10th of Ramadan trading connections. The city's design consultant channels drive mosaic specification for bathroom and spa applications.
Suez Canal Economic Zone
The Industrial Development Authority coordinates factory licensing and environmental permitting across this corridor, shaping capital deployment timelines for export-oriented plant investment. Heavy manufacturing facilities demand chemical-resistant unglazed flooring for machinery load-bearing requirements. Port infrastructure enables specialized logistics corridors toward Sub-Saharan African markets.
Upper Egypt Resource Belt
Aswan and Qena governorates control premium kaolin deposit access, concentrating upstream supply leverage among manufacturers with captive raw material extraction. Ceramica Cleopatra leverages vertical integration from extraction to retail distribution across this region. Kiln operations depend on subsidized Egyptian Natural Gas Holding Company supply, with tariff adjustments compressing margin predictability.
Delta and Canal Cities
10th of Ramadan and Obour City industrial corridors host bulk wholesale distribution serving contractor and retail tile shop demand. Existing housing stock in Delta governorates sustains small-format replacement volume. Environmental permitting timelines from the Industrial Development Authority extend capital deployment cycles by 8-14 months across this manufacturing concentration.
Egypt Ceramic Tiles Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across Egypt's ceramic tile market. Domestic manufacturers with captive kilns and raw material extraction face asset-light importers exploiting preferential trade terms under the Egypt-Turkey Free Trade Agreement. Three archetypes dominate: vertically integrated incumbents controlling Upper Egypt kaolin deposits, import-dependent distributors serving mid-tier segments, and specialized exporters targeting Sub-Saharan African corridors. Capacity expansion and installation service bundling represent the dominant competitive moves, with procurement teams consolidating relationships around full-service providers.
Among Egyptian-based integrated manufacturers, Ceramica Cleopatra exemplifies the upstream-controlled archetype through its Upper Egypt retail network and raw material extraction assets. Lecico Egypt occupies a position emphasizing product specialization in sanitary ware adjacent categories. Pharaohs Ceramics Group anchors the export-oriented tier through Sub-Saharan African channel development. These three represent distinct strategic postures within a market where EOS certification compliance and megaproject bundling capabilities increasingly separate contract winners from commodity suppliers.
| Leading Market Players |
|---|
| Ceramica Cleopatra |
| Lecico Egypt |
| Pharaohs Ceramics Group |
| Al-Ezz Ceramics and Porcelain |
| Misr International Ceramic Company |
| Al Amir Ceramics |
| Ceramica Venzia |
| Gloria Ceramics |
| Ceramica Prima |
| Others |
Supply & Pricing Matrix
Captive kaolin extraction in Upper Egypt's Aswan and Qena governorates anchors supply positioning and pricing power for vertically integrated manufacturers, while gas-fired kiln economics tether margin predictability to Egyptian Natural Gas Holding Company tariff policies.
Pricing Analysis
Margin tightening in mid-tier glazed ceramic traces to Turkish import pressure under preferential Egypt-Turkey Free Trade Agreement terms. Three-tier pricing structure across premium porcelain, standard glazed, and economy unglazed levels stratifies by EOS certification grade and after-sales service bundling. Cost-down pressure on standard grades accelerates because developer procurement teams consolidate around full-service providers. Middle-income residential developers in Greater Cairo exhibit highest price sensitivity; New Administrative City government procurement teams prioritize certification compliance over unit cost.
Supply Chain Analysis
Skilled kiln technician scarcity in 10th of Ramadan and Suez Canal Economic Zone manufacturing corridors constrains production scale-up for large-format porcelain firing. Supply concentrates in Egypt, Turkey, and Italy for finished tile flows, with raw material draws from Upper Egypt kaolin deposits and imported feldspar. Single-source vulnerability sits with concentrated kaolin deposit access. Distribution runs through 10th of Ramadan and Obour City wholesale hubs serving contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-body porcelain technology is displacing conventional full-body tile specification across commercial fit-outs, compressing legacy manufacturing cost structures while opening premium positioning for early adopters.
For Market Incumbents: Hedge against Turkish import substitution by deepening captive kaolin extraction in Upper Egypt and accelerating EOS certification investment for New Administrative City government procurement eligibility. Compress firing cost exposure through kiln efficiency programs that offset Egyptian Natural Gas Holding Company tariff volatility.
For New Entrants and Emerging Players: EOS certification requirements in Egypt open a window for accredited domestic production to capture share from uncertified import channels. Target Alexandria coastal resort hospitality projects with bundled installation service offerings. Pursue design-build contract positioning through architect and design consultant relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated regional ceramics groups seeking Upper Egypt raw material access. Long-term viability hinges on megaproject pipeline continuity and energy cost management capabilities. Watch New Administrative City procurement volume as inflection indicator for domestic certification-premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Extraction | Captive Upper Egypt deposit access insulates margin from raw material supply leverage concentration. |
| EOS Certification Investment | Accreditation unlocks New Administrative City government building procurement mandates filtering import competition. |
| Installation Service Bundling | After-sales contracts capture unbundled revenue streams beyond commodity tile sales in hospitality fit-outs. |
| Thin-Body Porcelain Production Line Addition | Reduced raw material inputs and shipping weights absorb margin pressure from Turkish import pricing. |
| Sub-Saharan Export Channel Development | Port Sudan and Mombasa logistics corridors unlock adjacent market access for Egyptian-manufactured tiles. |
Research Methodology
Document review covered customs trade data, Industrial Development Authority factory licensing records, and EOS certification databases, complemented by interviews with ceramics plant managers, developer procurement leads, design consultants, and wholesale distribution channel partners. Primary fieldwork with kiln operations directors and New Administrative City project specification officers informed production constraint and procurement timeline assessments. Secondary validation drew from Egyptian Natural Gas Holding Company tariff disclosures, Suez Canal Economic Zone investment incentive documentation, and competitor facility capacity announcements. Bottom-up tile production estimates triangulated against top-down construction sector material demand forecasts.
Segmented volume and value trajectories emerged from modeling across product type, application vertical, format size, and distribution channel dimensions throughout the forecast period. CAGRs derived from historical production trend extrapolation adjusted for megaproject pipeline visibility and regulatory compliance phase-in schedules. Key inputs included natural gas tariff policy scenarios, Turkish import volume elasticity estimates, and Sub-Saharan African export corridor infrastructure development timelines.
The model assumes a particular technology adoption path; alternative pathways for thin-body porcelain would alter the outlook if firing expertise scarcity persists or design consultant specification preferences shift. Forecasts reflect assumptions regarding megaproject execution continuity, EOS certification enforcement rigor, and energy subsidy policy stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Dielectric Ceramics Market
Ceramics
Ceramic Additives Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Aluminium Nitride Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
China Clay Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Active Calcium Silicate Market
Ceramics
Earthenware Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Global Barium Carbonate Market
Ceramics
North America Barium Carbonate Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Calcined Kaolin Market
Ceramics
Germany Ceramic Tiles Market