
 Carbon-Ceramic Discs Market | 2026-2036
Carbon-Ceramic Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon-Ceramic Discs Market Insights
Multi-source procurement of silicon carbide fiber preforms is expanding as brake system OEMs diversify beyond traditional European suppliers. Brembo S.p.A. leverages its Italian manufacturing base to dominate motorsport and supercar fitments. SGL Carbon anchors industrial carbon fiber supply through backward integration into precursor production. Surface Transforms plc differentiates via its patented carbon-ceramic manufacturing process targeting aerospace qualification.
Carbon-ceramic discs are composite friction components manufactured from silicon carbide-reinforced carbon matrices densified through chemical vapor infiltration or liquid silicon infiltration, delivering density below 2.5 g/cm³ and operating temperatures exceeding 1,350°C for sustained braking performance. Brake discs command the largest product type position due to aftermarket replacement cycles and OEM specification upgrades on performance vehicles. Aerospace application segments are recording the fastest expansion as next-generation aircraft programs specify carbon-ceramic heat shields and braking systems to meet stringent weight and thermal management targets.
Europe's ECHA administers REACH substance restrictions affecting raw material sourcing for carbon-ceramic matrices, while the F-Gas Regulation constrains process gas selections in chemical vapor infiltration. Japan's METI enforces JIS standards on friction materials that govern import eligibility for aftermarket discs. Stakeholders must monitor evolving emissions compliance for manufacturing processes alongside qualification timelines for aerospace material certifications.
Market Dynamics
Silicon carbide fiber preform supply concentration in Germany and Japan is forcing brake system OEMs into multi-source qualification programs, reshaping procurement economics and vendor consolidation patterns across the carbon-ceramic discs value chain.
Growth Catalysts
- EU F-Gas Regulation:Chemical vapor infiltration process gas constraints are accelerating liquid silicon infiltration adoption, expanding qualified supplier pools beyond traditional European equipment manufacturers.
- Motorsport weight targets:FIA technical regulations mandating mass reduction in prototype and GT categories are specifying carbon-ceramic brake systems as standard fitment, creating specification pull-through to road car programs.
- Silicon carbide densification:Next-generation ceramic matrix composites achieving density below 2.3 g/cm³ are extending thermal operating windows, qualifying components for aerospace heat shield applications.
Market Restraints
- Precursor carbon fiber cost volatility:Polyacrylonitrile feedstock exposure to petrochemical pricing swings compresses margin stability for preform manufacturers without backward integration into precursor production.
- Single-source CVI equipment:Chemical vapor infiltration reactor fabrication concentrates among German and French industrial equipment specialists, creating bottleneck risk for capacity expansion timelines.
- REACH substance restrictions:ECHA candidate list additions for specific phenolic resin hardeners are forcing reformulation of carbon matrix precursors, extending qualification cycles for existing aerospace contracts.
Strategic Opportunities
- India automotive qualification:BIS friction material standards revision for passenger vehicles above 200 kW creates first-mover positioning for carbon-ceramic aftermarket disc suppliers establishing local testing partnerships.
- Urban air mobility braking:eVTOL airframe specifications for emergency stopping systems on vertiport approaches are specifying carbon-ceramic heat sinks, opening a greenfield application vertical.
- Japan METI green innovation fund:Subsidies for lightweight automotive component manufacturing are offsetting capital equipment costs for domestic carbon-ceramic disc production lines targeting luxury OEM supply.
Industry Challenges
- Chemical vapor infiltration technician scarcity:Specialized reactor operation and pyrolysis cycle management skills concentrate among aging workforces in Italy and Germany, constraining capacity ramp rates.
- EASA material certification timelines:Aerospace qualification protocols for carbon-ceramic heat shields extend 18-36 months, delaying revenue recognition for next-generation aircraft program wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon-Ceramic Discs Market |
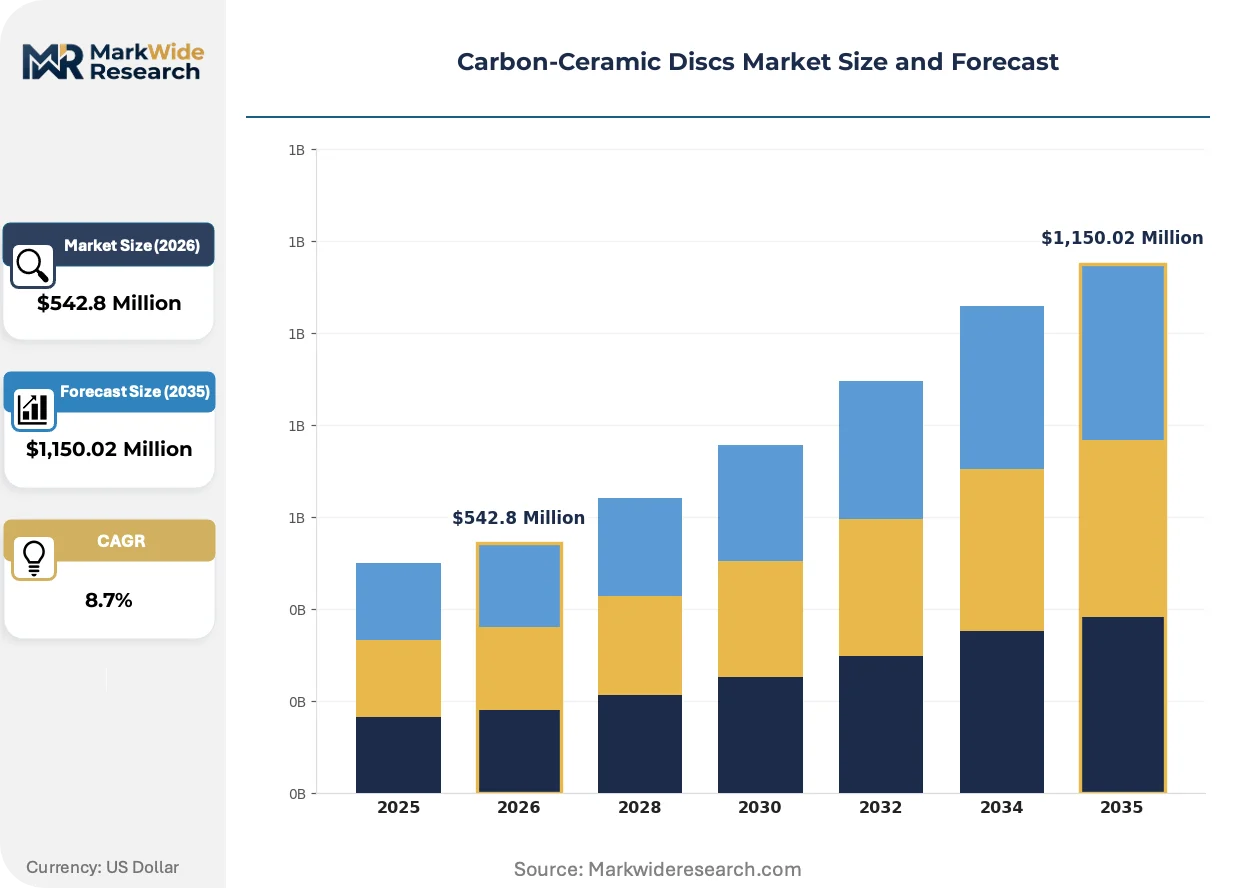
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $1,150.02 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Discs, Clutch Discs, Flywheel Discs, Heat Shields Application: Aerospace, Motorsport, Automotive, Industrial End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors Technology: Manufacturing Process, Material Composition, Surface Treatment, Quality Control |
| Companies Covered | Brembo S.p.A., SGL Carbon, Surface Transforms plc, Akebono Brake Industry Co., Ltd., Fusion Brakes LLC, Rotora Inc., Aisin Corp., MAT Foundry Group Ltd., Carbon Ceramics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon-Ceramic Discs Market Trends and Innovations
Manufacturing process digitization and regulatory compliance automation are compressing development cycles for carbon-ceramic components, while demand-side specification practices are shifting toward performance-based qualification frameworks.
Continuous fiber 3D weaving for silicon carbide preforms is modularizing legacy laminated layup approaches, enabling complex cooling vane geometries in brake discs. Aerospace brake OEMs in France and the United States are adopting these architectures for next-generation landing gear programs. The technology is modularizing supplier tier structures by collapsing separate preform and densification steps into integrated manufacturing cells.
Europe's F-Gas Regulation phase-down schedules for hydrofluorocarbon process gases are constraining chemical vapor infiltration operations in Germany and Italy. Industrial gas suppliers are qualifying fluorine-free alternatives for pyrolysis atmospheres, extending equipment retrofit timelines. Motorsport brake disc production lines in the United Kingdom and Japan are most affected, accelerating liquid silicon infiltration pilot investments.
Performance-based friction material specifications are displacing prescriptive compound recipes in premium automotive procurement. German and Italian OEMs now qualify suppliers against thermal decay curves and wear rate bands rather than mandating specific fiber architectures. This shift concentrates purchasing authority among engineering teams with dyno testing capabilities, marginalizing traditional trading house intermediaries in the aftermarket channel.
Carbon-Ceramic Discs Market Segmentation
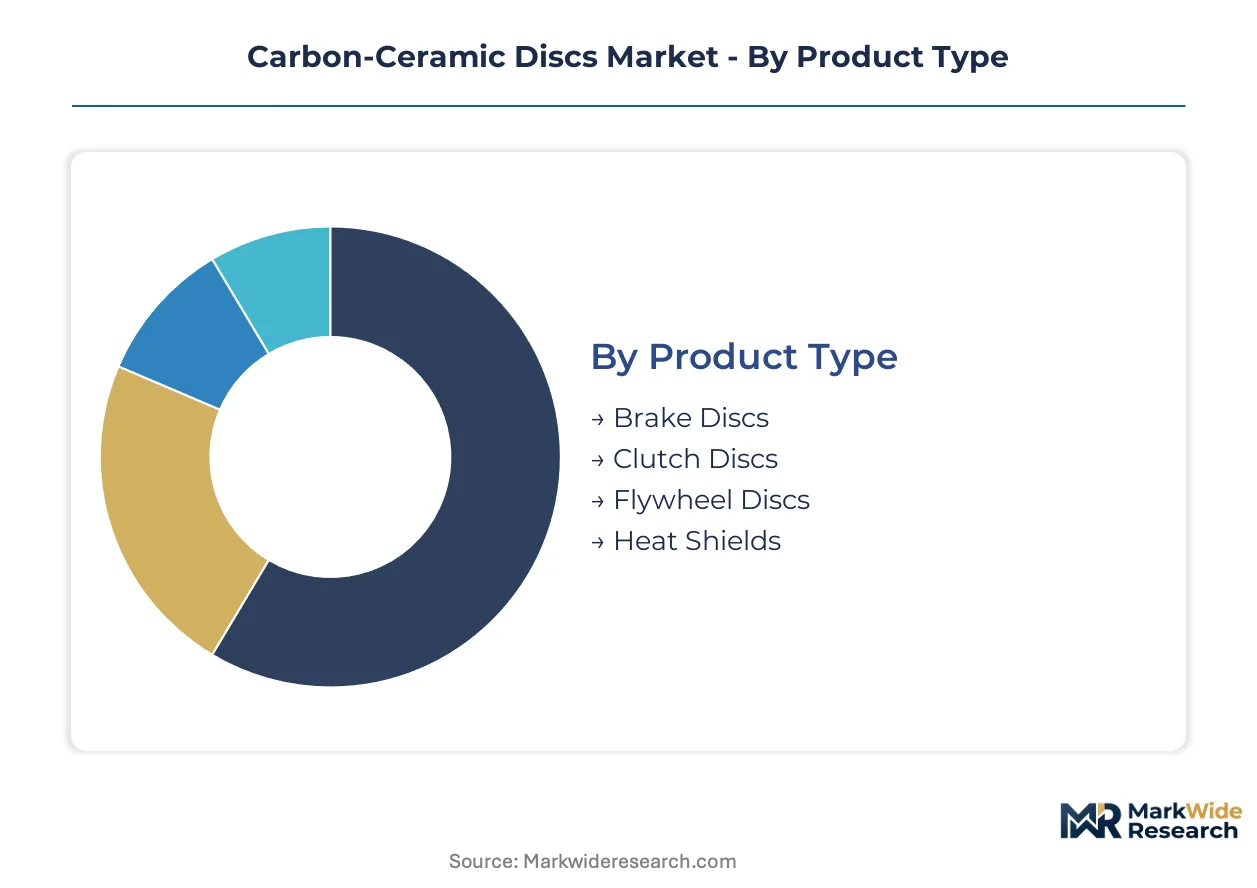
Carbon-ceramic discs serve radically different duty cycles across motorsport heat spikes, aerospace thermal protection, and automotive friction braking. Segmentation clarity separates specification-driven OEM procurement from price-sensitive aftermarket replacement economics.
Product Type:
Standalone brake discs dominate installed base and replacement velocity, while embedded clutch and flywheel systems integrate into broader powertrain architectures with longer qualification horizons.
- Brake Discs:Silicon carbide-reinforced carbon matrices densified through chemical vapor infiltration deliver density below 2.5 g/cm³ and sustained operation above 1,350°C. Demand concentrates in Germany and Italy where motorsport engineering clusters and luxury OEM production lines specify standard fitment for vehicles above 200 kW output.
- Heat Shields:Next-generation ceramic matrix composites achieving density below 2.3 g/cm³ extend thermal operating windows for aerospace re-entry protection. Japan's METI green innovation fund is subsidizing domestic production lines targeting qualification for next-generation aircraft programs.
- Clutch Discs:Friction-layer architectures integrate with dual-clutch transmissions in Italian supercar platforms.
- Flywheel Discs:Kinetic energy storage systems in German industrial test equipment use carbon-ceramic rotors for high-speed stability.
Brake discs lead volumes today; heat shields are gaining share fastest.
Application:
Cost tiers separate aerospace qualification premiums from motorsport specification pull-through and automotive aftermarket price sensitivity.
- Aerospace:EASA material certification protocols for heat shields and braking systems extend 18-36 months, delaying revenue recognition but locking in multi-year program commitments. French and US landing gear OEMs are adopting continuous fiber 3D weaving architectures for next-generation programs.
- Motorsport:FIA technical regulations mandating mass reduction in prototype and GT categories specify carbon-ceramic brake systems as standard fitment, creating specification pull-through to road car programs in Germany and Japan.
- Automotive:India's BIS friction material standards revision for passenger vehicles above 200 kW creates first-mover positioning for aftermarket disc suppliers.
- Industrial:German test rig manufacturers specify carbon-ceramic flywheels for high-cycle fatigue applications.
Aerospace commands the highest unit margins; motorsport provides the steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through engineering-qualified OEM supply agreements or fragmented aftermarket distribution channels.
- OEMs:German and Italian luxury vehicle manufacturers now qualify suppliers against thermal decay curves and wear rate bands rather than mandating specific fiber architectures, concentrating purchasing authority among engineering teams with dyno testing capabilities.
- Tier-1 Suppliers:Brembo S.p.A. leverages its Italian manufacturing base to dominate motorsport and supercar fitments through direct OEM relationships.
- Aftermarket Providers:Performance-based friction material specifications are displacing prescriptive compound recipes, marginalizing traditional trading house intermediaries.
- Distributors:Japanese import eligibility for aftermarket discs falls under METI-enforced JIS standards governing friction materials.
OEMs anchor procurement volumes today; Tier-1 suppliers are climbing the fastest through vertical integration into preform production.
Technology:
Manufacturing maturity separates qualified chemical vapor infiltration capacity from emerging liquid silicon infiltration investments responding to regulatory constraints.
- Manufacturing Process:Europe's F-Gas Regulation phase-down schedules for hydrofluorocarbon process gases are constraining CVI operations in Germany and Italy, accelerating liquid silicon infiltration pilot investments in UK and Japan motorsport lines.
- Material Composition:Silicon carbide fiber preform supply concentration in Germany and Japan is forcing brake system OEMs into multi-source qualification programs, reshaping procurement economics.
- Surface Treatment:Patented finishing processes differentiate aerospace qualification candidates from automotive aftermarket suppliers.
- Quality Control:Non-destructive testing protocols for ceramic matrix porosity govern EASA certification timelines.
Manufacturing process technology locks in supplier tier positions today; material composition innovations are expanding qualified supplier pools fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's motorsport engineering corridor anchors procurement intensity for carbon-ceramic brake systems, with Italian supercar manufacturing and Japanese precision ceramics forming complementary demand poles across the forecast window.
Germany
Luxury OEM production lines in Stuttgart and Munich specify carbon-ceramic discs as standard fitment for vehicles exceeding 200 kW output. The KBA enforces type-approval protocols that govern friction material homologation for road-legal aftermarket discs. Bavaria's chemical vapor infiltration equipment specialists concentrate reactor fabrication capacity, constraining regional expansion timelines.
Italy
Motorsport brake system procurement from Monza and Modena engineering clusters drives specification pull-through to road car programs. The F-Gas Regulation phase-down constrains hydrofluorocarbon process gas availability for pyrolysis operations. Emilia-Romagna's preform manufacturers leverage backward integration into precursor production to stabilize margin exposure.
Japan
METI's green innovation fund subsidizes capital equipment costs for domestic carbon-ceramic disc production lines targeting luxury OEM supply. JIS standards on friction materials govern import eligibility for aftermarket discs. Nagoya-area ceramics specialists qualify silicon carbide fiber preforms for aerospace heat shield applications.
United States
Aerospace landing gear OEMs in Ohio and California adopt continuous fiber 3D weaving architectures for next-generation programs. FAA certification protocols for carbon-ceramic braking systems extend qualification timelines. The Pacific Northwest hosts test rig manufacturers specifying carbon-ceramic flywheels for high-cycle fatigue applications.
United Kingdom
Motorsport brake disc production lines in the Midlands accelerate liquid silicon infiltration pilot investments responding to F-Gas constraints. The Health and Safety Executive administers emissions compliance for manufacturing processes. Surface Transforms plc anchors patented carbon-ceramic manufacturing process development targeting aerospace qualification.
Carbon-Ceramic Discs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aerospace qualification and urban air mobility braking applications outside traditional automotive supply chains. The supplier base concentrates among Italian and German fabricators with captive preform production, while Japanese and UK specialists compete on process technology differentiation. Three archetypes dominate: integrated preform-densification operators, specialty ceramics houses with aerospace pipelines, and trading intermediaries losing share to performance-based procurement. Capacity expansion and strategic partnerships represent the dominant competitive vectors as OEMs consolidate approved vendor lists.
Among Italy-based brake system specialists, Brembo S.p.A. exemplifies the integrated manufacturing archetype through its dominance of motorsport and supercar fitments. SGL Carbon anchors industrial carbon fiber supply through upstream control over precursor production. Surface Transforms plc occupies a position within the specialty tier, representing process-innovation-focused competition for aerospace material certifications. These three entities collectively illustrate the geographic and technological segmentation shaping vendor selection criteria across end-use segments.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| SGL Carbon |
| Surface Transforms plc |
| Akebono Brake Industry Co., Ltd. |
| Fusion Brakes LLC |
| Rotora Inc. |
| Aisin Corp. |
| MAT Foundry Group Ltd. |
| Carbon Ceramics Ltd. |
| Others |
Pricing and Supply Chain Analysis
Liquid silicon infiltration adoption is compressing production costs while fragmenting supplier power across German equipment specialists and Japanese ceramics houses. This process transition simultaneously erodes chemical vapor infiltration premiums and expands qualified vendor pools beyond traditional European fabricators.
Pricing Analysis
Input-cost pass-through from polyacrylonitrile precursor volatility governs margin stability for preform manufacturers without backward integration. Pricing stratifies across aerospace qualification premiums, motorsport specification tiers, and automotive aftermarket economy levels. Cost compression in the aftermarket tier is intensifying because Indian and Chinese suppliers are qualifying against BIS and JIS friction standards. Tier-1 brake system OEMs exhibit lowest price sensitivity; independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and French chemical vapor infiltration reactor fabricators, constraining capacity expansion timelines. Silicon carbide fiber preform supply draws from Germany, Japan, and Italy, with precursor carbon fiber anchored in petrochemical feedstock markets. Regulatory restriction risk concentrates in ECHA REACH substance additions and F-Gas phase-down schedules. Distribution runs through engineering-qualified OEM supply agreements for premium tiers and fragmented aftermarket channels for replacement discs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between METI-subsidized Japanese production lines and F-Gas-constrained European fabricators facing divergent cost trajectories.
For Market Incumbents: Anticipate margin compression from liquid silicon infiltration entrants by securing captive precursor supply through backward integration into polyacrylonitrile production. Defend aerospace qualification positions against emerging ceramics specialists by accelerating EASA certification timelines for heat shield applications. Prioritize capacity expansion in subsidy-eligible geographies to offset European regulatory cost disadvantages. For New Entrants and Emerging Players: Urban air mobility brake system OEMs represent an underserved buyer archetype with greenfield specification windows and limited incumbent relationships. Penetrate this segment through vertiport emergency stopping system partnerships before eVTOL platform consolidation locks in supplier lists. Leverage continuous fiber 3D weaving process differentiation to collapse preform and densification steps into integrated manufacturing cells. For Investors and Strategic Acquirers: Valuations sit cheapest among specialty ceramics houses with aerospace pipelines but pending EASA material certifications. Long-term viability over the projection horizon hinges on successful qualification for next-generation aircraft programs and urban air mobility braking applications. Monitor METI green innovation fund disbursement velocity as an inflection indicator for Japanese domestic capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | SGL Carbon's upstream control over polyacrylonitrile stabilizes margin exposure against petrochemical volatility. |
| Liquid Silicon Infiltration Pilot Investment | UK and Japan motorsport lines accelerate process diversification responding to F-Gas constraints. |
| EASA Material Certification Acceleration | Surface Transforms plc targets aerospace qualification to escape automotive aftermarket price compression. |
| Urban Air Mobility Brake System Partnership | eVTOL vertiport specifications create first-mover positioning outside traditional automotive supply chains. |
| Continuous Fiber 3D Weaving Adoption | French and US landing gear OEMs specify next-generation architectures for thermal management performance. |
Research Methodology
Multiple input streams — procurement director interviews at Tier-1 brake system suppliers, regulatory filings with EASA and METI, and customs trade data for silicon carbide fiber preforms — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at Italian densification facilities, OEM platform engineers in Stuttgart and Munich, and aftermarket distributors under JIS standards. Secondary validation drew from ECHA REACH candidate list updates, F-Gas Regulation phase-down schedules, and aerospace material certification databases.
Historical production capacity trends were cross-referenced against expert panel inputs on liquid silicon infiltration adoption rates. The analytical framework segmented volumes across brake discs, heat shields, clutch discs, and flywheel discs; by aerospace, motorsport, automotive, and industrial applications; and by CVI versus LSI manufacturing processes. CAGRs were derived from regression analysis against luxury vehicle production forecasts and next-generation aircraft program timelines. Forecast inputs included FIA technical regulation weight targets and BIS friction material standard revision schedules.
Underlying measurement precision varies by segment; aerospace qualification premiums and motorsport specification volumes carry tighter precision than emerging urban air mobility estimates. Forecasts reflect assumptions on regulatory phase-down adherence, subsidy program continuity, and certification timeline execution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Liquid Sodium Silicate Market
Ceramics
Ceramic Tiles Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Alumina Slurry Market
Ceramics
Methyl Silicate Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Aragonite Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Transparent Ceramics Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Ball Clay Market
Ceramics
Automotive Ceramics Market
Ceramics
Porous Ceramic Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Strontium Carbonate Market
Ceramics
High Temperature Ceramics Market