
 Spain Ceramic Tiles Market | 2026-2036
Spain Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Ceramic Tiles Market Analytics
Castellón's producer corridor is expanding kiln capacity and digital decoration lines to serve rebounding Mediterranean construction. Porcelanosa dominates Spain's premium residential segment through controlled distribution and in-house design studios. Grespania leverages continuous roller-hearth technology to sustain thin-porcelain output for facade systems. Baldocer anchors mid-market supply across Iberian retail channels with standardized large-format SKUs.
Spain ceramic tiles are fired clay or porcelain slabs, typically measuring 300x300mm to 1200x2400mm, formed by dry pressing and sintered at 1100-1300°C for dimensional stability and wear resistance; they serve as surfacing and cladding materials in buildings requiring moisture durability and aesthetic finish. Porcelain commands the structural margin pool due to low water absorption and mechanical load tolerance in commercial flooring. The residential end-use segment leads volume through renovation cycles in urban centers, while glazed products retain share in interior wall applications where stain resistance and design variety outweigh structural demands.
Spain's Ministry of Transport and Urban Agenda enforces CTE building code provisions that shape tile specification for thermal envelope performance, while BSI-equivalent UNE standards govern slip resistance and frost durability for exterior installations. EU REACH restrictions on heavy metal pigments in ceramic glazes are forcing reformulation of traditional color palettes across Castellón manufacturing bases. Stakeholders must monitor forthcoming EU Ecodesign requirements for construction products, as embodied carbon thresholds will likely requalify kiln energy profiles and raw material sourcing decisions before the decade closes.
Market Dynamics
Castellón's ceramic cluster is driving kiln modernization and digital decoration investment to meet tightening EU Ecodesign thresholds for embodied carbon in construction products.
Growth Catalysts
- CTE thermal envelope mandates:Spain's national building code updates redirect specification toward certified thermal-performance tiles for residential facades and flooring systems.
- Large-format porcelain technology:Continuous roller-hearth kilns enable thin-porcelain slab production for facade cladding applications across Mediterranean commercial construction.
- Andalusia renovation cycles:Urban residential rehabilitation in Seville and Málaga accelerates replacement demand for moisture-durable surfacing materials.
Market Restraints
- Natural gas cost volatility:Kiln firing operations depend on concentrated Iberian gas supply, exposing Castellón producers to input cost swings without fuel-switching infrastructure.
- REACH pigment reformulation:EU heavy metal restrictions in ceramic glazes force color palette simplification, constraining design differentiation for traditional decorative tiles.
- Thin-porcelain technical limits:Large-format slab handling requires specialized cutting equipment and skilled installation labor unavailable across all Spanish construction trades.
Strategic Opportunities
- Facade system integration:Ventilated rainscreen applications for commercial envelopes create specification pathways for certified thermal-performance porcelain in Madrid and Barcelona.
- Digital decoration convergence:Inkjet printing combined with dry-digital glazing enables batch-size-one customization for premium residential renovation projects.
- UNE slip resistance certification:Stricter accessibility standards for public buildings drive demand for R10-R13 rated floor tiles in healthcare and transport infrastructure.
Industry Challenges
- Dry-pressing technician scarcity:Castellón manufacturers face recruitment gaps for kiln control and digital line operation roles as veteran operators retire.
- Ecodesign compliance timelines:EU construction product regulations demand embodied carbon documentation that most Spanish producers lack lifecycle assessment infrastructure to deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Ceramic Tiles Market |
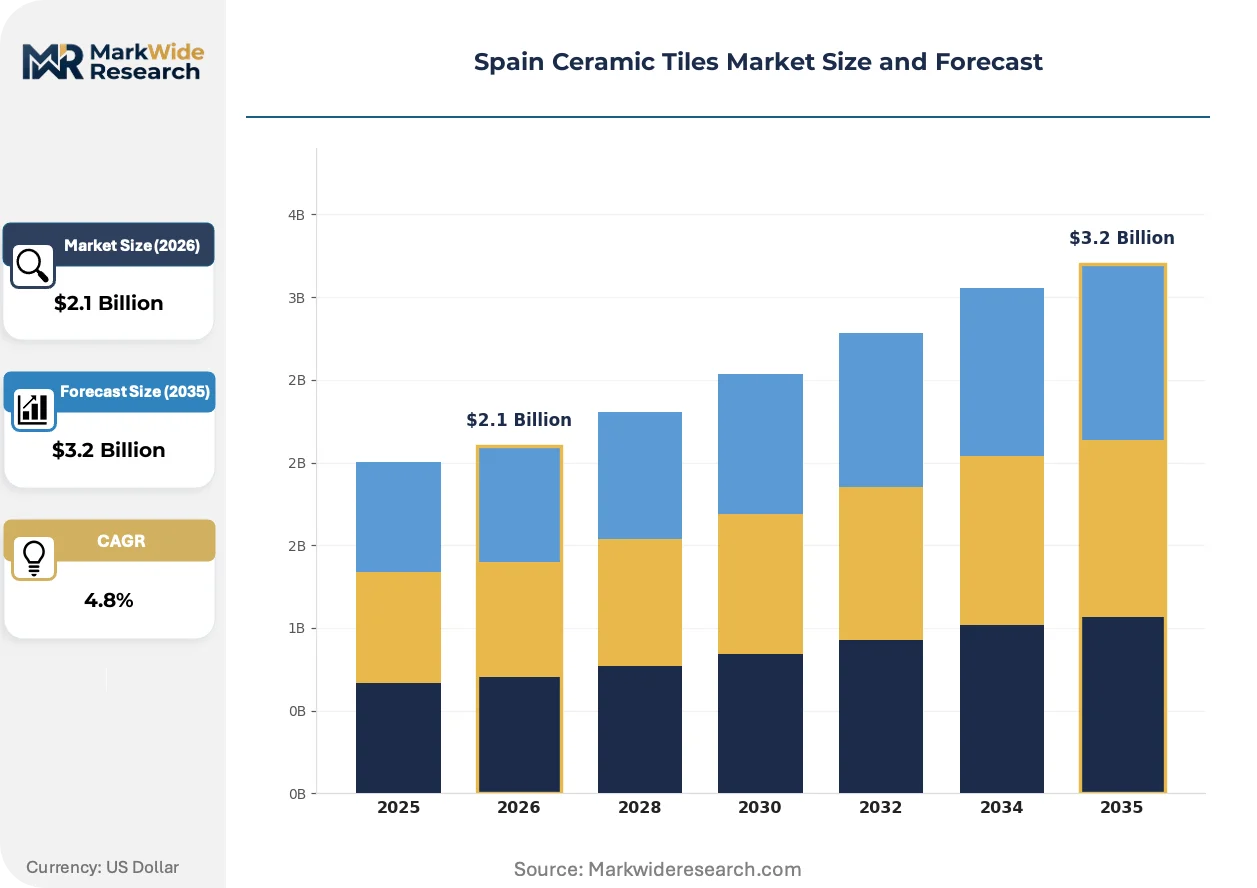
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glazed, Unglazed, Mosaic End Use: Residential, Commercial, Industrial, Institutional Thickness: Thin, Medium, Thick, Extra-Thick Surface Finish: Matte, Glossy, Textured, Polished |
| Companies Covered | Ceramicas Aparici, CEVICA, Roca Tiles, ITG Ceramica, Grespania, Baldocer, Colorker, Realonda, Porcelanosa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Ceramic Tiles Market Evolving Landscape
Digital manufacturing and regulatory carbon accounting are compressing traditional production cycles while opening specification pathways for high-performance porcelain systems.
Continuous inkjet decoration is rewriting the economics of short-run tile production. Residential renovation contractors in Valencia and Catalonia now specify custom-patterned batches without minimum order penalties. This capability is compressing inventory carrying costs for distributors while fragmenting the mid-market SKU landscape.
EU Ecodesign requirements for construction products are mandating lifecycle carbon disclosure across Spanish manufacturing bases. Castellón producers must document kiln energy profiles and raw material transport emissions to retain public project eligibility. Thermal-performance porcelain categories face the steepest compliance burden due to higher firing temperatures.
Architects and interior designers are consolidating specification authority previously held by general contractors. Direct relationships with Castellón design studios now determine tile selection for premium residential and hospitality projects in Madrid. This channel compression is marginalizing traditional wholesale distributors in high-margin segments.
Spain Ceramic Tiles Market Segmentation
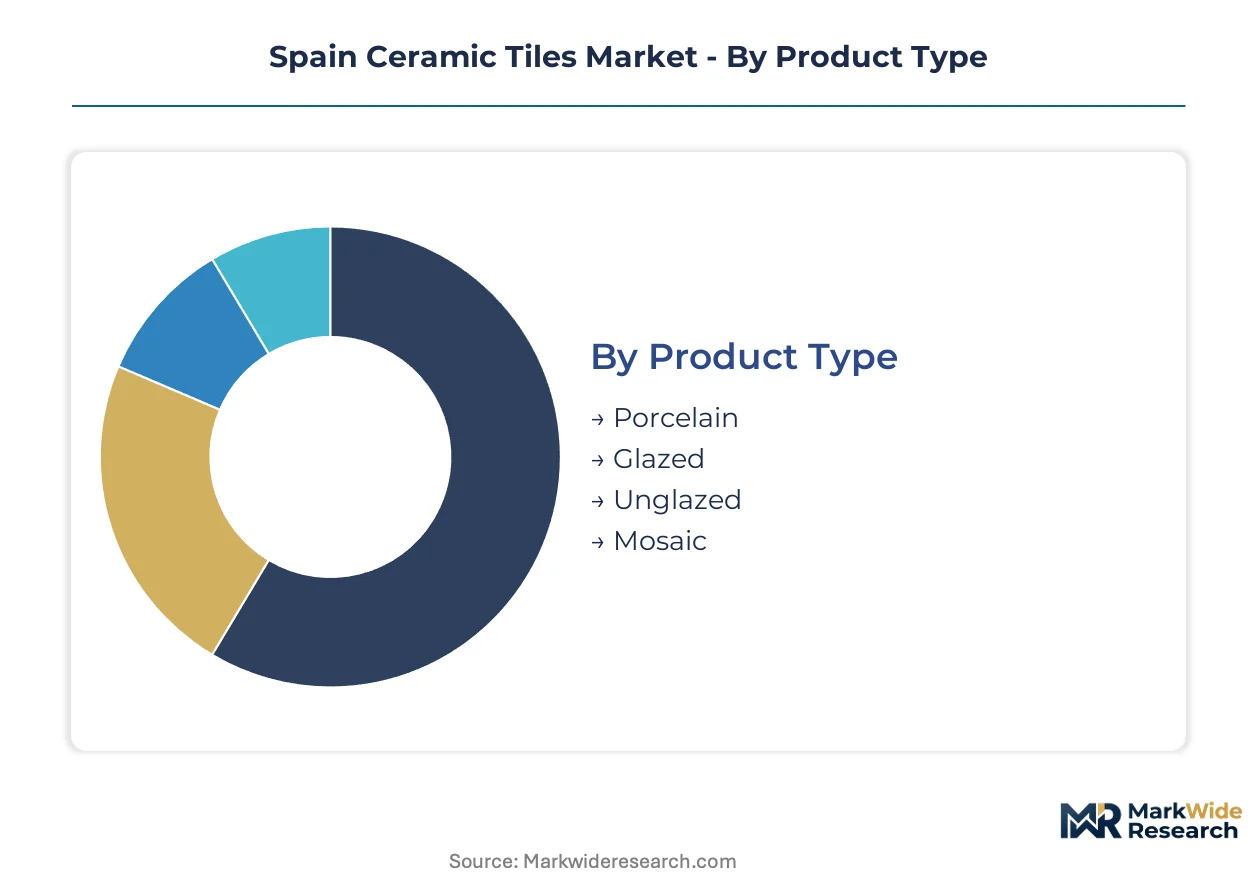
Segmentation reveals how renovation cycles and facade specification are fragmenting demand across technical grades and installation contexts. Understanding these splits exposes where margin pools concentrate versus where volume commoditizes.
Product Type:
Replacement decisions in Andalusia and Catalonia residential rehabilitation are driving specification shifts across technical categories, with performance requirements diverging sharply between structural and decorative applications.
- Porcelain:Dense, low-absorption ceramic fired above 1200°C delivers mechanical load tolerance for commercial flooring and ventilated rainscreen facades. Madrid architects specify certified thermal-performance porcelain for building envelope compliance under updated CTE code provisions.
- Glazed:Clay body coated with glass-forming minerals provides stain resistance and design variety for interior wall applications. Valencia renovation contractors favor inkjet-printed glazed tiles for moisture-durable kitchen and bathroom surfacing where structural demands remain secondary.
- Unglazed:Through-body coloration offers slip resistance and frost durability for exterior installations in Castellón's Mediterranean climate.
- Mosaic:Small-format tesserae assembled on mesh backing serve decorative accent and wet-area flooring in hospitality restoration projects.
Porcelain sits at the top of the volume ranking, with thin-format porcelain climbing the fastest.
End Use:
Customer procurement authority separates premium specification from standardized bulk purchasing across Spain's construction value chain.
- Residential:Urban rehabilitation in Seville and Málaga accelerates replacement demand for moisture-durable surfacing materials, with direct architect relationships displacing traditional wholesale distribution in premium segments.
- Commercial:Ventilated rainscreen applications for Madrid and Barcelona commercial envelopes create specification pathways for certified thermal-performance porcelain requiring embodied carbon documentation under forthcoming EU Ecodesign requirements.
- Industrial:Heavy-traffic flooring in logistics facilities demands abrasion-resistant thick-format products with R10-R13 slip ratings.
- Institutional:Healthcare and transport infrastructure procurement mandates stricter UNE accessibility standards for public building floor surfaces.
Residential commands the largest share, while commercial applications are gaining share fastest.
Thickness:
Handling constraints and installation labor availability shape feasibility for large-format slab deployment across Spanish construction trades.
- Thin:Continuous roller-hearth kiln output enables 3-6mm porcelain slabs for lightweight facade cladding systems.
- Medium:Standard 8-12mm wall and floor tiles dominate Iberian retail channel inventory for residential renovation.
- Thick:15-20mm structural pavers support exterior load-bearing applications in commercial landscaping.
- Extra-Thick:20mm+ porcelain stoneware enables dry-laid outdoor flooring without adhesive bedding.
Medium thickness holds the volume lead, with thin formats expanding most quickly.
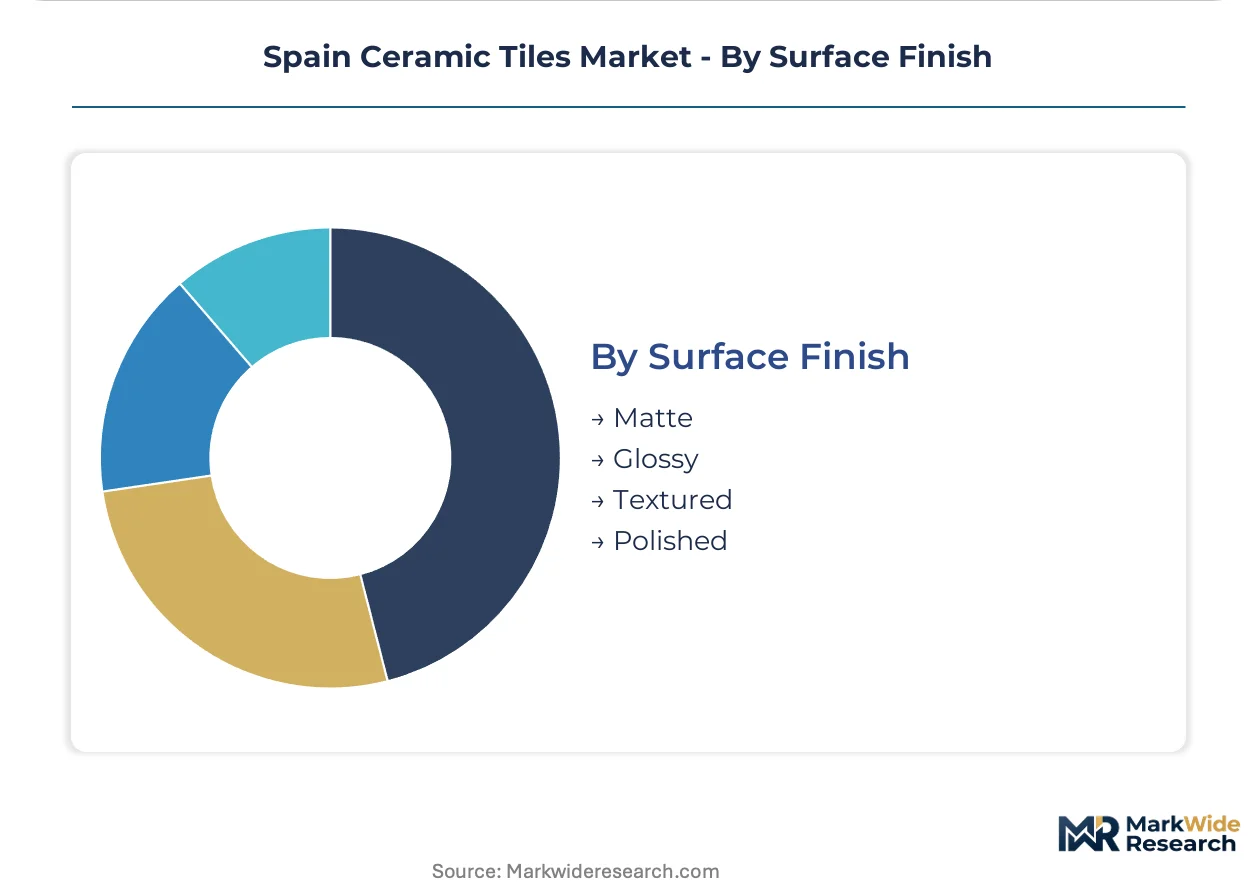
Surface Finish:
Maintenance regimes and aesthetic positioning determine finish selection across residential and commercial specification pathways.
- Matte:Low-reflectance surface treatment reduces glare in healthcare and hospitality interiors while concealing wear patterns.
- Glossy:High-sheen glaze maximizes light reflection for compact residential bathrooms in Barcelona apartment renovations.
- Textured:Slip-resistant surface profiling serves wet-area safety requirements under UNE accessibility standards.
- Polished:Mirror-finish porcelain commands premium positioning for Madrid luxury residential lobbies and retail environments.
Matte finishes lead current volume, with textured surfaces showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as Castellón's cluster absorbs compliance costs that smaller Mediterranean competitors cannot shoulder. Kiln energy profiles and embodied carbon documentation requirements are consolidating output in regions with established technical infrastructure.
Valencia
Castellón's ceramic corridor supplies the majority of domestic output and Mediterranean exports through continuous roller-hearth kiln expansion. Spain's Ministry of Transport and Urban Agenda enforces CTE building code provisions that shape tile specification for thermal envelope performance. Digital decoration lines at Vila-real and Alcora facilities enable batch-size-one customization for premium residential renovation projects.
Catalonia
Barcelona's commercial envelope construction drives specification pathways for certified thermal-performance porcelain in ventilated rainscreen applications. The autonomous community maintains accessibility standards aligned with UNE slip resistance certifications for public building procurement. Sant Vicenç dels Horts and Lleida distribution hubs serve rehabilitation contractors across the northeastern corridor.
Andalusia
Urban residential rehabilitation in Seville and Málaga accelerates replacement demand for moisture-durable surfacing materials. Andalusian building codes incorporate EU Ecodesign thresholds for construction products that requalify material selection in public housing renovation. Almería's logistics infrastructure supports export consolidation for North African markets.
Madrid
The capital's luxury residential and hospitality segments concentrate specification authority through direct architect relationships with Castellón design studios. Madrid's regional government mandates stricter accessibility standards for healthcare and transport infrastructure flooring. Coslada and Alcalá de Henares distribution centers anchor Iberian retail channel supply for standardized large-format SKUs.
Basque Country
Industrial flooring demand from logistics facilities in Bilbao and Vitoria-Gasteiz drives procurement of abrasion-resistant thick-format products with R10-R13 slip ratings. Basque energy efficiency regulations exceed national CTE minimums for building envelope thermal performance. Arrigorriaga manufacturing bases specialize in structural pavers for commercial landscaping applications.
Spain Ceramic Tiles Market Competitive Landscape
Castellón producers anchor the premium tier through controlled distribution and in-house design capabilities; mid-market specialists hold volume positions across Iberian retail channels. The vendor base fragments across three operational scales: integrated design-to-distribution houses, continuous-process manufacturers, and standardized-SKU distributors. Two strategic archetypes dominate: kiln-technology leaders competing on thin-porcelain output capacity, and channel-control players competing on architect specification relationships. Capacity expansion and digital decoration convergence represent the dominant competitive moves as producers prepare for EU Ecodesign compliance timelines.
Within the integrated-design archetype, Porcelanosa and Grespania occupy positions defined by controlled distribution networks and technical ceramic capabilities. Baldocer exemplifies the mid-market standardized-SKU approach across Iberian retail channels. These three Castellón-based entities represent how geographic clustering reinforces competitive positioning through shared technical infrastructure and regulatory compliance expertise.
| Leading Market Players |
|---|
| Ceramicas Aparici |
| CEVICA |
| Roca Tiles |
| ITG Ceramica |
| Grespania |
| Baldocer |
| Colorker |
| Realonda |
| Porcelanosa |
| Others |
Value Network & Pricing Analysis
Captive kiln ownership across Castellón's ceramic corridor anchors both supply security and pricing power for Spanish producers, insulating premium tiers from Iberian gas cost volatility while exposing mid-market players to margin compression.
Pricing Analysis
Distributor markups separate premium porcelain from standardized glazed products across Spanish retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under CTE thermal envelope codes and volume scale of renovation procurement. Cost compression in mid-market glazed tiles is intensifying because REACH pigment reformulation constrains design differentiation. Residential renovation contractors in Andalusia show highest price sensitivity, while Madrid architects specifying ventilated rainscreen facades prioritize thermal-performance certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with concentrated Iberian natural gas supply feeding Castellón's roller-hearth kilns. Manufacturing draws from kaolin deposits in Spain and Portugal, feldspar from Turkey, and digital decoration inks from Italy. Tariff exposure on Italian inkjet equipment threatens short-run customization economics. Distribution runs through Coslada and Alcalá de Henares logistics hubs serving Iberian retail channels, with direct architect relationships bypassing wholesale layers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain ceramic tiles market functions as a stable compounder, with residential renovation cycles in Andalusia and Catalonia generating predictable replacement demand regardless of new construction volatility.
For Market Incumbents: Hedge against REACH compliance cost escalation by accelerating digital decoration line deployment before EU Ecodesign embodied carbon thresholds take effect. Secure backward integration into certified raw material sourcing to defend thermal-performance porcelain margins against reformulation expenses. Prioritize kiln energy efficiency investments that document lifecycle carbon profiles for public project eligibility. For New Entrants and Emerging Players: Architect specification relationships represent the most penetrable channel layer, as direct design studio engagement displaces traditional wholesale distribution in Madrid and Barcelona premium segments. Target thin-porcelain facade system integration for commercial envelope applications where installation labor scarcity constrains incumbent expansion. Pursue UNE slip resistance certification as entry credential for healthcare and transport infrastructure procurement. For Investors and Strategic Acquirers: Roll-up economics work for mid-market standardized-SKU specialists because fragmented Iberian retail channel distribution rewards scale-based procurement leverage. Five-to-ten year viability hinges on Ecodesign compliance infrastructure rather than brand equity alone. Monitor EU construction product regulation implementation timelines as inflection indicator for requalification-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Energy Efficiency Investment | Documents embodied carbon profiles required for CTE thermal envelope compliance and EU Ecodesign eligibility. |
| Digital Decoration Line Expansion | Enables batch-size-one customization for premium residential renovation without minimum order penalties. |
| Backward Integration into Raw Materials | Secures kaolin and feldspar supply chains against transport emission documentation requirements. |
| Direct Architect Relationship Development | Bypasses wholesale distribution compression in Madrid and Barcelona specification-driven segments. |
| UNE Slip Resistance Certification Investment | Unlocks healthcare and transport infrastructure procurement mandating R10-R13 rated floor surfaces. |
Research Methodology
Coverage spans Valencia, Catalonia, Andalusia, Madrid, and Basque Country, with primary inputs from each. The analysis combines interviews with plant managers at Castellón manufacturing facilities, procurement leads at Madrid architectural studios, distribution channel partners across Iberian retail networks, and technical R&D directors overseeing digital decoration lines. Secondary validation draws from Spain's Ministry of Transport and Urban Agenda CTE documentation, EU ECHA REACH regulatory filings, UNE standard certification databases, and customs trade records for Mediterranean ceramic exports. Bottom-up production capacity assessments triangulate against top-down renovation expenditure estimates.
Rate-of-change decomposition separates volume growth from value mix shift across the analysis window. Segmentation dimensions include product type, end-use application, thickness category, and surface finish specification. CAGRs derive from regression analysis against construction permit data and rehabilitation expenditure indices. Industry-specific inputs incorporate kiln energy efficiency trajectories and digital decoration adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Ecodesign implementation timing and Iberian natural gas supply stability. Forecasts reflect documented assumptions regarding CTE code enforcement consistency and REACH pigment reformulation compliance costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Calcined Kaolin Market
Ceramics
Refractory Material Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Engineering Ceramics Market
Ceramics
Titanates Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Advanced Ceramics Market
Ceramics
Kaolin Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Ball Clay Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Zeolite 4A Market
Ceramics
Solid-Ion Conductors Market
Ceramics
White Fused Alumina Market
Ceramics
Global Alumina Market