
 Technical Ceramics Market | 2026-2036
Technical Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Ceramics Market Intelligence
Multi-source procurement for alumina and zirconia precursors is hardening as buyers reduce dependence on single-country supply after recent disruptions. CoorsTek, Inc. leverages captive mining and processing assets across North American sites to secure feedstock continuity. KYOCERA Corporation anchors its position through deep specialization in fine ceramic components for semiconductor fabrication equipment. CeramTec GmbH differentiates via medical-grade bioceramics certified for hip and dental implants across European health systems.
Technical ceramics are inorganic, non-metallic materials fired at temperatures exceeding 1,400°C to achieve dense, crystalline microstructures with hardness values above 1,500 HV and thermal stability beyond 1,600°C. These properties suit load-bearing insulators, cutting tools, and biomedical implants where metals fail. Oxide ceramics dominate volume shipments due to mature alumina and zirconia supply chains serving wear parts and electrical insulation. Nitride ceramics, particularly silicon nitride, represent the fastest-expanding product class as bearing and substrate applications multiply in electric drivetrains and RF electronics. Carbide ceramics concentrate margin pools in ballistic armor and mining tool inserts where ultra-high hardness commands premium pricing.
EPA emissions rules and OSHA silica exposure limits shape kiln operating permits and powder handling protocols at U.S. manufacturing plants. REACH registration requirements and the EU MDR biocompatibility framework govern material compositions and implant traceability for European medical ceramic suppliers. The FDA's 510(k) pathway and ISO 13356 standards for surgical-grade zirconia create dual compliance thresholds for market access. Stakeholders must track evolving carbon border adjustments and raw material export licensing in producer nations to anticipate cost shifts and supply reallocations.
Market Dynamics
Aerospace engine manufacturers are accelerating ceramic matrix composite adoption for turbine hot-section components, compressing qualification cycles and rewiring supplier qualification criteria across the supply base.
Growth Catalysts
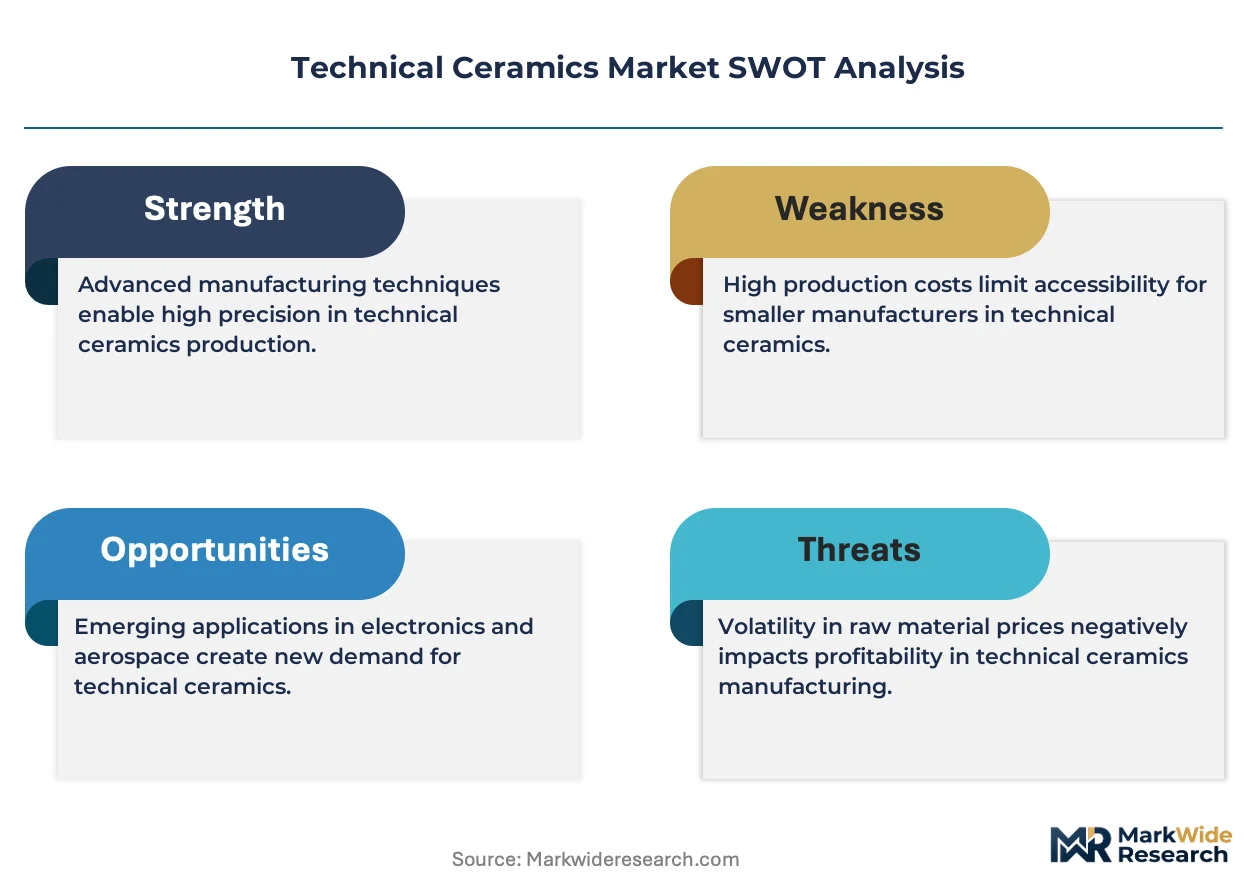
- EU F-Gas Regulation:Tightening emissions benchmarks for high-temperature industrial processes are forcing furnace operators toward silicon nitride burners and alumina kiln furniture, displacing refractory metals in Germany's precision ceramics clusters.
- Electric drivetrain bearing demand:Silicon nitride rolling elements are penetrating EV motor and inverter thermal management systems as automakers chase efficiency gains and extended service intervals.
- Semiconductor equipment buildout:Advanced node fabrication expansion in Taiwan and South Korea is pulling vacuum chamber components, electrostatic chucks, and wafer handling arms from technical ceramics suppliers.
Market Restraints
- Alumina precursor concentration:Bauxite refining and calcined alumina supply chains concentrate in China's Guizhou and Henan provinces, exposing processors to export licensing volatility and carbon border adjustment exposure.
- Sintering energy intensity:Continuous firing above 1,600°C consumes natural gas volumes that clash with EU Green Deal decarbonization timelines and EPA greenhouse gas reporting thresholds for major facilities.
- Silicon carbide substitution in armor:Boron carbide and composite ceramic-metal systems are capturing share in next-generation personnel protection systems, pressuring legacy SiC plate margins.
Strategic Opportunities
- India medical implant localization:CDSCO's phased manufacturing program and hospital procurement localization mandates are opening channels for zirconia and hydroxyapatite bioceramics in joint replacement and dental restoration markets.
- RF substrate convergence:Gallium nitride-on-silicon-carbide and aluminum nitride thermal spreaders are merging in 5G base station and radar module designs, creating specification overlap opportunities for nitride ceramics specialists.
- Japan METI carbon neutrality roadmap:Subsidized kiln electrification and hydrogen-fired sintering pilot programs are lowering clean production transition costs for oxide ceramics manufacturers serving automotive and electronics verticals.
Industry Challenges
- ISO 13356 and EU MDR dual certification:Surgical-grade zirconia implant manufacturers face 18-24 month validation timelines and notified body bottlenecks that delay European market entry and tie up R&D capital.
- Powder metallurgy talent scarcity:Formulation chemists and spray-dry process engineers with sub-micron particle size distribution expertise command premium compensation and limited geographic mobility, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Ceramics Market |
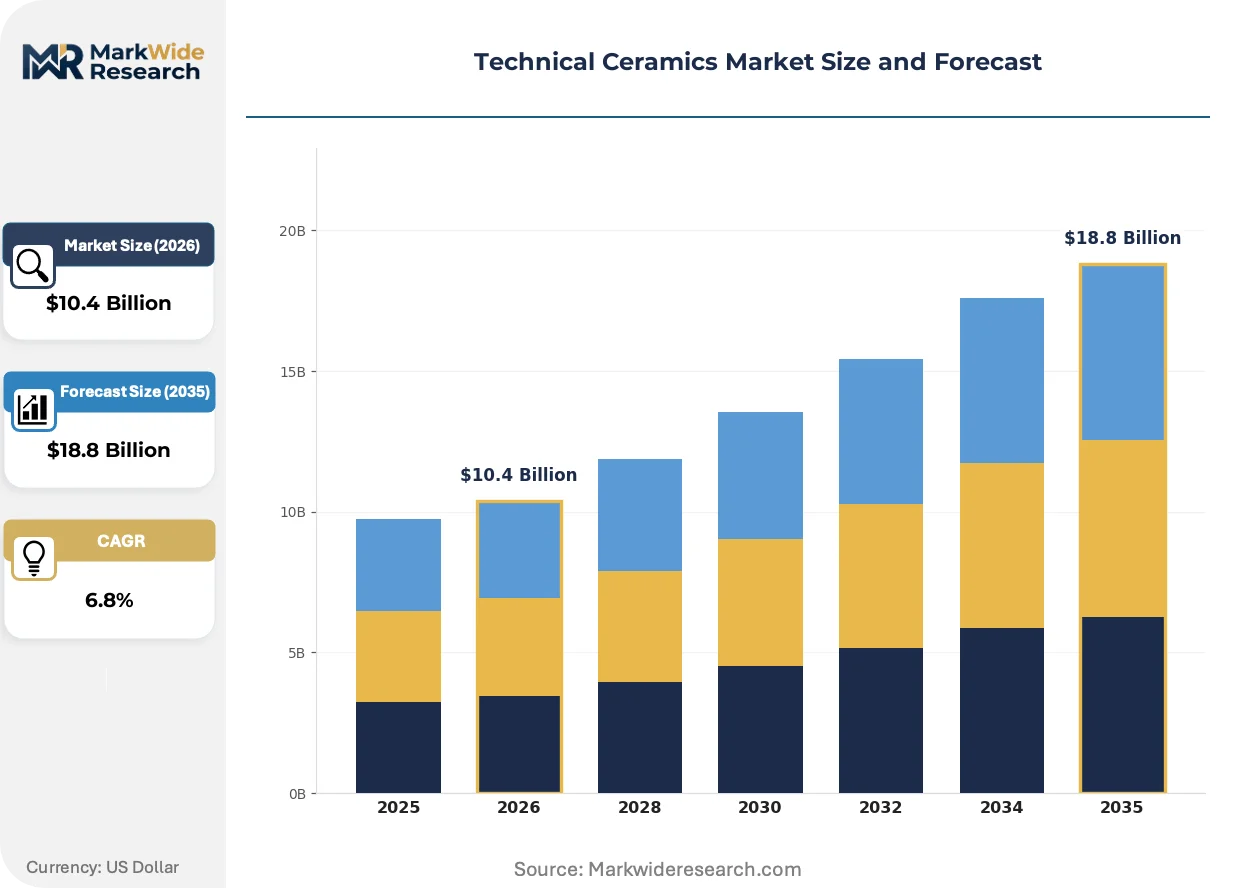
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxides, Nitrides, Carbides, Composites End Use Industry: Aerospace, Electronics, Medical Devices, Automotive Form: Sheets, Powders, Coatings, Components Application: Insulation, Structural Parts, Wear Parts, Engine Components |
| Companies Covered | Morgan Advanced Materials, NGK Insulators, CoorsTek, Inc., Rauschert GmbH, Saint-Gobain Ceramic Materials, KYOCERA Corporation, 3M Advanced Materials, AGC Ceramics Co., Ltd., CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Ceramics Market Strategic Shifts & Innovations
Additive manufacturing of technical ceramics is collapsing prototyping cycles and enabling topology-optimized heat exchangers that conventional pressing cannot produce. This shift is rewiring customer qualification protocols and supplier capability investments.
Silicon nitride bearing and substrate applications are expanding into electric drivetrains and RF electronics as automakers and telecom equipment makers chase thermal stability under mechanical load. Tier-1 suppliers in Germany and Japan are qualifying these materials for 800V inverter modules and millimeter-wave base stations. This expansion is compressing the traditional oxide ceramics dominance in volume applications and forcing raw material processors to secure high-purity silicon metal sources.
EPA emissions rules and OSHA silica exposure limits are reshaping kiln operating permits and powder handling protocols at U.S. manufacturing plants. Facilities in Ohio and Tennessee are retrofitting baghouse systems and automated powder transfer to avoid respiratory protection program citations and Title V permit modifications. The oxide ceramics segment bears the heaviest compliance burden due to alumina and zirconia powder volumes handled.
Buyer concentration among semiconductor equipment OEMs is consolidating procurement leverage and compressing supplier margins on standard alumina components. Long-term supply agreements now bundle volume commitments with joint development obligations for next-generation chamber materials. This pattern is most pronounced in California's Bay Area equipment cluster and Hsinchu's Science Park supplier ecosystem.
Technical Ceramics Market Segmentation
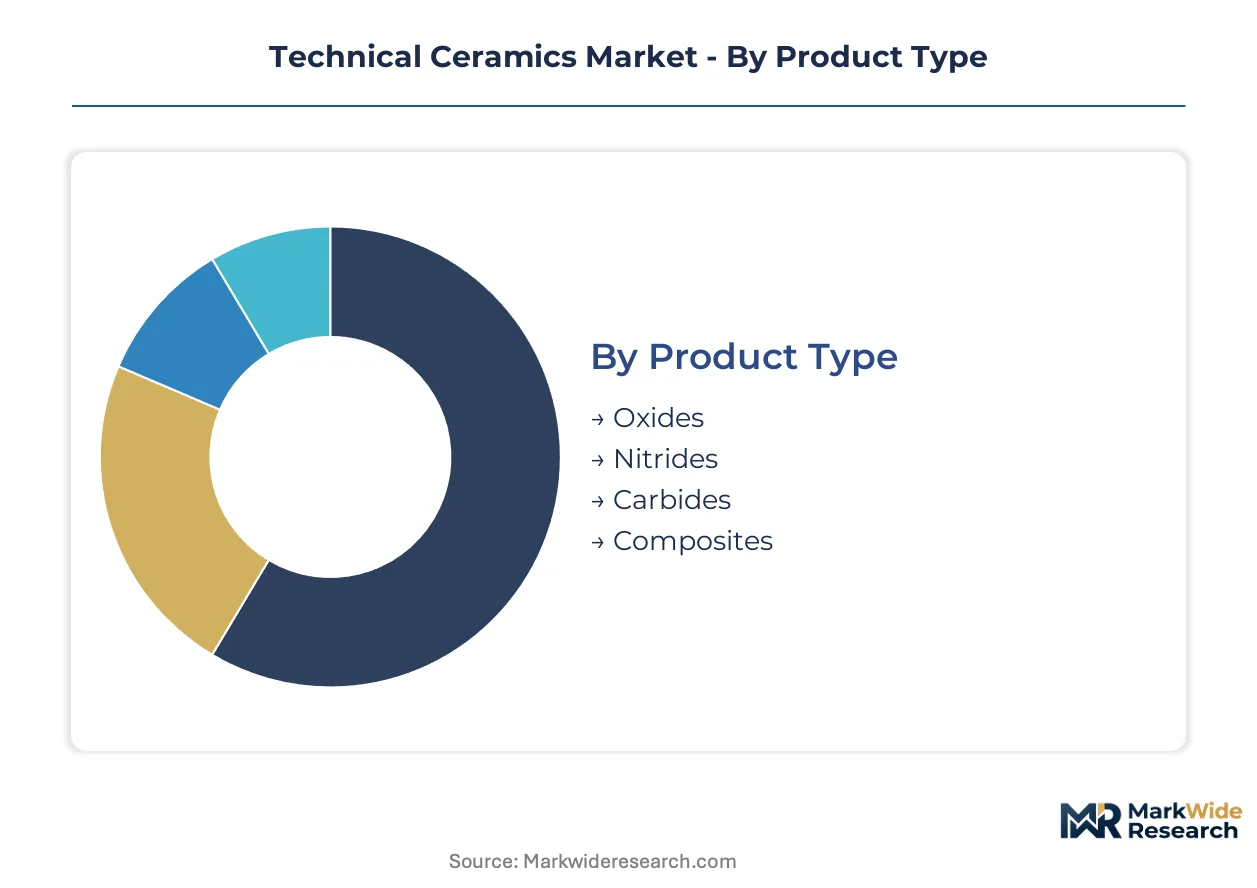
Technical ceramics buyers select materials based on thermal-mechanical performance thresholds rather than price elasticity, making product-type specification the primary segmentation axis. Form factor and application requirements then cascade through procurement decisions across aerospace, electronics, and medical verticals.
Product Type:
Material selection hinges on operating temperature, hardness requirements, and chemical stability in the end-use environment.
- Oxides:Alumina and zirconia formulations dominate volume shipments through mature supply chains serving electrical insulation and wear-resistant components. German precision ceramics clusters around Stuttgart source these materials for semiconductor equipment and medical implant manufacturers seeking proven biocompatibility certification pathways.
- Nitrides:Silicon nitride delivers the highest strength-to-weight ratio among monolithic ceramics, with bearing and substrate applications multiplying in 800V electric drivetrains and RF electronics. Taiwan and South Korean semiconductor equipment buildouts are pulling aluminum nitride thermal spreaders for gallium nitride power modules.
- Carbides:Silicon carbide and boron carbide concentrate in ballistic armor and mining tool inserts where ultra-high hardness commands specification-driven procurement.
- Composites:Ceramic matrix composites enable turbine hot-section components that monolithic ceramics cannot survive, with aerospace engine manufacturers compressing qualification cycles for CMC adoption.
Oxides lead on scale; nitrides lead on momentum.
End Use Industry:
Customer concentration varies sharply by vertical, with semiconductor equipment OEMs wielding consolidated procurement leverage against fragmented supplier bases.
- Aerospace:Engine manufacturers specify ceramic matrix composites for turbine blades and combustor liners, rewiring supplier qualification criteria across the hot-section supply base. FAA airworthiness certification timelines and EPA emissions rules shape material adoption roadmaps.
- Electronics:Advanced node fabrication expansion in Taiwan and South Korea drives vacuum chamber components, electrostatic chucks, and wafer handling arms from technical ceramics suppliers. REACH registration requirements govern material compositions for European equipment exports.
- Medical Devices:Surgical-grade zirconia and hydroxyapatite bioceramics serve hip and dental implant markets under FDA 510(k) and EU MDR dual compliance frameworks.
- Automotive:Silicon nitride rolling elements penetrate EV motor and inverter thermal management systems as automakers chase efficiency gains and extended service intervals.
Electronics commands procurement volume concentration; aerospace exhibits the steepest specification upgrade trajectory.
Form:
Processing method determines achievable geometries and surface finish, with additive manufacturing disrupting traditional forming constraints.
- Sheets:Thin ceramic substrates serve as thermal spreaders and electrical insulators in power electronics packaging, with thickness tolerances tightening for RF applications.
- Powders:Spray-dried granules with sub-micron particle size distribution feed pressing and additive manufacturing lines, with powder metallurgy talent scarcity constraining capacity expansion.
- Coatings:Thermal barrier and wear-resistant layers extend component life in turbine and cutting tool applications where bulk ceramic replacement is uneconomical.
- Components:Net-shape formed parts including bearings, seals, and biomedical implants capture the highest value per kilogram, with topology-optimized heat exchangers emerging from additive manufacturing qualification.
Components dominate value capture; powders anchor upstream supply security.
Application:
Functional requirement dictates material family selection, with thermal and mechanical load profiles narrowing the viable specification set.
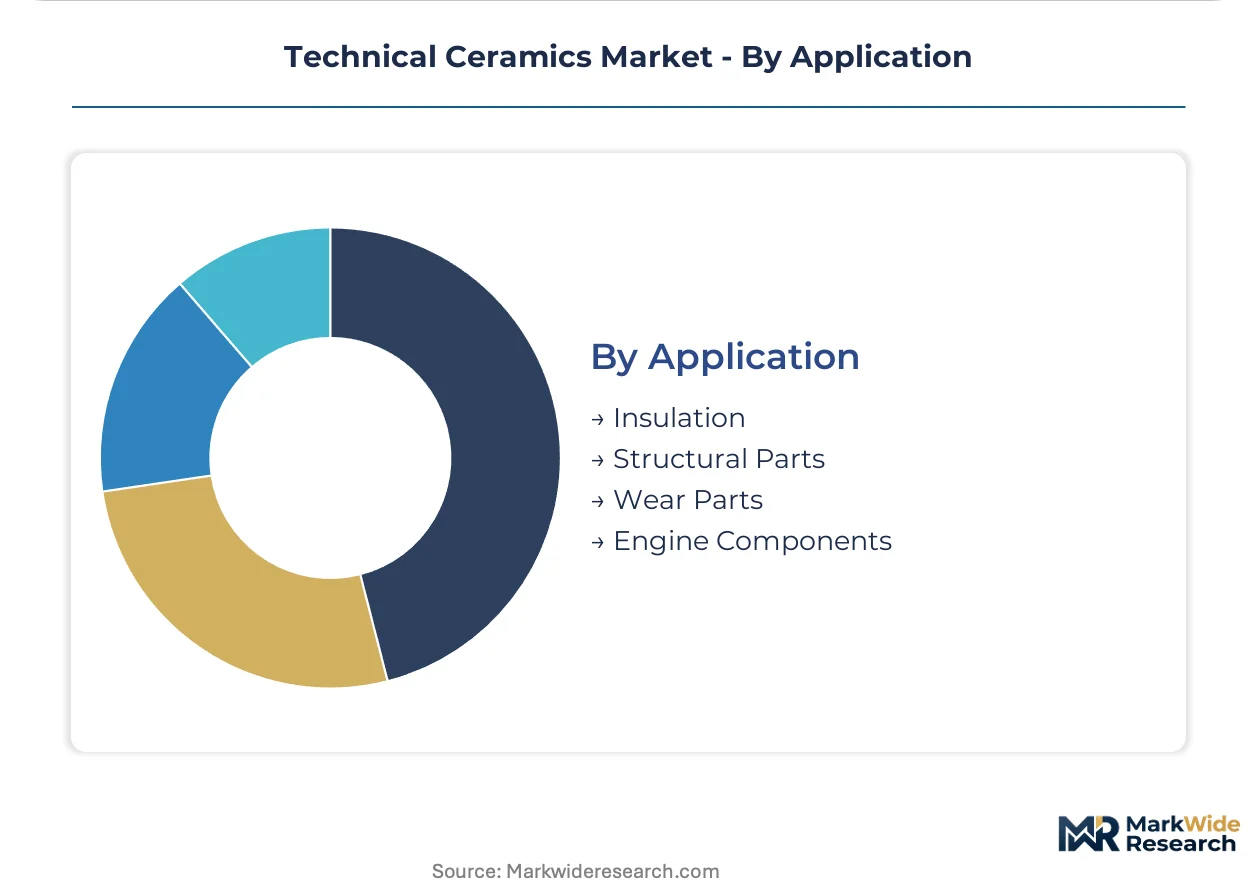
- Insulation:Alumina and porous ceramics manage heat flux in furnace linings and electrical equipment, with EU F-Gas Regulation tightening emissions benchmarks for high-temperature industrial processes.
- Structural Parts:Load-bearing components in semiconductor equipment and aerospace assemblies require dimensional stability across thermal cycling ranges.
- Wear Parts:Cutting tools, seals, and bearings exploit hardness values exceeding 1,500 HV to extend service intervals in abrasive environments.
- Engine Components:Turbine blades, combustor liners, and exhaust nozzles in aerospace propulsion systems push material limits above 1,600°C operating temperatures.
Wear parts sustain volume throughput; engine components drive technology premium extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns reflect divergent compliance costs across jurisdictions, with kiln electrification subsidies in some markets pulling capacity away from regions facing steeper carbon border adjustment exposure. The regulatory-arbitrage dynamic intensifies as EU Green Deal timelines compress against EPA greenhouse gas reporting thresholds.
United States
Semiconductor equipment OEMs in California's Bay Area cluster consolidate procurement leverage for vacuum chamber components and electrostatic chucks. EPA emissions rules and OSHA silica exposure limits reshape kiln operating permits at Ohio and Tennessee manufacturing plants. Facilities in these states retrofit baghouse systems and automated powder transfer to avoid Title V permit modifications.
Germany
Precision ceramics clusters around Stuttgart and Dresden supply medical implant and semiconductor equipment makers with alumina and zirconia formulations. EU F-Gas Regulation tightening emissions benchmarks forces furnace operators toward silicon nitride burners and alumina kiln furniture. The Stuttgart cluster anchors bioceramic certification pathways for European health systems under EU MDR frameworks.
China
Bauxite refining and calcined alumina supply chains concentrate in Guizhou and Henan provinces, exposing processors to export licensing volatility. Domestic semiconductor fabrication expansion pulls demand for vacuum chamber components and wafer handling arms. Yangtze River Delta industrial zones host sintering operations serving electronics and automotive verticals under tightening dual carbon goals.
Japan
Silicon nitride bearing and substrate applications multiply in 800V electric drivetrains and millimeter-wave base stations. METI carbon neutrality roadmap subsidizes kiln electrification and hydrogen-fired sintering pilot programs. Kanto and Kansai industrial corridors host oxide ceramics manufacturers serving automotive and electronics supply chains.
India
CDSCO phased manufacturing program and hospital procurement localization mandates open channels for zirconia and hydroxyapatite bioceramics in joint replacement markets. Gujarat and Maharashtra industrial zones attract medical ceramic fabrication investments. Domestic precision ceramics capacity expands to serve implant demand previously met through European imports.
Technical Ceramics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing qualification and clean production transitions. The vendor base spans captive mining operations, fine ceramic specialists, and medical-grade bioceramic certifiers. Three archetypes dominate: upstream-integrated material processors, application-specific component fabricators, and regulatory-certified implant suppliers. Competitive moves concentrate on backward integration into precursor supply and joint development obligations with semiconductor equipment OEMs.
Among North American upstream-integrated players, CoorsTek, Inc. exemplifies captive mining and processing strategies across multiple sites. KYOCERA Corporation and CeramTec GmbH occupy distinct specialization positions, with the former anchoring fine ceramic component supply and the latter representing medical-grade bioceramic certification pathways. These three entities illustrate the geographic and functional segmentation binding competitive positioning to regulatory access and raw material security.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| NGK Insulators |
| CoorsTek, Inc. |
| Rauschert GmbH |
| Saint-Gobain Ceramic Materials |
| KYOCERA Corporation |
| 3M Advanced Materials |
| AGC Ceramics Co., Ltd. |
| CeramTec GmbH |
| Others |
Cost & Logistics Intelligence
Calcined alumina spot indices in China's Guizhou and Henan provinces cascade through three pricing tiers that separate medical-grade zirconia implants from standard electrical insulators and economy wear parts, with EU carbon border adjustments now compressing margins on China-sourced feedstock.
Pricing Analysis
Input-cost pass-through from bauxite refining and high-purity silicon metal purchases shapes contract structures across the value chain. Pricing stratifies across premium, standard, and economy tiers based on ISO 13356 certification grade and volume scale. Cost compression in standard alumina components is intensifying because semiconductor equipment OEMs bundle volume commitments with joint development obligations. Hospital procurement committees exhibit lowest price sensitivity for surgical-grade bioceramics, while automotive Tier 1 suppliers drive hardest bargaining on silicon nitride bearing lots.
Supply Chain Analysis
Single-source vulnerability sits with China's Guizhou and Henan provinces for calcined alumina, and with Norway and China's Yunnan province for high-purity silicon metal feedstocks. Downstream fabrication draws from Germany's Stuttgart precision ceramics cluster, Japan's Kanto corridor, and Tennessee's sintering operations. Export licensing volatility from China's Ministry of Commerce creates persistent supply chain risk. Distribution runs through long-term offtake agreements with semiconductor equipment OEMs and medical device contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The technical ceramics market functions as a stable compounder anchored by irreplaceable material performance in turbine hot-section and implant applications where metals fail.
For Market Incumbents: Cement captive supply of Guizhou-sourced calcined alumina through backward integration or equity partnerships with bauxite refiners. Expand silicon nitride capacity in Germany's precision ceramics cluster to capture EV drivetrain bearing demand before qualification windows close. Boron carbide substitution in next-generation armor systems threatens legacy silicon carbide plate margins. For New Entrants and Emerging Players: Additive manufacturing qualification for topology-optimized heat exchangers offers a technology-first wedge into aerospace thermal management procurement. Target India's CDSCO-registered implant channel for zirconia and hydroxyapatite bioceramics, where hospital procurement localization mandates displace European imports. Pursue joint development obligations with Taiwan semiconductor equipment OEMs as the fastest qualification pathway. For Investors and Strategic Acquirers: Asymmetric upside sits with medical-grade bioceramic certifiers holding EU MDR and FDA 510(k) dual pathways. The five-to-ten-year viability thesis rests on implant demand demographics and aerospace engine refresh cycles. Monitor Japan METI hydrogen-fired sintering pilot outcomes as the inflection signal for clean production cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Secures calcined alumina continuity against China's export licensing volatility. |
| EU MDR Certification Investment | Unlocks European hospital procurement for surgical-grade zirconia implant suppliers. |
| Silicon Nitride Capacity Expansion | Captures EV drivetrain bearing specifications from Germany's automotive OEMs. |
| Additive Manufacturing Qualification | Enables topology-optimized geometries for aerospace heat exchanger contracts. |
| Joint Development with Semiconductor OEMs | Bundles volume commitments with next-generation chamber material R&D obligations. |
Research Approach
Direct dialogue with plant managers at German precision ceramics clusters, procurement leads at Taiwan semiconductor equipment OEMs, biomedical engineers at European hospital systems, and sintering operations directors in Tennessee and Ohio anchored qualitative findings. Secondary validation drew from SEC 10-K filings, ECHA REACH registration databases, FDA 510(k) clearance records, and Japan METI technology roadmaps. Bottom-up and top-down triangulation cross-checked capacity estimates against end-use demand models.
Bottom-up modeling aggregated product-type shipments across oxide, nitride, carbide, and composite categories, while top-down analysis calibrated against aerospace engine build rates and semiconductor equipment capex cycles. Segmentation dimensions included material family, end-use industry, form factor, and geographic production hub. CAGRs derived from slope-log regression on historical shipment values adjusted for feedstock price normalization. Forecast inputs incorporated EU Green Deal decarbonization timelines and EPA Title V permit modification rates.
The model holds under stable regulatory enforcement and continuous sintering energy supply; deviation in carbon border adjustment rates or export licensing moratoria would shift capacity migration patterns and pricing trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Pigments Market
Ceramics
US Kaolin Market
Ceramics
Kaolin Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Alumina Slurry Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Zeolite 4A Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Glass Ceramics Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Ceramic Proppant Market
Ceramics
Global Ceramic Coating Market
Ceramics
Ceramic Frit Market
Ceramics
Calcined Bauxite Market
Ceramics
Quartz Powder Market