
 Hot-Pressed Aluminum Titanate Ceramics Market | 2026-2036
Hot-Pressed Aluminum Titanate Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Hot-Pressed Aluminum Titanate Ceramics Market Analytics
Advanced hot-pressing automation is reshaping how aluminum titanate components achieve dimensional precision at scale. CoorsTek leverages deep vertical integration across powder synthesis to finished shaping, sustaining cost advantages in thermal barrier applications. CeramTec GmbH anchors European supply networks for catalytic converter substrates, while KYOCERA Corporation dominates Asian electronics-grade production through in-house sintering expertise.
Hot-pressed aluminum titanate ceramics are engineered oxide composites synthesized from aluminum oxide and titanium dioxide precursors, densified under simultaneous heat and uniaxial pressure exceeding 20 MPa to achieve near-theoretical density with controlled microcrack networks that deliver exceptional thermal shock resistance above 1000°C. These materials serve primarily as thermally stable structural components in environments demanding rapid temperature cycling tolerance. Tiles and plates occupy mature volume positions in refractory linings, while shapes command premium positioning in aerospace thermal protection systems where geometric complexity drives margin pools. Energy sector demand for catalytic converter substrates is accelerating fastest among end users, reflecting exhaust aftertreatment upgrades across automotive OEM supply chains.
EPA tailpipe emissions enforcement and the EU F-Gas Regulation directly shape product specifications by mandating higher thermal efficiency in exhaust components, while REACH compliance governs precursor chemical sourcing across European manufacturing. Japan's METI energy efficiency standards and JIS ceramic certification frameworks create structured market access thresholds for imported components. Stakeholders must monitor evolving cross-border carbon border adjustment mechanisms and their downstream effects on energy-intensive hot-pressing operations.
Market Dynamics
Automotive OEM thermal management specifications are compressing development cycles for hot-pressed aluminum titanate substrates, forcing manufacturers to synchronize sintering automation upgrades with EPA Tier 3 and Euro 7 compliance deadlines.
Growth Catalysts
- EPA tailpipe enforcement:Mandates for higher thermal efficiency in exhaust aftertreatment systems are pulling aluminum titanate into catalytic converter substrate stacks.
- Japan METI energy efficiency standards:JIS ceramic certification thresholds create structured procurement pipelines for precision thermal barrier components.
- Hot-pressing automation:Uniaxial pressure control systems exceeding 20 MPa now achieve near-theoretical density at production scales previously limited to laboratory batches.
Market Restraints
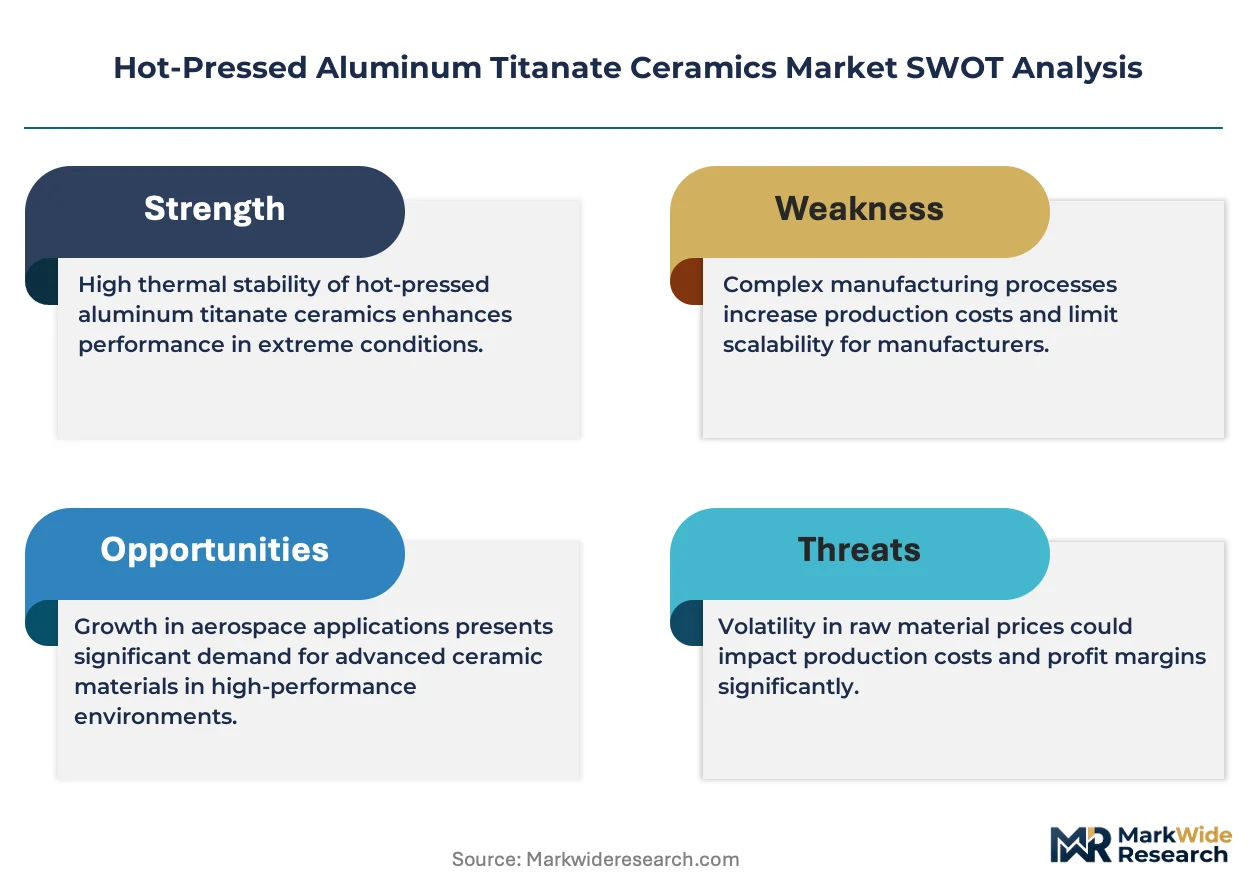
- Precursor cost volatility:High-purity titanium dioxide and aluminum oxide feedstock prices fluctuate with pigment and electronics demand cycles.
- Supply concentration risk:Precision powder synthesis capability clusters in Germany and Japan, creating single-source dependencies for automotive Tier 1 suppliers.
- Microcrack control limitation:Thermal shock resistance above 1000°C requires engineered crack networks that complicate geometric complexity in thin-walled shapes.
Strategic Opportunities
- Aerospace thermal protection:Geometrically complex shapes for re-entry vehicle heat shields command premium positioning outside automotive commodity cycles.
- EU F-Gas Regulation phase-down:Refrigeration and HVAC heat exchanger applications open as fluorinated gas restrictions intensify material substitution pressures.
- Direct OEM contracting:Bypassing traditional refractory distribution channels through captive supply agreements with exhaust system integrators.
Industry Challenges
- Hot-press operator skill scarcity:Simultaneous temperature-pressure profiling expertise sits with aging workforces in Nagoya and Düsseldorf manufacturing clusters.
- REACH compliance timeline:Precursor chemical registration and downstream user notification obligations extend European market access cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot-Pressed Aluminum Titanate Ceramics Market |
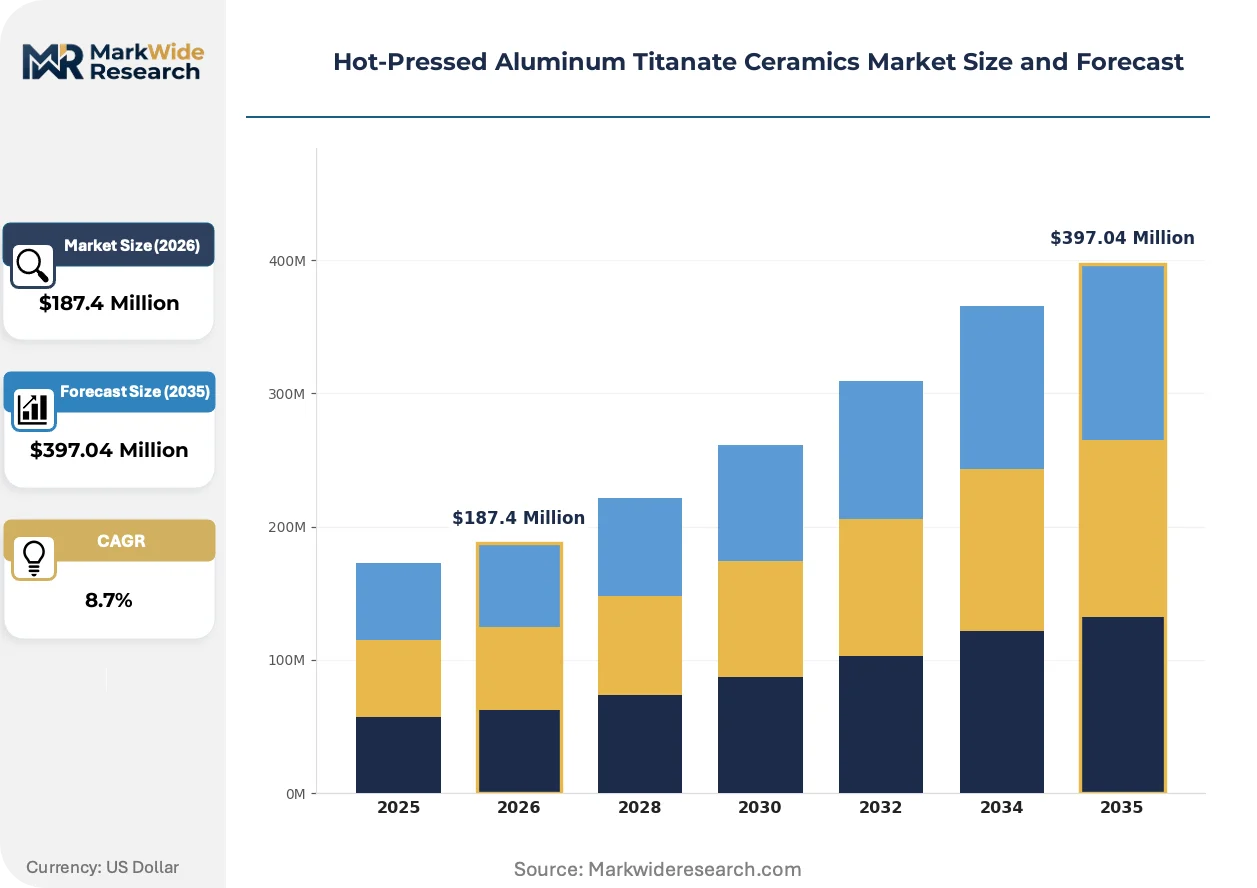
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tiles, Rods, Plates, Shapes End User: Aerospace, Automotive, Electronics, Energy Application: Catalytic Converters, Insulators, Refractories, Thermal Barriers Form: Raw, Finished, Semi-finished, Composites |
| Companies Covered | CoorsTek, CeramTec GmbH, KYOCERA Corporation, 3M, Morgan Advanced Materials, Saint-Gobain Performance Ceramics & Refractories, Blasch Precision Ceramics, AGC Ceramics, Applied Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot-Pressed Aluminum Titanate Ceramics Market Evolving Landscape
Process automation and regulatory chemistry mandates are compressing traditional development paradigms, while procurement rationalization among automotive exhaust integrators restructures channel economics.
Spark plasma sintering is collapsing the conventional trade-off between densification speed and microstructural control in aluminum titanate production. Aerospace thermal protection system contractors are piloting this technique for complex-shaped components, compressing lead times from weeks to days while maintaining thermal shock resistance thresholds.
The EU F-Gas Regulation's hydrofluorocarbon phase-down mandates are redirecting heat exchanger material specifications toward thermally stable ceramics. Aluminum titanate substrates are displacing metal-fin designs in refrigeration condensers, with German HVAC OEMs leading qualification programs ahead of 2030 reduction targets.
Automotive exhaust integrators are consolidating supplier panels and unbundling after-sales service obligations from component procurement. Tier 1 buyers now demand captive technical support for thermal barrier installation, with this pattern most visible in Detroit and Stuttgart manufacturing corridors where just-in-sequence delivery dominates.
Hot-Pressed Aluminum Titanate Ceramics Market Segmentation
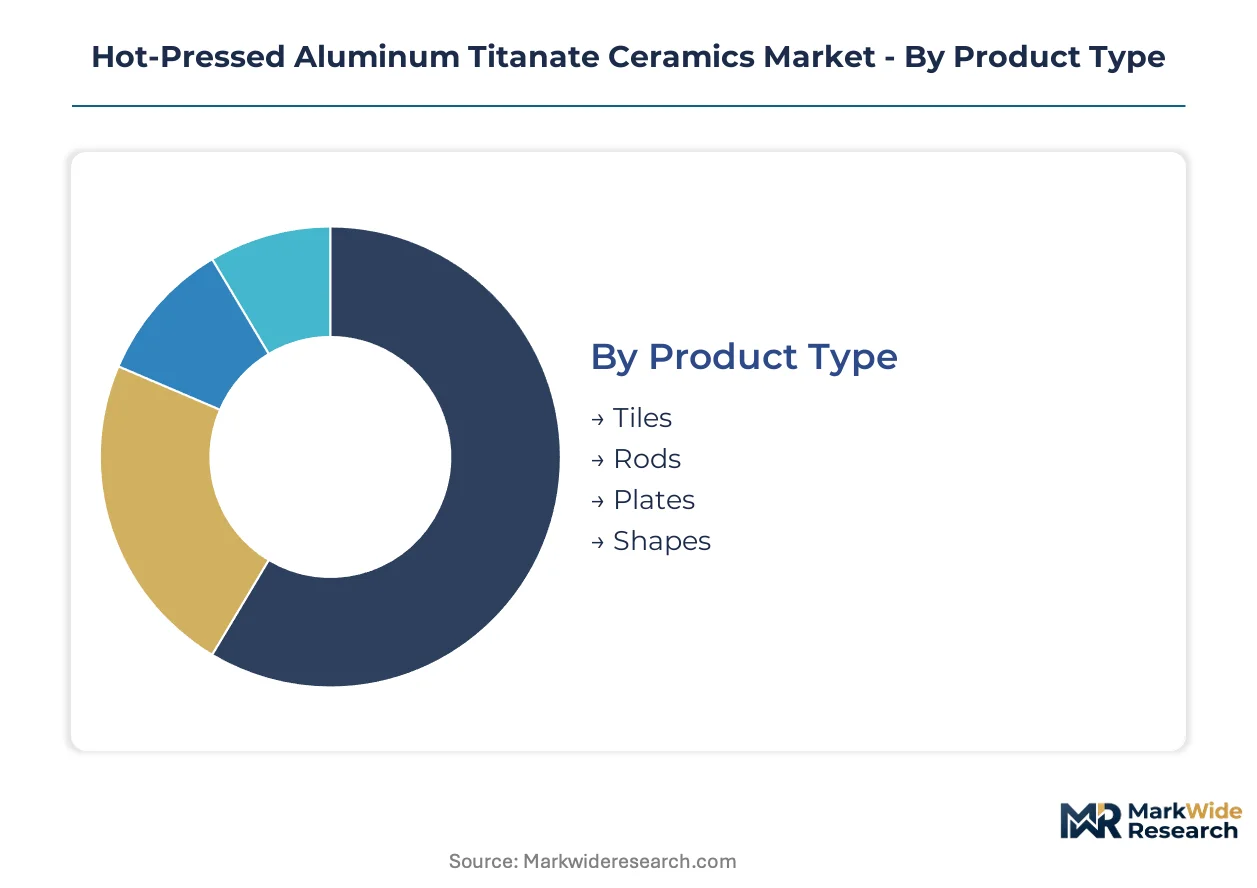
Hot-pressed aluminum titanate ceramics fragment across four structural dimensions that determine manufacturing investment, margin capture, and channel strategy. Product geometry and end-use thermal specifications create distinct capability requirements that separate commodity refractory suppliers from precision component specialists.
Product Type:
Geometric complexity drives processing economics from standard planar forms to engineered three-dimensional components.
- Tiles:Flat planar components with standardized thickness tolerances serve furnace lining retrofits and kiln deck applications. Demand concentrates in German steel mill maintenance cycles where rapid thermal cycling resistance reduces refractory replacement frequency.
- Plates:Larger-format planar substrates with controlled surface flatness specifications anchor catalytic converter substrate stacks. Japanese automotive exhaust integrators in Nagoya and Toyota City procurement pipelines specify these for EPA Tier 3 compliance retrofits.
- Rods:Cylindrical forms with axial symmetry requirements suit thermocouple protection sheaths and electrical insulator bushings.
- Shapes:Complex three-dimensional geometries with undercuts and thin-wall sections command premium positioning in aerospace thermal protection systems.
Established volume favors tiles; emerging adoption favors shapes.
End User:
Customer technical requirements range from commodity thermal cycling tolerance to mission-critical dimensional stability.
- Automotive:Exhaust aftertreatment system integrators specify near-theoretical density substrates with engineered microcrack networks for thermal shock resistance above 1000°C. Detroit and Stuttgart manufacturing corridors dominate procurement volumes tied to Euro 7 and EPA enforcement timelines.
- Aerospace:Re-entry vehicle heat shield contractors demand geometrically complex components with CTE-matched attachment interfaces. US prime contractors in Huntsville and Palmdale drive qualification programs for next-generation thermal protection.
- Energy:Catalytic converter substrate demand accelerates fastest among all end users, reflecting exhaust aftertreatment upgrades across automotive OEM supply chains.
- Electronics:KYOCERA Corporation anchors Asian electronics-grade production through in-house sintering expertise for semiconductor processing equipment.
Procurement scale favors automotive; technical complexity favors aerospace.
Application:
Functional thermal performance requirements separate passive insulation from active catalytic support applications.
- Catalytic Converters:Honeycomb-structured substrates with high geometric surface area enable exhaust gas conversion efficiency. EU F-Gas Regulation and tightening emissions standards across major economies reshape material specifications toward aluminum titanate in place of cordierite alternatives.
- Thermal Barriers:Low thermal conductivity components with controlled emissivity surfaces protect adjacent hardware from radiant heat flux. Aerospace engine compartment applications in Toulouse and Seattle manufacturing clusters specify these for turbine adjacent structures.
- Refractories:Mature volume positions in furnace lining applications where thermal shock resistance extends campaign life between rebuilds.
- Insulators:Electrical isolation components with dielectric strength specifications for high-temperature sensor applications.
Regulatory pull favors catalytic converters; margin stability favors thermal barriers.
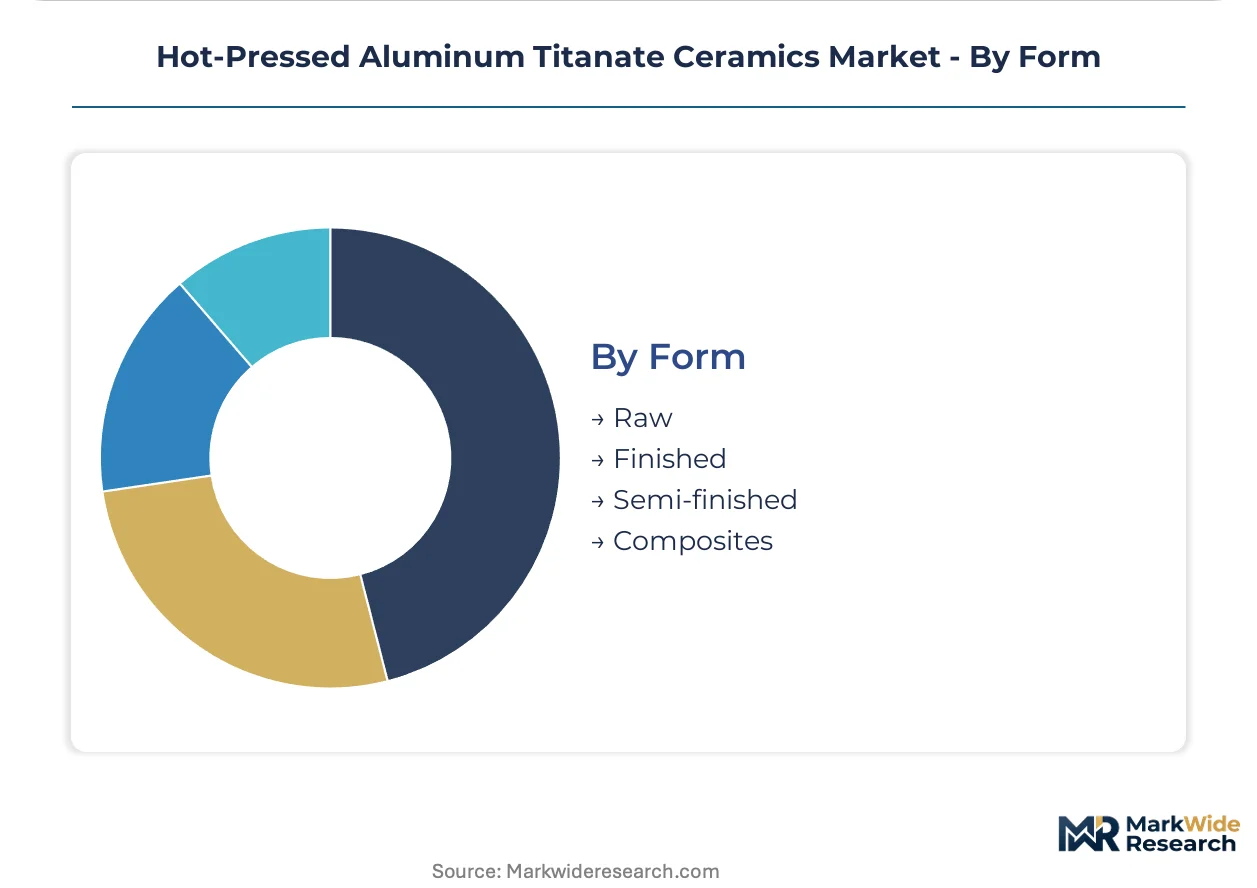
Form:
Supply chain position determines value capture from powder synthesis through finished component qualification.
- Finished:Fully densified components with final machining, surface treatment, and dimensional certification. Automotive Tier 1 suppliers in Düsseldorf and Detroit demand captive technical support for thermal barrier installation alongside just-in-sequence delivery.
- Semi-finished:Near-net-shape sintered blanks requiring final grinding or diamond machining to customer specifications.
- Raw:Unprocessed powder blends or green compacts for captive hot-pressing operations at integrated refractory manufacturers.
- Composites:Aluminum titanate matrix materials with secondary phase additions for enhanced fracture toughness or tailored thermal expansion.
Value concentration favors finished; backward integration incentives favor raw.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive exhaust integrators and aerospace thermal protection contractors concentrate procurement in manufacturing clusters where precision ceramics capabilities intersect with stringent emissions enforcement. Buyer archetypes map directly to regulatory pressure zones.
Germany
EPA Tier 3-equivalent Euro 7 preparation is accelerating substrate qualification timelines for Stuttgart and Munich exhaust system suppliers. The EU F-Gas Regulation's hydrofluorocarbon phase-down redirects HVAC heat exchanger specifications toward aluminum titanate alternatives. The Düsseldorf-Ruhr manufacturing corridor anchors captive powder synthesis operations serving automotive Tier 1 panels.
United States
Re-entry vehicle heat shield contractors in Huntsville and Palmdale drive qualification programs for geometrically complex thermal protection components. EPA tailpipe enforcement maintains pressure on Detroit automotive exhaust integrators to upgrade catalytic converter thermal efficiency. The Southeast refractory maintenance market extends furnace lining replacement cycles through thermal shock-resistant tile specifications.
Japan
METI energy efficiency standards and JIS ceramic certification frameworks structure procurement pipelines for precision thermal barrier components. Nagoya and Toyota City automotive exhaust manufacturers specify plate-format substrates for rapid temperature cycling applications. Aging hot-press operator expertise concentrates in the Chubu manufacturing cluster, creating workforce transition pressures.
China
Dual carbon goals and tightening industrial emissions standards reshape material specifications in steel mill refractory retrofits. Yangtze River Delta precision ceramics manufacturers are scaling hot-pressing automation to serve domestic automotive exhaust system integrators. Shanghai-based HVAC OEMs pilot aluminum titanate heat exchanger substrates ahead of fluorinated gas restriction timelines.
South Korea
Seoul Capital Area automotive component suppliers are synchronizing sintering automation upgrades with export market compliance deadlines. MFDS-equivalent industrial material certification frameworks govern precursor chemical sourcing for domestic hot-pressing operations. Busan-Ulsan manufacturing clusters specialize in electronics-grade aluminum titanate for semiconductor processing equipment.
Hot-Pressed Aluminum Titanate Ceramics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture positions. The vendor base organizes around three strategic archetypes: vertically integrated refractory conglomerates controlling powder-to-finished supply chains; precision ceramics specialists commanding geometric complexity premiums; and captive automotive suppliers integrated into exhaust system OEM hierarchies. Dominant competitive moves include sintering automation upgrades synchronized with regulatory compliance deadlines and direct OEM contracting that bypasses traditional distribution channels.
Among vertically integrated conglomerates, CoorsTek anchors North American supply networks through captive powder synthesis capabilities. CeramTec GmbH exemplifies the precision specialist archetype within European catalytic converter substrate supply chains. KYOCERA Corporation occupies a position at the intersection of electronics-grade production and in-house sintering expertise. These three entities represent distinct competitive vectors: scale-driven backward integration, application-specific technical positioning, and end-market captive supply relationships.
| Leading Market Players |
|---|
| CoorsTek |
| CeramTec GmbH |
| KYOCERA Corporation |
| 3M |
| Morgan Advanced Materials |
| Saint-Gobain Performance Ceramics & Refractories |
| Blasch Precision Ceramics |
| AGC Ceramics |
| Applied Ceramics |
| Others |
Value Network & Pricing Analysis
The Düsseldorf-Ruhr manufacturing corridor's captive powder synthesis capacity anchors European pricing power, with automotive Tier 1 buyers absorbing pass-through costs from high-purity titanium dioxide indexation. EPA Tier 3 and Euro 7 compliance deadlines compress procurement cycles, forcing exhaust system integrators into long-term offtake commitments that lock in volume discounts against spot-market volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked titanium dioxide indexation dominate procurement between German powder synthesizers and Detroit exhaust integrators. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade tiers separates mission-critical thermal protection from commodity refractory applications. Cost compression in automotive substrates intensifies as just-in-sequence delivery obligations erode margin buffers. Exhaust system OEMs exhibit highest price sensitivity; aerospace prime contractors accept premium positioning for geometric complexity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates risk calculus for precision ceramics distributors serving automotive Tier 1 panels. Germany, Japan, and the United States concentrate high-purity aluminum oxide and titanium dioxide feedstock synthesis. Production rests on rutile ore shipments from Australia, ilmenite processing in China, and specialty alumina refining in the Rhine-Ruhr cluster. Single-source vulnerability concentrates in Nagoya and Düsseldorf hot-press operator expertise. Distribution runs through captive supply agreements with exhaust system integrators, bypassing traditional refractory merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Simultaneous temperature-pressure profiling expertise sits with aging workforces in established manufacturing clusters, creating a bottleneck that constrains capacity expansion regardless of capital deployment. This scarcity dynamic favors incumbents with embedded technical knowledge over entrants relying on automated replication.
For Market Incumbents: Pre-empt spark plasma sintering adoption by aerospace contractors through qualification partnerships ahead of traditional hot-pressing obsolescence. Lock in backward integration into high-purity precursor synthesis to neutralize titanium dioxide cost volatility from pigment demand cycles. Defend channel position by unbundling after-sales technical support from component pricing, mirroring Detroit and Stuttgart procurement patterns. For New Entrants and Emerging Players: Build out HVAC heat exchanger substrate capabilities ahead of EU F-Gas Regulation phase-down deadlines, where qualification timelines remain open and incumbent attention focuses on automotive exhaust. Target Shanghai-based refrigeration OEMs piloting aluminum titanate alternatives to fluorinated gas systems. Pursue direct technical service contracting as the go-to-market angle, bypassing consolidated supplier panels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision ceramics specialists with aerospace thermal protection qualifications over commodity refractory conglomerates. Long-term viability hinges on geometric complexity premiums outside automotive commodity cycles. Monitor spark plasma sintering adoption rates among re-entry vehicle contractors as the inflection signal for process technology substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Pressing Automation Upgrade | CoorsTek and CeramTec GmbH synchronize uniaxial pressure control investments with EPA Tier 3 compliance deadlines. |
| Backward Integration into Precursor Synthesis | KYOCERA Corporation anchors cost advantages through captive high-purity titanium dioxide refining in Japanese manufacturing clusters. |
| Direct OEM Contracting | Exhaust system integrators in Detroit and Stuttgart bypass traditional refractory distribution through captive supply agreements. |
| Aerospace Qualification Partnership | Re-entry vehicle contractors in Huntsville and Palmdale pilot spark plasma sintering for geometrically complex heat shield components. |
| EU F-Gas Regulation Compliance Positioning | German HVAC OEMs accelerate aluminum titanate heat exchanger substrate programs ahead of hydrofluorocarbon phase-down targets. |
Research Methodology
Initial hypotheses were tested against primary input from hot-press operations managers, automotive Tier 1 procurement leads, aerospace thermal protection system engineers, and refractory distribution channel heads, then refined through secondary validation. Bottom-up triangulation combined customs data on titanium dioxide and aluminum oxide trade flows, SEC filings from precision ceramics manufacturers, JIS certification registry analysis, and EPA enforcement action databases. Top-down demand modeling cross-referenced automotive production schedules with catalytic converter substrate content assumptions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product geometry, end-use thermal specifications, application functional requirements, and supply chain position. CAGRs derived from installed base replacement cycles, emissions regulation phase-in schedules, and sintering automation penetration curves. Industry-specific inputs included hot-press operator workforce demographics and REACH compliance timeline distributions.
Stress conditions across titanium dioxide price volatility bands, Euro 7 implementation delays, and spark plasma sintering adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Transparent Ceramics Market
Ceramics
2N High Purity Alumina Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Ceramic Substrate Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Global Barium Carbonate Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Global Ceramic Foams Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Low Density Ceramic Proppant Market