
 Transcatheter Mitral Valve Market | 2026-2036
Transcatheter Mitral Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Mitral Valve Market Analytics
Capital-intensity divergence between established manufacturers and emerging entrants is bifurcating competitive dynamics in transcatheter mitral valve development. Abbott Laboratories leverages its structural heart portfolio to sustain integrated catheter and implant supply chains across multiple continents. Edwards Lifesciences dominates percutaneous mitral repair through its differentiated clip-based platform, while Medtronic anchors competitive positioning with self-expanding replacement technologies.
Transcatheter mitral valve encompasses percutaneously delivered prosthetic devices that restore coaptation or replace diseased native valves without sternotomy, typically constructed from bovine or porcine pericardial tissue mounted on nitinol or cobalt-chromium frames and delivered via 22-28 French delivery sheaths. These devices serve patients with severe mitral regurgitation who face prohibitive surgical risk due to age, frailty, or comorbidities. Mitral Valve Replacement captures the dominant share of current revenue as first-generation repair devices face durability questions, while Transfemoral delivery mode leads procedural volume due to reduced vascular complications compared to transapical access. Balloon-Expandable technology occupies a narrower niche but commands premium positioning in calcific anatomies where precise annular sizing proves critical.
The FDA breakthrough device program and EMA's early dialogue pathway shape trial design and premarket evidence requirements for transcatheter mitral innovations, while ISO 5840 cardiovascular implant standards govern fatigue resistance and hydrodynamic performance testing. Japan's PMDA imposes additional post-market surveillance obligations that extend clinical data collection timelines for manufacturers seeking reimbursement. Stakeholders must monitor evolving CMS national coverage determinations and parallel health technology assessment processes in France and Germany, as payer decisions will determine whether projected procedure volumes convert to sustainable revenue.
Market Dynamics
FDA breakthrough device designations are compressing clinical trial timelines for novel transcatheter mitral valve systems while simultaneously intensifying evidence requirements for reimbursement eligibility.
Growth Catalysts
- Structural Heart Program Expansion:Hospital systems in the United States are building dedicated catheterization laboratories with integrated imaging capabilities to capture high-risk surgical candidates.
- EMA Early Dialogue Pathway:European manufacturers leverage pre-submission consultations to align trial endpoints with health technology assessment criteria across France and Germany.
- Calcific Anatomy Prevalence:Aging populations with degenerative mitral valve disease create procedural demand for transcatheter replacement over repair in anatomically unfavorable cases.
Market Restraints
- Nitinol Price Volatility:Superelastic alloy supply concentration in specialized foundries exposes manufacturers to raw material cost swings affecting frame production economics.
- PMDA Post-Market Surveillance:Japan's extended clinical data collection obligations delay reimbursement decisions and compress revenue recognition timelines for entrants.
- Surgical Valve Durability:Long-term performance data from transcatheter systems remains immature compared to established surgical benchmarks, constraining guideline expansion.
Strategic Opportunities
- Tricuspid Convergence:Transcatheter platforms originally developed for mitral applications are migrating to tricuspid regurgitation, opening adjacent procedural markets with shared catheter infrastructure.
- CMS National Coverage Determinations:Favorable Medicare reimbursement decisions for expanded indications would unlock procedural volume in community hospital settings.
- Transseptal Delivery Innovation:Next-generation steerable sheaths reduce left atrial manipulation time, enabling outpatient discharge protocols and ambulatory surgery center penetration.
Industry Challenges
- Imaging Specialist Scarcity:Real-time intracardiac echocardiography interpretation requires dedicated training pipelines that outpace current fellowship output.
- ISO 5840 Fatigue Testing:Accelerated wear validation protocols demand extended capital equipment utilization and specialized hydrodynamic testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Mitral Valve Market |
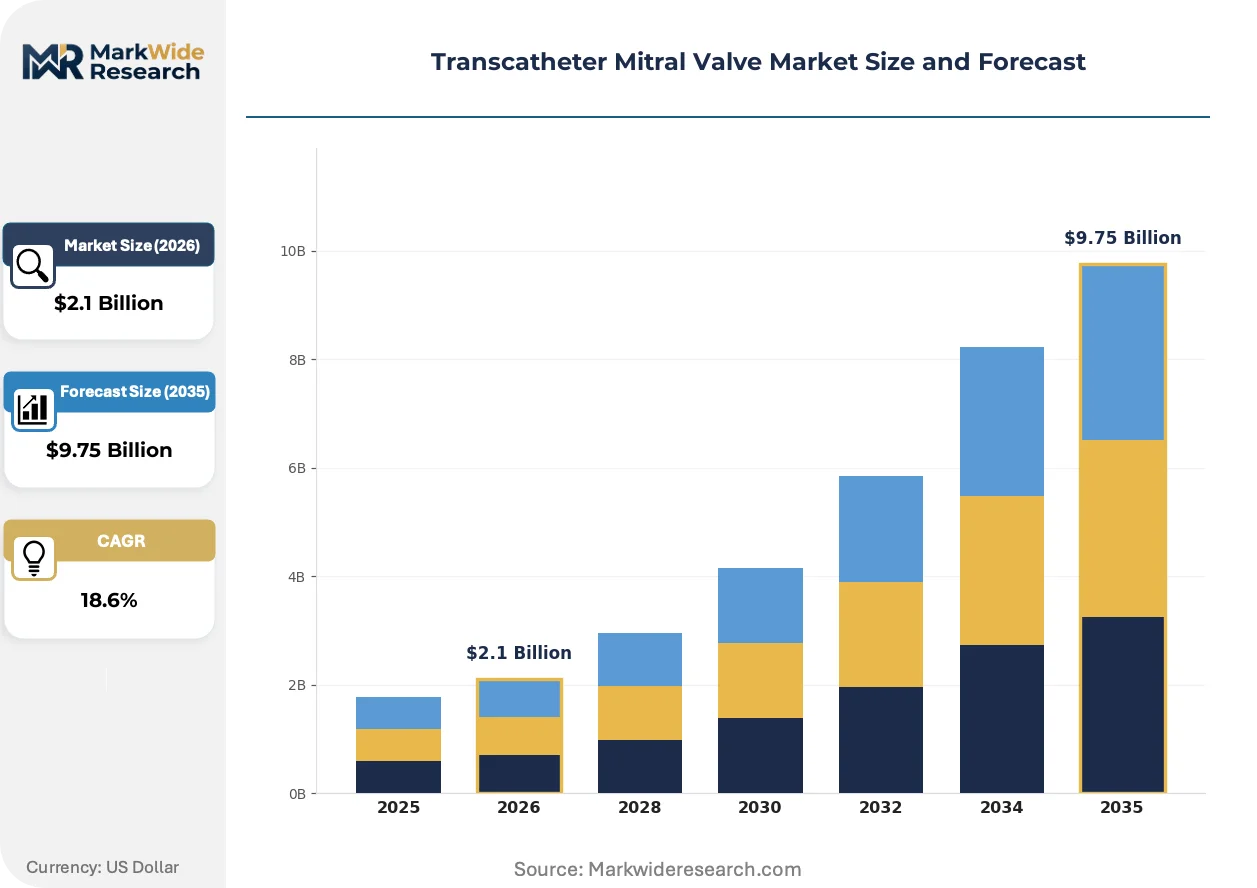
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mitral Valve Replacement, Mitral Valve Repair, Alternative Solutions, Accessories Technology: Telegraft, Self-Expanding, Balloon-Expandable, Transcatheter Techniques End User: Cardiology Clinics, Hospitals, Surgical Centers, Ambulatory Surgery Centers Delivery Mode: Transfemoral, Transapical, Transsepal, Others |
| Companies Covered | Abbott Laboratories, Edwards Lifesciences Corporation, Medtronic, Boston Scientific Corporation, LIVANOVA PLC, NeoChord, Inc., HLT Inc, Coramaze Technologies, Cardiac Dimensions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Mitral Valve Market Evolving Landscape
Device miniaturization and procedural simplification are converging to expand treatable patient populations beyond the surgically ineligible core segment.
Self-expanding nitinol frames with adaptive anchoring mechanisms are displacing first-generation rigid delivery systems in anatomically complex cases. High-volume cardiac centers in Germany and the United States are adopting these platforms for moderate-risk patients previously routed to conventional surgery. The shift is compressing the addressable market for surgical valve replacement in septuagenarian populations.
MDR Article 117 clinical evidence requirements are forcing manufacturers to supplement bench testing with prospective registry data for CE marking renewal. European notified bodies now demand extended follow-up periods for bioprosthetic tissue durability claims. Transcatheter replacement manufacturers are responding by embedding post-market surveillance into original trial designs rather than retrofitting compliance.
Hospital procurement committees are consolidating vendor relationships around full structural heart portfolios rather than single-product negotiations. Integrated supply agreements covering catheters, implants, and imaging equipment are displacing transaction-based purchasing in United States health systems. This concentration is most visible in multi-hospital networks seeking standardization across catheterization laboratory fleets.
Transcatheter Mitral Valve Market Segmentation
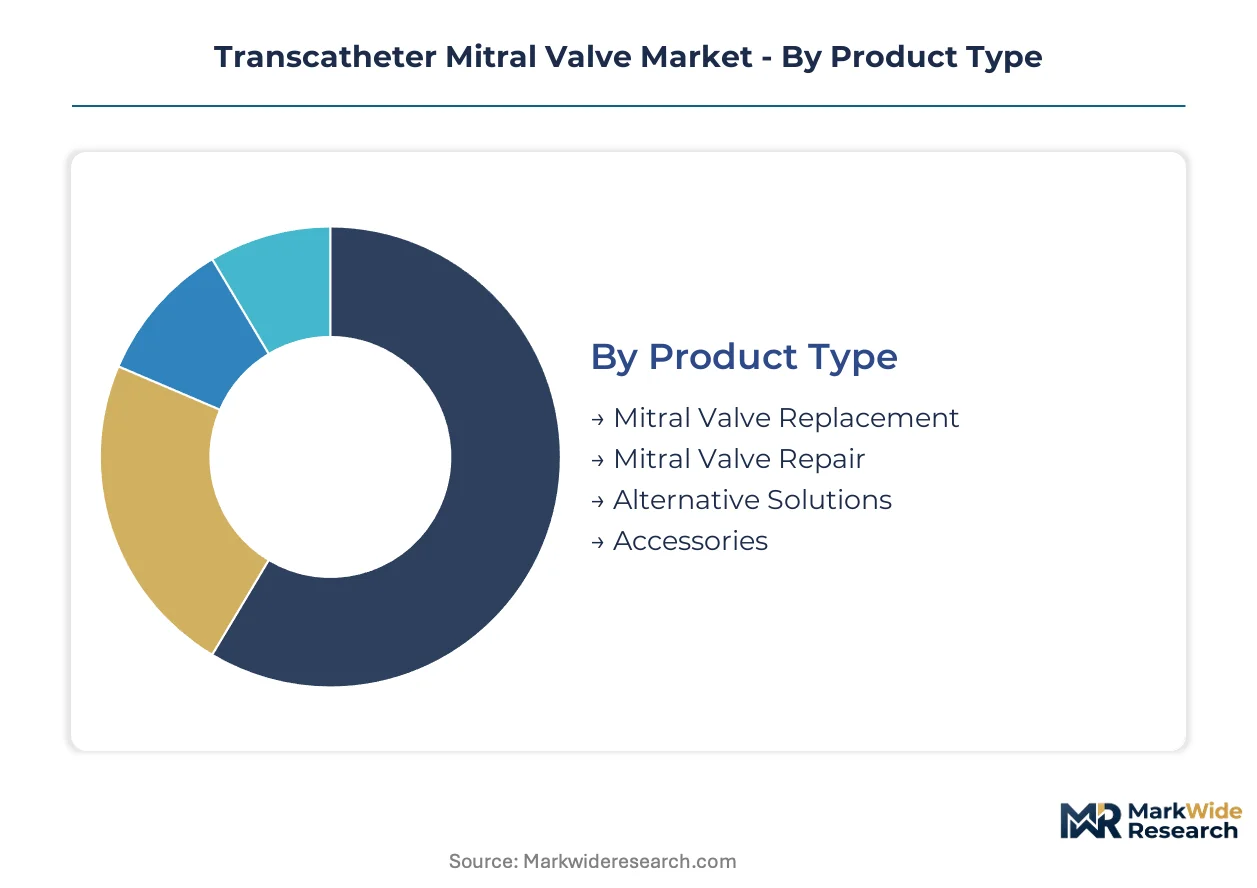
Transcatheter mitral valve segmentation reveals distinct commercial pathways where product configuration, delivery approach, and care setting interlock to determine reimbursement eligibility and procedural economics. Understanding these segment boundaries enables manufacturers to align clinical trial design with the specific evidence requirements of each channel.
Product Type:
Mitral Valve Replacement flows through hospital structural heart programs with integrated imaging infrastructure, while Mitral Valve Repair concentrates in specialized cardiac surgery centers with established interventional cardiology partnerships.
- Mitral Valve Replacement:Percutaneous implant systems constructed from bovine or porcine pericardial tissue mounted on nitinol frames, designed for complete native valve excision and prosthetic substitution. Demand concentrates in German cardiac surgery centers expanding programs for high-risk surgical candidates, driven by durability questions surrounding first-generation repair devices in calcific anatomies.
- Mitral Valve Repair:Clip-based or annuloplasty systems that restore native valve coaptation without valve excision, preserving subvalvular apparatus and ventricular geometry. United States hospital systems building dedicated structural heart programs represent the primary demand channel, with FDA breakthrough device designations compressing clinical trial timelines for novel systems.
- Alternative Solutions:Hybrid surgical-transcatheter approaches and chordal implant systems for anatomically complex regurgitation patterns.
- Accessories:Delivery sheath extensions, retrieval snares, and sizing balloons supporting primary implant procedures.
Mitral Valve Replacement dominates installed base. Mitral Valve Repair is where expansion concentrates.
Technology:
Cost tier stratification separates premium self-expanding platforms from standard balloon-expandable systems, with telegraft technologies occupying an emerging premium position requiring specialized training infrastructure.
- Self-Expanding:Nitinol frame systems with adaptive anchoring mechanisms that conform to irregular annular geometries without balloon inflation. Cardiac centers in Germany and the United States are adopting these platforms for moderate-risk patients, compressing the addressable market for surgical valve replacement in aging populations with degenerative disease.
- Balloon-Expandable:Cobalt-chromium frames deployed under fluoroscopic guidance with precise inflation control for calcific anatomies. These systems command premium positioning where annular sizing accuracy proves critical, though their narrower niche reflects procedural complexity and higher capital equipment requirements.
- Telegraft:Remote monitoring-enabled implant platforms with integrated hemodynamic sensors for post-procedure surveillance.
- Transcatheter Techniques:Procedure-specific methodological approaches including direct annuloplasty and chordal repair.
Self-Expanding platforms capture the majority of new system placements. Balloon-Expandable technology maintains its position in complex calcific cases.
End User:
Volume concentration differs sharply across settings, with hospitals absorbing complex replacement procedures while ambulatory surgery centers capture simplified repair cases eligible for same-day discharge protocols.
- Hospitals:Academic medical centers and community hospital systems with catheterization laboratories equipped for transseptal access and real-time intracardiac echocardiography. These facilities handle the full complexity spectrum including bailout surgical conversion capability, with procurement committees consolidating vendor relationships around full structural heart portfolios.
- Cardiology Clinics:Outpatient diagnostic and follow-up facilities supporting pre-procedure screening and post-implant surveillance.
- Surgical Centers:Hybrid operating rooms combining surgical backup with interventional catheter capabilities.
- Ambulatory Surgery Centers:Standalone facilities pursuing outpatient discharge protocols enabled by next-generation steerable sheaths reducing left atrial manipulation time.
Hospitals retain the dominant installed base. Ambulatory Surgery Centers represent the steepest expansion trajectory as reimbursement frameworks evolve.
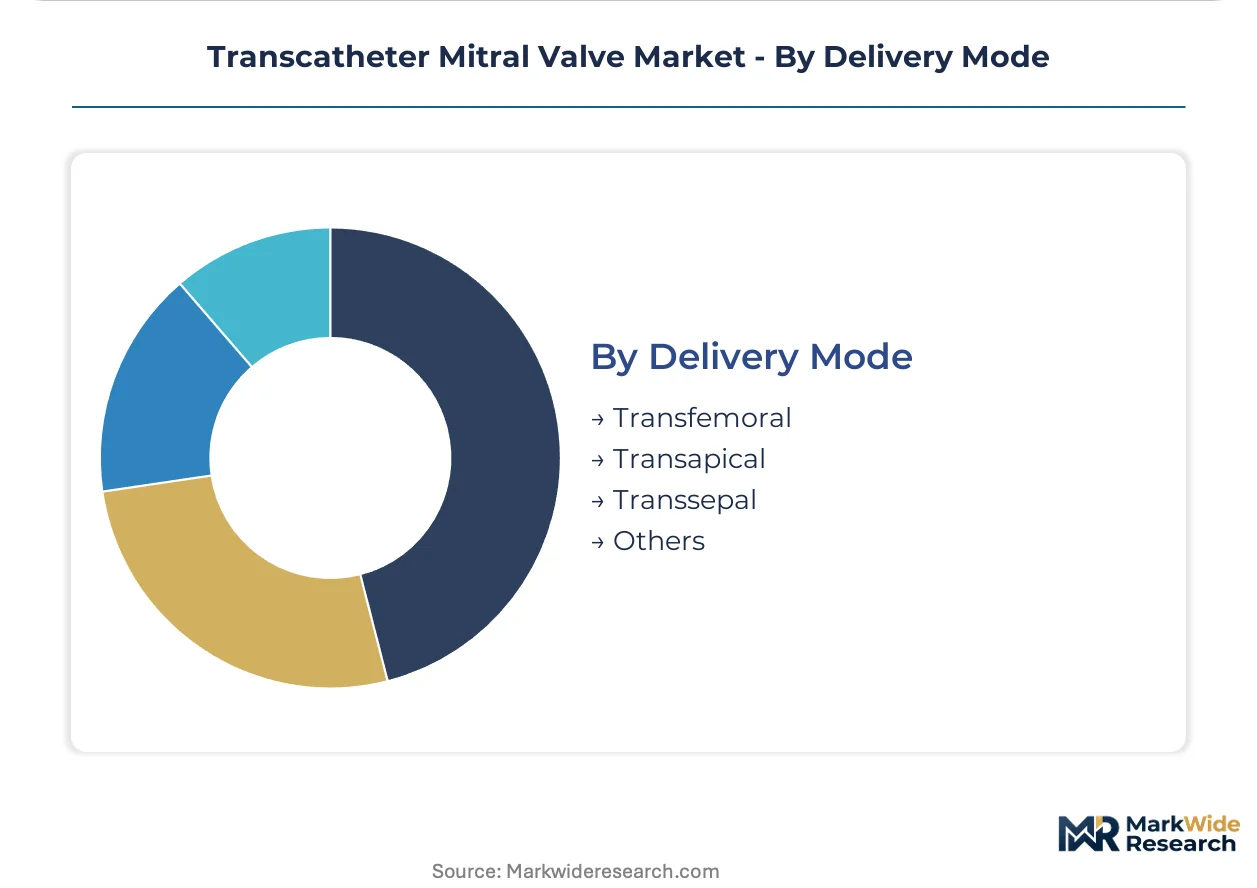
Delivery Mode:
Supply concentration in transfemoral sheath manufacturing creates procurement leverage for high-volume centers, while transapical access maintains relevance for patients with prohibitive femoral vascular disease.
- Transfemoral:Retrograde femoral venous access with transseptal puncture to reach the left atrium, utilizing 22-28 French delivery sheaths. This approach leads procedural volume due to reduced vascular complications compared to transapical access, with next-generation steerable sheaths enabling shorter procedure times and ambulatory surgery center penetration.
- Transapical:Direct left ventricular apex access through mini-thoracotomy for patients with severe peripheral vascular disease or prior femoral intervention. Demand persists in specific anatomical subsets where transfemoral delivery proves technically unfeasible.
- Transseptal:Atrial septal puncture techniques refined for mitral-specific trajectory and stability requirements.
- Others:Transatrial and transcarotid alternative access routes for exceptional anatomical circumstances.
Transfemoral delivery dominates installed base. Transseptal technique refinement is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes transcatheter mitral valves predominantly through replacement procedures in hospital structural heart programs, whereas Germany and Japan exhibit higher repair-to-replacement ratios driven by surgical center specialization and conservative patient selection protocols.
United States
Hospital systems in the United States are building dedicated catheterization laboratories with integrated imaging capabilities to capture high-risk surgical candidates. FDA breakthrough device designations compress clinical trial timelines while intensifying evidence requirements for CMS reimbursement eligibility. The Cleveland Clinic and Mayo Clinic anchor procedural volume concentration in the Midwest, with both centers expanding transcatheter mitral valve replacement programs for moderate-risk patients.
Germany
Cardiac surgery centers across Germany are expanding transcatheter mitral valve repair programs specifically for high-risk surgical candidates with degenerative disease. EMA early dialogue pathways enable manufacturers to align trial endpoints with German health technology assessment criteria. The Heidelberg and Munich metropolitan areas host the highest procedural densities, with university hospitals integrating self-expanding platforms into routine clinical workflows.
Japan
Aging demographics with calcific mitral valve disease generate procedural demand for transcatheter replacement systems in anatomically unfavorable cases. PMDA post-market surveillance obligations extend clinical data collection timelines and delay reimbursement decisions for market entrants. Tokyo and Osaka medical centers concentrate specialist expertise in real-time intracardiac echocardiography interpretation, creating training bottlenecks that constrain procedural expansion.
Switzerland
Swiss university hospitals participate in pan-European clinical trials for novel repair systems under Swissmedic streamlined approval frameworks. The country's reimbursement authorities require extended follow-up data for bioprosthetic tissue durability claims before permanent procedure codes. Zurich and Geneva cardiac centers coordinate with German and Austrian networks to standardize transseptal delivery protocols across the Alpine region.
United Kingdom
NHS England specialized commissioning frameworks concentrate transcatheter mitral procedures in designated cardiac surgery centers with surgical backup capability. NICE health technology assessments evaluate cost-effectiveness against surgical benchmarks, creating evidence thresholds that favor replacement over repair in initial coverage decisions. London teaching hospitals and the Manchester University NHS Foundation Trust anchor the national procedural volume.
Transcatheter Mitral Valve Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in transcatheter mitral valve development. Abbott Laboratories and Edwards Lifesciences occupy the integrated tier through structural heart portfolio breadth, while NeoChord and Cardiac Dimensions exemplify the specialist tier with focused repair technologies. Competitive dynamics bifurcate around M&A activity targeting catheter infrastructure and strategic partnerships for imaging integration. Vertical integration into nitinol frame manufacturing represents a second competitive vector as raw material cost volatility pressures margins.
Within the integrated tier, Abbott Laboratories, Edwards Lifesciences Corporation, and Medtronic occupy positions defined by portfolio breadth and geographic reach. Abbott exemplifies the diversified structural heart archetype with integrated catheter and implant supply chains. Edwards anchors the clip-based repair segment through platform specialization. Medtronic represents the self-expanding replacement technology archetype with adaptive anchoring mechanisms. These three entities sit within a competitive structure where hospital procurement committees increasingly consolidate vendor relationships around full structural heart portfolios rather than single-product negotiations.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Medtronic |
| Boston Scientific Corporation |
| LIVANOVA PLC |
| NeoChord, Inc. |
| HLT Inc |
| Coramaze Technologies |
| Cardiac Dimensions |
| Others |
Value Network & Pricing Analysis
FDA breakthrough device designations and ISO 5840 cardiovascular implant standards simultaneously gate supply qualification and stratify price tiers in transcatheter mitral valve manufacturing. Manufacturers must absorb extended fatigue testing costs and specialized hydrodynamic facility investments before capturing premium positioning in hospital procurement committees.
Pricing Analysis
Long-term supply agreements dominate hospital procurement, with integrated structural heart portfolios commanding preferential contract terms over single-product vendors. Price differentiation stems from FDA breakthrough designation status and CE marking tier under MDR Article 117, with balloon-expandable systems carrying steeper premiums for calcific anatomy applications. Cost compression runs through repair device segments as durability questions intensify competitive bidding. Ambulatory surgery centers exhibit highest price sensitivity due to reimbursement uncertainty, while academic medical centers prioritize clinical evidence depth over unit cost.
Supply Chain Analysis
Germany and the United States anchor nitinol frame fabrication and pericardial tissue processing for transcatheter valve manufacturing. Production draws from bovine and porcine tissue supply chains plus superelastic alloy foundries concentrated in specialized metallurgical facilities. Single-source vulnerability in nitinol supply exposes manufacturers to raw material cost swings affecting frame production economics. Distribution runs through integrated catheter and implant supply chains managed by hospital procurement committees consolidating vendor relationships across multi-hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement committee consolidation around full structural heart portfolios has shifted bargaining power toward buyers, compressing margins for single-product manufacturers and rewarding integrated suppliers with durable contract positions.
For Market Incumbents: Secure captive supply of nitinol frame manufacturing through backward integration into specialized foundry relationships, insulating against superelastic alloy price volatility. Deepen FDA breakthrough designation pipelines to maintain premium positioning as MDR Article 117 evidence requirements intensify. Anchor hospital system partnerships through integrated catheter, implant, and imaging equipment supply agreements that resist procurement committee consolidation pressures. For New Entrants and Emerging Players: Lead with tricuspid regurgitation applications as a white-space target, leveraging shared catheter infrastructure from mitral platforms to penetrate an adjacent procedural market with lighter competitive density. Target ambulatory surgery centers pursuing outpatient discharge protocols, where next-generation steerable sheath compatibility creates entry pathways outside incumbent-dominated academic medical centers. Build reimbursement strategy around CMS national coverage determination timelines rather than competing head-to-head in established hospital structural heart programs. For Investors and Strategic Acquirers: FDA breakthrough device designations reshaping the acquisition landscape signal differentiated regulatory trajectory value in target screening. Frame long-term viability around manufacturers embedding post-market surveillance into original trial designs rather than retrofitting MDR compliance. Watch EMA early dialogue pathway utilization rates as an inflection indicator for European market access efficiency and health technology assessment alignment capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated trial timelines compress competitive entry windows for novel repair systems. |
| CE Marking Pathway under MDR Article 117 | Extended follow-up requirements favor manufacturers with embedded post-market surveillance infrastructure. |
| Hospital System Partnership | Integrated supply agreements displace transaction purchasing in United States multi-hospital networks. |
| Backward Integration into Nitinol Supply | Captive frame manufacturing insulates margins from superelastic alloy foundry concentration. |
| Reimbursement Strategy | CMS national coverage determinations unlock procedural volume in community hospital settings. |
Research Methodology
Cross-validation between primary interviews with interventional cardiologists, structural heart program directors, hospital procurement managers, and GPO contracts specialists anchors the qualitative findings in this study. Secondary validation draws from FDA 510(k) and PMA filings, EMA submission databases, CMS national coverage determinations, and ISO 5840 testing protocols. Bottom-up procedure volume modeling triangulates against top-down market sizing from manufacturer revenue disclosures and hospital procurement database analysis.
Sensitivity analysis across technology adoption curves, reimbursement scenario variants, and competitive entry timing informs the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, delivery mode, technology tier, and care setting complexity. CAGRs derive from procedure volume trajectories mapped to implant pricing trends and hospital capacity expansion plans, with nitinol cost volatility and PMDA surveillance timelines as key forecast inputs.
Forecasts assume regulatory continuity in FDA breakthrough pathways, EMA early dialogue frameworks, and CMS reimbursement structures; material policy shifts would require re-modeling. Specific risk factors include MDR Article 117 evidence requirement evolution, PMDA post-market surveillance extension, and CMS national coverage determination unfavorable rulings. Recalibration cycles align with material shifts in regulatory pathway efficiency and hospital procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intubation Accessories Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
US C-Arms Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Global Pessary Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market