
 Echogenic Catheters Market | 2026-2036
Echogenic Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Echogenic Catheters Market Foresight
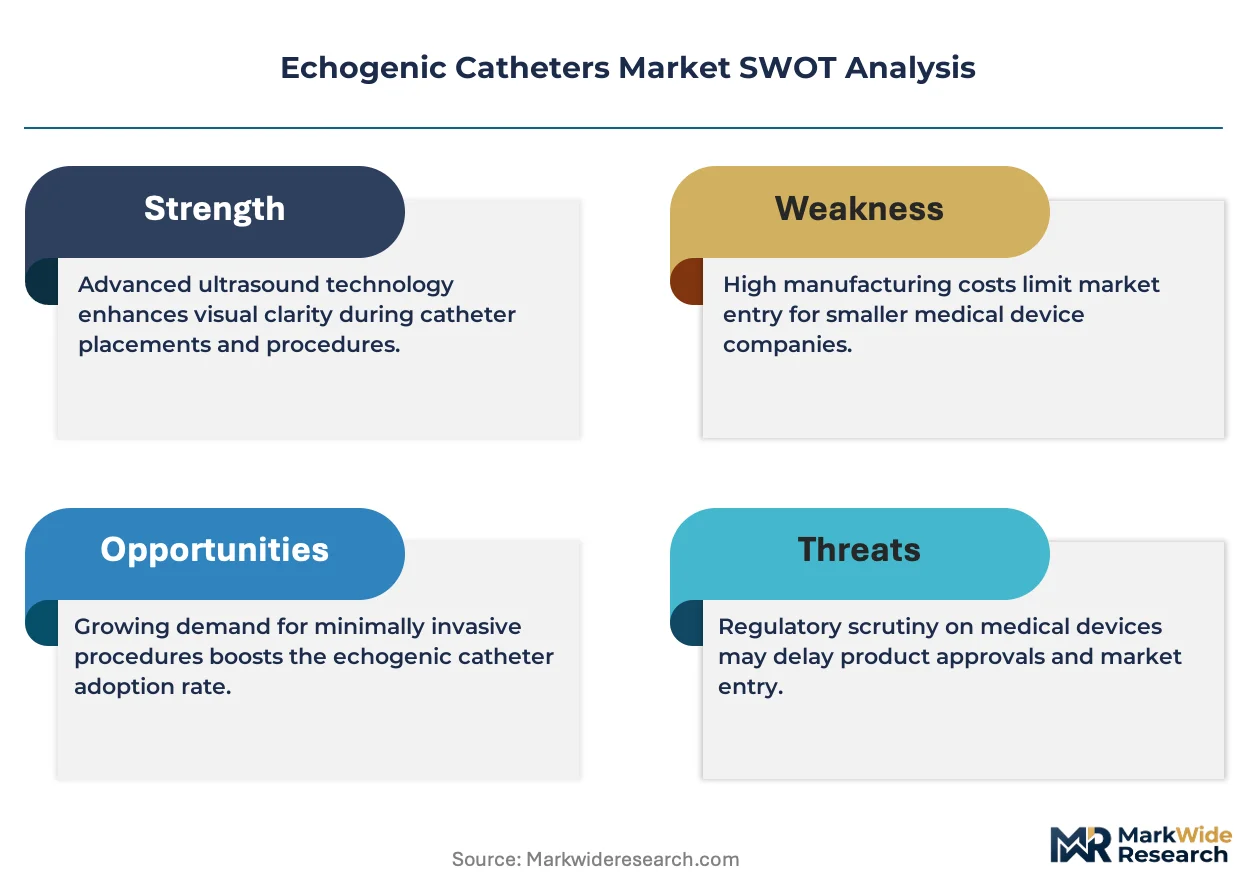
MDR in Europe is repositioning the cost-of-entry calculus for catheter manufacturers seeking CE marking, forcing smaller suppliers to consolidate quality management systems or exit the market entirely. B. Braun leverages its vertically integrated polymer compounding operations to absorb these compliance costs without outsourcing critical material qualification steps. Teleflex anchors its competitive stance through direct hospital contracting in Germany and France, where MDR notified body capacity constraints have created months-long approval queues that favor incumbents with established technical files.
Echogenic catheters incorporate acoustic enhancement features—typically embedded microbubbles, dimpled surfaces, or composite polymer layers containing high-impedance fillers—that scatter ultrasound waves and produce bright artifact patterns under real-time imaging, enabling clinicians to track catheter tip position during nerve blocks, central line placements, and cardiac electrophysiology procedures. Single-lumen catheters dominate procedural volumes in anesthesia departments, though multi-lumen configurations command premium positioning in cardiac intensive care units where simultaneous pressure monitoring and medication delivery reduce line exchanges. Polyurethane formulations lead material selection for vascular applications due to tensile strength and thromboresistance, while silicone variants sustain share in neurology where softer durometer reduces nerve trauma risk during prolonged indwelling use.
FDA 510(k) clearance requirements, EU MDR technical documentation standards, and ISO 13485 quality system certifications collectively shape product development roadmaps and market access timelines for echogenic catheter suppliers. The FDA's evolving predicate device policy for echogenic coatings creates uncertainty for novel surface technologies, while MDR's clinical evidence expectations for Class IIa devices extend time-to-revenue for European market entrants. Stakeholders must monitor how notified body interpretation of biocompatibility testing for acoustic filler materials evolves, as this will determine whether next-generation echogenic formulations gain regulatory traction or face extended premarket validation cycles.
Market Dynamics
Hospital procurement consortia in the United States are compressing vendor margins through standardized echogenic catheter specifications across integrated delivery networks, forcing manufacturers to absorb coating qualification costs or exit contracted supplier lists.
Growth Catalysts
- Ultrasound-guided vascular access protocols:Tertiary hospitals are embedding real-time catheter visualization into central line placement bundles, expanding procedural volume for acoustic-enhanced devices.
- FDA 510(k) pathway streamlining:The agency's updated predicate device policy for echogenic coating modifications accelerates clearance timelines for manufacturers with established acoustic filler biocompatibility data.
- Polyurethane thromboresistance:Material advances in segmented polyurethane formulations reduce catheter-related thrombosis rates, sustaining replacement demand in cardiac intensive care units.
Market Restraints
- MDR notified body capacity:European Union medical device regulation technical documentation queues extend time-to-revenue for Class IIa catheter entrants, favoring incumbents with pre-existing technical files.
- High-impedance filler supply concentration:Acoustic enhancement materials depend on specialized polymer compounding capabilities concentrated among vertically integrated manufacturers.
- Silicone durometer limitations:Softer catheter variants for neurology applications sacrifice tensile strength, restricting placement in high-flow vascular environments.
Strategic Opportunities
- Outpatient nerve block expansion:Ambulatory surgery centers in Germany and France are adopting ultrasound-guided regional anesthesia protocols, opening volume outside tertiary hospital capture.
- Multi-lumen cardiac configurations:Simultaneous pressure monitoring and medication delivery capabilities command premium positioning in electrophysiology suites.
- ISO 13485 certification arbitrage:Quality system harmonization across notified bodies enables manufacturers to leverage single audits for multiple regulatory jurisdictions.
Industry Challenges
- Acoustic filler biocompatibility validation:Evolving ISO 10993 interpretation for embedded microbubble materials extends preclinical testing timelines.
- Polymer compounding talent scarcity:Specialized formulation chemists with ultrasound impedance matching expertise command compensation premiums that strain mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Echogenic Catheters Market |
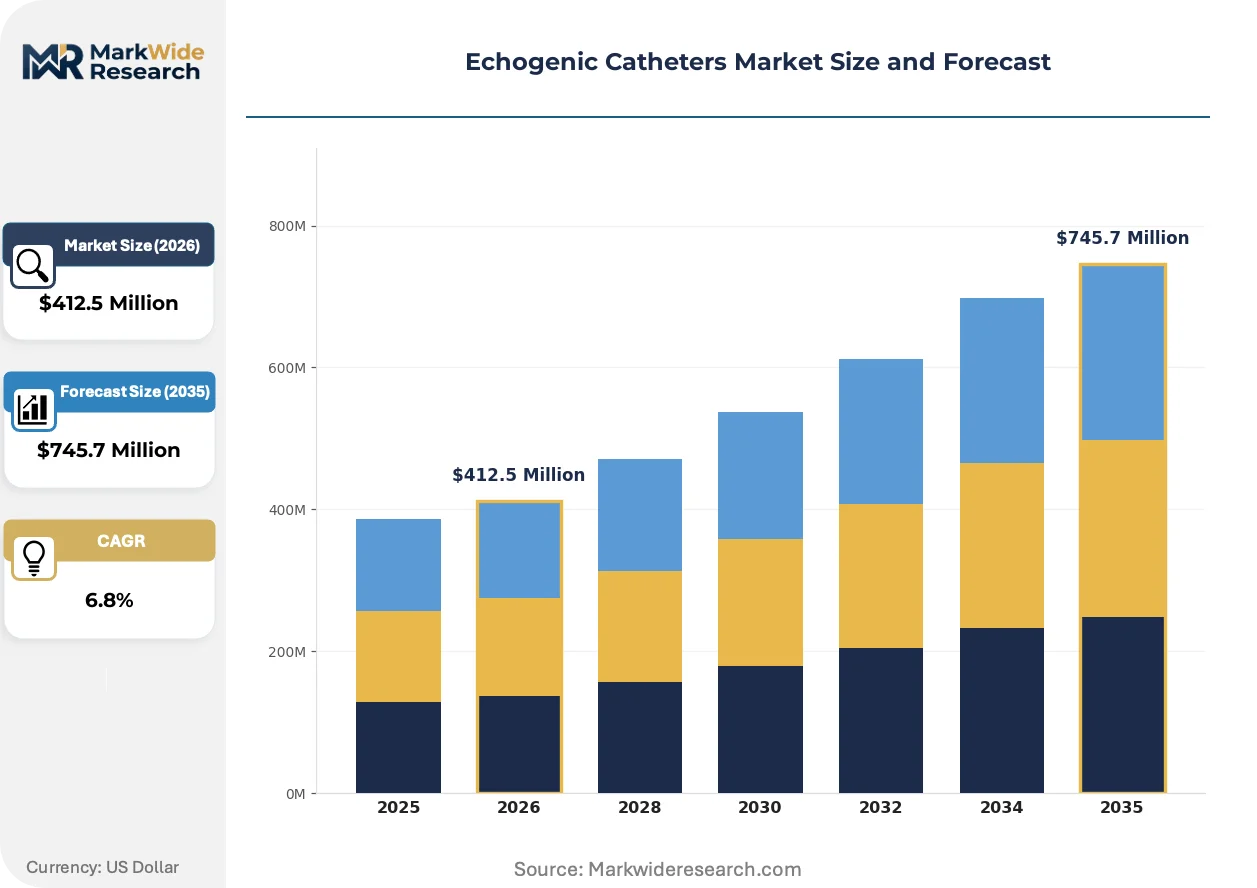
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen Catheters, Double-Lumen Catheters, Multi-Lumen Catheters, Accessory Catheters Application: Cardiology, Neurology, Anesthesia, Vascular End User: Hospitals, Clinics, Surgical Centers, Home Healthcare Material: Polyurethane, Polyvinyl Chloride, Silicone, Others |
| Companies Covered | B. Braun, Teleflex, Smith & Nephew, Argon Medical Devices, Pajunk GmbH, Epimed, Boston Scientific Corporation, Medtronic, CooperSurgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Echogenic Catheters Market Shifts & Advancements
Acoustic enhancement technologies are fragmenting into application-specific configurations, with manufacturers abandoning universal catheter platforms in favor of purpose-built designs for cardiac, anesthesia, and neurology verticals.
Composite polymer layers containing barium sulfate or tungsten-loaded matrices are modularizing echogenic catheter construction, enabling acoustic engineers to tune impedance mismatch independently of mechanical properties. Anesthesia departments in United States academic medical centers are piloting these configurable platforms for brachial plexus blocks. The technology is modularizing supplier-manufacturer relationships, as coating specialists now deliver acoustic enhancement as a discrete subassembly rather than integrated device production.
EU MDR clinical evidence requirements for Class IIa devices are compressing European market entry timelines, with notified bodies demanding prospective performance data for novel surface technologies. Manufacturers with legacy technical files under the Medical Device Directive retain transitional market access while new entrants face extended validation cycles. Cardiac catheter suppliers are responding by prioritizing FDA clearance first, deferring European commercialization until MDR precedent accumulates.
Hospital value analysis committees are unbundling catheter procurement from traditional distributor bundles, negotiating direct contracts with manufacturers for high-volume echogenic lines. Integrated delivery networks in the United States are consolidating purchasing across member hospitals to extract volume discounts. This concentration is most visible in interventional cardiology suites, where standardized tip visualization specifications reduce supplier count to two or three contracted vendors per network.
Echogenic Catheters Market Segmentation
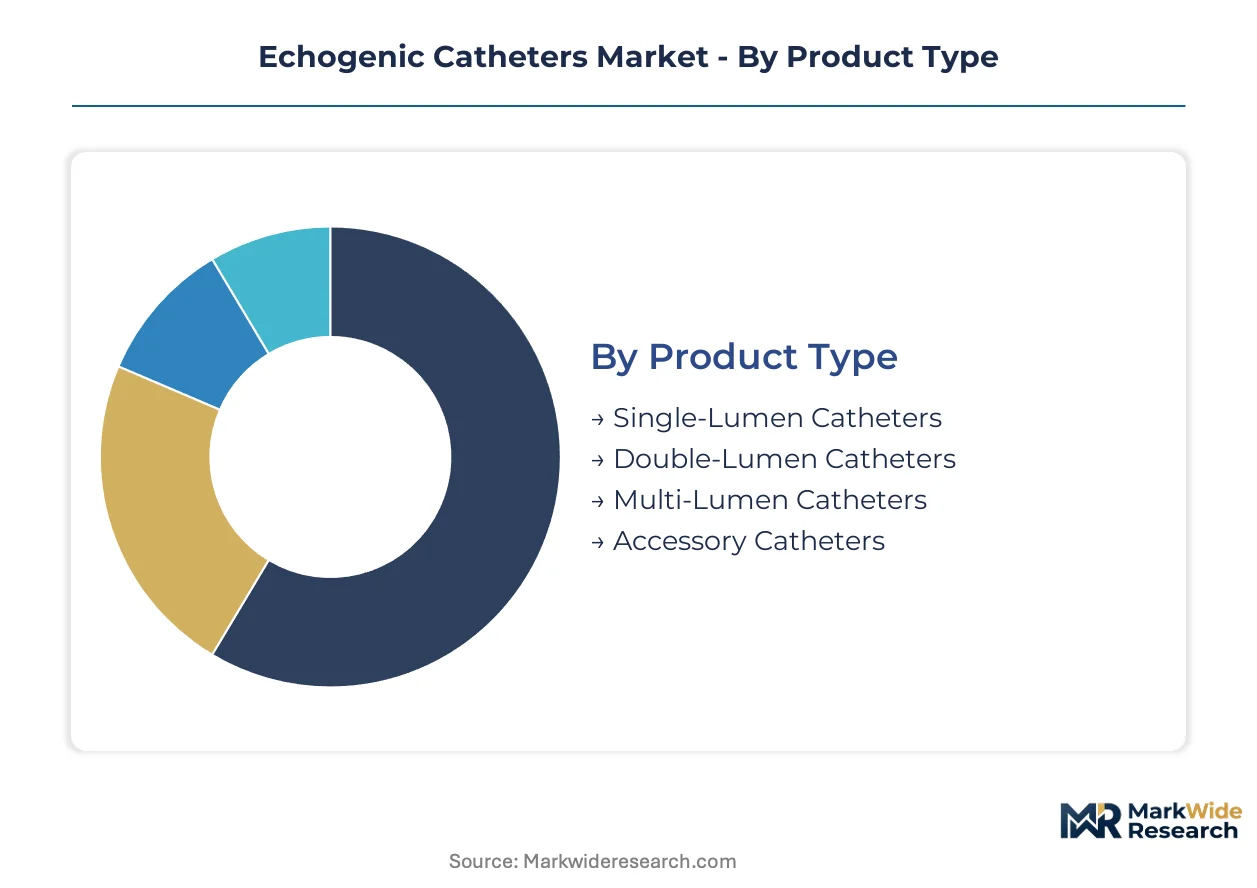
Product configuration, clinical application, and material composition determine procurement patterns and margin structures across echogenic catheter supply chains. Manufacturers tune acoustic enhancement features to procedural requirements, creating distinct competitive arenas within each segment boundary.
Product Type:
Single-lumen configurations dominate procedural volumes while multi-lumen systems capture premium positioning in high-acuity settings.
- Single-Lumen Catheters:Standardized designs incorporate embedded microbubbles or dimpled surfaces for ultrasound visibility during peripheral nerve blocks. Anesthesia departments in United States academic medical centers drive replacement volumes through high-frequency line placements.
- Double-Lumen Catheters:Dual-channel construction enables simultaneous infusion and aspiration in cardiac electrophysiology suites. Demand concentrates in tertiary hospitals where simultaneous pressure monitoring and medication delivery reduce line exchanges.
- Multi-Lumen Catheters:Three to five independent lumens support complex infusion protocols in cardiac intensive care units.
- Accessory Catheters:Specialized introducers and exchange systems complete echogenic catheter kits for bundled procurement.
Mature deployment sits with single-lumen systems. Newer deployment is concentrated in multi-lumen configurations.
Application:
Clinical specialization fragments demand across procedural domains with distinct imaging requirements and reimbursement profiles.
- Cardiology:Electrophysiology suites require tip visualization for transseptal punctures and ablation catheter navigation. United States integrated delivery networks standardize specifications across member hospitals, compressing vendor lists to contracted incumbents.
- Neurology:Softer durometer silicone variants reduce nerve trauma during prolonged indwelling use. European MDR clinical evidence requirements extend validation timelines for novel surface technologies entering this risk-sensitive segment.
- Anesthesia:Ultrasound-guided regional anesthesia protocols expand volumes in ambulatory surgery centers.
- Vascular:Central line placement bundles mandate real-time catheter visualization in tertiary hospitals.
Cardiology commands the steepest expansion trajectory as interventional suites upgrade imaging infrastructure.
End User:
Procurement authority concentrates in institutional buyers with volume leverage and standardized protocols.
- Hospitals:Tertiary centers with interventional cardiology suites anchor demand through bundled purchasing agreements. Hospital value analysis committees unbundle catheter procurement from distributor relationships, negotiating direct manufacturer contracts.
- Clinics:Outpatient facilities adopt ultrasound-guided access for cost-efficient procedural migration.
- Surgical Centers:Ambulatory settings in Germany and France pilot regional anesthesia protocols outside hospital capture.
- Home Healthcare:Extended indwelling applications favor softer silicone formulations for patient tolerance.
Contracted procurement sits with hospital systems. Volume growth is accelerating in surgical centers.
Material:
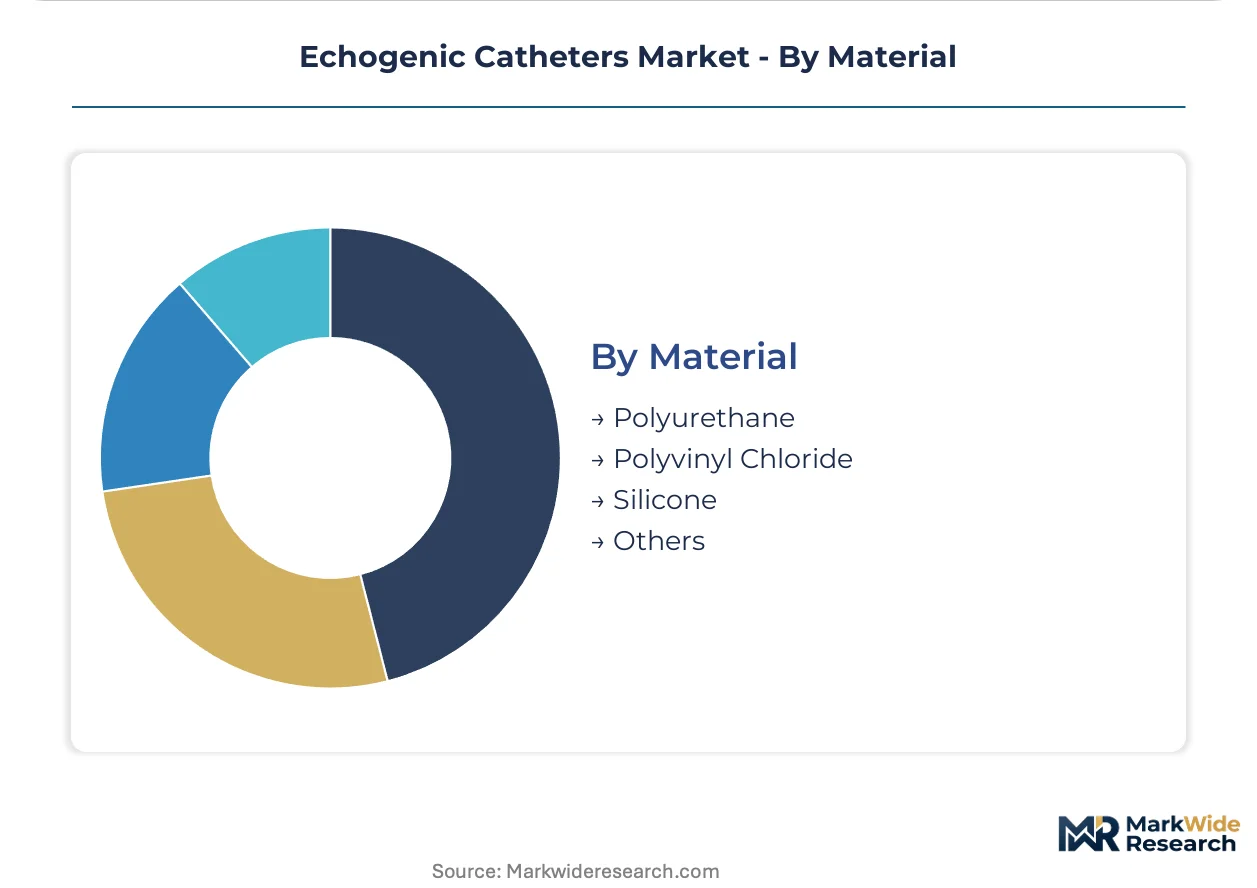
Mechanical properties and acoustic impedance characteristics drive material selection for specific vascular and neurological applications.
- Polyurethane:Segmented formulations deliver tensile strength and thromboresistance for high-flow vascular environments. Cardiac intensive care units sustain replacement demand through reduced catheter-related thrombosis rates.
- Silicone:Lower durometer variants minimize nerve trauma in neurology applications requiring prolonged indwelling periods.
- Polyvinyl Chloride:Cost-positioned alternatives serve standard access procedures with shorter dwell times.
- Others:Composite polymer layers with barium sulfate or tungsten-loaded matrices enable impedance tuning independent of mechanical properties.
Polyurethane anchors vascular applications. Silicone is gaining share fastest in neurology and home care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate catheter manufacturing operations serving North American hospital procurement networks. These zones offer tariff advantages and FDA-aligned quality infrastructure that accelerate time-to-market for acoustic-enhanced vascular access devices.
United States
Integrated delivery networks in Texas and Florida standardize echogenic catheter specifications across member hospitals, compressing vendor lists to contracted incumbents. FDA's updated 510(k) predicate device policy for echogenic coatings accelerates clearance timelines for manufacturers with established acoustic filler biocompatibility data. Minneapolis-St. Paul anchors polymer compounding expertise for high-impedance filler formulations.
Germany
Teleflex anchors direct hospital contracting in Baden-Württemberg and Bavaria, where MDR notified body capacity constraints create months-long approval queues favoring established technical files. EU MDR clinical evidence requirements for Class IIa devices extend validation timelines for novel surface technologies entering the European market. The Rhine-Main cluster concentrates catheter extrusion capabilities for cardiac electrophysiology applications.
France
Ambulatory surgery centers in Île-de-France and Auvergne-Rhône-Alpes pilot ultrasound-guided regional anesthesia protocols outside traditional hospital capture. ANSM interpretation of biocompatibility testing for acoustic filler materials determines whether next-generation echogenic formulations gain regulatory traction. The Lyon-Grenoble corridor hosts specialized polymer research institutes supporting impedance-matching development.
Japan
PMDA marketing authorization requirements for modified surface devices create parallel validation tracks for echogenic coating technologies. Tokyo-Osaka medical device clusters prioritize silicone durometer formulations for neurology applications requiring prolonged indwelling periods. METI funding programs support domestic catheter manufacturers developing composite polymer layers with barium sulfate matrices.
India
CDSCO medical device rules implementation is repositioning cost-of-entry calculus for catheter manufacturers seeking import licenses or local manufacturing approvals. Maharashtra and Gujarat medical device parks attract contract manufacturing organizations serving European and North American OEMs. BIS standards alignment with ISO 13485 enables quality system harmonization for export-oriented production.
Echogenic Catheters Market Competitive Landscape
United States producers anchor the premium-tier segment through integrated delivery network contracting; German and Swiss specialists hold regulatory-compliant positioning in European cardiac catheter markets. The vendor base fragments across three strategic tiers: vertically integrated polymer compounders, coating technology licensors, and regional contract manufacturers. Competitive moves concentrate on M&A for acoustic filler capabilities and strategic partnerships for MDR technical file access.
Among diversified medical technology conglomerates, B. Braun and Teleflex exemplify the integrated-manufacturer archetype, while Boston Scientific Corporation occupies a position within the cardiac-focused specialization tier. These entities represent distinct approaches to absorbing compliance costs—B. Braun through captive polymer compounding operations, Teleflex through established European technical files, and Boston Scientific through electrophysiology suite channel dominance. Their collective positioning illustrates how regulatory geography and manufacturing depth determine sustainable competitive advantage in acoustic-enhanced catheter supply.
| Leading Market Players |
|---|
| B. Braun |
| Teleflex |
| Smith & Nephew |
| Argon Medical Devices |
| Pajunk GmbH |
| Epimed |
| Boston Scientific Corporation |
| Medtronic |
| CooperSurgical |
| Others |
Supply & Pricing Matrix
Polyether polyol price indices cascade through echogenic catheter supply chains, compressing margins for non-integrated manufacturers while vertically integrated compounders absorb volatility across premium, standard, and economy pricing tiers.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to acoustic filler formulations held in regional compounding inventory, while spot market catheter lots trade at discounts when hospital procurement consortia delay contract renewals. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and acoustic performance validation depth. Cost compression in the standard tier is intensifying because MDR technical file preparation expenses are being amortized across narrower volume bases. Ambulatory surgery centers exhibit highest price sensitivity due to limited capital equipment budgets, while cardiac electrophysiology suites demonstrate lowest sensitivity given bundled reimbursement for visualization-guided procedures.
Supply Chain Analysis
Direct-to-hospital contracting channels handle integrated delivery network demand in the United States, while distributor-mediated routes serve fragmented clinic and surgical center procurement in Germany and France. Polymer compounding concentrates in the United States, Germany, and Japan, with Costa Rica and Puerto Rico hosting final device assembly for North American markets. High-impedance acoustic fillers draw from specialized tungsten and barium sulfate suppliers concentrated in German industrial clusters. Single-source vulnerability in notified body capacity for MDR conformity assessments creates approval bottlenecks that strain inventory planning. Distribution runs through hospital value analysis committees that unbundle catheter procurement from traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The echogenic catheter market operates as a cost-of-compliance story where EU MDR clinical evidence requirements for Class IIa devices erect barrier-to-entry moats favoring incumbents with legacy technical files.
For Market Incumbents: Lock in hospital procurement consortia through multi-year direct contracting that bundles acoustic filler customization with technical file maintenance services. Deepen backward integration into polymer compounding to insulate margin structures from polyether polyol price volatility. Prioritize capacity addition in Costa Rica medical device special economic zones to exploit tariff advantages and FDA-aligned quality infrastructure. For New Entrants and Emerging Players: Launch via ambulatory surgery center distribution partnerships in Germany and France where ultrasound-guided regional anesthesia protocols expand outside hospital procurement capture. Target outpatient nerve block applications as the most penetrable segment given lower regulatory validation thresholds and faster purchasing cycles. Pursue ISO 13485 certification arbitrage through single-audit quality system harmonization across multiple notified body jurisdictions. For Investors and Strategic Acquirers: The window for entry favors polymer compounding specialists with captive acoustic filler formulation capabilities and established biocompatibility testing histories. Long-term viability hinges on MDR technical file accumulation that accelerates European market access velocity. Watch notified body interpretation evolution for embedded microbubble materials as the signal indicating whether next-generation echogenic formulations gain regulatory traction or face extended premarket validation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Accumulation | Legacy documentation under Medical Device Directive accelerates European market entry against new entrant queues. |
| Acoustic Filler Backward Integration | Captive polymer compounding absorbs REACH and RoHS compliance costs without outsourcing critical material qualification. |
| Hospital System Direct Contracting | Integrated delivery network agreements in Texas and Florida compress vendor lists to two or three contracted incumbents. |
| Composite Polymer Layer Development | Barium sulfate and tungsten-loaded matrices enable impedance tuning independent of mechanical property constraints. |
| Ambulatory Surgery Center Partnership | Regional anesthesia protocol adoption in Île-de-France opens volume outside tertiary hospital procurement capture. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR notified body technical file registries, and ISO 13485 certification records, complemented by interviews with interventional cardiologists, anesthesia department heads, hospital purchasing committee members, and polymer compounding operations directors. Secondary validation drew from hospital procurement database extracts, GPO contract filings, and customs trade data for high-impedance filler materials. Bottom-up demand modeling triangulated against top-down market sizing across product configuration, clinical application, material composition, and end-user facility type.
Cross-referencing historical catheter placement volume trends against expert panel input on ultrasound infrastructure deployment yields projection trajectories across the analysis window. Segmentation dimensions modeled include lumen configuration, procedural specialty, polymer chemistry, and geographic regulatory cluster. CAGRs derive from weighted average of procedure volume elasticity, replacement cycle compression, and premium product mix shift assumptions. Forecast inputs incorporate notified body capacity constraints and acoustic filler supply concentration metrics.
Regulatory interpretation shifts, notified body approval queue extensions, and polymer raw material price volatility are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base-case assumptions regarding MDR implementation pace and hospital capital expenditure cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Europe Clear Aligners Market