
 Cavendish Banana Market | 2026-2036
Cavendish Banana Market Size, Share, and Industry Trends Forecast 2026-2036
Cavendish Banana Market Outlook
Pre-packaged bunch configurations in modified-atmosphere bags is shifting how European retailers source Cavendish bananas, reducing perishable waste while extending shelf presence. Dole Food Company leverages its refrigerated logistics network to sustain year-round supply consistency across Northern European markets. Chiquita Brands International anchors its competitive position through proprietary ripening technology that controls color-stage delivery to supermarket chains.
Cavendish bananas constitute a triploid AAA cultivar subgroup of Musa acuminata, propagated vegetatively through tissue culture to ensure genetic uniformity and disease-free planting material; the fruit delivers standardized sweetness profiles (18-22% total soluble solids) and peel reliability essential for industrial processing and fresh consumption. Fresh bananas dominate volume throughput but carry thinner margins due to perishability and freight sensitivity, whereas dried and puree segments concentrate margin pools where dehydration and aseptic processing create value-added shelf-stable formats. Food Industry procurement of frozen Cavendish bananas for smoothie manufacturing represents the fastest-growing end-user channel as beverage chains scale plant-based menu offerings.
The EU Plant Health Regulation and REACH framework govern phytosanitary entry requirements and pesticide residue thresholds for Cavendish imports into Europe, compelling exporters to adopt integrated pest management and certified tissue culture protocols to maintain market access. EFSA maximum residue level reviews periodically tighten allowable chemical treatments, directly shaping supplier compliance investments and sourcing geography decisions. Stakeholders must monitor evolving F-Gas Regulation constraints on refrigerated transport cooling systems, as logistics cost structures face restructuring from equipment replacement timelines and alternative refrigerant adoption requirements.
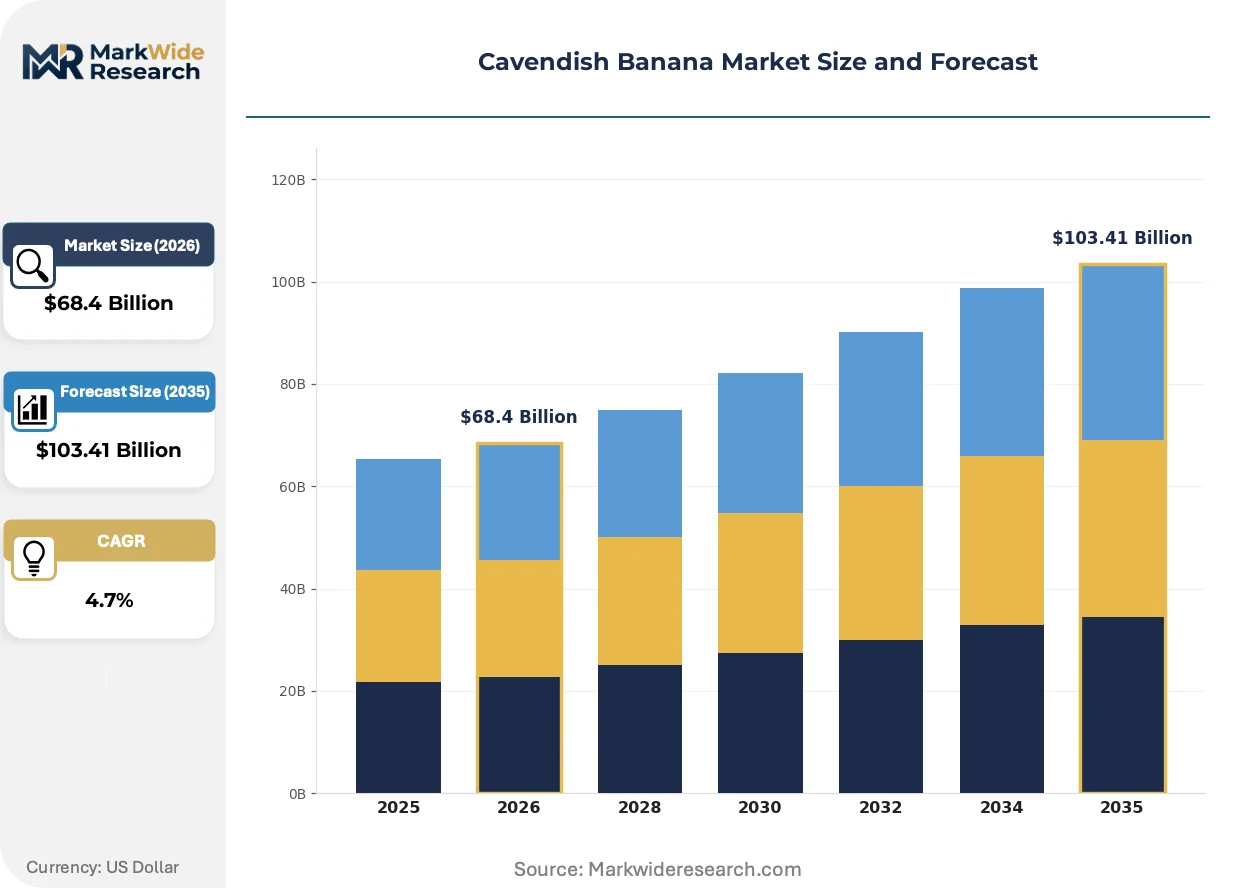
Market Dynamics
Modified-atmosphere packaging technology is compressing spoilage windows and rewiring procurement contracts between Latin American growers and European retail consortia.
Growth Catalysts
- Plant-based beverage manufacturing:Smoothie chains and dairy-alternative processors are scaling frozen Cavendish procurement as oat and almond bases require banana puree for texture standardization.
- EU Green Deal agricultural incentives:Carbon-border adjustment mechanisms favor certified low-emission supply chains, rewarding integrated pest management adoption in Costa Rica and Ecuador.
- Phytosanitary certification automation:Digital traceability platforms are collapsing pre-clearance timelines at Rotterdam and Hamburg port authorities.
Market Restraints
- Input cost volatility:Container freight rates and sulfur dioxide prices for controlled ripening chambers create margin compression for independent ripening operators.
- Supply concentration risk:Ecuador and Guatemala account for disproportionate fresh volume, exposing buyers to port congestion and labor action vulnerability.
- Regulatory friction:EFSA maximum residue level reviews tighten quarterly, forcing replanting cycles and agrochemical substitution costs on non-compliant farms.
Strategic Opportunities
- Underpenetrated processing markets:Poland and Romania show ripe conditions for aseptic puree facilities serving Central European baby food and bakery segments.
- Regulatory tailwind:REACH framework exemptions for biocontrol agents open substitution pathways away from synthetic fungicides in pre-export washing protocols.
- Channel innovation:Direct-to-foodservice platforms bypass traditional wholesale markets, capturing ripening-stage specification premiums from hotel and catering chains.
Industry Challenges
- Specialized ripening technician scarcity:Controlled atmosphere expertise lags behind facility expansion in Northern European distribution hubs.
- Capex intensity:F-Gas Regulation compliance demands full refrigeration fleet replacement, straining mid-scale logistics operators with 7-10 year equipment amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cavendish Banana Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Bananas, Dried Bananas, Frozen Bananas, Puree End User: Food Industry, Retailers, Exporters, Wholesale Packing Type: Boxed, Palletized, Loose, Bunches Distribution Channel: Direct Sales, Online Retail, Supermarkets, Farmers' Markets |
| Companies Covered | Reybanpac, Fyffes Group, Dole Food Company, Agroexport Carmita, Agroamerica, Chiquita Brands International, Grupo Noboa, GinaFruit S.A., Fresh Del Monte Produce Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cavendish Banana Market Strategic Shifts
Active packaging and precision ripening systems are compressing the gap between harvest maturity and retail-ready color stages, while regulatory chemistry restrictions force biological control adoption.
Ethylene-absorbing sachets integrated into modified-atmosphere bags are extending green-life by 4-8 days in ocean transit. German discount retailers are mandating this specification for private-label contracts. The technology is modularizing quality control responsibility away from centralized ripening centers toward primary packaging lines at source farms.
EFSA is accelerating reviews of post-harvest fungicides including thiabendazole and imazalil, with proposed MRL reductions of 30-50% for banana imports. Processing-dependent exporters face reformulation costs for washing tank protocols. Fresh segment suppliers in Colombia and Panama are pivoting toward hot water treatment and biocontrol coatings to maintain shelf-life performance.
Food manufacturers are consolidating procurement through annual volume tenders rather than spot-market purchases, compressing supplier rosters to three-to-five approved origins. This contract rationalization favors vertically integrated growers with in-house logistics. The shift is most pronounced in Netherlands-based dairy-alternative processors supplying Northern European retail chains.
Cavendish Banana Market Segmentation
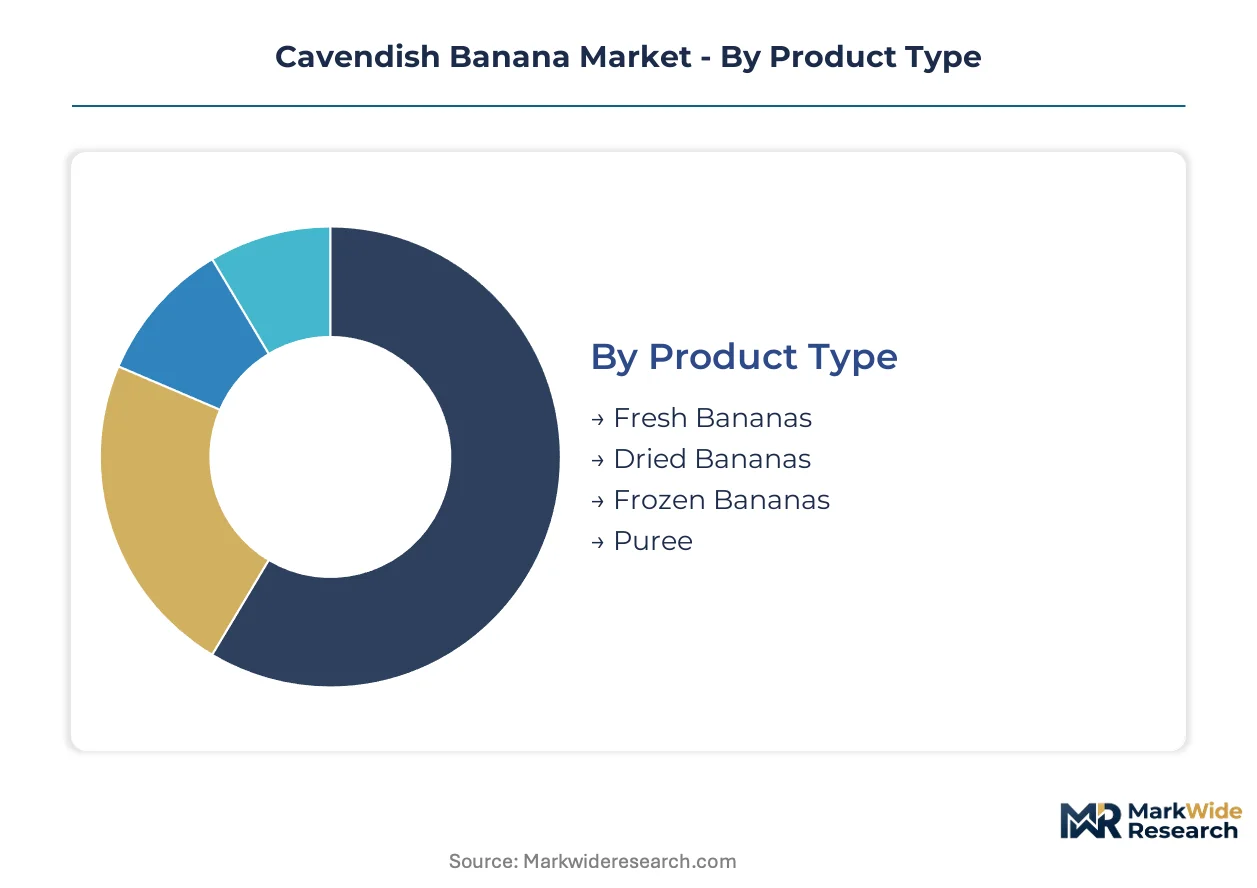
Cavendish banana segmentation reveals how value migrates from perishable fresh formats toward shelf-stable derivatives. Procurement patterns diverge sharply between industrial processors seeking specification-grade frozen inputs and retailers optimizing for color-stage delivery windows.
Product Type:
Integration depth separates standalone consumption formats from embedded industrial inputs requiring downstream processing infrastructure.
- Fresh Bananas:The AAA triploid cultivar delivers 18-22% total soluble solids and standardized peel reliability essential for retail color-stage protocols. German and Dutch supermarket chains concentrate procurement here, driving pre-packaged modified-atmosphere specifications that extend shelf presence while compressing spoilage windows.
- Frozen Bananas:Individually quick-frozen (IQF) segments and block-frozen purees serve smoothie manufacturing and plant-based dairy-alternative processors. Beverage chains scaling oat and almond bases require banana for texture standardization, concentrating demand in Netherlands-based dairy-alternative processors supplying Northern European retail.
- Dried Bananas:Dehydration creates value-added shelf-stable formats with concentrated margin pools. Snack food manufacturers and bakery segments in Poland and Romania represent emerging offtake channels.
- Puree:Aseptic processing delivers baby food and industrial bakery inputs. Central European processing capacity gaps present facility placement opportunities for aseptic puree operations.
Volume placements concentrate in Fresh Bananas; the faster expansion belongs to Frozen Bananas.
End User:
Cost tier stratification separates specification-intensive industrial buyers from price-sensitive wholesale intermediaries.
- Food Industry:Smoothie chains and plant-based beverage manufacturers drive frozen Cavendish procurement through annual volume tenders. Contract rationalization favors vertically integrated growers with in-house logistics and ripening-stage control capabilities.
- Retailers:German discount retailers mandate ethylene-absorbing sachet specifications for private-label contracts, modularizing quality control responsibility toward primary packaging lines at source farms.
- Exporters:Phytosanitary certification requirements under EU Plant Health Regulation tighten import protocols, compelling integrated pest management adoption in Costa Rica and Ecuador.
- Wholesale:Traditional wholesale markets face displacement from direct-to-foodservice platforms capturing ripening-stage specification premiums from hotel and catering chains.
Margin concentration sits with Food Industry; volume throughput dominates Retailers.
Packing Type:
Supply concentration patterns favor palletized configurations for industrial scale while loose formats serve fragmented wholesale channels.
- Palletized:Containerized ocean freight optimization for Rotterdam and Hamburg port authorities. Digital traceability platforms collapse pre-clearance timelines for palletized shipments meeting EU Plant Health Regulation documentation requirements.
- Boxed:Modified-atmosphere bag integration at source farms for German retail private-label contracts. Ethylene-absorbing sachet technology extends green-life by 4-8 days in transit.
- Bunches:Pre-packaged configurations reduce perishable waste in Northern European distribution hubs. Chiquita Brands International anchors positioning through proprietary ripening technology controlling color-stage delivery.
- Loose:Farmers' market and spot-market procurement with minimal processing intervention. Margin compression from freight sensitivity and perishability exposure limits commercial significance.
Industrial procurement concentrates in Palletized; retail differentiation favors Bunches.
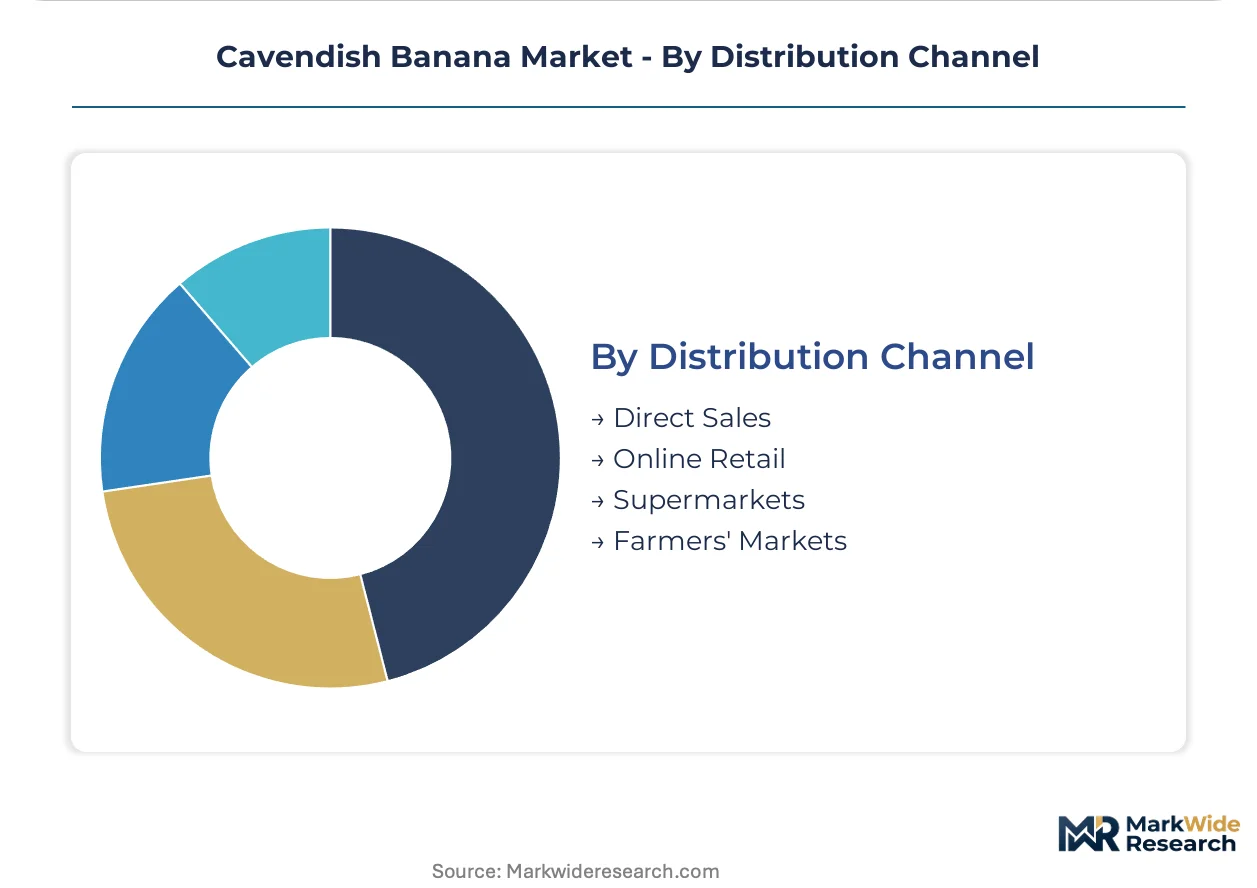
Distribution Channel:
Maturity gradients separate established supermarket infrastructure from emerging digital direct channels.
- Supermarkets:Dole Food Company leverages refrigerated logistics networks to sustain year-round supply consistency across Northern European markets. F-Gas Regulation constraints on cooling systems reshape logistics cost structures through equipment replacement timelines.
- Direct Sales:Foodservice platforms bypass traditional wholesale markets, capturing specification premiums through ripening-stage precision. Hotel and catering chains consolidate procurement through approved vendor rosters.
- Online Retail:Subscription-based fresh delivery models in German urban centers. Cold-chain integrity requirements limit geographic reach to dense population corridors.
- Farmers' Markets:Localized spot-market transactions with minimal quality standardization. Limited scale constrains participation from major integrated growers.
Volume flows through Supermarkets; channel innovation accelerates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Costa Rica's Free Trade Zone Regime concentrates Cavendish banana processing infrastructure near Limón, attracting vertically integrated exporters seeking tariff advantages into EU markets. Ecuador's Special Economic Zones anchor Latin American production gravity for European-bound shipments. Guatemala's Zona Libre de Industria y Comercio enables competitive re-export positioning.
Ecuador
Guayaquil and Machala port clusters handle the majority of European-bound Cavendish volume, driven by year-round production consistency and integrated pest management adoption. The country's national phytosanitary regulator enforces EU Plant Health Regulation alignment through certified tissue culture protocols. El Oro Province plantations concentrate backward integration into refrigerated logistics networks serving Rotterdam direct routes.
Costa Rica
Smoothie manufacturing demand from Netherlands-based dairy-alternative processors drives frozen Cavendish procurement through Puntarenas and Limón export terminals. The country's environmental ministry administers carbon-border adjustment documentation under EU Green Deal frameworks. Sarapiquí and Atlantic slope growing regions host biocontrol coating adoption for post-harvest fungicide substitution.
Guatemala
Escuintla and Suchitepéquez departments supply German discount retailers through modified-atmosphere packaging specifications with ethylene-absorbing sachet integration. The national agricultural regulator coordinates EFSA maximum residue level compliance through hot water treatment facility investments. Puerto Quetzal container terminals face congestion vulnerability from concentrated export timing.
Colombia
Urabá Gulf banana zone serves emerging Central European processing markets through aseptic puree investments targeting Polish baby food manufacturers. The national food safety authority accelerates biocontrol agent registration under REACH framework exemption pathways. Antioquia and Magdalena departments pivot from thiabendazole-dependent washing protocols toward integrated pest management systems.
Germany
Hamburg and Bremerhaven port authorities host digital traceability platform deployment collapsing pre-clearance timelines for Latin American Cavendish arrivals. The Federal Office for Agriculture and Food enforces F-Gas Regulation constraints on refrigerated transport cooling system replacement schedules. North Rhine-Westphalia ripening centers face technician scarcity against controlled atmosphere facility expansion.
Cavendish Banana Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Cavendish banana supply chain, creating a tiered structure where scale-driven integrated growers hold procurement contract advantages. The vendor base separates into three strategic archetypes: vertically integrated plantation-to-port operators, specialized ripening and logistics service providers, and regional cooperative export associations. Competitive moves concentrate on backward integration into tissue culture nursery operations and strategic port capacity partnerships.
Within the integrated plantation-to-port tier, Dole Food Company and Chiquita Brands International exemplify scale-driven archetypes with captive refrigerated logistics networks. Fyffes Group occupies a position representing European distribution-focused specialists. These three entities anchor competitive positioning through proprietary ripening technology and year-round supply consistency capabilities.
| Leading Market Players |
|---|
| Reybanpac |
| Fyffes Group |
| Dole Food Company |
| Agroexport Carmita |
| Agroamerica |
| Chiquita Brands International |
| Grupo Noboa |
| GinaFruit S.A. |
| Fresh Del Monte Produce Incorporated |
| Others |
Value Chain & Pricing Dynamics
German discount retailer procurement concentration anchors contract-based long-term offtake pricing with annual volume tenders favoring vertically integrated growers over spot-market intermediaries. This buyer archetype consolidation compresses margin pools for independent ripening operators while rewarding scale-driven plantation-to-port operators with logistics control.
Pricing Analysis
Short lead-time premiums attach to ripening-stage precision deliveries for hotel and catering chains bypassing traditional wholesale markets. Three-tier pricing structure across premium color-stage specification, standard retail-ready, and economy-grade spot inventory reflects differentiation by certification grade and volume scale. Cost compression in mid-tier contract renewals intensifies as F-Gas Regulation compliance costs restructure refrigerated logistics economics. Price sensitivity concentrates among independent ripening operators lacking backward integration into tissue culture nursery operations.
Supply Chain Analysis
Single-source vulnerability sits with Ecuador and Guatemala handling disproportionate fresh volume for European-bound shipments. Raw material dependencies center on sulfur dioxide for controlled ripening chambers, ethylene-absorbing sachet technology, and certified disease-free tissue culture planting stock. Port congestion at Puerto Quetzal and labor action exposure in Guayaquil clusters create logistics chokepoint risk. Distribution runs through Rotterdam and Hamburg as primary Northern European hubs for re-export across the continent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
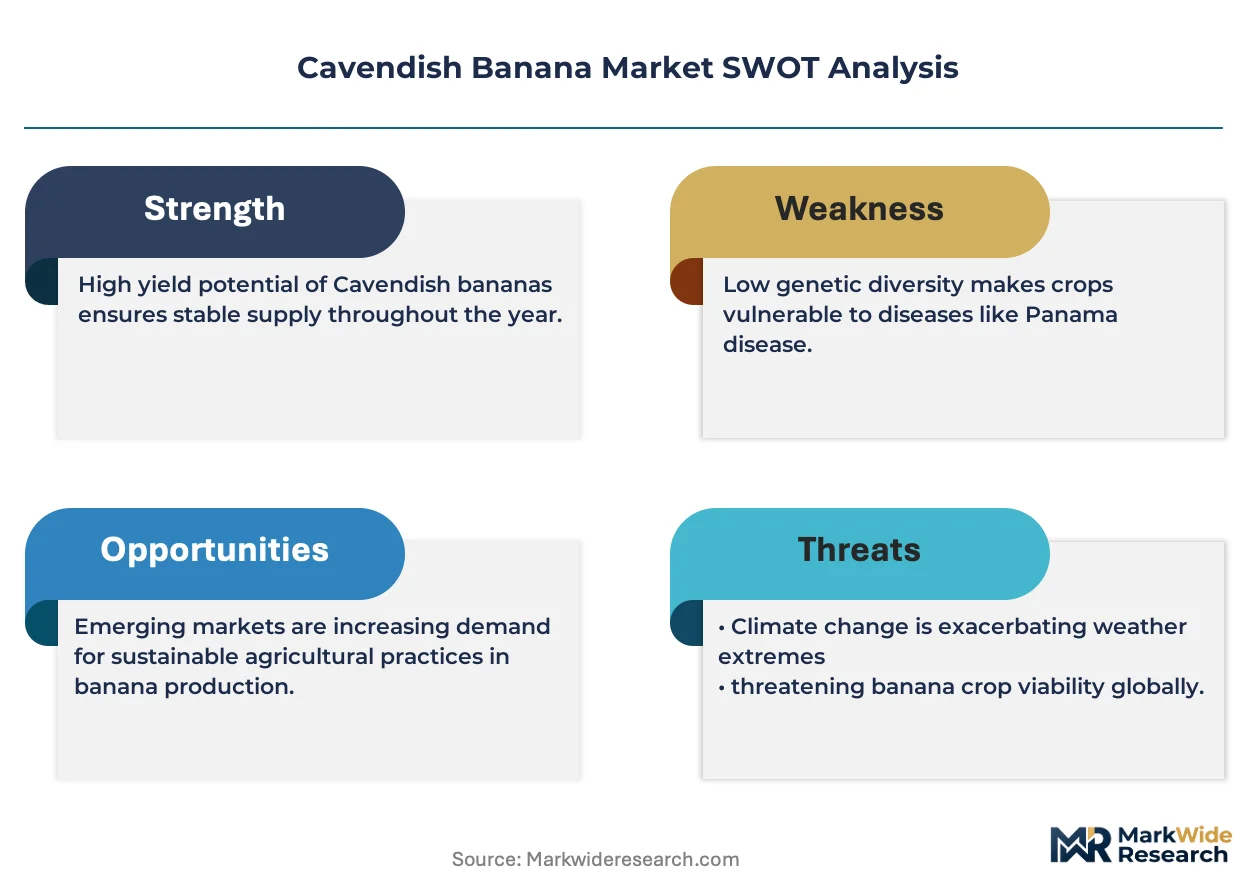
The Cavendish banana market operates as a cost-of-compliance story where EU Plant Health Regulation phytosanitary certification requirements erect barrier-to-entry moats favoring incumbent integrated pest management adopters over non-compliant challengers.
For Market Incumbents: Lock in multi-year procurement contracts with Netherlands-based dairy-alternative processors before REACH framework biocontrol agent exemptions mature into mandatory substitution pathways. Defend margin position by accelerating hot water treatment facility investments ahead of EFSA maximum residue level reviews tightening thiabendazole and imazalil thresholds. Prioritize technician training pipelines for controlled atmosphere expertise against facility expansion in North Rhine-Westphalia ripening centers.
For New Entrants and Emerging Players: Direct-to-foodservice platforms offer the most penetrable route for capturing ripening-stage specification premiums from hotel and catering chains consolidating procurement through approved vendor rosters. White-space targets include aseptic puree facility placement in Poland and Romania serving Central European baby food and bakery segments. Go-to-market positioning should emphasize carbon-border adjustment documentation compliance under EU Green Deal frameworks to access tariff-advantaged Free Trade Zone channels.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated plantation-to-port operators with captive refrigerated logistics networks and certified tissue culture protocols. Long-term viability over the coming decade rests on regulatory compliance infrastructure rather than commodity scale alone. Watch EFSA maximum residue level review acceleration timelines as the signal indicating consolidation pressure on independent growers lacking biocontrol substitution capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tissue Culture Nurseries | Captive disease-free planting stock supply secures EU Plant Health Regulation compliance against phytosanitary entry barriers. |
| Hot Water Treatment Facility Investment | Biocontrol substitution ahead of EFSA reviews protects market access as synthetic fungicide thresholds tighten. |
| Digital Traceability Platform Deployment | Pre-clearance timeline compression at Rotterdam and Hamburg port authorities accelerates inventory turns. |
| Direct-to-Foodservice Channel Development | Ripening-stage specification premiums from hotel and catering chains bypass wholesale margin compression. |
| F-Gas Regulation Compliant Fleet Replacement | Alternative refrigerant adoption ahead of equipment replacement deadlines preserves logistics cost structures. |
Study Parameters
Independent corroboration across plantation operations managers, refrigerated logistics coordinators, and EU regulatory affairs specialists underwrites the qualitative findings presented in this study. Primary interviews with ripening facility technicians, Netherlands-based dairy-alternative processor procurement leads, and German discount retailer category buyers combined with secondary validation from customs and trade data, EFSA maximum residue level review documentation, and EU Plant Health Regulation implementation guidance. Bottom-up volume modeling across product type, end user, and distribution channel segments triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition across the projection horizon disaggregates volume expansion drivers between fresh consumption growth and frozen processing demand acceleration. Segmentation dimensions modeled include product format, end-use application, packaging configuration, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy intervention effects, with forecast inputs incorporating F-Gas Regulation equipment replacement timelines and REACH framework biocontrol agent registration pathways.
The model holds under stable EU Plant Health Regulation enforcement intensity; deviation in EFSA maximum residue level review acceleration or carbon-border adjustment mechanism expansion would shift supply geography decisions and compliance investment requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market