
 Global Banana Market | 2026-2036
Global Banana Market Size, Share, and Industry Trends Forecast 2026-2036
Global Banana Market Analysis
The price gap between premium organic bananas and conventional commodity fruit is hardening as certification costs and cold-chain investments accumulate at the top tier. Dole Food Company, Inc. leverages its integrated plantation-to-port infrastructure across Latin America to sustain volume leadership in mass-market supply. Chiquita Brands International, LLC differentiates through branded packaging and ripening technology that controls retail shelf life. Fresh Del Monte Produce Inc. competes by anchoring year-round availability through multi-hemisphere sourcing.
Bananas are tropical berry fruits of the genus Musa, harvested green at 75-80% maturity for transport and gassed with ethylene to trigger controlled ripening before retail sale; their primary commercial purpose is to deliver a low-cost, high-potassium fresh fruit with extended post-harvest handling tolerance. Cavendish cultivars dominate global trade volume due to disease resistance and uniform shipping geometry, while the food service segment leads value capture through contracted ripening programs and portion-controlled formats. Distribution through wholesale channels supports margin pools in emerging markets where supermarket penetration remains incomplete.
The EU F-Gas Regulation restricts hydrofluorocarbon use in refrigerated transport serving European import corridors, while USDA organic certification and ISO 22000 food safety frameworks govern market access for premium-tier suppliers. India's FSSAI and BIS standards are tightening pesticide residue limits on imported fruit, redirecting sourcing toward certified low-chemical operations. Stakeholders must monitor phytosanitary rule changes in destination countries and assess backward integration into ripening infrastructure as a defensive capability.
Market Dynamics
Ethylene-based ripening infrastructure is concentrating procurement power among food service operators with captive ripening chambers, compressing margins for wholesalers without controlled-atmosphere capabilities.
Growth Catalysts
- Plant-based menu expansion:Food service chains in the United States and United Kingdom are locking in multi-year banana supply contracts for smoothie programs and dairy alternatives.
- EU F-Gas Regulation:Cold-chain operators are retrofitting refrigerated transport with natural refrigerants, creating certification premiums for compliant Latin American exporters.
- Processing hub development:India's FSSAI-mandated residue testing is redirecting import volumes toward certified low-chemical plantations in Ecuador and Guatemala.
Market Restraints
- Fuel and fertilizer input volatility:Bunker fuel surcharges and synthetic nitrogen price spikes are eroding plantation operating margins in Central America.
- Single-variety genetic vulnerability:Global trade dependence on Cavendish cultivars exposes supply chains to Panama disease Tropical Race 4 spread.
- Phytosanitary friction:India's BIS pesticide maximum residue limits are disqualifying conventional operations lacking integrated pest management documentation.
Strategic Opportunities
- Underpenetrated Indian retail cold chain:Supermarket penetration remains below fifteen percent, creating first-mover advantage for ripening-as-a-service providers in Mumbai and Bangalore.
- EU Green Deal agricultural import standards:Deforestation-free supply chain mandates are creating premium tier access for certified sustainable operations.
- Bioplastic packaging convergence:Banana fiber extraction and starch-based films are merging with mechanical engineering advances to displace polyethylene in retail bags.
Industry Challenges
- Ripening technician skill scarcity:Controlled-atmosphere chamber operation requires specialized training unavailable in secondary Vietnamese and Philippine logistics hubs.
- Organic certification timeline compression:USDA and EU organic conversion periods lock land for thirty-six months before premium pricing eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Banana Market |
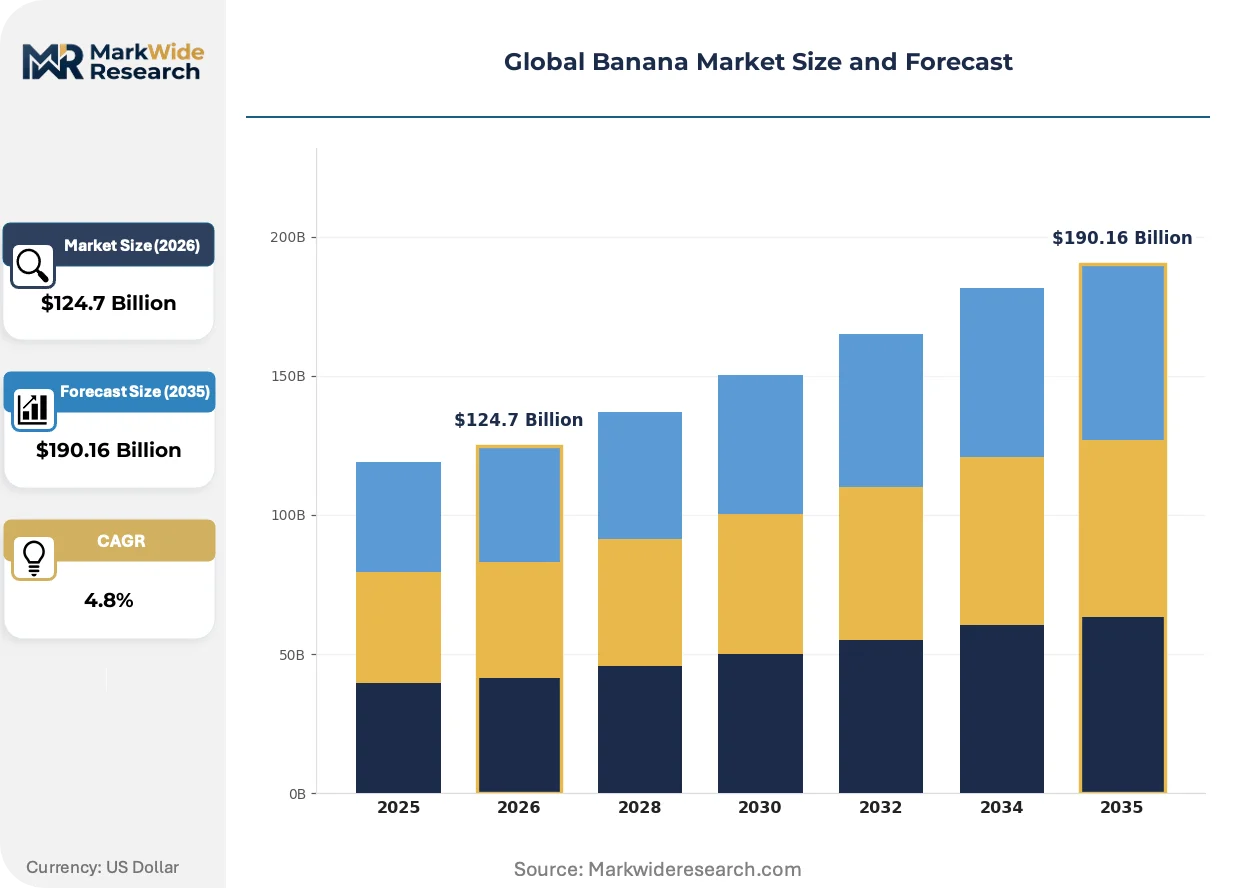
| Market Size in 2026 | $124.7 Billion |
| Market Size in 2035 | $190.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cavendish, Red Dwarf, Apple Banana, Lady Finger Distribution Channel: Supermarkets, Online Retail, Wholesale, Farmer's Markets Packaging Type: Bunches, Cartons, Bulk, Bags End User: Food Service, Retail Consumers, Food Manufacturing, Exporters |
| Companies Covered | Fyffes plc, Corporación Bananera Nacional S.A., Dole Food Company, Inc., Banacol S.A., Turbana S.A., Chiquita Brands International, LLC, Grupo Noboa S.A., Agroamerica Holdings, Inc., Fresh Del Monte Produce Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Banana Market Emerging Trajectories
Controlled-atmosphere technology and digital monitoring systems are compressing post-harvest loss rates while regulatory pressure on refrigerant chemistry accelerates equipment replacement cycles across export corridors.
Ethylene generator technology with sensor-driven dosing is modularizing ripening room configurations. Mid-sized food service distributors in Germany and the Netherlands are adopting container-scale units for just-in-time ripening. This distributed architecture is modularizing capital deployment away from centralized port facilities toward urban distribution nodes.
EU F-Gas Regulation phase-down schedules are forcing refrigerated transport operators to abandon hydrofluorocarbon systems before 2030. Equipment retrofit costs are concentrating fleet ownership among capitalized logistics groups with bond-market access. Latin American exporters serving Rotterdam and Hamburg are prioritizing carrier partnerships with natural refrigerant compliance.
Contracted ripening programs are displacing spot-market purchasing among European retail chains. Dedicated ripening agreements with fixed volume commitments are replacing auction-based procurement in the United Kingdom and France. This shift is most visible in the German discount retail segment, where Aldi and Lidl operations now specify ripening-stage delivery windows in supply agreements.
Global Banana Market Segmentation
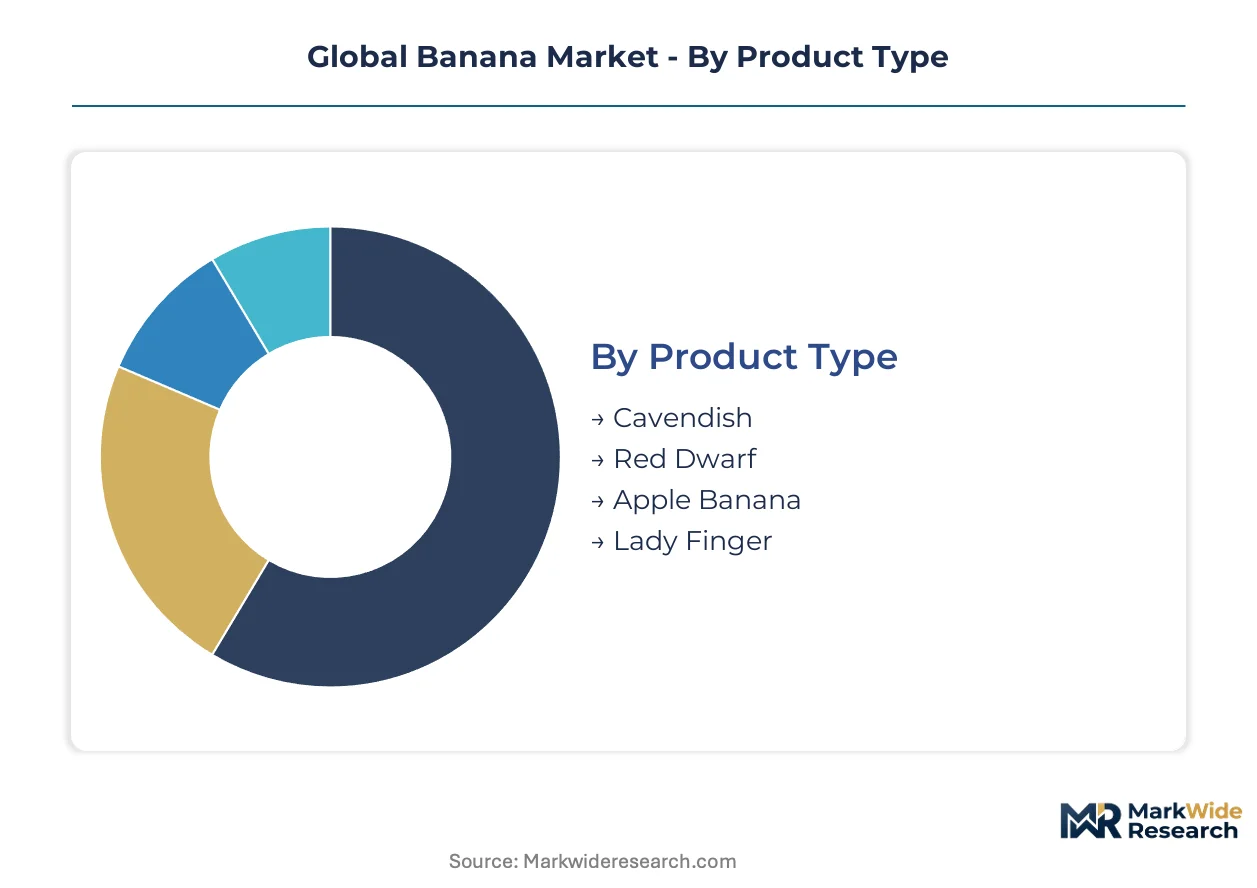
Banana market segmentation tracks how cultivar selection, channel infrastructure, and packaging format intersect with ripening technology investments and regulatory compliance requirements. Buyers in each category face distinct cold-chain cost structures and shelf-life specifications that determine procurement patterns.
Product Type:
Cultivar choice determines transport geometry, disease susceptibility, and ripening protocol compatibility for buyers.
- Cavendish:Standardized cylindrical fruit geometry optimizes container cube utilization and ethylene dosing uniformity. Mass-market retail and food service chains in the United States and Germany specify this cultivar for contracted ripening programs due to predictable color-stage progression.
- Red Dwarf:Compact bunch architecture suits premium retail positioning with shorter transport legs. Demand concentrates in Japanese and South Korean import markets where consumers pay tariff-adjusted premiums for visual differentiation.
- Apple Banana:Tart flavor profile targets smoothie manufacturing and dairy-alternative processing in India and Vietnam.
- Lady Finger:Small finger size serves portion-controlled hospitality formats in Australian and UAE food service.
Volume sits with Cavendish; growth tilts toward Red Dwarf.
Distribution Channel:
Channel selection reflects buyer scale, ripening capability, and geographic penetration of cold-chain infrastructure.
- Supermarkets:Controlled-atmosphere ripening chambers at distribution centers enable just-in-time color-stage delivery. Chains in France and the United Kingdom specify 24-48 hour shelf-life windows through direct plantation contracts.
- Wholesale:Spot-market purchasing with buyer-managed ripening dominates emerging market procurement in Mumbai and São Paulo where supermarket penetration remains incomplete.
- Online Retail:Last-mile temperature control requirements favor local ripening-as-a-service partnerships in Berlin and Amsterdam urban nodes.
- Farmer's Markets:Minimal cold-chain investment suits short-radius supply in Indonesian and Philippine domestic trade.
Procurement concentrates in wholesale; margin expansion favors supermarket direct contracting.
Packaging Type:
Format determines ventilation rates, mechanical protection, and retail presentation flexibility.
- Cartons:Corrugated fiberboard with ethylene-permeable liners protects fruit during intermodal transit from Guayaquil and Manzanillo ports. Retail chains in the Netherlands and Belgium mandate carton specifications for automated warehouse handling.
- Bunches:Stem-wrapped full hands preserve natural ripening gas exchange for premium organic positioning in Italian and Spanish markets.
- Bulk:Loose fruit in ventilated containers minimizes unit cost for processing-grade supply to Indian banana flour and chip manufacturers.
- Bags:Perforated polyethylene retail packs with modified atmosphere properties extend counter life in Japanese convenience store channels.
Cartons dominate ocean freight; bag formats are climbing fastest in convenience retail.
End User:
User category dictates ripening precision, volume scale, and specification tolerance.
- Food Service:Contracted ripening programs with fixed color-stage delivery windows command premium pricing from QSR chains and smoothie operators in the United States and United Kingdom. Aldi and Lidl operations in Germany now specify ripening-stage delivery windows in supply agreements.
- Food Manufacturing:Processing-grade fruit with cosmetic tolerance for puree, flour, and extract production concentrates demand in Indian and Vietnamese processing hubs.
- Retail Consumers:Supermarket and online channels serve household purchase with ripeness-graded pricing tiers.
- Exporters:Re-export operations in Dubai and Singapore require phytosanitary certification alignment with multiple destination regimes.
Food manufacturing captures volume; food service delivers steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guayaquil anchors Latin American export infrastructure through its refrigerated port terminals serving European and Asian corridors. The city's ripening-as-a-service clusters concentrate pre-shipment ethylene treatment capacity for mass-market Cavendish supply.
Ecuador
Smoothie manufacturing contracts from US and UK food service chains drive import demand for processing-grade fruit. The national phytosanitary authority enforces residue testing protocols aligned with EU F-Gas Regulation transit requirements. Guayaquil-Manzanillo corridor operations prioritize carrier partnerships with natural refrigerant compliance for Rotterdam and Hamburg service.
United States
QSR chains and plant-based menu operators lock in multi-year supply contracts for portion-controlled ripening programs. FDA food safety modernization rules govern cold-chain documentation for imported fruit. Gulf Coast distribution nodes in Houston and New Orleans concentrate ethylene-based ripening infrastructure for domestic redistribution.
Germany
Discount retail chains specify ripening-stage delivery windows through direct plantation contracting. EU F-Gas Regulation phase-down schedules force refrigerated transport fleet retrofits by 2030. Hamburg port facilities serve as consolidation points for natural refrigerant-compliant Latin American supply.
India
Processing hub development in banana flour and chip manufacturing concentrates demand in Maharashtra and Karnataka. FSSAI-mandated residue testing redirects import volumes toward certified low-chemical plantations. Mumbai and Bangalore cold-chain gaps create first-mover opportunity for ripening-as-a-service providers as supermarket penetration climbs.
Netherlands
Rotterdam's re-export infrastructure handles phytosanitary certification alignment for multiple destination regimes. EU Green Deal agricultural import standards create premium tier access for deforestation-free certified operations. Amsterdam urban distribution nodes adopt container-scale ethylene generator units for just-in-time ripening to food service clients.
Global Banana Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and cold-chain capability tiers. The vendor base organizes around three archetypes: integrated plantation-to-port operators with captive ripening infrastructure, branded packaging specialists with retail shelf-life control technology, and multi-hemisphere sourcing aggregators anchoring year-round availability. Competitive moves concentrate on backward integration into ripening infrastructure and geographic diversification of plantation assets to mitigate phytosanitary and climate risks.
Within the integrated infrastructure tier, Dole Food Company, Inc. and Fresh Del Monte Produce Inc. exemplify plantation-to-port control models, while Chiquita Brands International, LLC occupies a position in branded ripening technology deployment. These three entities represent the dominant competitive archetypes: volume leadership through integrated supply chain control, premium positioning through ripening-stage specification capabilities, and availability assurance through multi-source procurement networks.
| Leading Market Players |
|---|
| Fyffes plc |
| Corporación Bananera Nacional S.A. |
| Dole Food Company, Inc. |
| Banacol S.A. |
| Turbana S.A. |
| Chiquita Brands International, LLC |
| Grupo Noboa S.A. |
| Agroamerica Holdings, Inc. |
| Fresh Del Monte Produce Inc. |
| Others |
Supply Flow & Price Mechanics
Bunker fuel index fluctuations cascade through Latin American export corridors into three distinct pricing tiers, with certified low-chemical operations commanding premiums over conventional supply while spot-market wholesale absorbs cost volatility at the margin pool bottom.
Pricing Analysis
Contracted ripening-stage delivery anchors value-based pricing for food service chains, with premium tiers separating USDA organic-certified supply from ISO 22000 food safety tier and conventional commodity fruit. Certification costs and cold-chain investments harden the gap between tiers. Pricing pressure stems from synthetic nitrogen price spikes eroding plantation operating margins. Food manufacturing buyers exhibit highest price sensitivity; supermarket direct contracting shows lowest.
Supply Chain Analysis
EU F-Gas Regulation certification gates access to Rotterdam and Hamburg corridors, with compliant Latin American exporters drawing from Ecuador, Guatemala, and Costa Rica. Supply chains rest on bunker fuel, synthetic nitrogen fertilizer, and refrigerated container availability. Single-variety genetic vulnerability to Panama disease Tropical Race 4 poses structural risk. Distribution runs through plantation-to-port integrated operators, wholesale spot markets, and ripening-as-a-service urban nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere ripening chamber scarcity props pricing for capable operators, as technician training bottlenecks constrain capacity expansion across secondary logistics hubs.
For Market Incumbents: Extend backward integration into captive ripening infrastructure across Mumbai and Bangalore distribution nodes. Consolidate carrier partnerships with natural refrigerant compliance before EU F-Gas Regulation phase-down deadlines. Dole Food Company, Inc. and Fresh Del Monte Produce Inc. exemplify this plantation-to-port control model.
For New Entrants and Emerging Players: Enter via ripening-as-a-service provision in underpenetrated Indian retail cold chain, where supermarket penetration remains below fifteen percent. Target Maharashtra and Karnataka processing hub demand for banana flour and chip manufacturing feedstock. Pursue FSSAI certification alignment as primary go-to-market credential.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Ecuadorian and Guatemalan plantation operators with integrated pest management documentation amid India's BIS pesticide residue limit enforcement. Long-term viability centers on deforestation-free certification access under EU Green Deal agricultural import standards. Watch Panama disease Tropical Race 4 spread patterns as inflection indicator for genetic vulnerability repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ripening Infrastructure | Captive ethylene chamber capacity secures Aldi and Lidl delivery window contracts in Germany. |
| Natural Refrigerant Fleet Retrofit Partnership | EU F-Gas Regulation compliance unlocks Rotterdam and Hamburg port access premiums. |
| FSSAI-Certified Low-Chemical Plantation Sourcing | Indian import redirection creates first-mover positioning in Mumbai processing hub supply. |
| Bioplastic Packaging Development | Banana fiber extraction merges with mechanical engineering to displace polyethylene retail bags. |
| Multi-Hemisphere Sourcing Network Expansion | Year-round availability anchoring defends against seasonal phytosanitary disruption in single-origin supply. |
Methodological Framework
Multi-period observation of bunker fuel surcharges, synthetic nitrogen price indices, and EU F-Gas Regulation compliance rates anchored the trend analysis, supplemented by interviews with plantation operations managers, cold-chain logistics directors, food service procurement leads, and Indian FSSAI regulatory affairs officers. Secondary validation drew from customs and trade data, SEC 10-K filings of listed produce companies, EU phytosanitary certification databases, and IHS Markit agricultural commodity price series. Bottom-up plantation capacity estimates triangulated against top-down import volume data.
Input-output matrices modeled cultivar selection, distribution channel infrastructure, packaging format, and end-user specification requirements across the projection horizon. CAGRs derived from segmented volume and value build-ups incorporating ethylene-based ripening technology adoption curves and EU Green Deal agricultural import standard phase-in assumptions. Forecast inputs included Panama disease spread modeling and Indian supermarket penetration trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phytosanitary rule changes in destination countries and climate disruption events. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Cyanidin Market