
 Plant Milk Market | 2026-2036
Plant Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Milk Market Analysis
Buyer concentration among foodservice chains and specialty coffee roasters is hardening as procurement volumes consolidate under fewer national accounts. Blue Diamond Growers leverages its almond supply base in California to anchor ingredient cost stability for downstream partners. Oatly AB competes through barista-grade formulation leadership, while Califia Farms extends its portfolio across refrigerated plant-based beverages in North American retail channels.
Plant milk denotes aqueous extracts of oilseeds, grains, or nuts, processed through wet milling, enzymatic hydrolysis, and homogenization to achieve colloidal stability and protein content typically between one and eight percent. Its primary commercial purpose is to replace bovine dairy in direct consumption and formulated food applications. Oat milk now leads product type growth due to neutral flavor compatibility with coffee applications and lower allergenicity versus almond or soy variants. Supermarkets dominate distribution channel volume, though online retail captures the fastest expansion as subscription models and direct-to-consumer brands build repeat purchase loyalty.
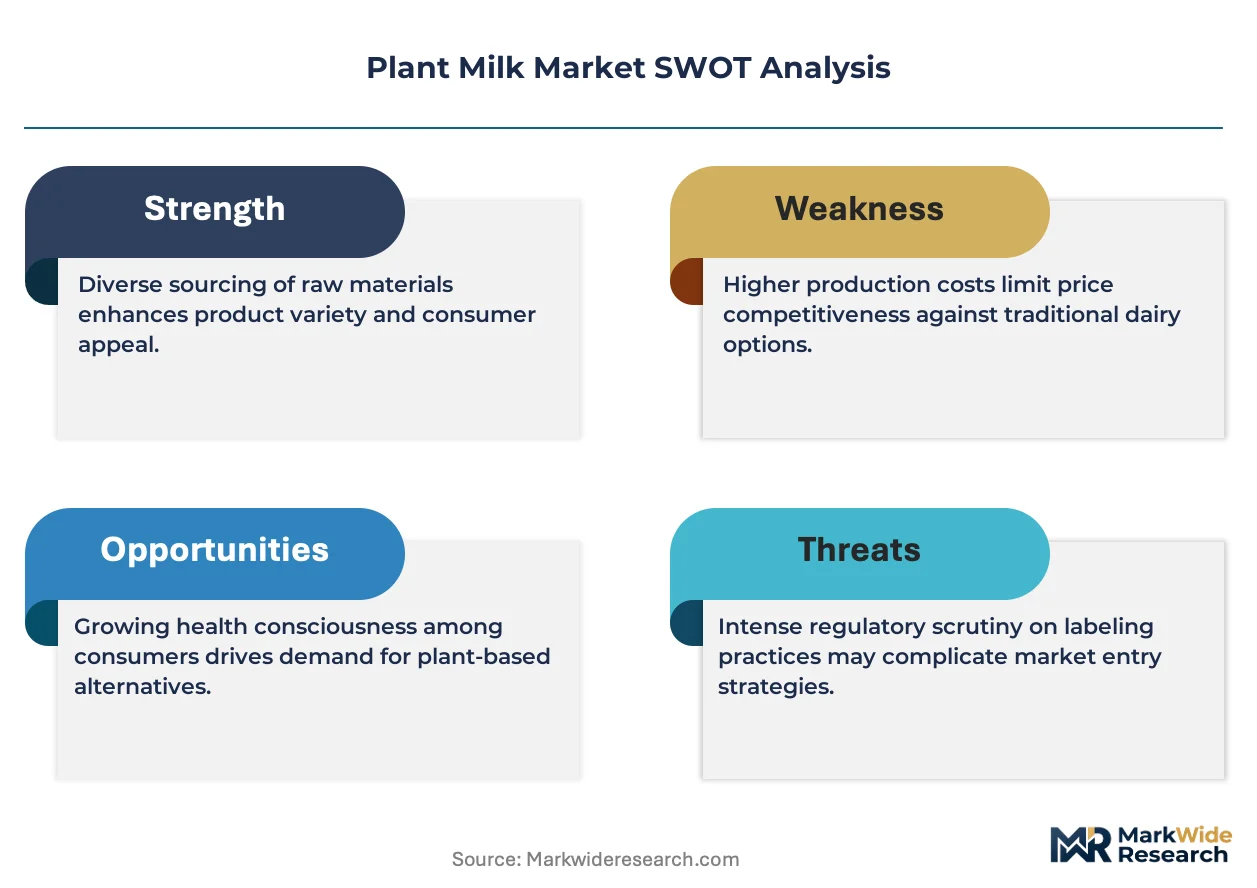
FDA oversees plant milk labeling disputes with dairy industry stakeholders, while EU Green Deal frameworks mandate carbon footprint disclosure for plant-based alternatives sold in European markets. EFSA evaluates novel protein claims and nutritional equivalence standards that determine shelf positioning and premium pricing eligibility. Stakeholders must monitor evolving allergen threshold regulations and front-of-pack labeling mandates that will reshape formulation investments and geographic launch sequencing.
Market Dynamics
Barista-format coffee chains are consolidating procurement volumes under national accounts, compressing supplier margins while demanding enzymatic hydrolysis capabilities that smaller processors cannot replicate at scale.
Growth Catalysts
- EU Green Deal carbon disclosure mandates:Supermarkets in Germany and France now require footprint labeling, accelerating oat milk formulation investments that deliver measurable emissions reductions versus dairy benchmarks.
- Enzymatic hydrolysis advances:Wet milling processors achieve protein stability above six percent without chalking, enabling clean-label positioning in premium refrigerated segments.
- Coffee shop menu penetration:National roaster chains specify barista-grade foaming performance, locking in multi-year supply agreements with qualified processors.
Market Restraints
- Almond supply concentration in California Central Valley:Drought cycles and water allocation disputes create input cost volatility that downstream partners cannot hedge through contract structures.
- EFSA novel protein equivalence thresholds:Nutritional positioning claims face eighteen-month evaluation timelines, delaying shelf placement and premium pricing eligibility for reformulated entrants.
- Soy allergen cross-contamination protocols:Shared processing infrastructure requires dedicated line certification that elevates capital requirements for mid-scale operators.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retail captures repeat purchase loyalty through personalized flavor rotation and auto-replenishment algorithms.
- Fermentation-derived protein convergence:Precision fermentation suppliers partner with oat base processors to achieve amino acid profiles matching dairy benchmarks.
- India FSSAI plant-based labeling clarity:Emerging regulatory frameworks create first-mover advantage for processors establishing local formulation facilities.
Industry Challenges
- Colloidal stability expertise shortage:Food science programs produce insufficient homogenization specialists capable of scaling barista-grade formulations.
- Organic certification timeline compression:Three-year transition periods for oat sourcing constrain supply expansion for premium-positioned product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Milk Market |
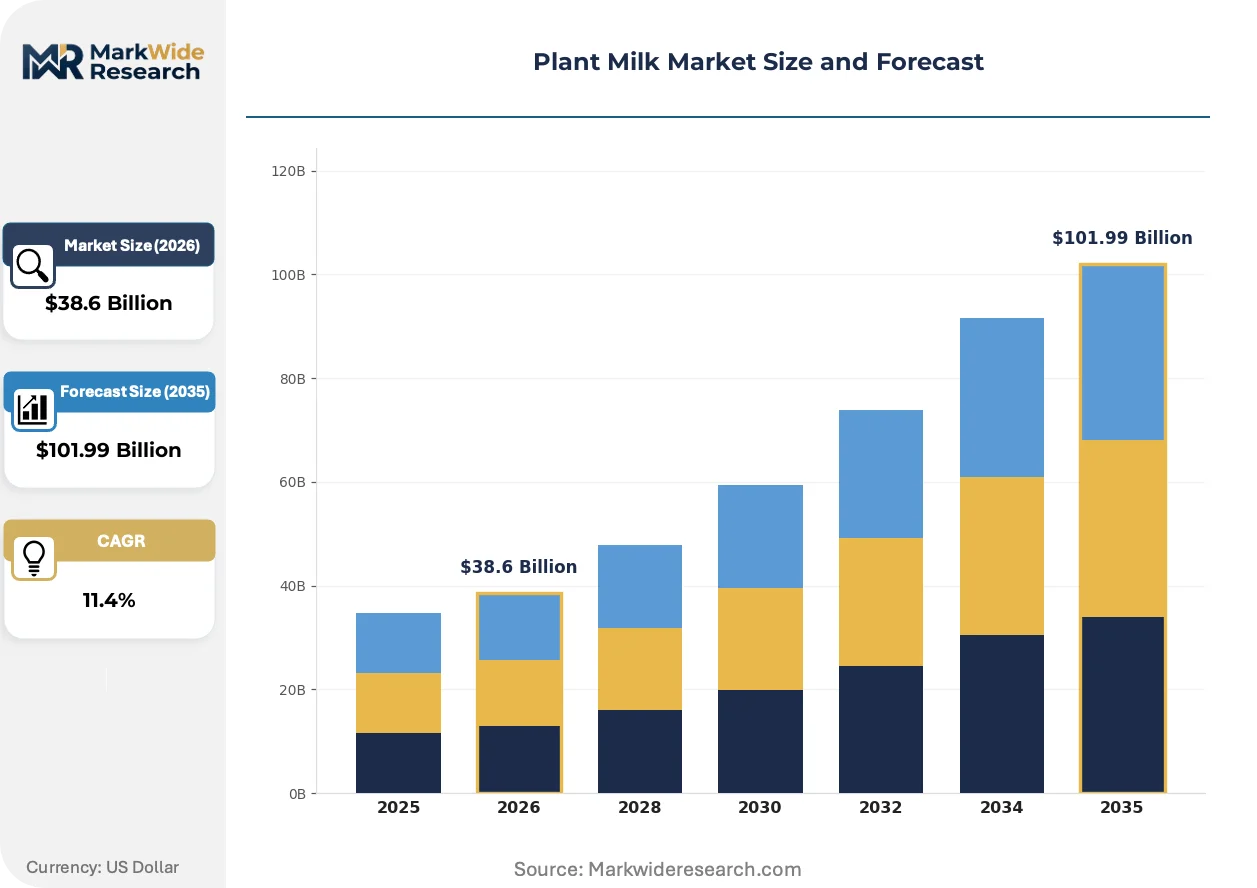
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Application: Beverages, Cooking, Baking, Coffee Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Customer Type: Vegans, Lactose-Intolerant, Fitness Enthusiasts, General Consumers |
| Companies Covered | Danone S.A., Blue Diamond Growers, The Hain Celestial Group, Califia Farms, SunOpta, Oatly AB, Döhler GmbH, Ripple Foods, Alpina Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Milk Market Emerging Trajectories
Enzymatic processing capabilities and carbon accounting transparency are rewriting competitive thresholds, while procurement consolidation among foodservice chains compresses supplier qualification cycles.
Fermentation-enhanced protein fortification is expanding into barista-grade oat bases, enabling foam stability previously achievable only with dairy proteins. National coffee chains specify these formulations in multi-year supply agreements. The technology is expanding into private-label retail segments where processors compete on clean-label positioning.
EU Green Deal carbon footprint disclosure rules now mandate lifecycle documentation for plant-based alternatives sold in European markets. EFSA evaluates methodological compliance, determining which products qualify for premium shelf positioning. German retailers lead enforcement, rejecting suppliers without verified emissions data.
Foodservice procurement has consolidated under fewer national accounts, with coffee chains demanding dedicated technical service teams and co-development agreements. This displaces fragmented regional distributor relationships. The shift concentrates volume in Germany, where formulation expertise and retail density exceed other European markets.
Plant Milk Market Segmentation
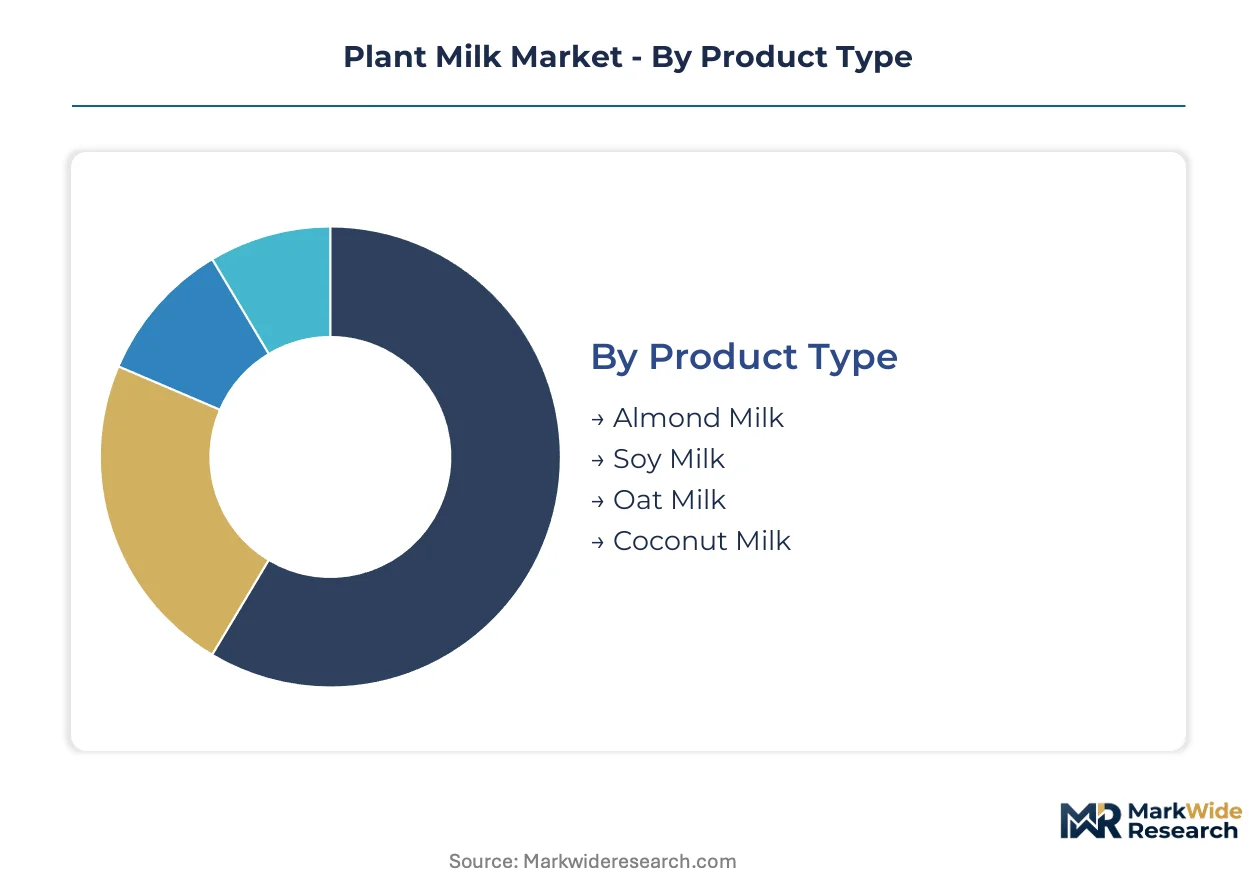
Plant milk segmentation reveals how formulation chemistry and channel economics create divergent margin pools. Category boundaries are blurring as barista-grade specifications migrate from coffee shops into retail premium tiers.
Product Type:
Volume leaders compete on input cost stability while premium segments command formulation premiums through enzymatic processing capabilities.
- Oat Milk:Neutral flavor profile and lower allergenicity versus nut-based alternatives enable seamless coffee application integration. German retailers and specialty coffee chains concentrate procurement here, driven by EU Green Deal carbon disclosure advantages over dairy benchmarks. Enzymatic hydrolysis advances now push protein stability above six percent without chalking defects.
- Almond Milk:California Central Valley supply concentration anchors ingredient cost structures for mass-market positioning. Drought cycles and water allocation disputes create input volatility that downstream partners struggle to hedge, compressing margins during scarcity periods.
- Soy Milk:Legacy category with established processing infrastructure across Asian and European manufacturing bases.
- Coconut Milk:Tropical sourcing dependencies and fat separation challenges limit barista-grade adoption outside Southeast Asian markets.
Today's leader: Oat Milk. Tomorrow's challenger: Almond Milk.
Application:
End-use specifications are hardening as foodservice chains consolidate procurement under technical performance requirements.
- Coffee:Barista-grade foam stability and enzymatic hydrosis capabilities now determine supplier qualification. National roaster chains lock in multi-year supply agreements with processors demonstrating colloidal stability above commercial thresholds.
- Beverages:Direct consumption formats prioritize clean-label positioning and refrigerated shelf presence in premium retail segments.
- Cooking:Neutral flavor profiles and heat stability requirements favor oat and soy bases in formulated food manufacturing.
- Baking:Fat content and protein interaction specifications create niche demand for coconut and almond variants in artisanal and industrial bakery channels.
Foodservice procurement consolidation favors Coffee. Retail premiumization elevates Beverages.
Distribution Channel:
Channel economics are diverging as subscription algorithms capture repeat purchase loyalty versus supermarket velocity requirements.
- Supermarkets:Dominant volume channel with shelf positioning determined by EFSA nutritional equivalence claims and front-of-pack labeling compliance. German retail density exceeds other European markets.
- Online Retail:Auto-replenishment models and personalized flavor rotation build customer lifetime value metrics that outperform traditional retail economics. This channel is expanding most quickly as direct-to-consumer brands scale fulfillment infrastructure.
- Health Stores:Organic certification and three-year oat sourcing transition periods constrain supply expansion for premium-positioned lines.
- Specialty Shops:Curated assortment and barista-format equipment sales create experiential positioning for formulation innovators.
Supermarkets anchor current volume. Online Retail commands steepest expansion trajectory.
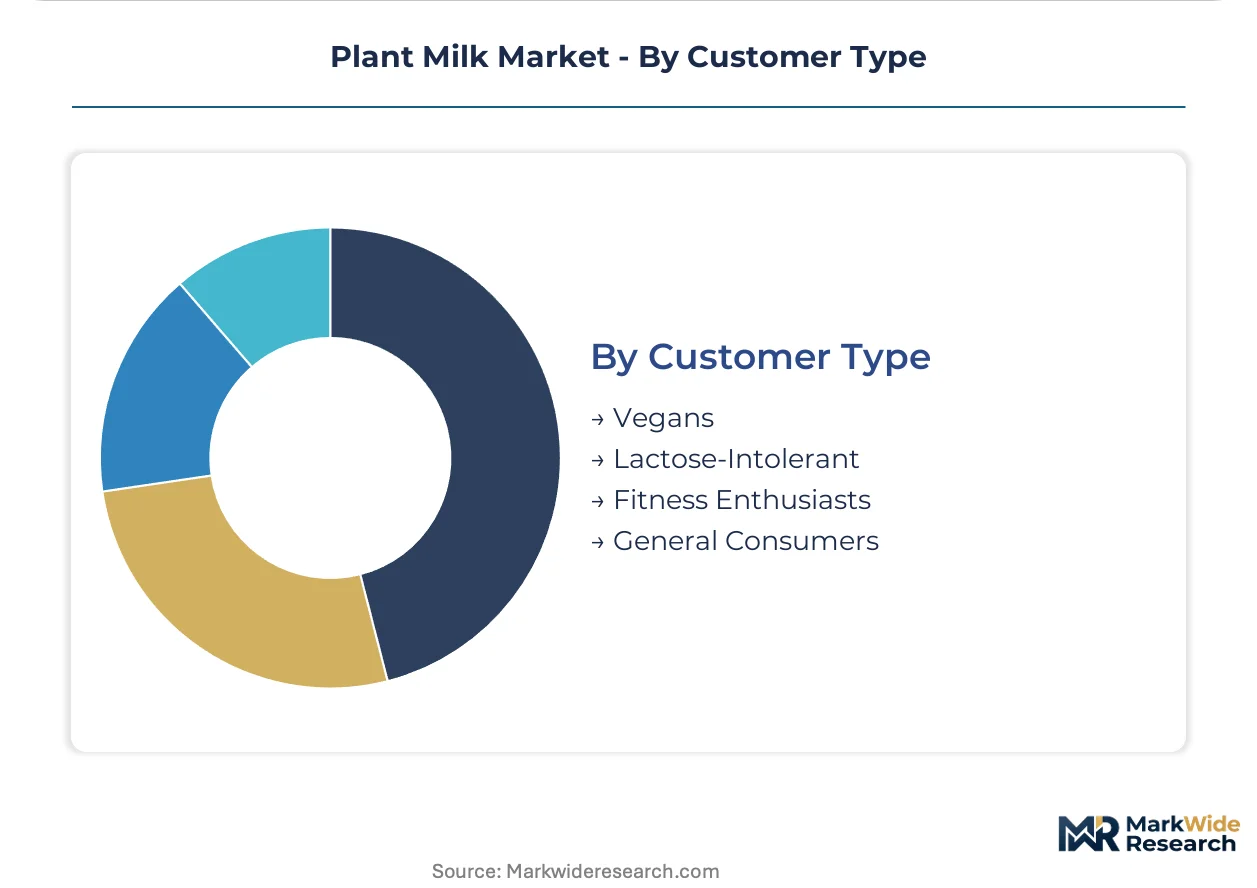
Customer Type:
Health-motivated segments tolerate price premiums while mainstream adoption depends on taste parity and convenience equivalence.
- Lactose-Intolerant:Medical necessity drives consistent repurchase with lower price sensitivity than lifestyle-motivated segments. German and French market concentration reflects diagnostic awareness and retail access.
- Vegans:Ethical positioning correlates with willingness to pay premiums for certified supply chains and carbon footprint transparency.
- Fitness Enthusiasts:Protein fortification and fermentation-enhanced amino acid profiles match dairy benchmarks in sports nutrition applications.
- General Consumers:Taste parity and price convergence with conventional dairy determine trial-to-adoption conversion in mass-market penetration.
Lactose-Intolerant segments provide stable base demand. General Consumers represent the largest addressable expansion pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food science graduates from Wageningen University and Hohenheim University anchor European formulation expertise, while UC Davis and Cornell supply enzymatic processing specialists to North American processors. This talent concentration shapes regional competitive advantages in barista-grade product development.
Germany
Berlin and Hamburg coffee chains drive oat milk procurement volumes, with national accounts consolidating under multi-year supply agreements. The EU Green Deal mandates carbon footprint disclosure for all plant-based alternatives sold through German retail channels. Bavaria hosts enzymatic hydrolysis research clusters where processors achieve protein stability above six percent without chalking defects.
United States
California Central Valley almond growers supply input cost structures for mass-market positioning, though drought cycles create volatility that downstream partners struggle to hedge. FDA labeling disputes with dairy industry stakeholders continue to shape front-of-pack positioning rules. Pacific Northwest oat processing facilities in Oregon and Washington expand capacity to serve specialty coffee roasters.
France
Parisian specialty coffee culture accelerates barista-grade adoption, with national roaster chains specifying foam stability requirements in technical procurement documents. EFSA evaluates novel protein equivalence claims that determine eighteen-month shelf placement timelines for reformulated entrants. The Auvergne-Rhône-Alpes region concentrates organic oat sourcing operations subject to three-year certification transition periods.
United Kingdom
London's independent coffee shop density exceeds other European capitals, creating fragmented but high-volume demand for barista-compatible formulations. The Competition and Markets Authority monitors retail pricing patterns as supermarket private-label penetration intensifies. East Anglia hosts oat milling infrastructure that supplies both domestic beverage manufacturers and export markets.
India
Mumbai and Bangalore urban consumers drive trial adoption among lactose-intolerant segments with lower price sensitivity than lifestyle-motivated buyers. FSSAI plant-based labeling clarity creates first-mover advantage for processors establishing local formulation facilities. Maharashtra and Karnataka host emerging manufacturing clusters where domestic brands scale enzymatic processing capabilities.
Plant Milk Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and channel access dimensions. The vendor base organizes into three tiers: multinational beverage conglomerates with dairy-alternative portfolios, regional processors with enzymatic hydrolysis capabilities, and direct-to-consumer brands scaling subscription fulfillment infrastructure. Strategic moves concentrate on backward integration into oat sourcing and co-development agreements with national coffee chains.
Within the pure-play specialist tier, Oatly AB and Califia Farms exemplify divergent geographic positioning strategies, while Blue Diamond Growers anchors the nut-based input supply archetype. Danone S.A. occupies a position representing conglomerate diversification into plant-based alternatives through acquired brands. These three company structures illustrate how capital access and channel relationships determine competitive mobility across premium refrigerated and mass-market ambient segments.
| Leading Market Players |
|---|
| Danone S.A. |
| Blue Diamond Growers |
| The Hain Celestial Group |
| Califia Farms |
| SunOpta |
| Oatly AB |
| Döhler GmbH |
| Ripple Foods |
| Alpina Foods |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up oat processors in Germany and Sweden anchor supply discipline through captive sourcing agreements, translating input cost predictability into stable premium-tier pricing for barista-grade formulations while compressing margins for unintegrated competitors.
Pricing Analysis
Bundled technical service and co-development agreements command premiums over unbundled commodity supply, with national coffee chains locking in multi-year contracts that embed enzymatic processing capabilities. Three-tier pricing structure across premium barista-grade, standard refrigerated, and economy ambient segments reflects certification grade and volume scale differentiation. Pricing pressure stems from almond input volatility in California's Central Valley, where drought-driven scarcity compresses mass-market margins. General Consumers in supermarket channels exhibit highest price sensitivity, while specialty coffee roasters tolerate premiums for foam stability performance.
Supply Chain Analysis
Direct-to-retail channels handle German and French supermarket volume, while foodservice distributors serve fragmented coffee shop networks. Raw material sourcing concentrates in Sweden and Finland for oat bases, California for almonds, and Southeast Asia for coconut extracts. Enzymatic processing equipment and homogenization specialists represent critical dependencies that constrain mid-scale expansion. Single-source vulnerability in California almond supply creates structural risk during water allocation disputes. Distribution runs through temperature-controlled logistics networks with distinct cold-chain requirements for refrigerated versus ambient formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal carbon disclosure mandates in Germany create compliance costs that US-based competitors can avoid by serving less regulated export markets.
For Market Incumbents: Deepen backward integration into organic oat sourcing to secure three-year certification timelines before supply constraints tighten. Lock in dedicated enzymatic processing capacity in Bavaria research clusters to defend against precision fermentation substitutes. Colloidal stability expertise shortage represents the critical threat to qualification for national coffee chain contracts. For New Entrants and Emerging Players: FSSAI plant-based labeling clarity in India opens a window for local formulation facilities serving lactose-intolerant urban segments in Mumbai and Bangalore. White-space targets include direct-to-consumer subscription channels with personalized flavor rotation and fermentation-enhanced protein fortification for sports nutrition applications. Go-to-market through auto-replenishment algorithms builds customer lifetime value metrics that outperform traditional retail economics. For Investors and Strategic Acquirers: Valuations sit cheapest among regional processors with enzymatic hydrolysis capabilities but fragmented coffee chain relationships. Long-term viability over a five-to-ten year window hinges on securing multi-year supply agreements with consolidating national roaster accounts. Watch for EFSA novel protein equivalence approval timelines as the inflection signal determining premium shelf positioning eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Sourcing | Captive organic supply secures three-year certification timelines ahead of competitor expansion. |
| Barista-Grade Formulation Partnership | Co-development agreements with national coffee chains lock in multi-year volume commitments. |
| Precision Fermentation Collaboration | Amino acid profile matching enables clean-label positioning against dairy protein benchmarks. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment algorithms capture repeat purchase loyalty in online retail expansion. |
| Carbon Footprint Certification Investment | EU Green Deal compliance determines premium shelf positioning in German retail channels. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with enzymatic processing specialists, coffee chain procurement directors, supermarket category buyers, and plant-based R&D directors with secondary validation through EFSA guidance documents, EU Green Deal regulatory filings, FDA labeling dispute records, and customs trade data for oat and almond imports. Bottom-up volume modeling triangulated against top-down category spending estimates.
Segment-weighting approaches applied differential growth assumptions across product types, applications, and distribution channels, with oat milk barista-grade formulations, coffee end-use specifications, and online retail subscription models receiving distinct trajectory parameters. CAGRs derived from trend extrapolation anchored in documented procurement consolidation patterns and enzymatic processing capacity expansion timelines. Forecast inputs incorporated EU carbon disclosure enforcement intensity and FSSAI regulatory clarity progression.
Revisions become necessary when EFSA novel protein equivalence thresholds shift, California water allocation disputes intensify, or national coffee chain procurement consolidation accelerates beyond modeled rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Vegan Cheese Alternatives Market