
 Global Physical Security Software Market | 2026-2036
Global Physical Security Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Physical Security Software Market Foresight
The capital-intensity divergence between cloud-native entrants and legacy hardware-anchored incumbents is rotating competitive investment toward software-centric architectures. Johnson Controls International plc leverages its building-automation heritage to bundle security software with HVAC and energy management systems. Honeywell International Inc. sustains R&D intensity across artificial intelligence-powered video analytics. Bosch Security Systems anchors European manufacturing scale with edge-computing video platforms.
Physical security software encompasses integrated platforms that manage access credentials, video streams, intrusion alerts, and identity verification through centralized or distributed architectures, typically operating on IP networks with encryption protocols and API-based interoperability. Its primary commercial purpose is to replace siloed analog systems with unified digital command environments that reduce response latency and audit friction. Video surveillance solutions dominate current revenue pools, though cloud-based deployment is expanding fastest as enterprises abandon on-premises server maintenance. Security management platforms capture disproportionate margin contribution by stitching together multi-vendor hardware estates.
The EU AI Act, GDPR, and NIST Cybersecurity Framework collectively tighten algorithmic transparency mandates for biometric identification and cross-border data flows in security applications. FDA oversight of certain building-access health sensors and FCC spectrum rules for wireless security devices add layered compliance cost in the United States. Buyers must weigh vendor certification depth against the pace of regulatory refresh cycles.
Market Dynamics
The migration from on-premises server stacks to cloud-native architectures is compressing deployment timelines and forcing incumbents to unwind decades of hardware-anchored business models. This structural shift rewards software-first vendors with recurring revenue streams while stranding capital-intensive legacy estates.
Growth Catalysts
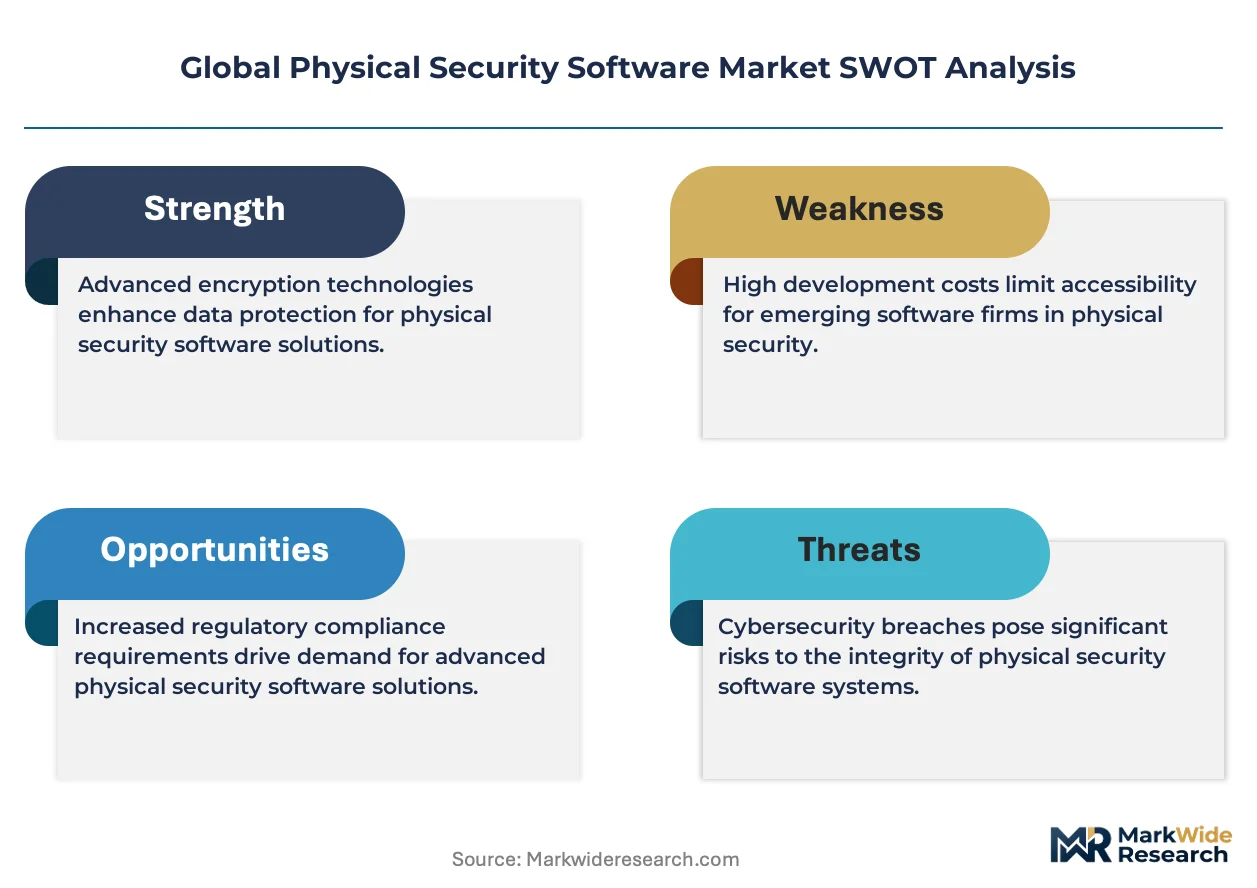
- EU AI Act compliance mandates:Biometric surveillance restrictions across member states are accelerating procurement of algorithmically transparent platforms that document decision pathways for audit trails.
- Data center operator consolidation:Hyperscale facility builders in the United States are standardizing on unified physical-cybersecurity command layers to reduce operational complexity across distributed campuses.
- Edge computing maturation:On-device video analytics are eliminating latency bottlenecks for real-time threat detection in bandwidth-constrained environments.
Market Restraints
- Semiconductor supply concentration:GPU and NPU shortages for AI-enabled cameras create procurement queues stretching 12-18 months for specialized security silicon.
- GDPR cross-border friction:Data localization requirements complicate cloud deployment architectures for multinational enterprises operating across EU member state boundaries.
- Legacy analog substitution ceiling:Budget-constrained municipal and educational facilities delay full digital transitions, extending hybrid maintenance burdens.
Strategic Opportunities
- India smart city infrastructure:National urban renewal programs are embedding integrated security software into transportation and utility command centers with localized data residency.
- Healthcare access convergence:FDA-regulated building sensors for occupancy and air quality are creating bundled procurement opportunities with identity management systems.
- API-first platform ecosystems:Open interoperability standards are enabling third-party developers to build vertical-specific applications atop core security infrastructure.
Industry Challenges
- Cyber-physical security skill fusion:Enterprises struggle to hire personnel fluent in both OT network segmentation and traditional perimeter defense methodologies.
- Multi-vendor integration complexity:Stitching together access control, video management, and intrusion systems from different suppliers consumes 40-60% of deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Physical Security Software Market |
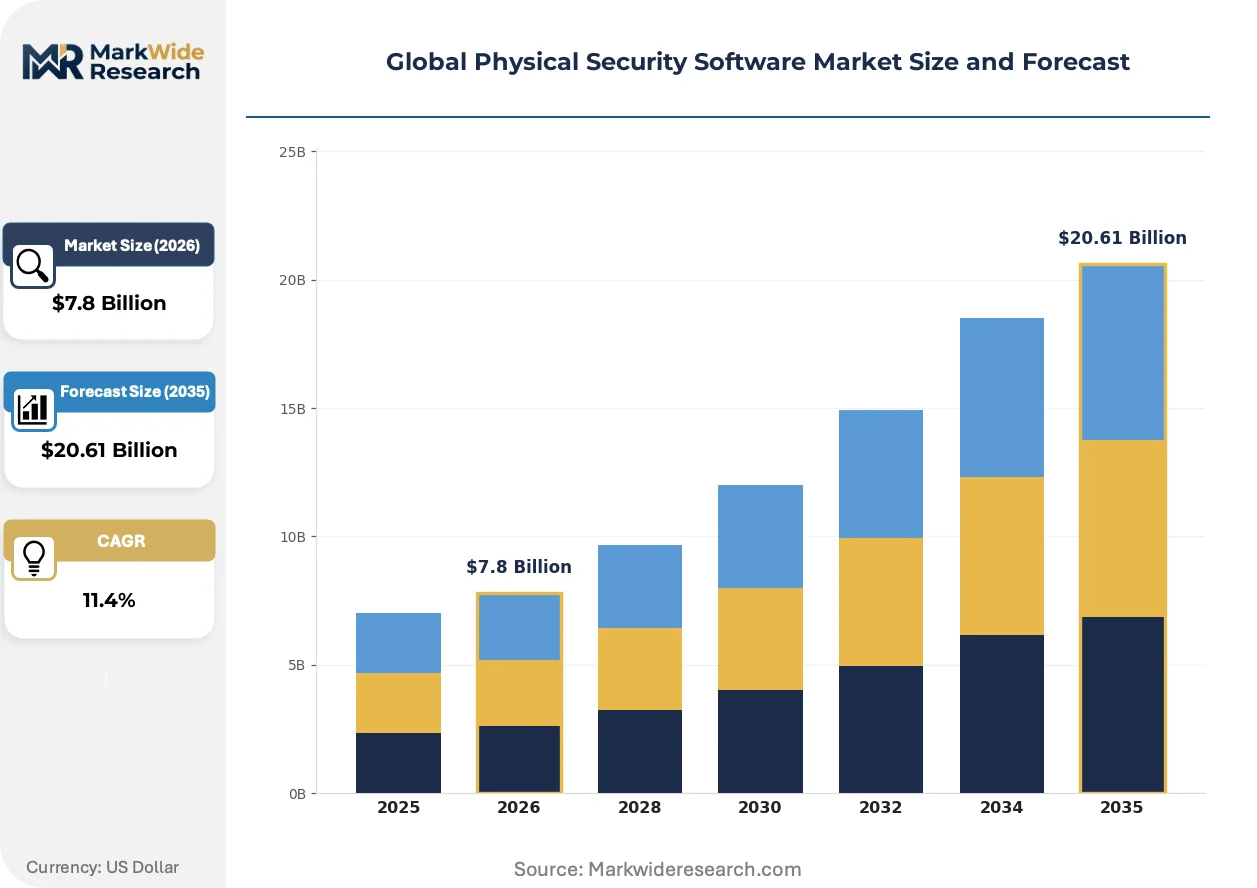
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Access Control, Video Surveillance, Intrusion Detection, Security Management, Visitor Management Deployment Mode: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Critical Infrastructure, Transportation Hubs, Commercial Complexes, Educational Institutions, Government Facilities End User: Correctional Facilities, Data Centers, Financial Institutions, Retail Chains, Hospitality Groups |
| Companies Covered | Johnson Controls International plc, Honeywell International Inc., Bosch Security Systems, ADT Inc., Cisco Systems Inc., Genetec Inc., Axis Communications AB, Hangzhou Hikvision Digital Technology Co., Ltd., LenelS2, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Physical Security Software Market Shifts & Advancements
Artificial intelligence inference is migrating from centralized data centers toward camera endpoints and edge gateways, redistributing computational load and rewiring vendor competitive advantages around silicon efficiency rather than server scale.
Computer vision algorithms are decomposing monolithic video analytics platforms into modular microservices that run on commodity edge hardware. Critical infrastructure operators in Germany and the Netherlands are piloting these containerized workloads to reduce bandwidth costs and enable offline operation during network outages. This architecture is decomposing traditional vendor lock-in by allowing buyers to mix analytics providers across a single camera estate.
The EU AI Act's risk-based classification system is forcing biometric identification vendors to retrain models on ethnically diverse datasets and document performance variance across demographic groups. Industrial consequence includes mandatory conformity assessments before market entry. High-security transportation hubs in France and Spain are now requiring algorithmic impact statements as standard procurement documentation.
Subscription pricing for video management software is displacing perpetual license models among mid-market buyers who prioritize operational expenditure predictability over capital ownership. Value-added resellers in the United States are restructuring compensation around recurring revenue share rather than upfront margin. This shift is most visible among K-12 school districts and regional healthcare networks consolidating fragmented campus security estates under unified cloud platforms.
Global Physical Security Software Market Segmentation
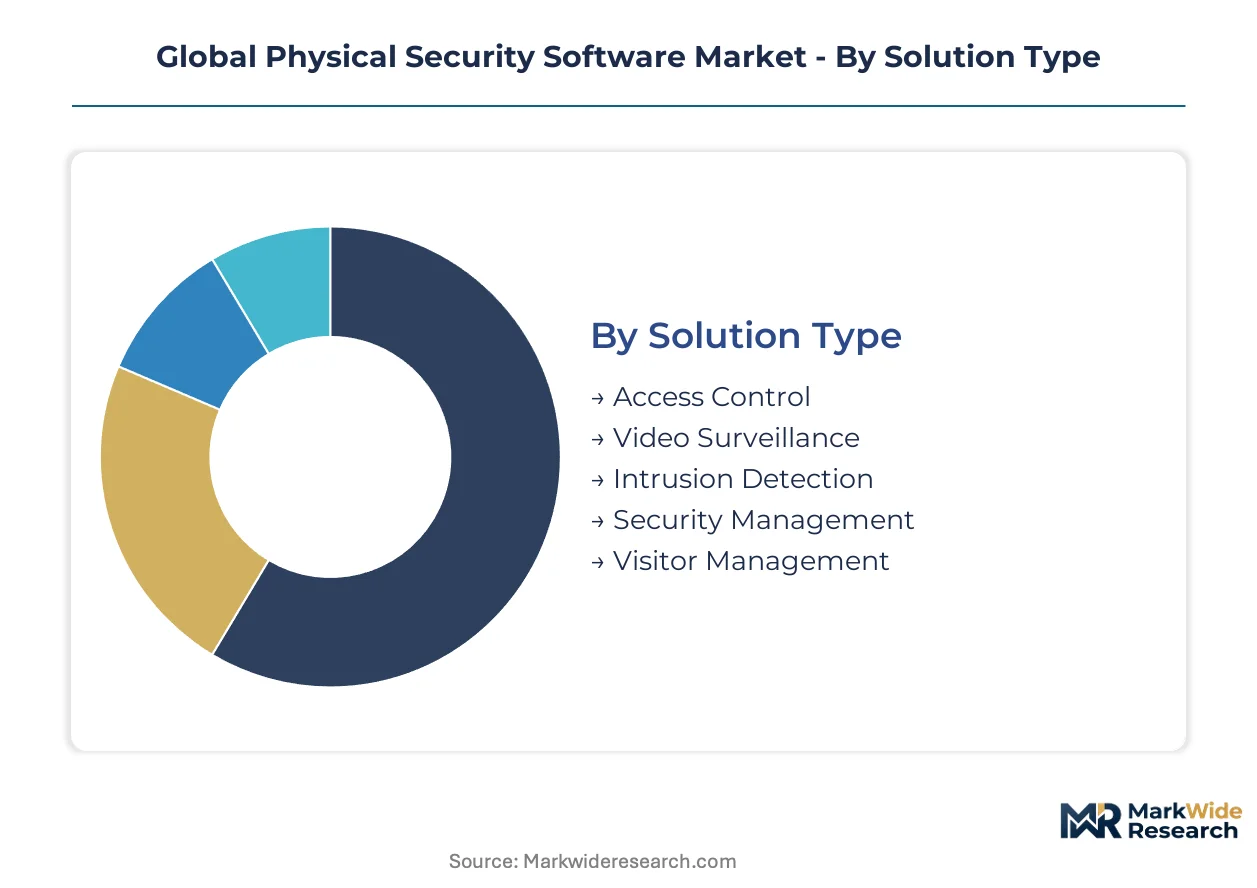
Segmentation in physical security software reveals how procurement channels fragment across deployment complexity and compliance maturity. Buyers route cloud-native solutions through managed service providers while edge-heavy estates demand systems integrators with OT networking expertise.
Solution Type:
Channel mix varies sharply by solution complexity—video surveillance flows through distributor networks, security management platforms route direct-to-enterprise, and access control splits between locksmith channels and IT resellers.
- Access Control:Credential management systems integrating biometric readers, mobile tokens, and physical keycard databases with directory services. Demand clusters among data center operators in Northern Virginia and Frankfurt seeking multi-factor authentication for cage-level entry. Regulatory pressure from the EU AI Act on biometric storage is accelerating procurement of on-device template matching systems.
- Video Surveillance:IP camera management platforms with AI-powered analytics for object detection and behavioral analysis. Large-scale deployments concentrate at transportation hubs in France and Spain where algorithmic impact statements are now mandatory procurement documentation. Edge inference capabilities are eliminating centralized server dependencies.
- Intrusion Detection:Sensor fusion platforms correlating motion, glass-break, and perimeter breach signals.
- Security Management:Unified command dashboards stitching multi-vendor estates through API orchestration.
- Visitor Management:Identity verification workflows for temporary credential issuance and audit trail generation.
Video surveillance dominates installed base. Security management is where expansion concentrates.
Deployment Mode:
Cost tier segmentation separates capital-intensive on-premises estates from operational expenditure-driven cloud subscriptions, with hybrid architectures capturing mid-market buyers seeking staged migration paths.
- On-Premises:Server-based architectures with localized storage and dedicated network segmentation. Financial institutions in Switzerland and Singapore maintain these configurations for air-gapped compliance with banking secrecy frameworks. High upfront capital requirements limit refresh cycles to 7-10 year intervals.
- Cloud-Based:Multi-tenant SaaS platforms with elastic compute for video analytics and centralized policy administration. K-12 school districts across Texas and California are consolidating fragmented campus estates under unified cloud platforms to reduce IT maintenance overhead. Subscription pricing displaces perpetual licenses among operational expenditure-constrained buyers.
- Hybrid:Local edge processing with cloud backup and remote management capabilities.
- Edge Computing:On-device inference engines enabling offline operation during network outages.
On-premises retains the largest installed base. Cloud-based deployment is climbing the fastest.
Application:
Volume concentration tracks critical infrastructure protection budgets, with transportation hubs and government facilities commanding multi-year procurement cycles while commercial complexes operate on shorter refresh timelines.
- Critical Infrastructure:Energy, water, and telecommunications facility protection with NERC CIP and EU NIS2 compliance mandates. Operators in Germany and the Netherlands are piloting containerized video analytics to reduce bandwidth costs and enable autonomous threat response during network isolation.
- Transportation Hubs:Airport, seaport, and railway security with passenger flow optimization and baggage screening integration. High-security terminals in France now require documented algorithmic bias testing for biometric identification systems under EU AI Act enforcement.
- Commercial Complexes:Mixed-use property management with tenant-specific access policies.
- Educational Institutions:Campus-wide emergency notification and lockdown system integration.
- Government Facilities:Classified and unclassified space protection with FedRAMP or national equivalent certification requirements.
Critical infrastructure commands the highest per-site spend. Transportation hubs show the steepest expansion trajectory.
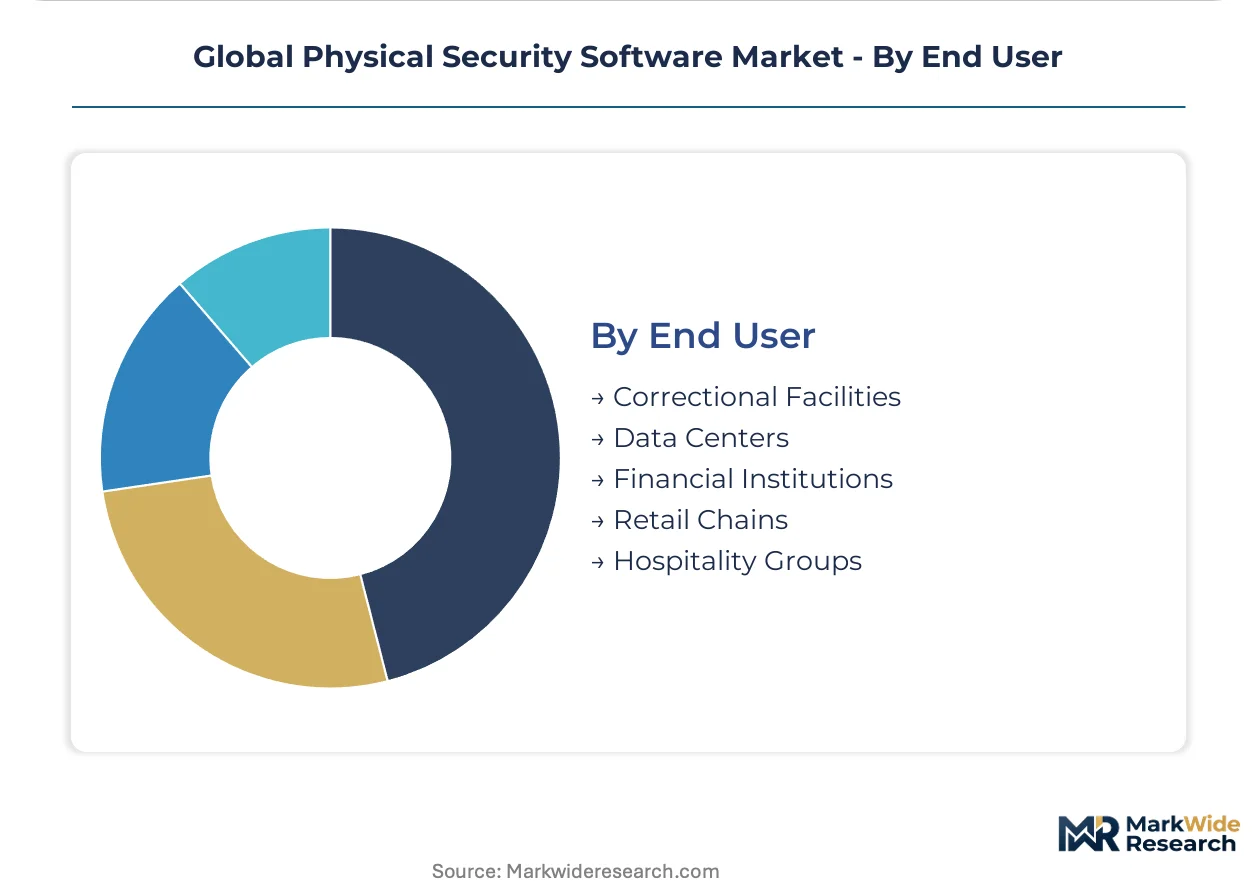
End User:
Customer type segmentation separates buyers with captive security operations from those outsourcing to managed services, with data centers and financial institutions maintaining internal SOC capabilities while retail chains favor outsourced monitoring.
- Data Centers:Hyperscale and colocation facilities requiring unified physical-cybersecurity command layers. Operators in Ashburn, Virginia and Dallas, Texas are standardizing on integrated platforms to reduce complexity across distributed campuses with 50+ MW power densities.
- Financial Institutions:Bank branches, trading floors, and vault protection with PCI-DSS and GLBA compliance requirements. Swiss private banks and Singaporean wealth managers maintain on-premises architectures for transaction surveillance data sovereignty.
- Correctional Facilities:Perimeter detection and inmate movement tracking with tamper-resistant hardware specifications.
- Retail Chains:Loss prevention and occupancy analytics across distributed storefront portfolios.
- Hospitality Groups:Guest access management and back-of-house staff credentialing.
Data centers anchor premium solution demand. Financial institutions represent the most compliance-intensive procurement process.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural trade surplus in physical security software exports, shipping integrated command platforms to data center operators across Northern Europe and the Gulf states while importing specialized edge-computing silicon from Taiwan and South Korea.
United States
Federal facilities and hyperscale data centers in Northern Virginia and Dallas drive procurement of unified physical-cybersecurity platforms. NIST Cybersecurity Framework compliance mandates shape vendor selection for critical infrastructure operators. Ashburn, Virginia anchors the densest concentration of multi-megawatt facilities standardizing on cloud-native security architectures.
Germany
Industrial operators and transportation authorities seek algorithmically transparent biometric systems under EU AI Act enforcement. The country's national data protection regulator enforces strict cross-border data localization for surveillance footage. The Rhine-Ruhr corridor hosts pilot deployments of containerized video analytics for autonomous threat response during network isolation.
India
National smart city programs embed integrated security software into transportation and utility command centers with localized data residency requirements. The Bureau of Indian Standards mandates interoperability certifications for government procurement. Mumbai and Delhi-NCR concentrate deployment of multi-factor authentication systems for financial district access control.
France
High-security transportation hubs in Paris and Lyon require documented algorithmic impact statements for biometric identification systems. CNIL, the national data protection authority, audits surveillance systems for GDPR compliance across cross-border data flows. The Île-de-France region leads pilot programs for passenger flow optimization with privacy-preserving video analytics.
United Arab Emirates
Mega-project developments in Dubai and Abu Dhabi procure integrated security platforms for mixed-use commercial and hospitality estates. MOHAP, the national health regulator, oversees building-access health sensor deployments creating bundled procurement opportunities. Dubai's smart city initiative standardizes on API-first security management platforms for third-party developer ecosystems.
Global Physical Security Software Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that leverage building-automation heritage to bundle security software with adjacent infrastructure systems. The vendor base spans three tiers: global multi-industry platforms, specialized security pure-plays, and regional systems integrators. Strategic moves center on API-first ecosystem expansion and edge-computing silicon partnerships that redistribute computational load toward camera endpoints.
Within the diversified conglomerate tier, Johnson Controls International plc and Honeywell International Inc. exemplify players that occupy positions spanning HVAC, energy management, and security software integration. Bosch Security Systems anchors European manufacturing scale with edge-computing video platforms. These three entities represent distinct geographic anchoring—Irish-American, American, and German—that shapes their respective regulatory compliance depth and channel partner ecosystems across regional markets.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Honeywell International Inc. |
| Bosch Security Systems |
| ADT Inc. |
| Cisco Systems Inc. |
| Genetec Inc. |
| Axis Communications AB |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| LenelS2 |
| Others |
Supply & Pricing Matrix
Cloud-native subscription models replacing perpetual license sales are simultaneously redistributing vendor revenue geography toward recurring-revenue SaaS providers and compressing upfront pricing power among legacy hardware-anchored incumbents. This substitution dynamic concentrates margin capture with software-first platforms while stranding capital-intensive on-premises estates that cannot match operational expenditure predictability.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium FedRAMP-certified tiers, standard commercial cloud subscriptions, and economy on-premises perpetual licenses. Price differentiation rests on certification depth and integration complexity, with hyperscale data center operators in Northern Virginia and Dallas showing lowest price sensitivity while K-12 school districts in Texas and California exhibit acute budget constraints. Pricing pressure stems from GPU and NPU shortages for AI-enabled cameras stretching procurement queues, forcing buyers toward less compute-intensive edge inference alternatives.
Supply Chain Analysis
Taiwan and South Korea anchor specialized security silicon fabrication for AI-enabled cameras and edge inference engines. Taiwan Semiconductor Manufacturing Company and Samsung Foundry feed from GPU and NPU wafer production, while Malaysia and Vietnam handle final assembly and testing for IP camera modules. Single-source vulnerability concentrates in advanced node semiconductor manufacturing, with distribution running through distributor networks for video surveillance and direct-to-enterprise channels for security management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment complexity and compliance maturity creates white-space opportunities for specialists addressing edge-heavy estates and algorithmically transparent biometric systems.
For Market Incumbents: Compound building-automation heritage into bundled security-HVAC-energy offerings that raise switching costs for data center operators. Prioritize edge-computing silicon partnerships to redistribute computational load toward camera endpoints and defend against cloud-native entrants. Invest in EU AI Act conformity assessment capabilities to capture procurement mandates at high-security transportation hubs in France and Spain. For New Entrants and Emerging Players: Anchor in India smart city infrastructure programs embedding localized data residency requirements into transportation and utility command centers. Target healthcare access convergence opportunities bundling FDA-regulated building sensors with identity management systems. Pursue API-first platform ecosystems enabling third-party developers to build vertical-specific applications atop core infrastructure. For Investors and Strategic Acquirers: The market sits at a cloud migration phase that favors recurring-revenue SaaS platforms with demonstrated FedRAMP or EU AI Act certification depth. Long-term viability centers on vendors bridging cyber-physical security skill fusion gaps through integrated OT-IT command layers. Watch hyperscale data center operator procurement standardization as the inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies multi-vendor access control and video estates through API orchestration layers. |
| Edge Computing Partnership | Redistributes AI inference toward camera endpoints to reduce bandwidth and latency. |
| Regulatory Certification Investment | Secures EU AI Act conformity assessments for biometric surveillance market entry. |
| Strategic Partnership | Aligns with Taiwan and South Korean foundries for specialized security silicon supply. |
| Geographic Expansion | Captures India smart city infrastructure with localized data residency compliance. |
Research Methodology
The analysis maps access control, video surveillance, intrusion detection, and security management platforms, each validated through CTOs at hyperscale data centers, IT procurement officers at K-12 districts, platform engineers at systems integrators, and channel partners distributing through locksmith and IT reseller networks. Primary interview findings triangulate against SEC 10-K filings from diversified industrial conglomerates, hyperscaler capex disclosures, EU AI Act implementation guidance, and NIST Cybersecurity Framework documentation. Bottom-up deployment sizing and top-down market aggregation cross-validate volume estimates.
Consistency checks against external benchmarks validate analytical framework outputs across the projection horizon. Segmentation dimensions include deployment mode, organization size, vertical application, integration complexity, and regional regulatory cluster. CAGRs derive from trend extrapolation calibrated to documented procurement cycles and technology substitution rates. Forecast inputs incorporate documented GPU and NPU supply constraints and EU AI Act enforcement timelines.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration momentum and stable cross-border data flow frameworks; material deviation in semiconductor supply or regulatory enforcement velocity would warrant model refresh. Recalibration cycles align with material shifts in AI Act implementation guidance and hyperscale data center construction pipelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Private Security Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Global Bot Security Market