
 Global Bot Security Market | 2026-2036
Global Bot Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bot Security Market Foresight
Buyer concentration among digital payment platforms and online marketplaces is expanding as fraud losses from credential stuffing and scalping bots mount. Cloudflare Inc. leverages its edge network density to deliver sub-millisecond bot detection at scale. Akamai Technologies anchors enterprise trust through deep integration with content delivery workflows. DataDome specializes in behavioral analytics that adapt to evolving attacker patterns without manual rule tuning.
Bot security encompasses technologies that distinguish automated malicious traffic from legitimate human users through behavioral biometrics, device telemetry, and request fingerprinting. Solutions analyze JavaScript execution environments, mouse kinematics, and TLS handshake characteristics to score risk in real time. Web Application Firewall and Behavioral Analytics segments command the deepest engineering investment as attackers shift from volumetric floods to low-and-slow credential abuse. Cloud-Based deployment dominates new procurement cycles while Hybrid architectures retain traction among regulated banks requiring data sovereignty controls.
FCC guidelines on robocall mitigation and the EU AI Act's risk classification for automated decision systems are reshaping compliance baselines for bot management vendors. HIPAA security rule extensions in US healthcare and Japan's METI cybersecurity framework for critical infrastructure further fragment certification requirements across jurisdictions. Stakeholders must evaluate whether their detection pipelines can satisfy divergent evidentiary standards for algorithmic transparency without degrading latency.

Market Dynamics
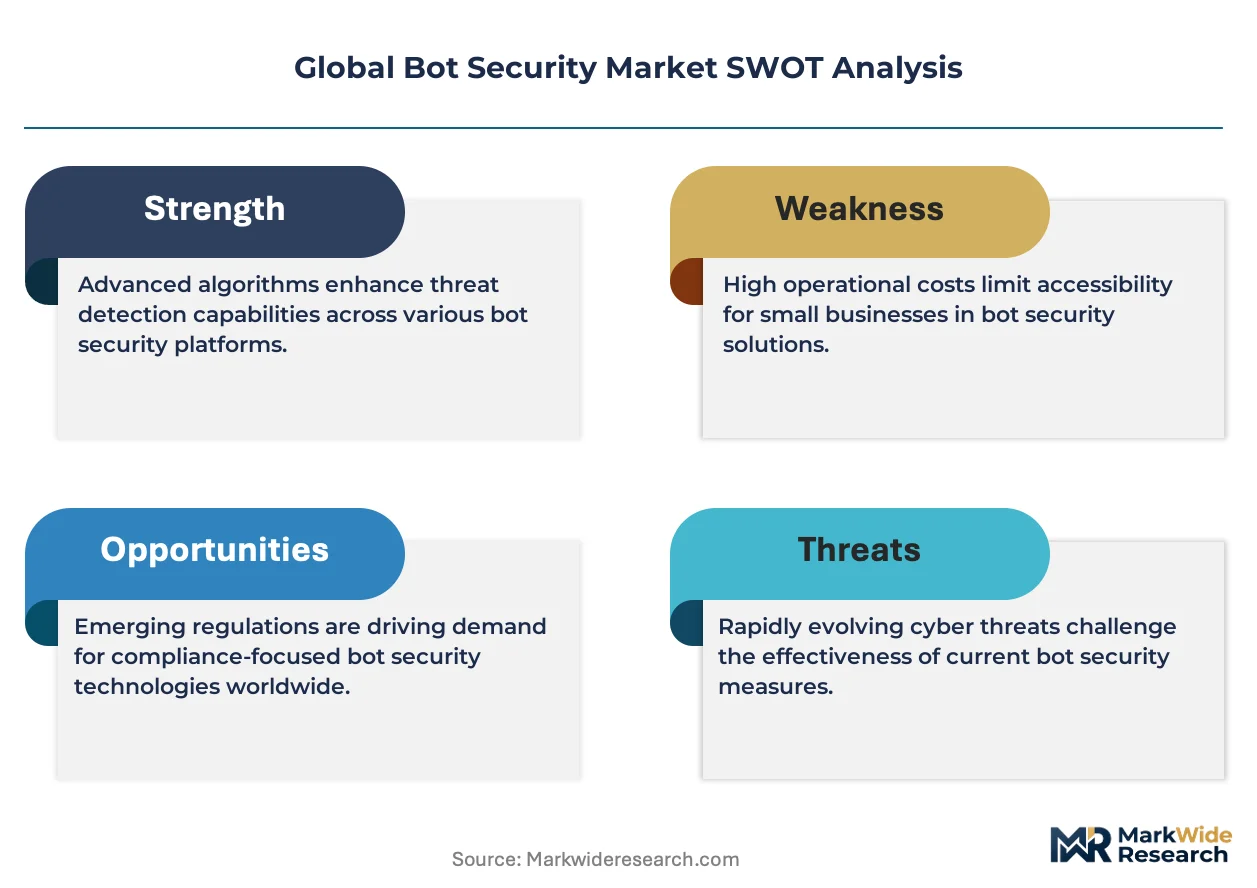
The EU AI Act's risk classification framework for automated decision systems is forcing bot management vendors to reengineer detection pipelines for algorithmic transparency without degrading sub-millisecond latency requirements.
Growth Catalysts
- Credential stuffing surge:Digital payment platforms and online marketplaces face mounting fraud losses from scalping bots, accelerating procurement of behavioral analytics solutions.
- GDPR compliance obligations:The EU's data protection regime mandates automated traffic transparency, expanding enterprise budgets for bot detection with audit-ready telemetry.
- Edge network density:Cloud infrastructure providers now embed bot detection directly into content delivery nodes, collapsing deployment friction for e-commerce platforms.
Market Restraints
- Data sovereignty requirements:Regulated banks in Germany and Japan demand hybrid architectures, fragmenting vendor R&D across jurisdiction-specific compliance stacks.
- TLS fingerprinting arms race:Attackers rotate client signatures faster than behavioral models retrain, compressing detection efficacy windows.
- Certificate fragmentation:Divergent HIPAA extensions, METI cybersecurity frameworks, and FCC robocall guidelines multiply certification costs for cross-border vendors.
Strategic Opportunities
- Healthcare automation:HIPAA-covered entities in the United States require bot protection for patient portals, an underpenetrated vertical with strict evidentiary standards.
- API security convergence:Behavioral biometrics merge with request fingerprinting to address machine-to-machine traffic, opening new product categories beyond web applications.
- Japan's critical infrastructure:METI's cybersecurity framework mandates protections for energy and logistics platforms, creating regulatory tailwinds for specialized vendors.
Industry Challenges
- Adversarial ML expertise scarcity:Vendors struggle to hire engineers capable of training models that resist evasion through prompt injection and environment spoofing.
- Legacy WAF integration:Enterprises demand seamless handoffs between rule-based firewalls and behavioral systems, requiring complex orchestration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bot Security Market |
| Market Size in 2026 | $745.8 Million |
| Market Size in 2035 | $3,159.62 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Web Application Firewall, CAPTCHA, Behavioral Analytics, Device Fingerprinting, Rate Limiting Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services Application Area: E-Commerce, Banking & Financial Services, Media & Entertainment, Government, Telecommunications End User Industry: Online Marketplaces, Digital Payment Platforms, Content Publishers, Public Sector Agencies |
| Companies Covered | Cequence, Imperva, Cloudflare Inc., PerimeterX Inc., Radware, Akamai Technologies, DataDome, Netacea, F5 Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bot Security Market Shifts & Advancements
Bot detection architectures are consolidating around edge-deployed inference engines that score risk using device telemetry rather than centralized analysis, compressing response latency while complicating data residency compliance.
Behavioral biometrics is consolidating disparate signals—mouse kinematics, JavaScript execution traces, and TLS handshake anomalies—into unified risk scores. E-commerce platforms adopt these fused models fastest, replacing siloed rule sets that required manual tuning. The technology is consolidating vendor competitive positions around data moats rather than algorithmic novelty.
The EU AI Act's high-risk system classification applies directly to bot management platforms making automated blocking decisions. Vendors must now maintain model cards documenting training data provenance and decision boundaries. German automotive marketplaces and French financial services firms lead compliance investments, pressuring laggards in the United States to adopt similar transparency standards preemptively.
Enterprise buyers now unbundle bot detection from broader web application firewall contracts, selecting specialized vendors for specific traffic types. Digital payment processors in Japan and healthcare portals in the United States drive this fragmentation, rejecting one-size-fits-all pricing. Procurement teams negotiate separate SLAs for credential stuffing versus content scraping use cases, forcing vendors to expose granular performance telemetry.
Global Bot Security Market Segmentation
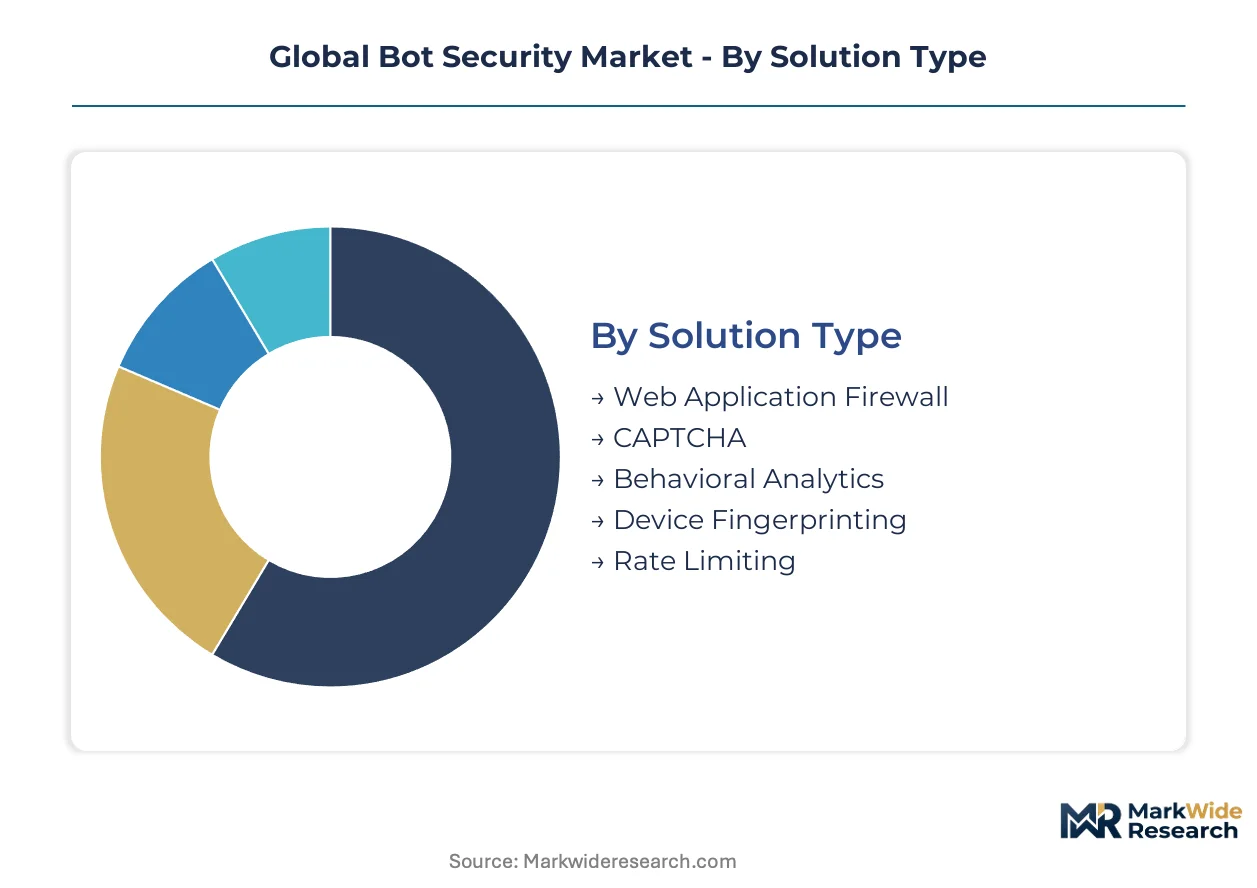
Bot security procurement patterns diverge sharply based on integration depth and traffic architecture. Buyers with legacy infrastructure prioritize embedded detection modules, while cloud-native platforms favor standalone behavioral stacks that deploy without code changes.
Solution Type:
Standalone solutions command premium pricing for rapid deployment, whereas embedded modules require deeper engineering integration but reduce latency.
- Web Application Firewall:Rule-based traffic filtering inspects HTTP requests against signature databases. German automotive marketplaces and French financial services firms deploy these at network edges to satisfy EU AI Act audit requirements for automated blocking decisions.
- Behavioral Analytics:Machine learning models score risk from mouse kinematics, JavaScript execution traces, and TLS handshake anomalies. Digital payment processors in Japan and healthcare portals in the United States drive fastest adoption as credential stuffing losses mount.
- CAPTCHA:Interactive challenge systems distinguish humans through visual or audio puzzles.
- Device Fingerprinting:Telemetry collection identifies returning devices via browser and hardware characteristics.
- Rate Limiting:Threshold-based request throttling prevents volumetric abuse.
Volume placements concentrate in Web Application Firewall; the faster expansion belongs to Behavioral Analytics.
Deployment Model:
Cost tiers separate enterprise buyers with compliance burdens from mid-market adopters prioritizing speed-to-value.
- Cloud-Based:Vendor-managed infrastructure delivers sub-millisecond detection without client-side hardware. E-commerce platforms across the United States and Germany dominate procurement, collapsing deployment friction through edge network integration.
- Hybrid:Split architectures process sensitive data on-premises while routing telemetry to cloud analytics engines. Regulated banks in Japan and Germany mandate these configurations to satisfy METI cybersecurity frameworks and data sovereignty requirements.
- On-Premises:Fully captive infrastructure meets strictest data residency obligations.
- Managed Services:Outsourced security operations centers monitor and respond to bot traffic.
Cloud-Based deployments capture the largest share; Hybrid architectures climb the fastest as jurisdictional fragmentation intensifies.
Application Area:
Customer maturity varies by vertical exposure to automated attack sophistication and regulatory scrutiny.
- E-Commerce:Scalping and inventory hoarding protection for product catalogs and checkout flows. United States and German retailers lead spending as bot-driven purchase automation erodes margin.
- Banking & Financial Services:Credential stuffing defense for authentication portals and transaction APIs. Japanese financial institutions accelerate procurement under METI critical infrastructure mandates.
- Media & Entertainment:Content scraping prevention and streaming access control.
- Government:Citizen service portal protection against automated abuse.
- Telecommunications:SMS pumping and robocall mitigation aligned with FCC guidelines.
E-Commerce holds the dominant placement volume; Banking & Financial Services gains share fastest as fraud losses compound.
End User Industry:
Supply concentration clusters around transaction-heavy platforms with highest automated attack surface.
- Digital Payment Platforms:Real-time transaction risk scoring prevents card testing and account takeover. United States processors face mounting fraud losses, expanding budgets for behavioral biometrics with audit-ready telemetry.
- Online Marketplaces:Seller verification and listing protection against automated fraud. German and Japanese platforms invest heavily to maintain trust metrics.
- Content Publishers:Ad fraud prevention and paywall bypass detection.
- Public Sector Agencies:Citizen-facing service protection with strict procurement oversight.
Online Marketplaces represent the largest volume segment; Digital Payment Platforms show the steepest expansion trajectory as real-time fraud losses accelerate.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital payment platforms and e-commerce marketplaces in the United States, Germany, and Japan concentrate procurement volume for bot security solutions. Regulatory fragmentation across jurisdictions accelerates hybrid deployment architectures as enterprises balance latency requirements against data sovereignty mandates.
United States
Credential stuffing attacks against financial services and healthcare portals drive enterprise spending. HIPAA security rule extensions mandate audit-ready telemetry for patient-facing systems. Silicon Valley technology clusters and New York financial services hubs anchor domestic demand for behavioral analytics with sub-millisecond detection.
Germany
Automotive marketplaces and industrial platforms require automated decision transparency under EU AI Act risk classifications. GDPR compliance obligations expand budgets for bot detection with algorithmic accountability. Munich and Frankfurt cybersecurity clusters concentrate vendor engineering resources for hybrid cloud deployments.
Japan
METI cybersecurity frameworks mandate protections for energy and logistics critical infrastructure. Financial institutions accelerate procurement to satisfy regulatory deadlines for automated traffic monitoring. Tokyo and Osaka technology corridors dominate domestic implementation of edge-integrated detection systems.
United Kingdom
Digital banking platforms and content publishers face escalating scraping and account takeover losses. Post-Brexit regulatory divergence complicates cross-border data flows for multinational enterprises. London fintech clusters drive demand for specialized behavioral biometrics with granular performance telemetry.
India
E-commerce expansion and digital payment proliferation expose platforms to inventory hoarding and card testing attacks. RBI cybersecurity guidelines for financial infrastructure tighten baseline protection requirements. Bangalore and Mumbai technology hubs concentrate domestic vendor development for cloud-native detection architectures.
Global Bot Security Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue behavioral specialization and edge-native architectures. The vendor base stratifies across three maturity levels: infrastructure-scale platforms with global edge networks, mid-tier specialists in vertical-specific detection, and venture-backed innovators in adversarial machine learning. Consolidation pressure intensifies as enterprise buyers unbundle bot detection from legacy web application firewall contracts. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and geographic expansion through localized compliance engineering.
Within the infrastructure-scale tier, Cloudflare Inc. and Akamai Technologies exemplify edge-network density as a competitive moat. DataDome occupies a specialist position concentrated in behavioral analytics without manual rule tuning. These three anchors represent divergent strategic bets: network-integrated latency optimization, enterprise workflow embedding, and adaptive model architectures respectively.
| Leading Market Players |
|---|
| Cequence |
| Imperva |
| Cloudflare Inc. |
| PerimeterX Inc. |
| Radware |
| Akamai Technologies |
| DataDome |
| Netacea |
| F5 Inc. |
| Others |
Supply & Pricing Matrix
Edge-network premium tiers and behavioral-analytics commodity tiers diverge sharply in both cost structures and supply chain footprints, with latency-optimized solutions commanding infrastructure-scale investments while rule-based alternatives source from distributed engineering pools across Eastern Europe and South Asia.
Pricing Analysis
Volume placements concentrate in subscription-based SaaS tiers with per-request metering, while margin capture sits with enterprise contracts bundling managed detection and response. Price differentiation hinges on sub-millisecond latency guarantees and EU AI Act compliance certification. Pricing pressure stems from open-source behavioral models commoditizing signature-based detection. Mid-market e-commerce platforms exhibit highest price sensitivity; regulated banks in Germany and Japan show lowest.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke delivery for edge-deployed inference engines. Core software development draws from engineering clusters in Israel, Singapore, and Poland. Supply chain risk centers on single-source dependency for specialized GPU hardware. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification erects a compliance moat that rewards vendors with pre-built algorithmic transparency documentation, locking out undercapitalized entrants unable to sustain audit-ready telemetry infrastructure.
For Market Incumbents: Deepen vertical integration into edge hardware partnerships to collapse latency below competitor reach. Consolidate position by acquiring adversarial ML specialists in Tel Aviv and Singapore before talent scarcity intensifies. Anchor enterprise retention through pre-certified compliance modules for HIPAA and METI frameworks.
For New Entrants and Emerging Players: Launch via API-first distribution targeting mid-market healthcare portals in the United States with modular behavioral biometrics. Penetrate the underdefended patient authentication segment where incumbent WAF bundles prove overbuilt. Lead with transparent model cards as a competitive differentiator against opaque legacy systems.
For Investors and Strategic Acquirers: Re-rating potential sits with behavioral-analytics specialists given EU AI Act compliance deadlines accelerating enterprise procurement. Long-term viability favors vendors with captive data moats from multi-vertical telemetry collection. Watch for inflection when Japanese financial institutions complete METI-mandated procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Network Partnership | Cloudflare and Akamai infrastructure integration collapses deployment friction for e-commerce platforms. |
| Adversarial ML Acquisition | Specialist talent pools in Israel and Singapore resist evasion through prompt injection attacks. |
| Compliance Certification Program | Pre-built EU AI Act model cards accelerate German automotive marketplace procurement cycles. |
| API-First Product Launch | Modular behavioral biometrics penetrate healthcare portals rejecting monolithic WAF bundles. |
| Healthcare Vertical Expansion | HIPAA-covered entities in the United States drive fastest growth in audit-ready telemetry demand. |
Research Methodology
Independent corroboration across CTO interviews, IT procurement officer surveys, and hyperscaler capex disclosures underwrites the qualitative findings. Primary fieldwork engaged platform engineers at digital payment processors, integration specialists at cloud infrastructure providers, and channel partners distributing behavioral analytics solutions. Secondary validation drew from SEC filings, EU regulatory impact assessments, and METI cybersecurity framework documentation. Bottom-up deployment counts triangulate against top-down vendor revenue estimates.
Rate-of-change decomposition separates baseline credential-stuffing frequency growth from regulatory acceleration effects across the analysis window. Segmentation dimensions include solution type, deployment model, application area, and jurisdiction-specific compliance burden. CAGRs derive from logistic adoption curves fitted to procurement pipeline data. Forecast inputs incorporate TLS fingerprinting arms-race dynamics and adversarial ML retraining cycle compression.
Regulatory enforcement delays, adversarial evasion breakthroughs, and hyperscaler pricing warfare are the dominant revision risks. Forecasts embed assumptions about EU AI Act implementation timelines and METI deadline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Threat Detection Systems Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Cargo and Vehicle Screening Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Seaport Security Management Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
North America People Screening Market